
 Capacitive Stylus Pen Market | 2026-2036
Capacitive Stylus Pen Market Size, Share, and Industry Trends Forecast 2026-2036
Capacitive Stylus Pen Market Insights
Active stylus bundling with premium tablets is decoupling from traditional standalone retail channels, forcing buyers to evaluate compatibility ecosystems rather than hardware specs alone. Apple leverages vertical integration across its iPad and Pencil lines to control the full user experience. Samsung anchors its S Pen ecosystem within Galaxy Note and Tab series devices, creating switching costs for enterprise buyers. Wacom specializes in pressure-sensitive technology for creative professionals, sustaining premium positioning against mass-market alternatives.
A capacitive stylus pen is an input device that conducts electrical charge from the human body to a touchscreen surface through a conductive tip, typically employing copper mesh, conductive foam, or active electronic components to register precise contact coordinates. Its primary commercial purpose is to enable handwriting, drawing, and gesture navigation on capacitive touchscreens with greater accuracy than a fingertip. The active stylus segment leads in revenue contribution due to embedded Bluetooth and pressure-sensitivity features that command premium pricing. Passive stylus demand concentrates in education budgets where low-cost plastic and rubber variants serve K-12 deployment at scale. Metal-bodied styluses occupy a narrowing mid-tier as material differentiation weakens against performance-based segmentation.
The EU F-Gas Regulation and REACH compliance frameworks govern chemical substances in electronic accessories sold across Europe, compelling manufacturers to reformulate rubber and silicone compounds. The US FCC certifies active styluses emitting Bluetooth signals for electromagnetic compatibility. China's MIIT enforces GB standards on wireless transmission modules integrated into smart stylus designs. Stakeholders must monitor evolving interoperability protocols as operating system vendors tighten certification requirements for third-party accessory ecosystems.
Market Dynamics
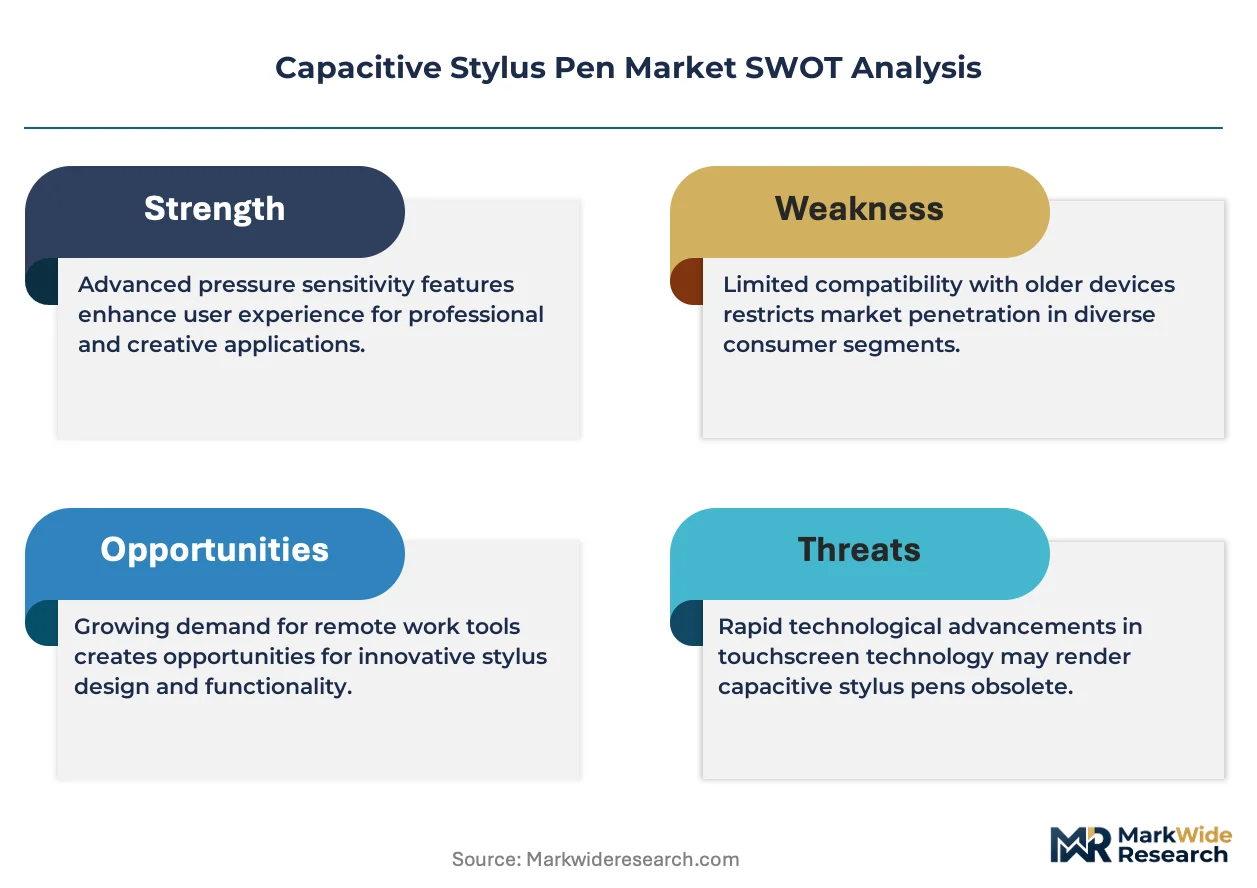
The capacitive stylus pen market is fragmenting around ecosystem lock-in rather than hardware performance, with operating system vendors tightening certification protocols that marginalize unlicensed third-party accessories and compress margins for standalone manufacturers.
Growth Catalysts
- REACH chemical compliance:European ECHA enforcement on rubber and silicone compounds is accelerating reformulation investments among compliant suppliers, filtering out low-grade competitors.
- Digital note-taking in professional services:Legal, medical, and financial services verticals are standardizing stylus-based documentation workflows to meet audit and privacy requirements.
- Conductive foam tip innovation:Advances in copper-polymer hybrid materials are extending passive stylus durability while maintaining sub-dollar manufacturing economics for education procurement.
Market Restraints
- Bluetooth module cost volatility:Active stylus BOM exposure to semiconductor foundry capacity constraints in Taiwan and South Korea is compressing gross margins for mid-tier producers.
- Substitution by fingertip UX improvements:Capacitive touchscreen palm-rejection algorithms and haptic feedback are reducing precision advantages that previously justified stylus purchase.
- Ecosystem certification friction:Apple's MFi and Google's Works With Android programs impose royalty burdens and technical barriers that exclude smaller accessory vendors.
Strategic Opportunities
- India education digitization:The country's PM SHRI Schools scheme and state-level tablet distribution programs create bulk procurement channels for K-12 passive stylus deployment.
- Healthcare sterile workflow integration:Antimicrobial-coated stylus designs are penetrating hospital EMR systems where infection control protocols restrict shared device contact.
- EU F-Gas Regulation phase-down:Refrigerant gas restrictions are indirectly pressuring electronics manufacturers to eliminate fluorinated compounds in all accessory lines, favoring reformulation-ready suppliers.
Industry Challenges
- Pressure sensor calibration expertise:The scarcity of firmware engineers capable of integrating force-sensitive resistor arrays with Bluetooth latency requirements is throttling active stylus development pipelines.
- Interoperability testing backlog:FCC Part 15 certification queues for 2.4 GHz emitters are extending time-to-market for new active stylus launches by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Capacitive Stylus Pen Market |
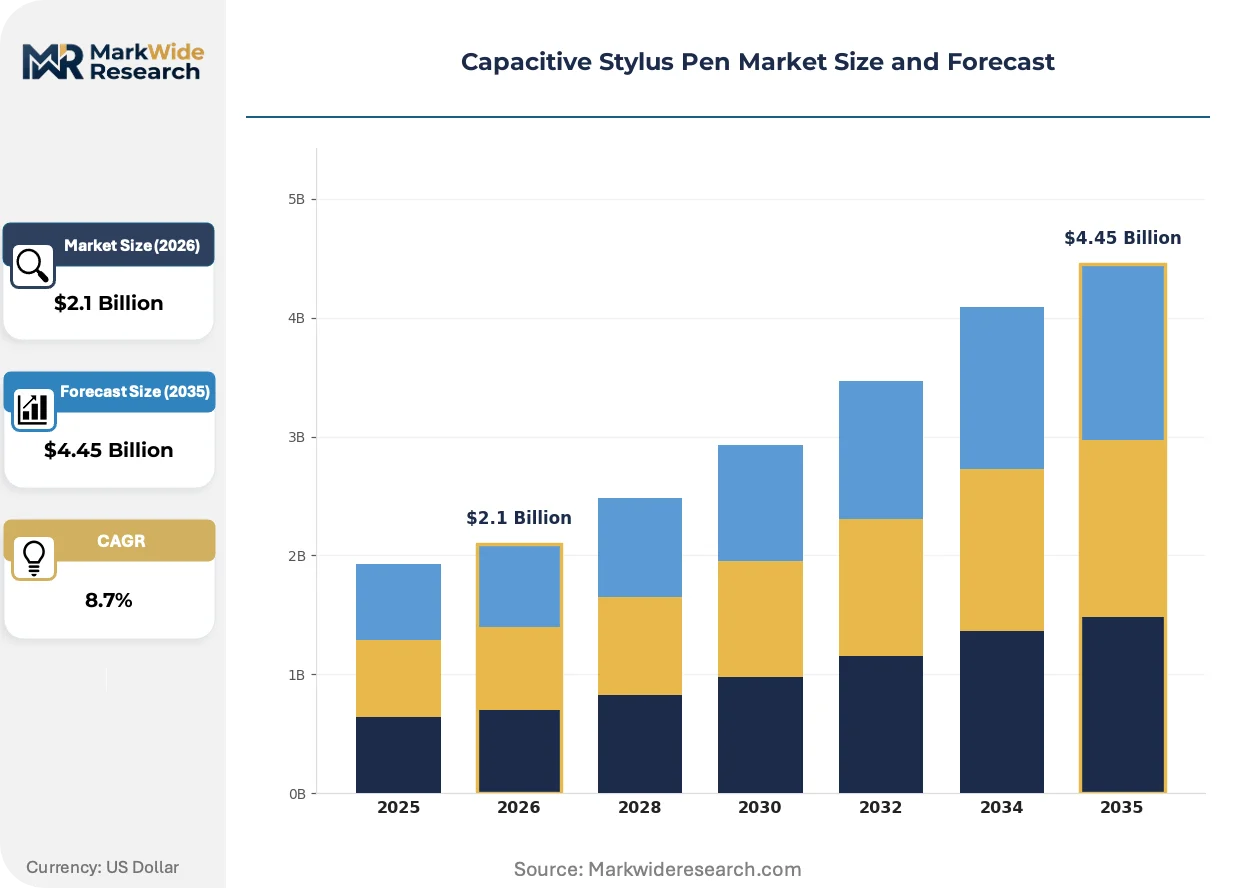
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Stylus, Passive Stylus, Digital Pen, Multi-Touch Stylus Use Case: Graphic Design, Note Taking, Education, Gaming End User: Students, Professionals, Artists, Gamers Material: Plastic, Metal, Rubber, Silicone |
| Companies Covered | Apple Inc., Samsung Electronics, Wacom Co., Ltd, Microsoft Corp., Adonit, Logitech, Hunt Wave Industry, Huion Technology Corporation, XP-Pen Technology Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Capacitive Stylus Pen Market Trends and Innovations
Stylus hardware architecture is decomposing into interchangeable subsystems, enabling vendors to swap tip assemblies, battery modules, and wireless chipsets without full product redesign cycles. This modularity is compressing development timelines and fragmenting supplier tiers.
Active stylus tip assemblies incorporating force-sensitive resistor arrays and interchangeable conductive polymers are modularizing across price tiers. Education procurement officers now specify field-replaceable tip cartridges to extend device lifecycles. This standardization is modularizing the aftermarket supply chain and displacing integrated-tip designs in institutional contracts.
China's MIIT GB standards for wireless transmission modules are tightening electromagnetic compatibility thresholds for Bluetooth-enabled accessories. Manufacturers must redesign RF shielding and antenna configurations to maintain market access. Active stylus producers targeting Chinese tablet OEMs are absorbing additional testing cycles and component costs.
Enterprise buyers are consolidating stylus procurement under device-as-a-service contracts that bundle hardware, software licensing, and support into per-seat subscriptions. This displaces standalone retail purchases and concentrates volume with vendors capable of multi-year service agreements. Financial services and healthcare verticals in North America and Western Europe are driving this contract structure adoption.
Capacitive Stylus Pen Market Segmentation
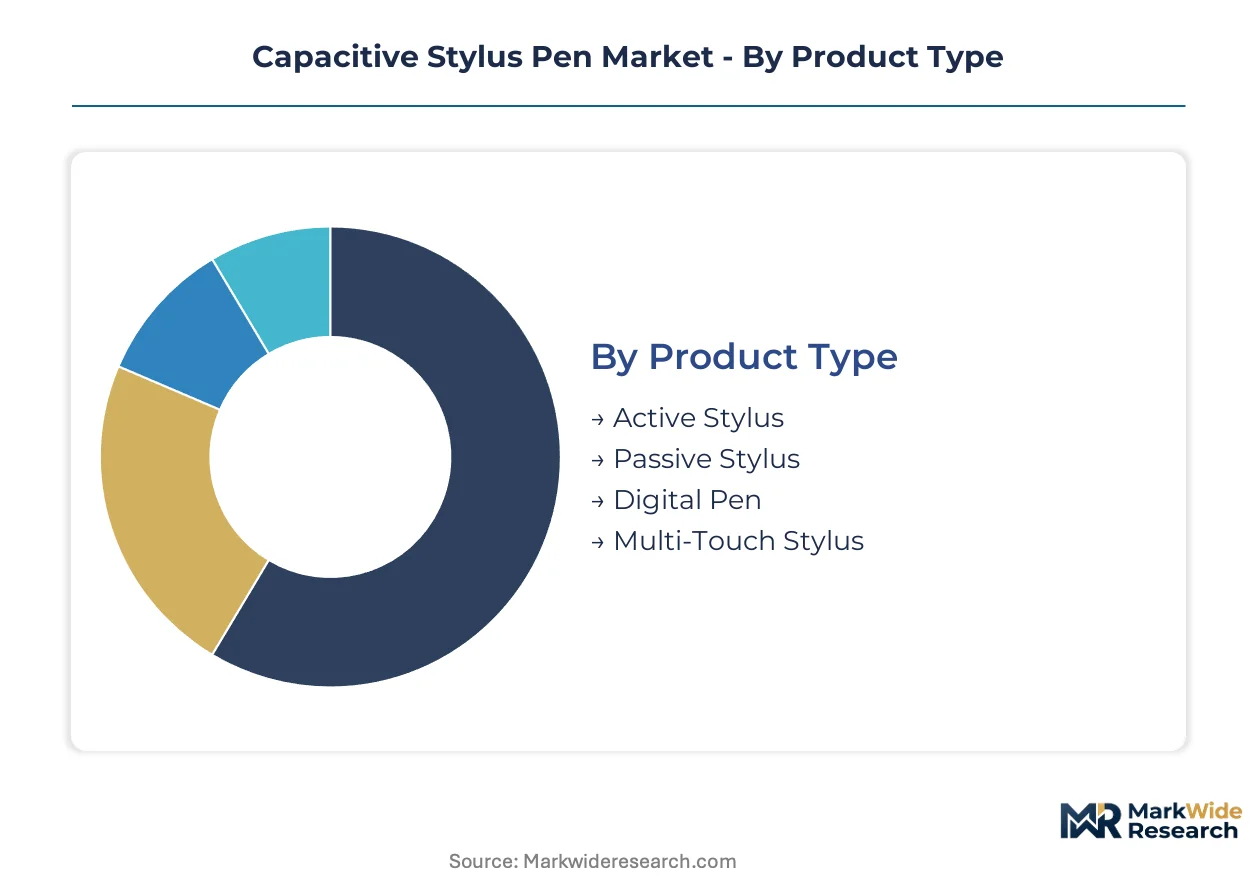
Product architecture and material composition dictate upgrade cycles across the capacitive stylus pen market, with active stylus refresh rates tied to tablet replacement schedules while passive variants follow K-12 device procurement calendars. Understanding segment boundaries reveals where ecosystem lock-in versus price sensitivity governs purchasing decisions.
Product Type:
Upgrade cadence varies sharply across product categories, with embedded electronics shortening replacement cycles for active variants while passive designs persist through multiple device generations.
- Active Stylus:Bluetooth-enabled pressure-sensitive input devices integrate force-sensitive resistor arrays and proprietary wireless chipsets. Demand concentrates among creative professionals in the United States and Germany where Adobe Creative Cloud and Autodesk workflows mandate precision input; ecosystem certification requirements from Apple and Google constrain third-party compatibility and sustain premium positioning.
- Passive Stylus:Conductive foam or mesh-tipped implements transmit body capacitance without electronic components. Procurement in China's Jiangsu and Guangdong provinces dominates volume as domestic tablet OEMs bundle low-cost variants with education sector orders; copper-polymer hybrid tip innovations extend field durability against budget constraints.
- Digital Pen:Optical tracking variants with dedicated writing surfaces serve enterprise documentation workflows.
- Multi-Touch Stylus:Multi-point capacitive designs enable gesture expansion for presentation and navigation applications.
Volume placements concentrate in Passive Stylus; the faster expansion belongs to Active Stylus.
Use Case:
Application-specific requirements reshape cost tolerance thresholds, with compliance-driven verticals accepting premium pricing while entertainment-oriented segments resist hardware expenditure.
- Graphic Design:Pressure-sensitive workflows demand sub-10ms latency and tilt recognition for brush emulation. Creative studios in California and Tokyo absorb premium hardware costs where Wacom and Apple ecosystem integration accelerates production throughput; cloud-based asset libraries synchronize stroke data across devices.
- Note Taking:Handwriting recognition and OCR integration dominate professional services procurement. Legal and medical practices in New York and London standardize stylus-based documentation to satisfy HIPAA and GDPR audit trails; searchable ink archives displace paper filing systems.
- Education:K-12 deployment scales prioritize field-replaceable tips and antimicrobial coatings.
- Gaming:Touchscreen precision for mobile esports drives low-latency peripheral demand.
Education captures the highest unit placements; Note Taking is climbing the fastest as compliance requirements tighten.
End User:
User sophistication and purchasing authority fragment procurement channels, with institutional buyers negotiating enterprise contracts while individual consumers respond to retail bundling incentives.
- Students:K-12 and higher education procurement operates through district-level and university IT departments. India's PM SHRI Schools scheme and state tablet distribution programs in Maharashtra and Karnataka generate bulk orders for passive stylus variants; antimicrobial specifications are penetrating hospital-affiliated medical school contracts.
- Professionals:Enterprise device-as-a-service contracts consolidate hardware, software licensing, and support into per-seat subscriptions. Financial services firms in Singapore and healthcare systems in Switzerland specify multi-year service agreements that displace standalone retail purchases.
- Artists:Freelance and studio-based creative professionals drive pressure-sensitive feature adoption.
- Gamers:Mobile esports participants prioritize latency reduction over pressure sensitivity.
Students account for the largest volume base; Professionals are expanding most quickly through subscription contract adoption.
Material:
Material selection governs regulatory compliance exposure and manufacturing economics, with REACH and RoHS frameworks filtering supplier bases across European markets.
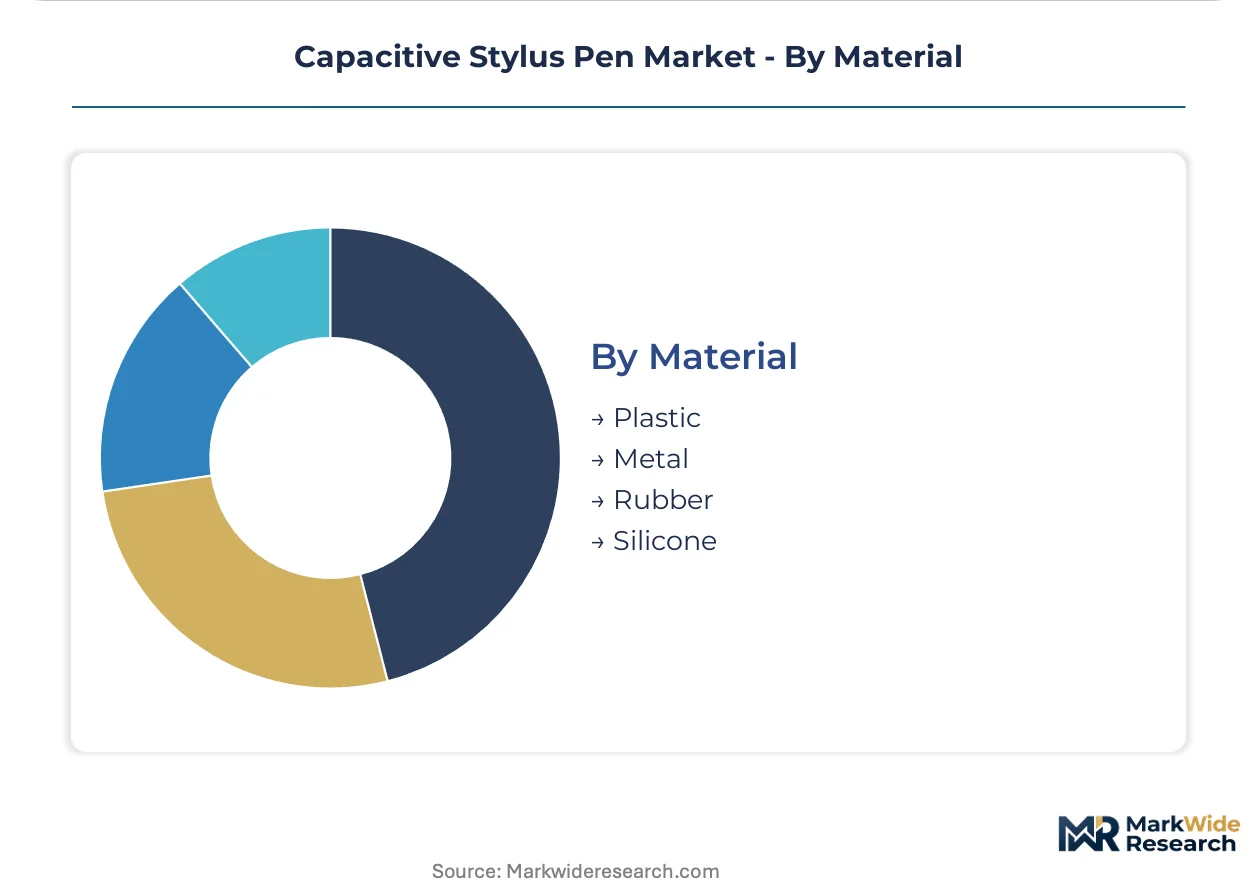
- Plastic:ABS and polycarbonate housings dominate education sector cost targets. Injection molding clusters in Shenzhen and Dongguan supply K-12 procurement globally; ECHA enforcement on phthalate content is accelerating reformulation investments among compliant suppliers.
- Metal:Aluminum and stainless steel bodies occupy narrowing mid-tier positioning as performance-based segmentation weakens material differentiation. Premium tablet bundling in South Korea and Japan favors machined unibody designs; anodizing processes must satisfy MIIT GB standards for electromagnetic compatibility in wireless-enabled variants.
- Rubber:Grip compounds face F-Gas Regulation pressure on fluorinated processing aids.
- Silicone:Medical-grade variants penetrate healthcare sterile workflow applications.
Plastic dominates absolute unit shipments; Metal retains the steepest expansion trajectory in premium bundled configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate capacitive stylus manufacturing through Shenzhen and Dongguan clusters, where bonded warehousing and export tax rebates accelerate component assembly for global tablet OEMs.
China
Domestic tablet manufacturing in Jiangsu and Guangdong provinces drives bulk procurement of passive stylus components. MIIT enforces GB standards on wireless transmission modules integrated into smart stylus designs. Shenzhen's electronics assembly corridors supply copper-polymer hybrid tip innovations to education sector distributors.
United States
Creative professionals in California and New York absorb premium active stylus hardware where Adobe Creative Cloud workflows mandate precision input. FCC Part 15 certifies Bluetooth-enabled accessories for electromagnetic compatibility. Austin's semiconductor design hubs develop force-sensitive resistor firmware for pressure-sensitive applications.
Germany
Industrial designers in Bavaria and Baden-Württemberg standardize stylus-based documentation for CAD workflows. ECHA REACH compliance frameworks govern chemical substances in rubber and silicone grip compounds. Stuttgart's precision engineering clusters prototype modular tip assemblies for field-replaceable configurations.
India
Maharashtra and Karnataka state tablet distribution programs generate bulk orders for K-12 passive stylus deployment. The PM SHRI Schools scheme channels procurement through district-level IT departments. Bengaluru's electronics manufacturing corridors assemble antimicrobial-coated variants for hospital-affiliated medical school contracts.
South Korea
Premium tablet bundling in Seoul Capital Area favors machined unibody metal designs with embedded S Pen ecosystems. The national radio research agency certifies 2.4 GHz emitters for electromagnetic compatibility. Busan-Ulsan industrial zones supply anodized aluminum housings to domestic OEMs.
Capacitive Stylus Pen Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across a tiered structure where ecosystem certification barriers marginalize unlicensed third-party accessories. Apple and Samsung leverage captive tablet installed bases to bundle proprietary stylus hardware, compressing standalone retail channels. Three archetypes dominate: vertically integrated platform vendors, pressure-sensitivity specialists serving creative verticals, and contract manufacturers supplying education procurement. Competitive moves concentrate on M&A for Bluetooth chipset capabilities and strategic partnerships with tablet OEMs for bundling rights.
Within the platform-vendor archetype, Apple Inc. and Samsung Electronics exemplify ecosystem lock-in through hardware-software integration. Wacom Co., Ltd occupies the specialist tier representing pressure-sensitive technology positioning against mass-market alternatives. Microsoft Corp. anchors the enterprise productivity vector where device-as-a-service contracts consolidate hardware and software licensing.
| Leading Market Players |
|---|
| Apple Inc. |
| Samsung Electronics |
| Wacom Co., Ltd |
| Microsoft Corp. |
| Adonit |
| Logitech |
| Hunt Wave Industry |
| Huion Technology Corporation |
| XP-Pen Technology Co. Ltd. |
| Others |
Pricing and Supply Chain Analysis
Captive integration of Bluetooth chipset design and force-sensitive resistor calibration anchors supply positioning for active stylus producers while insulating premium tiers from commodity pricing pressure. Apple's in-house Pencil ecosystem and Samsung's captive S Pen manufacturing demonstrate how upstream control over wireless module firmware and pressure sensor arrays translates into pricing power that passive stylus vendors cannot replicate.
Pricing Analysis
Short lead-time premiums dominate contract negotiations for enterprise device-as-a-service bundles, while spot inventory of education-grade passive styluses trades at volume discounts. Three-tier pricing structure across premium, standard, and economy levels separates Apple Pencil and Wacom Pro tiers from mid-tier metal-bodied alternatives and K-12 plastic variants. Cost compression in the passive segment intensifies because copper-polymer hybrid tip innovations extend product lifecycles and reduce replacement frequency. Education procurement officers exhibit highest price sensitivity, while financial services and healthcare verticals absorb premium hardware costs for compliance-ready active stylus configurations.
Supply Chain Analysis
Freight cost volatility from Shenzhen and Dongguan assembly clusters to North American and European distribution hubs is reshaping inventory positioning strategies for tablet OEM bundling programs. Component sourcing draws from Taiwan and South Korea for Bluetooth chipsets, China's Jiangsu province for copper-polymer hybrid tips, and Guangdong for injection-molded plastic housings. Single-source vulnerability concentrates in semiconductor foundry capacity for wireless transmission modules. Distribution runs through bonded warehousing in Yangtze River Delta special economic zones before OEM bundling or retail channel allocation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The capacitive stylus pen market sits in a technology-transition phase where fingertip UX improvements with palm-rejection algorithms and haptic feedback are displacing precision advantages that previously justified standalone stylus purchases.
For Market Incumbents: Cement ecosystem lock-in by deepening backward integration into pressure sensor firmware and Bluetooth latency optimization. Invest in MIIT GB standard pre-certification for Chinese tablet OEM bundling rights. Defend against substitution threat from touchscreen algorithm improvements by embedding stroke data synchronization with cloud-based asset libraries.
For New Entrants and Emerging Players: Capture white-space in India's PM SHRI Schools scheme and state-level tablet distribution programs where antimicrobial-coated passive stylus specifications are penetrating hospital-affiliated medical school contracts. Target enterprise device-as-a-service contract structures in North American financial services where multi-year service agreements displace standalone retail. Pursue field-replaceable tip cartridge standardization as the go-to-market angle for institutional procurement.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by platform vendors seeking Bluetooth chipset capabilities and pressure sensor calibration expertise. Long-term viability favors vendors with captive certification under Apple's MFi and Google's Works With Android programs. Watch FCC Part 15 certification queue lengths as inflection indicator for active stylus launch velocity and time-to-market compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Bluetooth Chipset Acquisition | Captive wireless module design secures MFi certification and compresses BOM exposure. |
| Pressure Sensor Firmware Development | Force-sensitive resistor calibration expertise throttles competitor development pipelines. |
| Antimicrobial Coating Certification | Hospital EMR system penetration satisfies infection control protocols in healthcare verticals. |
| Field-Replaceable Tip Standardization | Education procurement specifications extend device lifecycles and displace integrated designs. |
| Enterprise Device-as-a-Service Partnership | Per-seat subscription bundling consolidates volume with multi-year service agreement capability. |
Research Methodology
Independent corroboration across tablet OEM procurement directors, education sector IT administrators, and semiconductor component suppliers underwrites the qualitative findings in this study. Primary interviews with stylus hardware engineers, FCC certification consultants, and hospital biomedical equipment managers combined with secondary validation from MIIT GB standard filings, ECHA REACH substance databases, and FCC Part 15 equipment authorization records. Bottom-up assembly cost modeling and top-down tablet bundling contract analysis triangulate volume estimates.
Comparable-period anchoring to historical tablet replacement cycles and K-12 device procurement calendars structured the forecast window across the projection horizon. Segmentation dimensions modeled include product architecture, use case application, end user sophistication, and material composition, with ecosystem certification tier as an industry-specific dimension. CAGRs derived from unit shipment trajectories weighted by average selling price evolution, incorporating Bluetooth module cost volatility and copper-polymer hybrid tip adoption curves as forecast inputs.
The model holds under stable tablet OEM bundling relationships and consistent regulatory enforcement intensity; deviation in semiconductor foundry capacity allocation or REACH chemical substance restrictions would shift trajectory assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Digital Isolator Market
Electronic Components
Intel Motherboards Market
Electronic Components
Efuse Market
Electronic Components
Global Circuit Protection Market
Electronic Components
Silicon Capacitors Market
Electronic Components
Low-Dropout (LDO) Regulator Market
Electronic Components
Data Acquisition Card Market
Electronic Components
Electric Fuse Market
Electronic Components
Display Port Adapters Market
Electronic Components
Coin Battery Holder Market
Electronic Components
Safety Relay Market
Electronic Components
Flex-Rigid PCB Market
Electronic Components
Circuit Protection Kits Market
Electronic Components
Global Waveguide Components and Assemblies Market
Electronic Components
United States Radiation-Hardened Electronics Market
Electronic Components
Industrial Relays Market