
 Coated Paper Packaging Box Market | 2026-2036
Coated Paper Packaging Box Market Size, Share, and Industry Trends Forecast 2026-2036
Coated Paper Packaging Box Market Outlook
Buyer concentration in European cosmetics is decoupling from traditional mass-market retail toward direct-to-consumer and specialty boutique channels. International Paper Company leverages its North American containerboard network to serve fragmented e-commerce beauty startups. WestRock Company sustains margin through coated kraft specialization for pharmaceutical blister packs. Mondi Group anchors Central European supply with integrated virgin fiber mills serving serialized drug packaging.
A coated paper packaging box consists of paperboard substrate laminated with clay, polymer, or wax-based surface treatments to achieve specific gloss, barrier, or print-receptivity properties, typically manufactured through calendering or extrusion coating followed by die-cutting and folding. Its primary commercial purpose is to protect goods during distribution while enabling high-fidelity brand communication at retail point-of-sale. Folding box formats dominate pharmaceutical and food applications where automated cartoning lines require consistent crease recovery and dimensional stability. Rigid box segments command premium positioning in cosmetics gift packaging, where structural integrity and tactile surface quality justify material overruns. Recycled paper substrates face technical ceilings in moisture-sensitive electronics applications, pushing specialty paper grades toward Asia-Pacific electronics clusters.
FDA enforces strict contact-substance migration limits for food-grade coated packaging under 21 CFR 176.170, while EMA's EU Good Distribution Practice mandates serialization-ready carton substrates for pharmaceutical track-and-trace compliance. REACH restrictions on perfluorinated compounds and California's Safer Consumer Products regulations are forcing coating chemistry reformulation across multinational supply chains. Stakeholders must monitor evolving state-level extended producer responsibility laws and biopolymer coating certification schemes to preempt compliance-driven sourcing disruptions.
Market Dynamics
EU Green Deal packaging waste targets are forcing rapid substrate substitution across European cosmetics and pharmaceutical supply chains, compressing lead times for aqueous coating qualification while serialized track-and-trace mandates expand substrate performance requirements beyond conventional specifications.
Growth Catalysts
- EMA serialization mandates:Pharmaceutical distributors in Germany and France now require carton substrates with embedded authentication features, expanding demand for coated folding boxes with tamper-evident closures and traceability-ready surfaces.
- Aqueous coating chemistry:Water-based barrier treatments are displacing solvent-based alternatives in premium cosmetics packaging as brands race to meet EU perfluorinated compound restrictions ahead of enforcement deadlines.
- E-commerce beauty startups:Direct-to-consumer channels in North America are driving small-batch rigid box orders with short-run digital print compatibility, reshaping converter capacity allocation toward quick-turn production.
Market Restraints
- Pulp fiber cost volatility:Integrated virgin fiber mills in Scandinavia and North America face input cost pressure from energy-intensive bleaching processes, squeezing margin on specialty coated grades.
- Technical ceiling on recycled content:Post-consumer fiber substrates fail moisture-vapor transmission requirements for temperature-sensitive biologics, forcing pharmaceutical buyers toward higher-cost virgin alternatives.
- REACH chemical restrictions:ECHA's evolving substance restrictions on fluorinated coatings create formulation uncertainty, extending R&D cycles and delaying new product commercialization.
Strategic Opportunities
- Biopolymer coating certification:ASTM D6400 and EN 13432 compostable certification schemes are opening premium positioning for brands targeting zero-waste retail commitments in French and German luxury markets.
- Serialized cold-chain cartons:Temperature-indicating coatings combined with 2D barcode substrates address emerging EMA GDP requirements for biologic drug distribution across Central European logistics corridors.
- Digital print convergence:Inkjet-compatible coated boards are enabling mass customization for beauty subscription boxes, collapsing minimum order quantities and unlocking micro-segment targeting.
Industry Challenges
- Coating chemist talent scarcity:Formulation expertise in barrier polymer science commands premium compensation, constraining mid-tier converters from developing proprietary aqueous treatments in-house.
- Qualification timeline compression:Pharmaceutical buyers now demand 12-week substrate validation cycles versus historical 26-week windows, straining quality systems and regulatory documentation capacity.
- Legacy cartoning line incompatibility:New high-gloss coated stocks generate static and crease-recovery failures on aging European packaging equipment, requiring capital-intensive line retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coated Paper Packaging Box Market |
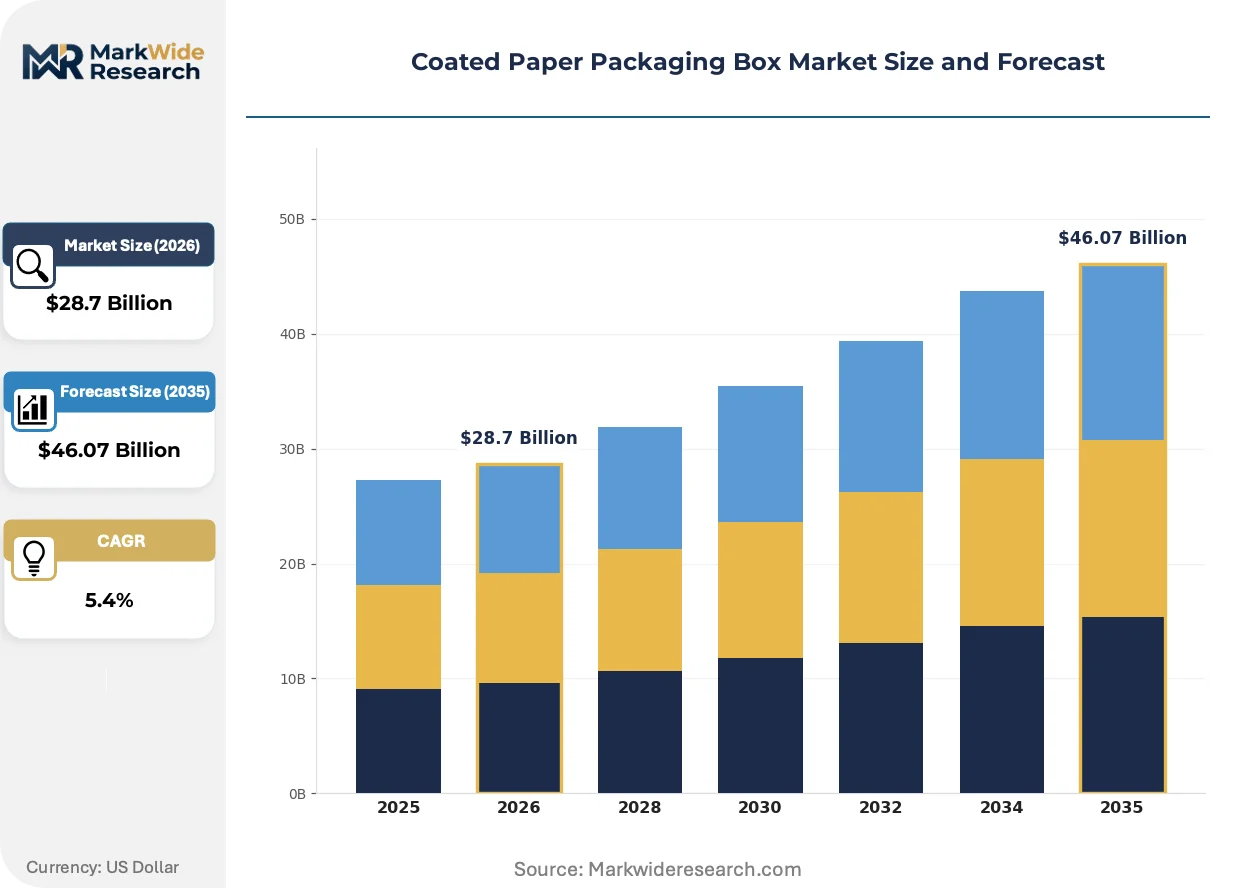
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $46.07 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Folding Box, Rigid Box, Tubes, Blister Packs End User: Food & Beverage, Cosmetics, Electronics, Pharmaceuticals Material: Recycled Paper, Virgin Fiber, Coated Kraft, Specialty Paper Application: Retail Packaging, Shipping Packaging, Gift Packaging, Display Packaging |
| Companies Covered | International Paper Company, WestRock Company, Mondi Group, Smurfit Kappa Group, Stora Enso Oyj, DS Smith plc, Huhtamaki Oyj, Mayr-Melnhof Karton AG, Shenzhen Pack Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coated Paper Packaging Box Market Strategic Shifts
Surface treatment chemistry and digital production workflows are converging to collapse traditional trade-offs between barrier performance, print fidelity, and end-of-life recoverability across pharmaceutical and prestige cosmetics applications.
Water-based aqueous coatings with oxygen and moisture barrier properties are consolidating technical validation efforts among European pharmaceutical contract manufacturers. German and French serialization-ready carton suppliers have accelerated qualification timelines as EMA track-and-trace deadlines compress procurement cycles. The technology is consolidating substrate specification standards around clay-polymer hybrid formulations that satisfy both barrier migration limits and high-speed inkjet print receptivity.
REACH restrictions on perfluorinated alkyl substances are forcing coating chemistry reformulation across multinational paperboard supply chains. ECHA's 2023 restriction proposal eliminates long-chain fluorinated treatments for food-contact applications, compelling converters to qualify silicone and bio-wax alternatives. Pharmaceutical packaging buyers in Germany's Rhine-Main corridor face extended validation periods as they assess substitute barrier performance against EMA migration limits.
Beauty brand procurement teams are consolidating supplier relationships around converters with integrated digital print and coating capabilities. North American direct-to-consumer cosmetics startups now specify 500-unit minimum runs with variable data printing, displacing traditional offset-plus-foil workflows. This pattern concentrates order placement with mid-cap converters in New Jersey and Ontario that have invested in single-pass inkjet and inline aqueous coating systems.
Coated Paper Packaging Box Market Segmentation
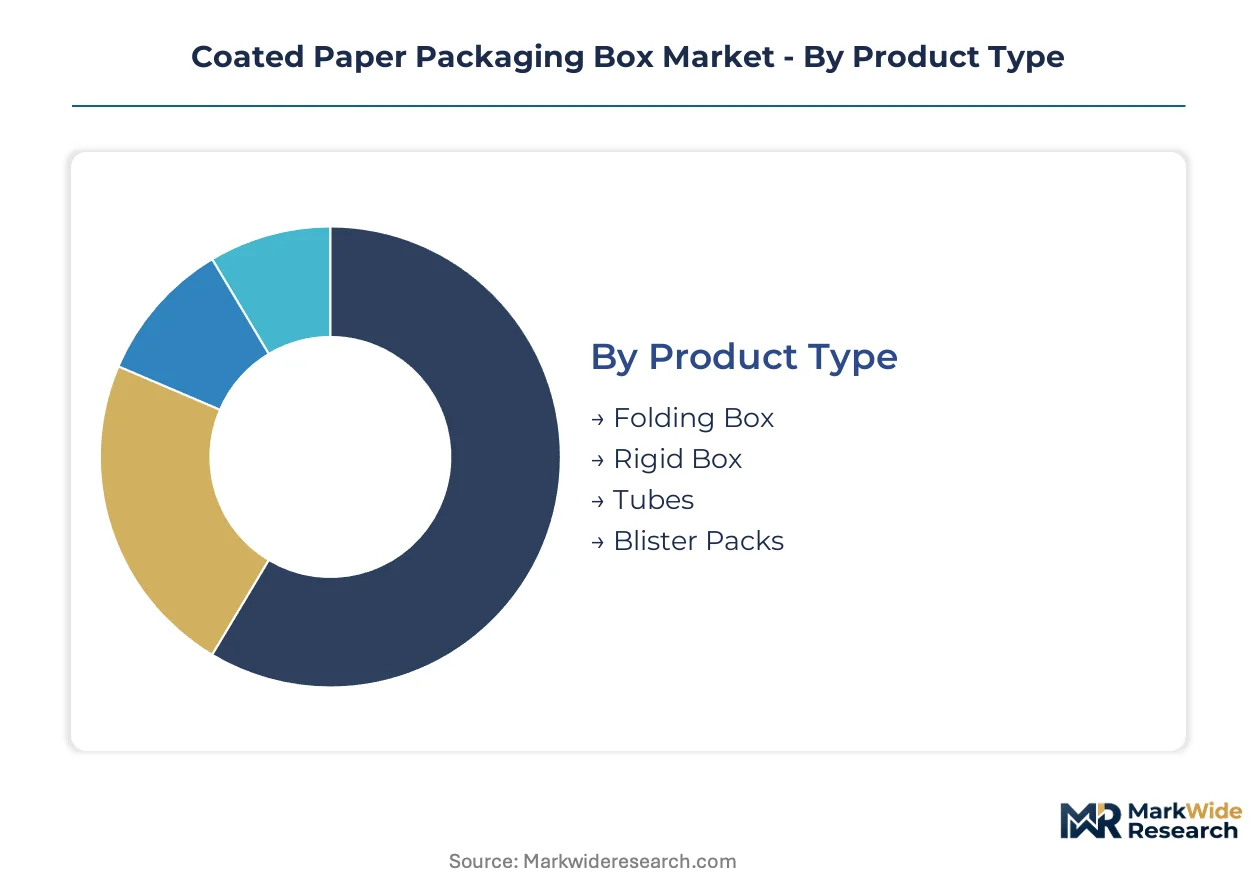
Segmentation in coated paper packaging reflects divergent capital requirements across converter equipment, coating chemistry R&D, and substrate qualification protocols. Pharmaceutical and cosmetics end-uses impose distinct technical specifications that reshape profitability profiles within each product category.
Product Type:
Capital intensity peaks with rigid box manufacturing, where automated casing-in lines and board laminating equipment demand seven-figure upfront investment versus folding carton rotary die-cutters.
- Folding Box:Multi-point glued cartons built from clay-coated recycled or virgin fiberboard, engineered for high-speed pharmaceutical cartoning lines. Demand concentrates in Germany's Rhine-Main pharmaceutical corridor, where EMA serialization mandates require tamper-evident crease recovery and dimensional stability under automated handling.
- Rigid Box:Wrapped chipboard or greyboard structures with separate base and lid components, surfaced with aqueous or UV coatings for tactile premium presentation. French and German cosmetics brands drive specification toward aqueous-coated gift formats as EU Green Deal targets eliminate solvent-based alternatives.
- Tubes:Spiral-wound or convolute paper cylinders with metal or plastic closures, serving cosmetics and specialty food applications.
- Blister Packs:Heat-sealed foil-paperboard laminations for unit-dose pharmaceuticals, requiring barrier-coated lidding substrates.
Most installed capacity flows through Folding Box segments serving high-volume pharmaceutical and food automation. Expansion is steepest in Rigid Box formats as direct-to-consumer beauty channels collapse minimum order quantities.
End User:
Margin structure varies sharply across end-use segments, with pharmaceutical buyers absorbing premium pricing for serialized, barrier-qualified substrates versus commoditized food-grade folding cartons.
- Food & Beverage:Barrier-coated folding cartons for frozen, dry, and liquid food products. FDA 21 CFR 176.170 migration limits and EU Green Deal packaging waste targets are forcing aqueous coating substitution across North American and European converter supply chains.
- Cosmetics:Rigid and folding boxes with high-gloss or soft-touch surface treatments for prestige and mass-market beauty products. Direct-to-consumer subscription channels in the United States and Canada are reshaping procurement toward 500-unit digital print runs with variable data capability.
- Electronics:Anti-static coated boxes for consumer devices and components, where moisture-vapor transmission rates determine substrate selection.
- Pharmaceuticals:Serialized folding cartons with embedded authentication features and temperature-indicating coatings for biologics distribution. EMA EU GDP compliance and track-and-trace mandates in Germany and France have compressed substrate validation timelines from 26 weeks to 12 weeks.
Pharmaceutical and Cosmetics segments command pricing premiums for barrier and authentication functionality. Food & Beverage volume dominates tonnage but faces margin compression from recycled fiber cost volatility.
Material:
Raw material sourcing strategy separates integrated virgin fiber producers from converters dependent on merchant market pulp, with energy-intensive bleaching processes concentrated in Scandinavian and North American mill networks.
- Recycled Paper:Post-consumer fiber substrates with technical ceilings in moisture-sensitive applications. Pharmaceutical buyers reject recycled content for temperature-sensitive biologics, forcing reliance on virgin alternatives despite sustainability positioning pressures.
- Virgin Fiber:Bleached kraft or sulfite pulp delivering consistent strength and barrier properties for pharmaceutical serialization and high-definition print reproduction. Integrated mills in Finland and Sweden anchor European supply for EMA-compliant drug packaging.
- Coated Kraft:Clay or polymer-surfaced unbleached kraft for durable shipping and retail applications with moderate print quality requirements.
- Specialty Paper:Engineered substrates with controlled porosity, heat-seal layers, or metallized surfaces for electronics anti-static and pharmaceutical barrier applications.
Virgin Fiber substrates capture the steepest expansion trajectory as pharmaceutical serialization and biologics cold-chain requirements outpace recycled fiber performance limits. Recycled Paper maintains volume leadership in non-barrier food and retail applications.
Application:
Application segmentation tracks the divergence between protective logistics functionality and brand communication at retail point-of-sale, with coating specifications varying accordingly.
- Retail Packaging:Shelf-ready folding cartons with high-gloss aqueous or UV coatings for visual differentiation in mass-market and specialty retail environments. German drugstore and French perfumery channels specify premium rigid formats with soft-touch laminations.
- Shipping Packaging:Corrugated or solid fiber boxes with moisture-resistant coatings for e-commerce fulfillment durability. North American beauty subscription services drive specification toward crush-resistant constructions with inline digital print compatibility.
- Gift Packaging:Rigid boxes with decorative finishes including foil stamping, embossing, and textured coatings for seasonal and limited-edition cosmetics releases.
- Display Packaging:Point-of-sale corrugated or solid fiber structures with high-impact graphics for retail floor merchandising.
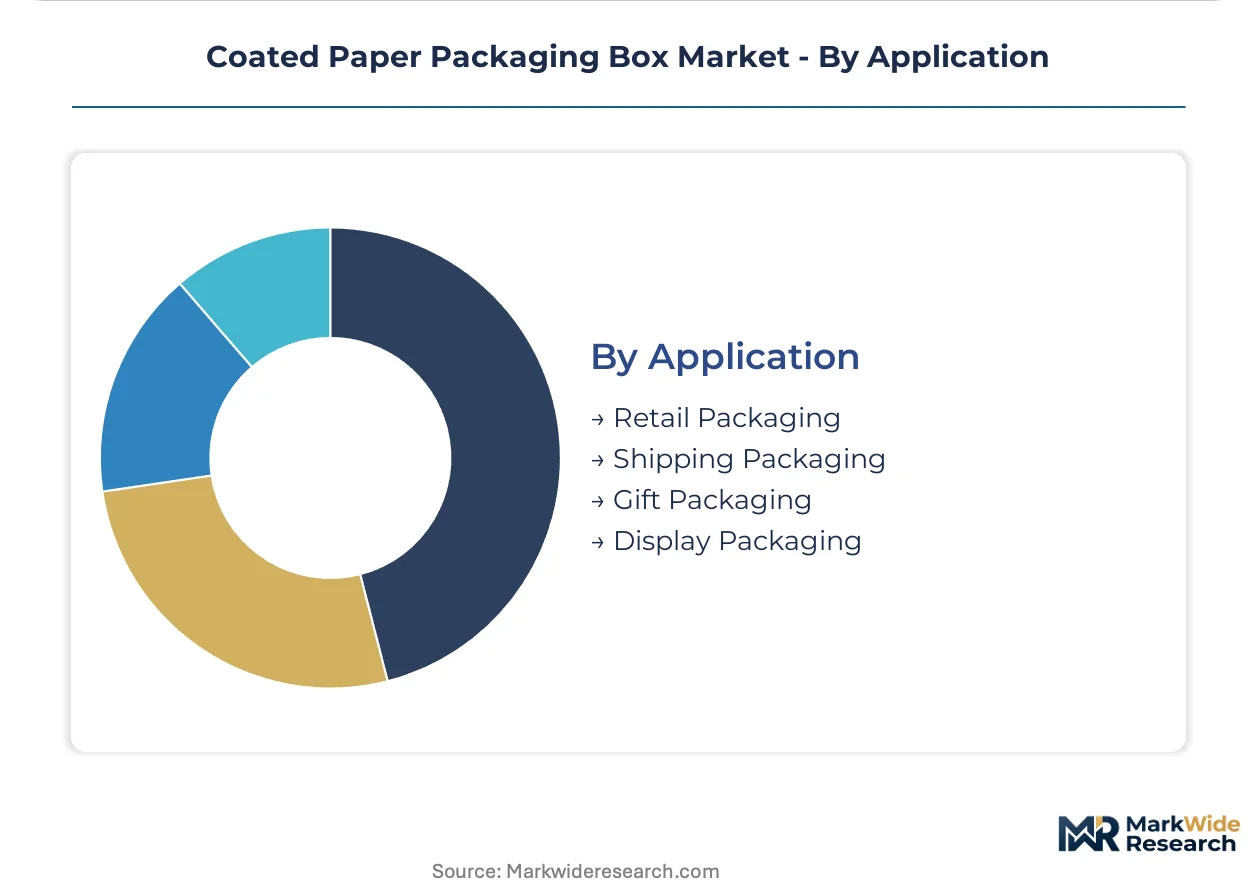
Retail Packaging commands the largest installed base of coating and converting capacity. Shipping Packaging is gaining share fastest as e-commerce penetration reshapes beauty and electronics distribution economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and France diverge in coated paper packaging demand patterns, with German pharmaceutical serialization mandates driving technical substrate specifications while French cosmetics brands prioritize aqueous-coated gift formats for luxury retail channels.
United States
Direct-to-consumer beauty subscription services in New Jersey and Ontario corridor demand 500-unit digital print runs with variable data capability. FDA enforces strict contact-substance migration limits under 21 CFR 176.170 for food-grade applications. Chicago and New York Metro converters are retrofitting inline aqueous coating systems to serve fragmented e-commerce beauty startups.
Germany
EMA EU GDP serialization mandates compress pharmaceutical substrate validation timelines from 26 weeks to 12 weeks. REACH restrictions on perfluorinated alkyl substances force coating chemistry reformulation across paperboard supply chains. Rhine-Main pharmaceutical corridor buyers specify tamper-evident folding cartons with embedded authentication features for temperature-sensitive biologics distribution.
France
Prestige cosmetics brands in Île-de-France and Provence-Alpes-Côte d'Azur are eliminating solvent-based coatings ahead of EU Green Deal enforcement deadlines. ECHA's evolving substance restrictions create formulation uncertainty for fluorinated treatments. Paris and Lyon perfumery channels specify soft-touch laminated rigid boxes for seasonal gift packaging with biopolymer certification under EN 13432.
China
Electronics manufacturers in Yangtze River Delta and Pearl River Delta require anti-static coated boxes with controlled moisture-vapor transmission rates. NMPA pharmaceutical packaging regulations align with international track-and-trace standards for export-oriented drug distribution. Shenzhen and Shanghai converters are qualifying clay-polymer hybrid substrates for high-speed inkjet print receptivity in consumer device packaging.
India
Domestic cosmetics brands in Maharashtra and Gujarat are adopting aqueous-coated rigid boxes for premium positioning in specialty retail. FSSAI food-contact packaging regulations and BIS quality standards shape converter qualification protocols. Mumbai and Ahmedabad packaging clusters are investing in single-pass digital print systems to serve 500-unit minimum runs for direct-to-consumer beauty channels.
Coated Paper Packaging Box Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across substrate manufacturing and converter tiers. Integrated virgin fiber producers in Scandinavia and North America control upstream supply for pharmaceutical serialization applications. Three archetypes dominate: multinational paperboard conglomerates with coating R&D capabilities, mid-cap converters with digital print integration, and regional specialists in aqueous barrier formulations. Competitive moves center on backward integration into virgin fiber supply and rapid qualification of biopolymer-coated substrates for EU zero-waste commitments.
Among North American and European conglomerates, International Paper Company exemplifies scale-driven substrate supply to fragmented e-commerce channels, while WestRock Company occupies a position in coated kraft specialization for pharmaceutical applications. Mondi Group anchors Central European supply with integrated virgin fiber capabilities. These three represent distinct strategic postures: containerboard network leverage, pharmaceutical margin capture, and regional mill integration respectively.
| Leading Market Players |
|---|
| International Paper Company |
| WestRock Company |
| Mondi Group |
| Smurfit Kappa Group |
| Stora Enso Oyj |
| DS Smith plc |
| Huhtamaki Oyj |
| Mayr-Melnhof Karton AG |
| Shenzhen Pack Materials |
| Others |
Value Chain & Pricing Dynamics
EMA's compressed 12-week substrate validation timelines are forcing pharmaceutical buyers to consolidate supplier relationships, concentrating procurement power among integrated virgin fiber mills and squeezing margin on specialty coated grades. This demand-side consolidation feeds directly into pricing power asymmetries across the converter tier.
Pricing Analysis
Capacity additions in Germany and France are reshaping price floors for aqueous-coated rigid boxes as converters race to qualify biopolymer alternatives ahead of EU Green Deal enforcement. Three-tier pricing structure across premium, standard, and economy levels separates EMA-compliant serialization-ready substrates from commodity food-grade folding cartons. Price differentiation hinges on barrier certification tier and volume scale, with pharmaceutical buyers absorbing premium pricing for tamper-evident authentication features. Cost compression in standard-grade recycled fiberboard is intensifying because energy-intensive Scandinavian bleaching processes face input volatility.
Supply Chain Analysis
Freight cost escalation across Baltic and North Sea corridors is amplifying landed cost differentials for virgin fiber substrates sourced from Finnish and Swedish integrated mills. Supply concentrates in Finland, Sweden, and Germany for pharmaceutical-grade bleached kraft, with raw material dependencies on northern softwood pulp, titanium dioxide for clay coatings, and silicone-based barrier polymers. Single-source vulnerability sits with Scandinavian energy-intensive bleaching capacity. Distribution runs through pharmaceutical contract manufacturers in Germany's Rhine-Main corridor and cosmetics converters in France's Île-de-France cluster.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in coated paper packaging rests on aqueous coating chemistry substitution displacing solvent-based alternatives, unlocking premium positioning for EU Green Deal-compliant substrates.
For Market Incumbents: Deploy backward integration into virgin fiber supply to defend against pulp cost volatility and qualification timeline compression. Integrated mills should accelerate biopolymer coating certification under EN 13432 to capture French and German luxury cosmetics procurement. Mid-tier converters must invest in single-pass inkjet and inline aqueous coating systems or face displacement by digital-native competitors serving 500-unit beauty subscription runs. For New Entrants and Emerging Players: Capture the aqueous barrier formulation white-space created by REACH restrictions on perfluorinated alkyl substances, where incumbent coating chemist talent scarcity constrains rapid qualification. Target Indian domestic cosmetics brands in Maharashtra and Gujarat adopting premium rigid boxes for specialty retail positioning. Lead with digital print convergence capability and 12-week pharmaceutical validation documentation as the go-to-market wedge. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap converters possessing integrated digital print and aqueous coating capabilities in North American e-commerce corridors. Long-term viability favors assets with captive virgin fiber supply or exclusive biopolymer certification positioning for EU zero-waste retail commitments. Watch EMA serialization mandate expansion beyond Germany and France as the signal for accelerated substrate specification consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Biopolymer Coating Certification | EN 13432 compostable certification opens premium positioning in French and German luxury markets. |
| Digital Print System Integration | Single-pass inkjet with inline aqueous coating collapses minimum order quantities for beauty subscriptions. |
| Backward Integration into Virgin Fiber | Captive bleached kraft supply insulates against Scandinavian pulp cost volatility and energy shocks. |
| Serialized Cold-Chain Carton Development | Temperature-indicating coatings with 2D barcode substrates address EMA GDP biologics distribution requirements. |
| Coating Chemistry R&D Expansion | Silicone and bio-wax barrier formulations substitute banned fluorinated treatments under REACH restrictions. |
Study Parameters
Direct dialogue with pharmaceutical packaging procurement managers, aqueous coating chemists, digital print system operators, and cosmetics brand supply chain directors grounded qualitative insights in operational reality. Secondary validation drew from EMA serialization guidance documents, ECHA substance restriction proposals, FDA 21 CFR 176.170 migration limit databases, and EU Green Deal packaging waste target disclosures. Bottom-up substrate demand modeling triangulated against top-down converter capacity assessments across German, French, and North American supply clusters.
Bottom-up volume build-ups segmented by product type, end-use vertical, material substrate, and application channel across the analysis window. Pharmaceutical serialization mandates, aqueous coating chemistry substitution curves, and e-commerce beauty channel penetration served as core forecast inputs. CAGRs derived from regression against historical substrate qualification timelines and coating chemistry R&D cycle compression.
Regulatory enforcement delays, pulp fiber cost volatility, and coating chemist talent scarcity are the dominant revision risks to substrate demand projections. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Global Corrugated Board Packaging Market
Paper & Paperboard Packaging
Europe Paper Packaging Market
Paper & Paperboard Packaging
Kraft Envelopes Market
Paper & Paperboard Packaging
Bamboo Packaging Market
Paper & Paperboard Packaging
North America Paper Bags Market
Paper & Paperboard Packaging
Paper Cup Machine Market
Paper & Paperboard Packaging
Kraft Paper Shopping Bag Market
Paper & Paperboard Packaging
US Paper Cups and Paper Plates Market
Paper & Paperboard Packaging
Push-Pull Slip Sheets Market
Paper & Paperboard Packaging
Global Fanfold Corrugated Market
Paper & Paperboard Packaging
Box Liners Market
Paper & Paperboard Packaging
Indonesia Paper Packaging Market
Paper & Paperboard Packaging
Paper Honeycomb Market
Paper & Paperboard Packaging
Paper IBC Container Market
Paper & Paperboard Packaging
C1S Packaging Paper Market
Paper & Paperboard Packaging
North America Corrugated Packaging Market