
 Paper Cup Machine Market | 2026-2036
Paper Cup Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Paper Cup Machine Market Analytics
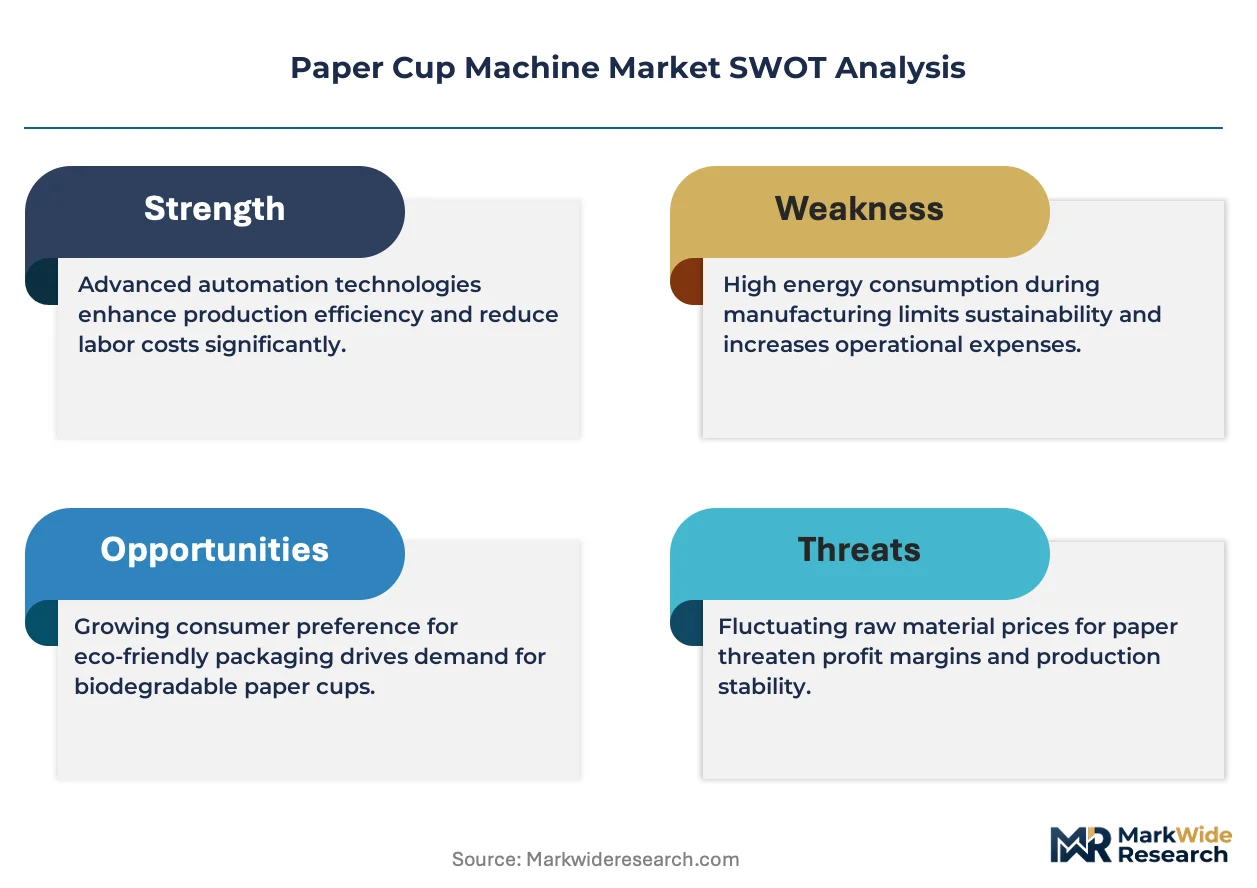
Aftermarket service revenue is reconfiguring profit pools across the paper cup machine sector. Paper Machinery Corporation leverages its installed base in North America to capture recurring parts and retrofit contracts. SEE Machinery sustains competitive intensity through dedicated technical support networks in European coffee packaging hubs. QingHua dominates cost-engineered spare parts logistics for Asian operators seeking minimal downtime.
A paper cup machine forms, seals, and trims paperboard blanks into finished beverage containers at speeds exceeding 200 cups per minute, using heated mandrels and ultrasonic or hot-air sealing to bond side seams and bottom disks. Double-wall cup forming systems command premium positioning as specialty coffee chains require insulation performance without sleeve add-ons. Flexographic printing integration on forming lines anchors margin capture for brands demanding in-line custom graphics. PLA-coated material handling modules represent the fastest-growing technology segment as converters retrofit legacy polyethylene-compatible equipment.
US FDA food-contact substance notifications and EU EFSA framework regulations on paperboard coatings directly determine which forming and sealing configurations qualify for café and restaurant supply contracts. China's SAMR biodegradable standards enforcement and India's FSSAI packaging safety codes are progressively restricting conventional polyethylene barrier coatings, compelling machinery buyers toward PLA-ready or aqueous-barrier platforms. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded capital in non-compliant equipment configurations.
Market Dynamics
India's FSSAI packaging safety codes and China's SAMR biodegradable standards enforcement are forcing machinery buyers toward PLA-ready forming platforms, compressing equipment replacement cycles and reshaping vendor competitive positioning.
Growth Catalysts
- PLA-coated material handling modules:Converters across Maharashtra and Gujarat industrial corridors are retrofitting legacy polyethylene-compatible equipment to meet BIS food-contact material standards.
- Quick-service restaurant automation:Chains in Southeast Asian urban centers are scaling automated cup production lines to serve expanding consumer bases.
- EU EFSA framework regulations:Paperboard coating compliance requirements are anchoring margin capture for brands demanding in-line custom graphics through flexographic printing integration.
Market Restraints
- Specialty paperboard input volatility:Food-grade cup stock prices fluctuate with pulp futures, squeezing converter margins and deferring machinery investments.
- Heated mandrel supply concentration:Precision thermal forming components concentrate among German and Japanese precision engineering suppliers, creating single-source vulnerability.
- Ultrasonic sealing technical limitations:High-speed bonding of aqueous barrier coatings remains unreliable above 180 cups per minute, capping throughput for next-generation materials.
Strategic Opportunities
- Vietnam and Indonesia underpenetration:Domestic packaging OEM clusters remain nascent, opening first-mover positioning for integrated forming-and-printing line suppliers.
- Double-wall specialty coffee application:Insulation performance requirements without sleeve add-ons are creating premium equipment tiers for café chains.
- India PLI scheme incentives:Machinery manufacturing subsidies are attracting component localization investments near paper mill corridors.
Industry Challenges
- Multi-jurisdiction certification timelines:FDA food-contact substance notifications, EU EFSA compliance, and BIS conformity assessments create staggered market entry schedules.
- Legacy polyethylene equipment integration:Retrofitting aqueous-barrier handling modules onto existing forming lines requires custom mechanical engineering and extended commissioning periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paper Cup Machine Market |
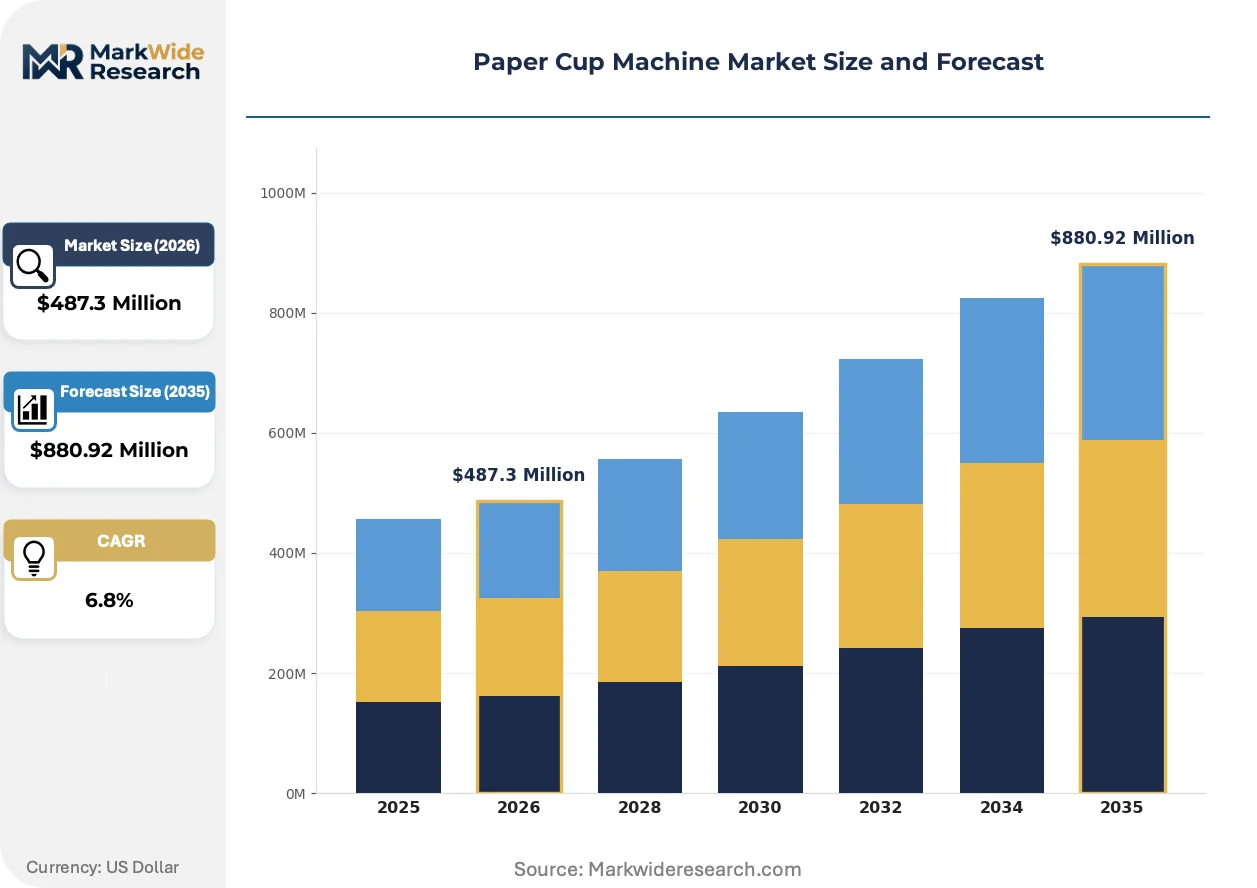
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Wall Cups, Double-Wall Cups, Cold Cups, Specialty Cups End User: Cafes, Restaurants, Food Trucks, Catering Services Material: Recycled Paper, Food-Grade Coating, PLA, Polyethylene Technology: Flexographic Printing, Offset Printing, Die-Cutting, Laminating |
| Companies Covered | QingHua, SEE Machinery, Paper Machinery Corporation, Ruian Mingbo Machinery, SPB Machinery, Hörauf America, TOPPRO Machinery, SKYLYF, Nessco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paper Cup Machine Market Evolving Landscape
Forming line architectures are converging around coating-material flexibility and in-line customization capabilities, compressing the traditional separation between converting and printing operations.
Ultrasonic side-seam bonding technology is hybridizing with hot-air bottom-disk sealing in next-generation cup forming systems. Specialty coffee chains in European packaging hubs are specifying these dual-mode configurations to handle both PLA and aqueous barrier substrates without tooling changeovers. Equipment vendors are compressing delivery lead times for hybrid platforms as converter procurement cycles accelerate.
China's SAMR biodegradable standards enforcement is progressively restricting conventional polyethylene barrier coatings in food-contact applications. Machinery qualification protocols now require documented PLA-compatibility testing before café and restaurant supply contract eligibility. Converters in Zhejiang and Jiangsu provinces are prioritizing aqueous-barrier ready forming lines to maintain domestic market access.
Service contract unbundling is fragmenting traditional equipment procurement models. Asian operators are separating hardware acquisition from technical support agreements, sourcing cost-engineered spare parts through independent logistics networks while retaining OEM commissioning services. This pattern concentrates in India's Gujarat industrial corridor where downtime minimization overrides brand loyalty in vendor selection.
Paper Cup Machine Market Segmentation
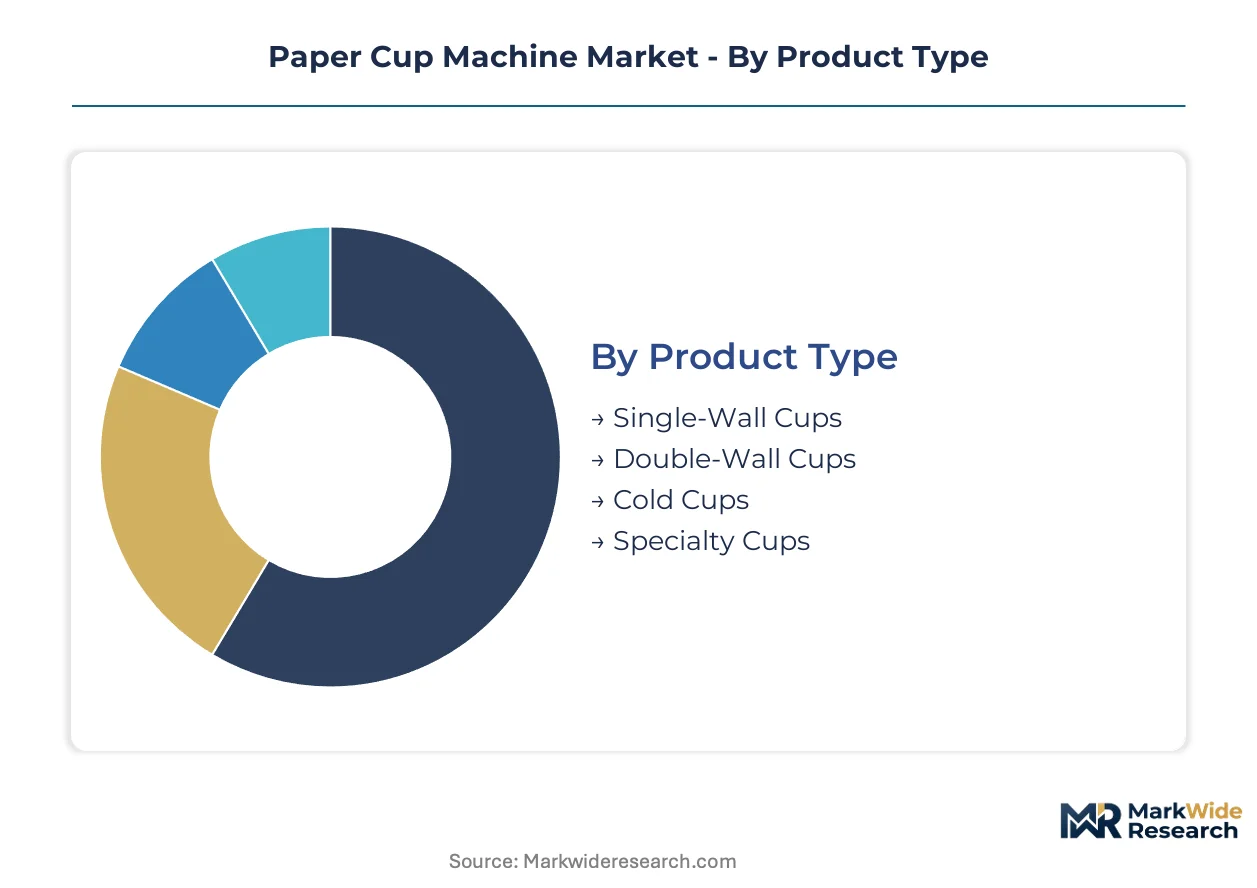
Segmentation in the paper cup machine market reveals how coating compatibility, insulation performance, and in-line customization capabilities determine equipment specification patterns. Machinery buyers select configurations based on beverage temperature requirements, regulatory compliance obligations, and brand differentiation needs.
Product Type:
Equipment specifications span from basic single-layer forming to complex multi-wall systems with integrated thermal management.
- Single-Wall Cups:Forming lines bond single-layer paperboard blanks through heated mandrel expansion and ultrasonic side-seam welding. Quick-service restaurants in India's Maharashtra corridor deploy these systems for high-volume cold beverage service where insulation is secondary to cost efficiency.
- Double-Wall Cups:Nested sleeve-forming modules create air-gap insulation without separate sleeve application. Specialty coffee chains across European packaging hubs specify these configurations to eliminate secondary sleeve costs while maintaining thermal performance for hot beverages.
- Cold Cups:Aqueous-barrier coating compatibility dominates equipment selection for refrigerated beverage applications. Converters prioritize forming lines with reduced heat exposure to preserve coating integrity.
- Specialty Cups:Irregular geometries and embossed surface treatments require custom mandrel tooling and extended forming cycles. Premium café brands commission these systems for limited-edition promotional runs.
The dominant share belongs to Single-Wall Cups, while Double-Wall Cups is closing the gap fastest.
End User:
Procurement patterns diverge sharply between high-frequency disposable users and event-based operators with intermittent production needs.
- Cafes:Daily volume consistency drives investment in automated forming lines with flexographic printing integration. Chains in Southeast Asian urban centers specify PLA-compatible equipment to preempt regulatory compliance deadlines.
- Restaurants:Menu diversification requirements favor modular systems handling multiple cup sizes without tooling changeovers. Full-service operators in Gujarat industrial clusters prioritize aqueous-barrier platforms as FSSAI enforcement tightens.
- Food Trucks:Space-constrained operations demand compact tabletop forming units with manual feed mechanisms. Mobile operators accept lower throughput for portability and minimal installation footprint.
- Catering Services:Batch production cycles suit semi-automatic equipment with quick-change mandrel sets. Event-based demand patterns favor rental and lease arrangements over capital purchase.
Cafes command the largest installed base, though Restaurants are expanding machinery orders most aggressively.
Material:
Coating chemistry determines forming temperature profiles, sealing energy requirements, and regulatory qualification pathways.
- Recycled Paper:Post-consumer fiber content creates variability in caliper and moisture absorption, demanding adaptive tension control and pre-conditioning modules. Sustainability-focused brands in European markets specify these materials despite processing complexity.
- Food-Grade Coating:Conventional polyethylene barriers remain prevalent in legacy equipment configurations. China's SAMR biodegradable standards enforcement is progressively restricting new installations of polyethylene-dependent forming lines.
- PLA:Polylactic acid coatings require modified heat profiles and reduced sealing temperatures to prevent thermal degradation. India's BIS food-contact material standards are accelerating converter migration toward PLA-ready machinery.
- Polyethylene:Traditional barrier chemistry faces regulatory phase-out timelines across multiple jurisdictions. Equipment buyers treat polyethylene compatibility as transitional capability rather than long-term specification.
Food-Grade Coating retains the greatest current share, yet PLA is gaining adoption momentum fastest.
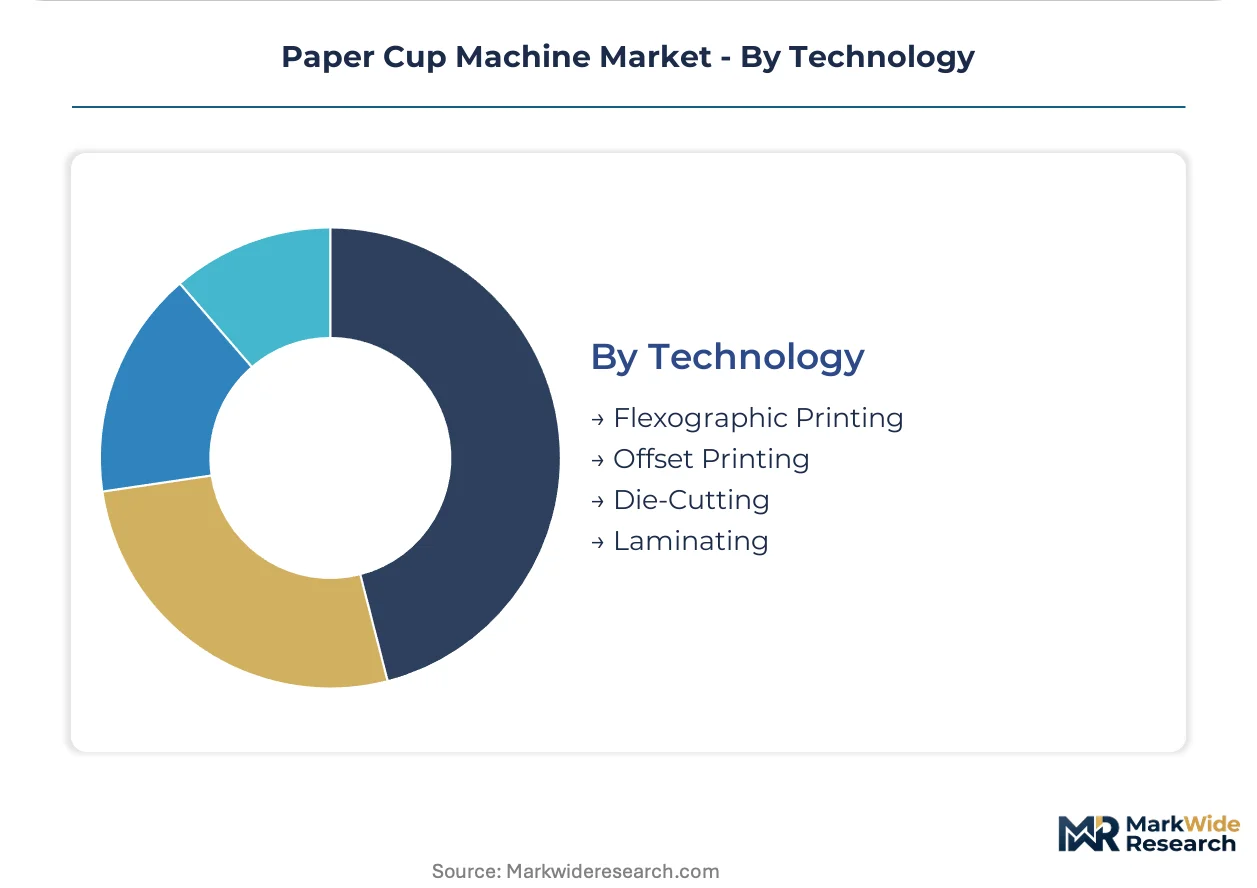
Technology:
Process integration levels separate basic forming operations from value-added customization capabilities.
- Flexographic Printing:In-line graphic application enables real-time design changes and variable data printing. Brand owners specify these integrated lines to compress lead times for seasonal promotional campaigns.
- Offset Printing:Pre-formed blank decoration delivers superior image resolution for premium applications. High-end café chains accept offline processing for quality differentiation.
- Die-Cutting:Precision blank preparation systems determine material yield and edge quality. German and Japanese precision engineering suppliers dominate heated mandrel component sourcing.
- Laminating:Multi-layer bonding modules create composite structures with combined barrier and structural properties. Double-wall specialty applications drive demand for synchronized laminating and forming sequences.
Flexographic Printing holds the leading position, while Laminating is expanding its application scope most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Machine fabricators cluster near paperboard converting hubs in Germany, China, India, and the United States, with secondary concentrations emerging in Southeast Asian manufacturing zones. Regulatory divergence on food-contact coatings is fragmenting equipment qualification pathways across jurisdictions. Industrial corridor density determines aftermarket service economics and spare parts logistics efficiency.
China
Converters in Zhejiang and Jiangsu provinces are prioritizing aqueous-barrier ready forming lines to maintain domestic market access under SAMR biodegradable standards enforcement. GB standards for biodegradable coatings are compelling machinery upgrades toward PLA-compatible and polyethylene-free forming systems. The Yangtze River Delta industrial corridor hosts the densest concentration of cup machine OEMs serving both domestic and export demand.
India
Quick-service restaurants across Maharashtra and Gujarat are scaling automated cup production lines to serve expanding urban consumer bases. FSSAI packaging safety codes are progressively restricting conventional polyethylene barrier coatings, compressing equipment replacement cycles. The Gujarat industrial corridor clusters domestic packaging OEMs near paper mills and converting facilities, minimizing raw material logistics costs.
Germany
Specialty coffee chains across European packaging hubs are specifying dual-mode sealing configurations to handle both PLA and aqueous barrier substrates. EFSA framework regulations on paperboard coatings directly determine which forming and sealing configurations qualify for café and restaurant supply contracts. Precision thermal forming component suppliers concentrate in Baden-Württemberg engineering clusters, creating single-source vulnerability for heated mandrel sourcing.
United States
Paper Machinery Corporation leverages its installed base to capture recurring parts and retrofit contracts across North American quick-service restaurant chains. FDA food-contact substance notifications determine equipment eligibility for foodservice supply contracts, creating staggered market entry schedules relative to European qualification timelines. The Midwest industrial belt maintains legacy polyethylene-compatible equipment fleets while evaluating PLA retrofit economics.
Vietnam
Domestic packaging OEM clusters remain nascent, opening first-mover positioning for integrated forming-and-printing line suppliers from regional exporters. Quick-service restaurant automation is accelerating in Ho Chi Minh City and Hanoi urban centers as Western fast-food chains expand franchise networks. Local converters currently rely on imported machinery from Chinese and Indian suppliers, creating service response time disadvantages.
Paper Cup Machine Market Competitive Landscape
Integrated solution providers and component specialists split the market along the value-added spectrum. The vendor base organizes around three strategic archetypes: full-line system integrators with in-house printing and forming capabilities, precision component fabricators dominating heated mandrel and ultrasonic sealing subsystems, and regional aftermarket service networks optimizing spare parts logistics. Competitive intensity concentrates on coating-material flexibility and commissioning speed rather than pure equipment pricing. M&A activity targets printing-technology integration, while strategic partnerships address multi-jurisdiction certification complexity.
Within the full-line system integrator tier, Paper Machinery Corporation and SEE Machinery exemplify divergent geographic anchoring strategies. QingHua occupies a position among cost-engineered spare parts logistics providers serving Asian operators seeking minimal downtime. Ruian Mingbo Machinery represents the Zhejiang-based fabrication cluster supplying aqueous-barrier ready platforms to domestic and Southeast Asian converters. Nessco and SKYLYF sit within the mid-scale specialist segment, while Hörauf America anchors German precision engineering heritage in North American market development. SPB Machinery and TOPPRO Machinery exemplify the component-to-system expansion pattern visible across Indian and Chinese vendor bases.
| Leading Market Players |
|---|
| QingHua |
| SEE Machinery |
| Paper Machinery Corporation |
| Ruian Mingbo Machinery |
| SPB Machinery |
| Hörauf America |
| TOPPRO Machinery |
| SKYLYF |
| Nessco |
| Others |
Value Network & Pricing Analysis
The Yangtze River Delta freight corridor's container cost dynamics amplify pricing power for German and Japanese heated mandrel suppliers while compressing margins for Asian converters sourcing precision thermal forming components. This logistics-cost asymmetry feeds downstream price differentiation between PLA-compatible forming systems and legacy polyethylene-dependent equipment.
Pricing Analysis
Aftermarket service contracts drive lifetime value capture across equipment tiers. Three-tier pricing structure across premium, standard, and economy levels separates OEM-integrated full-line systems from component-specialist offerings and independent spare parts networks. Cost compression in the economy tier intensifies because Asian operators unbundle hardware acquisition from technical support agreements. Quick-service restaurant chains in India's Gujarat corridor exhibit highest price sensitivity, while European specialty coffee chains prioritize coating-material flexibility over upfront equipment cost.
Supply Chain Analysis
Tariff exposure between China and Southeast Asian markets dominates supply chain risk calculations for machinery fabricators. Precision thermal forming components concentrate among German and Japanese engineering suppliers, while food-grade cup stock draws from Scandinavian and Canadian pulp sources. Single-source vulnerability for heated mandrel sourcing creates procurement bottlenecks during equipment commissioning surges. Distribution runs through OEM-direct channels for integrated systems and independent logistics networks for cost-engineered spare parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as reusable container systems and deposit-return schemes threaten single-use paper cup demand in European regulatory jurisdictions.
For Market Incumbents: Harden coating-material flexibility credentials through aqueous-barrier testing protocols that preempt SAMR and FSSAI enforcement timelines. Capture stranded legacy equipment value by retrofitting polyethylene-compatible lines with PLA handling modules. Backward integration into heated mandrel production reduces single-source vulnerability from Baden-Württemberg and Japanese precision engineering clusters.
For New Entrants and Emerging Players: Build out service-response capabilities in Vietnam's nascent domestic packaging OEM cluster where Western fast-food franchise expansion outpaces local machinery supply. Ho Chi Minh City and Hanoi urban centers present first-mover positioning for integrated forming-and-printing line suppliers. Lead with commissioning speed guarantees rather than equipment pricing to differentiate against established Chinese and Indian exporters.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with dormant paper converting equipment divisions that possess dormant EFSA qualification pathways. The segment's long-term viability hinges on regulatory divergence management across FDA, EFSA, and BIS jurisdictions. Monitor India's PLI scheme machinery manufacturing subsidy disbursement rates as inflection indicator for component localization investment momentum.
| Strategic Initiative | Industry Significance |
|---|---|
| PLA-Compatibility Retrofit Program | Extends legacy equipment economic life under China's SAMR biodegradable enforcement timeline. |
| Heated Mandrel Supply Agreement | Reduces commissioning delays from German and Japanese precision engineering concentration. |
| India PLI Scheme Localization | Captures machinery manufacturing subsidies near Maharashtra and Gujarat paper mill corridors. |
| Aqueous-Barrier Testing Certification | Qualifies forming lines for FSSAI and BIS food-contact material compliance contracts. |
| Vietnam Service Network Expansion | Addresses response-time disadvantages facing Chinese and Indian machinery exporters. |
Research Methodology
Cross-validation between machinery OEM technical documentation and converter procurement records anchors the qualitative findings. Primary interviews with plant engineers at Maharashtra and Gujarat quick-service restaurant suppliers, aftermarket service heads at European packaging hubs, and procurement leads at Zhejiang converting facilities combined with secondary validation from BIS certification databases, FSSAI packaging safety circulars, and SAMR biodegradable standards enforcement notices. Bottom-up equipment shipment tallies and top-down pulp futures correlation analysis triangulate market sizing.
Calibration against historical replacement cycle patterns and regulatory phase-out announcements shapes the projection framework. Segmentation dimensions span coating chemistry compatibility, wall construction type, end-user procurement frequency, and regional regulatory cluster. CAGRs derive from equipment shipment momentum indexed to quick-service restaurant expansion rates and pulp input cost trajectories. PLA coating adoption curves and aqueous-barrier technical reliability thresholds inform material-handling module demand assumptions across the analysis window.
Stress conditions across pulp price volatility bands, heated mandrel supply disruption scenarios, and multi-jurisdiction certification timeline divergence were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding SAMR enforcement stringency and FSSAI packaging safety code implementation pace. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Wrapping Paper Market
Paper & Paperboard Packaging
Waxing Base Paper Market
Paper & Paperboard Packaging
Paper Release Liners Market
Paper & Paperboard Packaging
Boxboard Packaging Market
Paper & Paperboard Packaging
Cardboard Tubs Market
Paper & Paperboard Packaging
Paper Carrier Bags Market
Paper & Paperboard Packaging
Aluminum Foil Laminated Paper Market
Paper & Paperboard Packaging
Macerated Paper Padded Mailers Market
Paper & Paperboard Packaging
Hanging Box Market
Paper & Paperboard Packaging
Freezer Paper Market
Paper & Paperboard Packaging
Postage Stamp Paper Market
Paper & Paperboard Packaging
Paperboard Packaging Market
Paper & Paperboard Packaging
Corrugated Shippers Market
Paper & Paperboard Packaging
Coated Paper Packaging Box Market
Paper & Paperboard Packaging
Recycled Paper Packaging Market
Paper & Paperboard Packaging
United States Corrugated Packaging Market