
 Paper Honeycomb Market | 2026-2036
Paper Honeycomb Market Size, Share, and Industry Trends Forecast 2026-2036
Paper Honeycomb Market Intelligence
Modular packaging configurations is shifting buyer preference toward customizable honeycomb inserts that adapt to irregular product geometries without tooling changes. Smurfit Kappa Group leverages its European corrugated network to bundle honeycomb protective systems with existing boxboard contracts. DS Smith anchors its automotive logistics portfolio with engineered honeycomb dunnage designed for just-in-time vehicle component delivery. International Paper competes on manufacturing scale, operating integrated pulp-to-honeycomb production lines that reduce fiber cost volatility.
Paper honeycomb consists of a cellular core structure formed by expanding adhesive-bonded paper strips into hexagonal cells, typically achieving densities of 20–150 kg/m³ depending on cell size and paper basis weight. The geometry delivers exceptional strength-to-weight ratios for protective packaging, furniture cores, and lightweight structural panels. Reinforced honeycomb variants command premium positioning where load-bearing thresholds exceed standard specifications, while composite honeycomb laminates with kraft facings capture margin pools in aerospace interior fit-outs. Packaging solutions remain the volume anchor, though automotive components represent the fastest-expanding application as vehicle assemblers pursue mass reduction targets.
FDA food-contact regulations in the United States and REACH chemical compliance across Europe shape adhesive selection and recycling certification pathways for honeycomb manufacturers. EPA guidelines on recycled content thresholds influence procurement specifications for logistics firms and building contractors seeking environmental product declarations. Stakeholders must monitor evolving extended producer responsibility frameworks that will determine whether honeycomb producers or their brand-owner customers bear end-of-life collection costs.
Market Dynamics
The EU Green Deal's single-use plastic restrictions are compressing demand for petroleum-based protective packaging, redirecting automotive and logistics procurement toward cellulose honeycomb cores with verified recyclability credentials.
Growth Catalysts
- Automotive lightweighting mandates:Vehicle assemblers in Germany and Czechia specify honeycomb door inserts and trunk floors to meet fleet CO₂ reduction targets, creating specification pull through Tier-1 supplier networks.
- E-commerce fulfillment density:Logistics operators in the Netherlands and Belgium deploy honeycomb dunnage for irregular electronics geometries, cutting void fill volume by half versus molded pulp alternatives.
- REACH chemical compliance:Adhesive formulations certified under ECHA substance restrictions unlock building and furniture applications previously closed to uncertified cellulose composites.
Market Restraints
- Kraft pulp cost volatility:Integrated producers with captive pulp supply command margin stability that merchant honeycomb converters cannot match, concentrating viable production among fiber-integrated groups.
- Moisture sensitivity thresholds:Standard honeycomb cores degrade above 85% relative humidity, limiting outdoor construction and cold-chain applications without laminated barrier treatments.
- Expanded polystyrene price anchoring:EPS protective packaging retains cost advantage in bulk commodity shipments, delaying substitution in price-sensitive agricultural and industrial distribution.
Strategic Opportunities
- Indian building sector penetration:Modular housing developers in Maharashtra and Karnataka specify honeycomb partition cores for rapid-assembly commercial interiors, with BIS certification accelerating specification.
- Aerospace interior laminates:Composite honeycomb with phenolic-impregnated kraft facings captures qualification for cabin sidewalls and galleys as airlines refresh narrow-body fleets.
- Extended producer responsibility frameworks:EU member-state implementations of packaging waste directives position honeycomb producers to capture end-of-life collection contracts from brand-owner customers.
Industry Challenges
- Adhesive curing energy intensity:Hot-melt application systems require sustained thermal input that conflicts with site decarbonization pledges, forcing capital-intensive oven retrofit cycles.
- Cell geometry standardization gaps:Absence of unified ISO dimensional tolerances for hexagonal cell pitch forces dual tooling investments for exporters serving divergent German and French automotive specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paper Honeycomb Market |
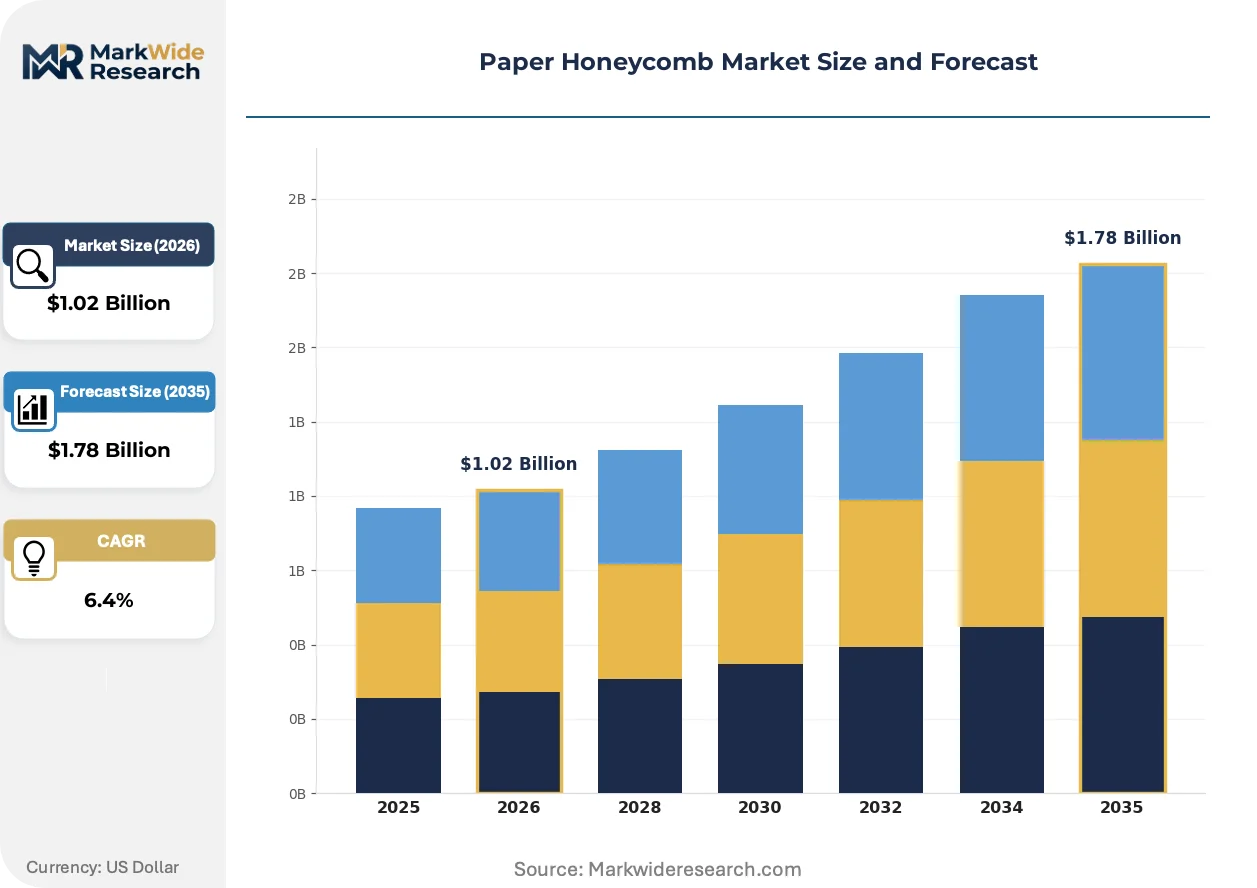
| Market Size in 2026 | $1.02 Billion |
| Market Size in 2035 | $1.78 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Honeycomb, Reinforced Honeycomb, Composite Honeycomb, Fluted Honeycomb Application: Packaging Solutions, Furniture Panels, Automotive Components, Aerospace Interiors, Construction Materials End User Industry: Logistics Firms, Furniture Manufacturers, Vehicle Assemblers, Aircraft Outfitters, Building Contractors Form Factor: Sheets, Rolls, Blocks, Customized Panels |
| Companies Covered | International Paper, Helios Packaging, Smurfit Kappa Group, Honicel Nederland B.V., Lsquare Eco Products Pvt. Ltd., DS Smith, Axxor, Cascades Inc., Packaging Corporation of America, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paper Honeycomb Market Strategic Shifts & Innovations
Bio-based adhesive chemistry and automated core expansion equipment are converging to reset production economics, while procurement specifications increasingly bundle recyclability verification with mechanical performance testing.
Waterborne polyurethane adhesive systems are absorbing moisture-resistance requirements previously met by synthetic barrier films. German automotive seating suppliers have qualified these formulations for trunk floor applications exposed to condensation cycling. The technology is absorbing specification share from laminated alternatives by eliminating secondary facing steps and associated material costs.
REACH substance restriction updates are tightening formaldehyde emission thresholds for interior-grade honeycomb panels. French furniture manufacturers face reformulation deadlines that favor pre-certified adhesive suppliers with established ECHA dossiers. Building contractors in Nordic markets now require environmental product declarations referencing the updated restrictions, filtering procurement toward compliant producers.
Just-in-time component delivery contracts are compressing honeycomb dunnage refresh cycles from annual to quarterly intervals. Tier-1 automotive logistics providers in Stuttgart and Wolfsburg negotiate disposable insert programs that transfer inventory risk to packaging converters. This pattern concentrates volume among regional producers with 72-hour fulfillment radii and modular die-cutting capacity.
Paper Honeycomb Market Segmentation
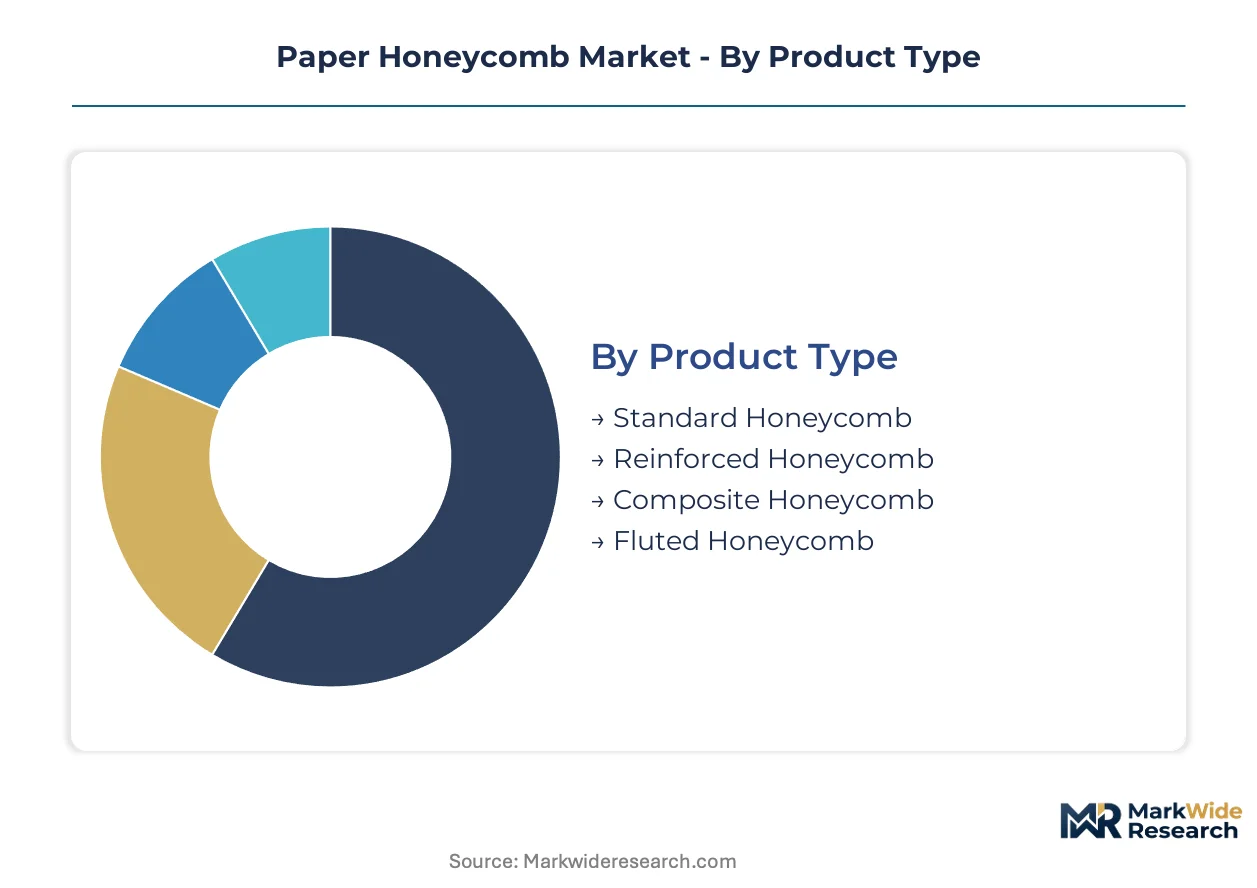
Paper honeycomb manufacturers configure production lines around distinct product architectures that trade density against cost. Each segment carries specific tooling requirements and certification thresholds that shape margin profiles and customer lock-in.
Product Type:
Replacement cycles in protective packaging and automotive interiors drive upgrade decisions toward reinforced and composite variants as specifications tighten.
- Standard Honeycomb:Hexagonal cell structures formed from kraft paper strips bonded with starch or dextrin adhesives, achieving densities between 20–80 kg/m³. Logistics firms in Belgium and the Netherlands specify these cores for e-commerce void fill where cost minimization dominates over load-bearing margins.
- Reinforced Honeycomb:Cell walls incorporate glass fiber or synthetic scrim layers that boost compressive strength by 40–60% over standard grades. German automotive seating suppliers specify these for trunk floor assemblies exposed to condensation cycling, absorbing specification share from laminated alternatives.
- Composite Honeycomb:Phenolic-impregnated kraft facings bonded to expanded cores create sandwich panels qualified for aerospace cabin sidewalls. Aircraft outfitters in France and Germany refresh narrow-body fleets with these laminates.
- Fluted Honeycomb:Corrugated paper layers substitute for hexagonal geometry in low-stress furniture backing and temporary protective shells. Furniture manufacturers in Poland and Czechia specify these for flat-pack interior panels.
Standard Honeycomb sits at the top of the volume ranking, with Composite Honeycomb climbing the fastest.
Application:
Margin concentration follows application complexity, with aerospace and automotive commanding multiples over commodity packaging.
- Packaging Solutions:Dunnage inserts and protective cradles for electronics and automotive components. Logistics operators in Stuttgart and Wolfsburg negotiate quarterly refresh cycles that transfer inventory risk to converters.
- Furniture Panels:Core material for doors, tabletops, and partition walls in flat-pack and modular office systems. Swedish and Danish furniture manufacturers source honeycomb cores to reduce shipping weight.
- Automotive Components:Door inserts, trunk floors, and headliner substrates specified by vehicle assemblers pursuing mass reduction targets. Tier-1 suppliers in Czechia and Germany anchor procurement volumes here.
- Aerospace Interiors:Cabin sidewalls, galleys, and lavatory modules requiring fire-resistant phenolic facings. Qualification timelines stretch 18–24 months, creating defensive moats for certified producers.
- Construction Materials:Partition cores and temporary formwork for rapid-assembly commercial interiors. Modular housing developers in Maharashtra and Karnataka specify these under BIS certification pathways.
Packaging Solutions anchors absolute volume, while Automotive Components gains share fastest on fleet CO₂ compliance deadlines.
End User Industry:
Procurement sophistication varies sharply across buyer categories, with vehicle assemblers and aircraft outfitters imposing qualification regimes that exclude merchant converters.
- Logistics Firms:Third-party fulfillment operators and parcel carriers specifying protective packaging for e-commerce and industrial distribution. These buyers prioritize 72-hour fulfillment radii and modular die-cutting capacity.
- Furniture Manufacturers:Flat-pack and modular office producers sourcing core materials for lightweight panel construction. REACH chemical compliance filters procurement toward adhesive-certified suppliers.
- Vehicle Assemblers:OEMs and Tier-1 suppliers in Germany, Czechia, and France specifying honeycomb for interior mass reduction. Just-in-time delivery contracts compress dunnage refresh cycles to quarterly intervals.
- Aircraft Outfitters:Cabin interior specialists and MRO providers qualifying honeycomb laminates for fleet refurbishment programs. EASA and FAA fire-resistance certifications govern material selection.
- Building Contractors:Commercial and residential developers specifying partition cores for rapid-assembly interiors. Nordic markets now require environmental product declarations referencing updated formaldehyde thresholds.
Logistics Firms generate the highest transaction velocity, with Vehicle Assemblers expanding specification fastest.
Form Factor:
Supply chain configuration determines form factor economics, with sheet and roll formats favoring scale producers while customized panels reward regional die-cutting specialists.
- Sheets:Expanded honeycomb cores supplied in flat rectangular dimensions for lamination and die-cutting operations. Furniture and packaging converters in Poland and Germany standardize on 1200×2400 mm formats.
- Rolls:Continuous unexpanded honeycomb supplied in collapsed configuration for on-site expansion. Logistics firms with in-house packaging operations favor this format for inventory efficiency.
- Blocks:Pre-cut three-dimensional forms for void fill and cushioning applications. Electronics distributors in the Netherlands specify these for irregular product geometries.
- Customized Panels:Finished sandwich laminates with applied facings and perimeter machining for direct assembly. Aerospace and automotive buyers source these to eliminate secondary processing steps.
Sheets dominate production tonnage, with Customized Panels expanding most quickly on outsourcing trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Paper honeycomb manufacturing originated in post-war Europe as kraft paper surplus found structural applications, with German engineering firms pioneering the expansion bonding techniques that defined modern production. The industry retains this geographic imprint while diversifying toward Asia-Pacific packaging demand and North American automotive supply chains.
Germany
Vehicle assemblers in Stuttgart and Wolfsburg specify honeycomb door inserts and trunk floors to meet fleet CO₂ reduction targets under EU Green Deal automotive regulations. REACH chemical compliance administered by ECHA governs adhesive formulations for interior-grade panels. The Baden-Württemberg automotive cluster anchors procurement volumes, with Tier-1 seating suppliers negotiating quarterly dunnage refresh cycles that transfer inventory risk to converters.
United States
Logistics operators deploy honeycomb protective packaging for e-commerce fulfillment density, cutting void fill volume versus molded pulp alternatives. FDA food-contact regulations shape adhesive selection pathways for honeycomb manufacturers serving food distribution networks. The Midwest corrugated manufacturing corridor around Chicago and Milwaukee integrates honeycomb production with existing boxboard infrastructure.
China
Modular housing developers specify honeycomb partition cores for rapid-assembly commercial interiors in Yangtze River Delta construction markets. GB standards and MIIT industrial policy guide quality certification for building material applications. The Pearl River Delta furniture manufacturing cluster sources fluted honeycomb variants for flat-pack export production.
India
Building contractors in Maharashtra and Karnataka specify honeycomb cores for temporary formwork and partition systems in commercial construction. BIS certification accelerates specification pathways for domestic producers. The Pune-Nashik industrial corridor hosts emerging honeycomb fabrication capacity serving Western India modular housing demand.
France
Aircraft outfitters qualify composite honeycomb laminates with phenolic-impregnated kraft facings for narrow-body fleet refurbishment programs. EASA fire-resistance certifications govern material selection for cabin sidewalls and galleys. The Toulouse aerospace cluster drives qualification timelines stretching 18–24 months, creating defensive moats for certified producers.
Paper Honeycomb Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification intensity and fiber integration depth. The vendor base organizes into three tiers: integrated pulp-to-honeycomb producers with captive fiber supply, regional converters serving automotive logistics clusters, and specialized aerospace laminate fabricators holding EASA/FAA qualifications. Consolidation pressure concentrates among merchant converters lacking backward integration into pulp supply. Dominant competitive moves include capacity expansion in automotive corridor proximity and strategic partnerships with Tier-1 logistics providers for just-in-time dunnage programs.
Within the integrated producer tier, International Paper and DS Smith exemplify scale-driven positioning through manufacturing footprint and fiber supply control. Among European specialists, Smurfit Kappa Group and Honicel Nederland B.V. occupy positions anchored to regional automotive and logistics demand. These named entities represent archetype segmentation rather than exhaustive market coverage.
| Leading Market Players |
|---|
| International Paper |
| Helios Packaging |
| Smurfit Kappa Group |
| Honicel Nederland B.V. |
| Lsquare Eco Products Pvt. Ltd. |
| DS Smith |
| Axxor |
| Cascades Inc. |
| Packaging Corporation of America |
| Others |
Cost & Logistics Intelligence
Kraft pulp cost volatility cascades through paper honeycomb pricing tiers, with integrated producers commanding margin stability that merchant converters cannot replicate. Fiber-integrated groups in Germany and the United States leverage captive pulp supply to anchor contract pricing, while non-integrated competitors absorb spot market swings.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs transaction dynamics. Certification grade and volume scale differentiate quotes, with REACH-compliant automotive laminates capturing substantial premiums over commodity packaging cores. Cost compression in standard grades intensifies because expanded polystyrene retains cost advantage in bulk shipments. Logistics firms exhibit highest price sensitivity, while aircraft outfitters prioritize qualification timelines over unit economics.
Supply Chain Analysis
Freight cost differentials between collapsed roll formats and expanded sheet goods shape procurement geography. Manufacturing concentrates in Germany, China, and the United States, with each hub serving distinct specification regimes. Production draws from kraft paper, starch adhesives, and phenolic resins as primary inputs. Single-source vulnerability persists in aerospace-qualified phenolic facings sourced from French and German specialty chemical producers. Distribution runs through regional converter networks with 72-hour fulfillment radii for automotive logistics clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Paper honeycomb offers margin expansion through bio-based adhesive chemistry cost-down curves and aerospace laminate premium-tier shifts. Procurement specifications increasingly bundle recyclability verification with mechanical performance testing.
For Market Incumbents: Deepen backward integration into pulp supply to neutralize fiber cost volatility that erodes merchant converter viability. Expand modular die-cutting capacity within 72-hour fulfillment radii of Stuttgart and Wolfsburg automotive corridors. Defend against waterborne polyurethane adhesive displacement by qualifying next-generation moisture-resistant formulations before REACH formaldehyde deadlines. For New Entrants and Emerging Players: The premium-economy price-point gap in Indian building applications offers white-space entry. Maharashtra and Karnataka modular housing developers specify honeycomb partition cores under accelerating BIS certification pathways. Target construction material segments with simplified fluted honeycomb variants that bypass automotive qualification barriers. Anchor go-to-market through regional fabrication partnerships rather than greenfield manufacturing. For Investors and Strategic Acquirers: Consolidation pressure builds where merchant converters lack captive fiber supply and face adhesive curing energy intensity capital burdens. Long-term viability favors integrated pulp-to-honeycomb producers with aerospace laminate qualifications. Acquisition targets include regional automotive logistics specialists with established Tier-1 supplier relationships. Watch EASA qualification timeline compression as narrow-body fleet refresh cycles accelerate.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kraft Pulp Supply | Captive fiber sourcing insulates margin stability against spot market volatility. |
| Waterborne Polyurethane Adhesive Qualification | Eliminates secondary barrier lamination steps for automotive trunk floor applications. |
| Modular Die-Cutting Capacity Expansion | 72-hour fulfillment radii capture quarterly refresh cycles from Tier-1 automotive logistics. |
| Aerospace Laminate EASA Certification | 18-24 month qualification timelines create defensive moats against commodity competition. |
| Indian BIS Certification Pathway Investment | Maharashtra and Karnataka building codes accelerate specification for partition core applications. |
Research Approach
Bottom-up automotive and logistics demand modeling reconciled against top-down pulp-to-honeycomb production capacity tracking forms the analytical core. Primary interviews with Tier-1 supplier procurement managers, packaging converter operations directors, and aircraft outfitter material qualification engineers combined with secondary validation from ECHA substance restriction updates, BIS certification registries, and customs trade flow data. Automotive production databases and furniture industry shipment records anchored volume triangulation.
Input-output matrices mapped kraft paper consumption through honeycomb expansion equipment to end-use segment absorption across product type, application, and form factor dimensions. CAGRs derived from segment-level demand elasticity modeling against fleet CO₂ compliance deadlines and EU Green Deal plastic substitution timelines. Forecast inputs incorporated REACH formaldehyde threshold revisions and EASA fire-resistance certification pipeline status.
Caveats apply where adhesive chemistry breakthroughs or extended producer responsibility framework implementations could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Paper Cups Market
Paper & Paperboard Packaging
Kraft Paper Shopping Bag Market
Paper & Paperboard Packaging
Corrugated Handle Box Market
Paper & Paperboard Packaging
Composite Cardboard Tube Packaging Market
Paper & Paperboard Packaging
Tacky Transfer Paper Market
Paper & Paperboard Packaging
Cellular Paper Cardboard Market
Paper & Paperboard Packaging
UAE Corrugated Board Packaging Market
Paper & Paperboard Packaging
Clear Envelopes and Mailing Supplies Market
Paper & Paperboard Packaging
Qatar Paper Packaging Products Market
Paper & Paperboard Packaging
United States Corrugated Packaging Market
Paper & Paperboard Packaging
Mailer Box Market
Paper & Paperboard Packaging
Indonesia Paper Packaging Market
Paper & Paperboard Packaging
Paper Release Liners Market
Paper & Paperboard Packaging
Global Multi Depth Corrugated Boxes Market
Paper & Paperboard Packaging
Shredded Paper Filler Market
Paper & Paperboard Packaging
Malaysia Corrugated Boxes Market