
 Box Liners Market | 2026-2036
Box Liners Market Size, Share, and Industry Trends Forecast 2026-2036
Box Liners Market Analysis
REACH compliance is pivoting European procurement toward virgin-grade polyethylene documentation. Plascon Group leverages integrated resin compounding to sustain margin control across custom formulations. Thrace Group anchors southern European supply through multi-site extrusion capacity.
Box liners are flexible containment membranes, typically extruded from polyethylene or polypropylene resins in gauges ranging from 2 to 8 mils, engineered to prevent product contamination, moisture ingress, and particulate migration during storage and transport. Polyethylene dominates material selection for cost-sensitive food packaging applications, while polypropylene captures premium chemical and pharmaceutical segments demanding elevated temperature resistance. The thickness dimension stratifies around medium and heavy gauges, where margin pools concentrate due to specialized compounding requirements and longer production runs.
EMA pharmaceutical packaging guidelines, FDA food contact substance regulations, and EU Packaging and Packaging Waste Regulation collectively determine material eligibility, migration testing protocols, and end-of-life obligations across the value chain. These frameworks elevate compliance costs for non-integrated converters while creating certification barriers for import-dependent suppliers. Stakeholders must monitor evolving extended producer responsibility schemes and substrate-specific recycling quotas to align capital allocation with regulatory trajectory.
Market Dynamics
EU Packaging and Packaging Waste Regulation mandates are forcing converters to requalify entire product portfolios around recyclability thresholds, compressing development timelines and elevating documentation burdens across the value chain.
Growth Catalysts
- Food Safety Mandates:FDA food contact substance regulations and EFSA migration limits are compelling processors to upgrade containment specifications, driving specification-grade liner procurement in dairy and meat packaging.
- REACH Documentation:ECHA substance of very high concern listings are pivoting chemical logistics buyers toward virgin-grade polyethylene with full chain-of-custody certification.
- Germany's Industrial Corridor:Chemical and pharmaceutical logistics clusters in the Rhine-Ruhr region concentrate demand for heavy-gauge polypropylene liners with elevated temperature resistance.
Market Restraints
- Resin Price Volatility:Ethylene and propylene feedstock swings compress converter margins, particularly for medium-gauge polyethylene formulations serving cost-sensitive food segments.
- Supply Concentration Risk:Southern European extrusion capacity dominates specialty polypropylene supply, creating geographic vulnerability for northern European converters.
- Technical Substitution:Rigid intermediate bulk containers and flexible intermediate bulk bags displace box liners in bulk chemical transport above 500-liter volumes.
Strategic Opportunities
- Underpenetrated Pharmaceutical Cold Chain:Cell and gene therapy logistics in Switzerland and Belgium require validated thermal barrier liners with temperature excursion documentation.
- Extended Producer Responsibility Tailwinds:EU Green Deal packaging-specific recycling quotas create first-mover advantage for converters with closed-loop collection infrastructure.
- Digital-Physical Convergence:Integration of RFID-enabled track-and-trace membranes with standard liner substrates enables premium pricing in high-value pharmaceutical lanes.
Industry Challenges
- Compounding Expertise Scarcity:Formulation chemists capable of balancing migration limits with mechanical performance specifications command premium compensation, constraining mid-tier converter expansion.
- Qualification Timeline Compression:Pharmaceutical customers now demand 12-month stability data packages concurrent with prototype submission, doubling pre-commercialization investment.
- Legacy Equipment Retrofit Costs:Co-extrusion lines require substantial modification to process post-consumer recycled content at required gauge consistency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Box Liners Market |
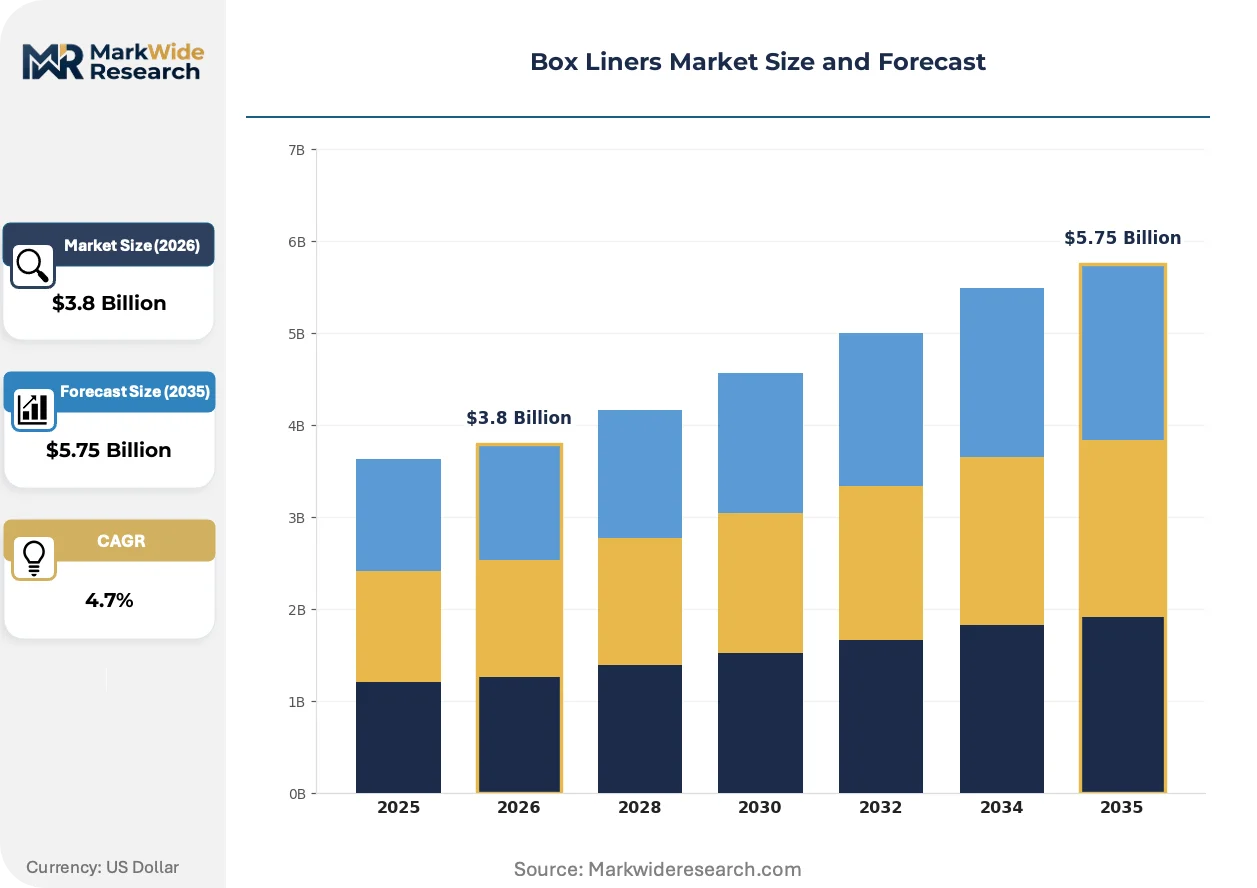
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Polyethylene, Polypropylene, PVC, Paper End Use: Food Packaging, Electronics, Pharmaceuticals, Chemicals Thickness: Thin, Medium, Heavy, Extra Heavy Type: Custom, Standard, Reusable, Biodegradable |
| Companies Covered | Plascon Group, Thrace Group, Dolav, Champion Plastics, IMPAK Corporation, CDF Corporation, Protective Lining Corp., International Plastics Inc., Berry Global Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Box Liners Market Emerging Trajectories
Material science advances and regulatory stringency are compressing traditional product lifecycles, forcing simultaneous innovation across substrate chemistry, manufacturing process, and end-of-life design.
Multi-layer co-extrusion technology is converging with post-consumer recycled content streams to produce food-contact compliant liners with 30-50% recycled content by weight. Major dairy processors in France and the Netherlands are piloting these formulations for cheese and butter packaging. This convergence is compressing the premium gap between virgin and recycled-grade specifications.
EU Green Deal packaging-specific recycling quotas are mandating design-for-recyclability assessments across all new product introductions. Converters must now submit technical documentation demonstrating mono-material construction or compatible layer adhesion before commercial approval. Pharmaceutical and chemical segments are responding most aggressively, with several German logistics operators now specifying recyclable liners as a procurement gate.
Specification consolidation among large food retailers is compressing the number of approved liner SKUs by 40-60% across European supply bases. Buyers now demand single-source accountability for migration compliance, mechanical performance, and end-of-life documentation. This consolidation is most visible in the Nordic retail sector, where three buying cooperatives control 70% of private-label packaged food distribution.
Box Liners Market Segmentation
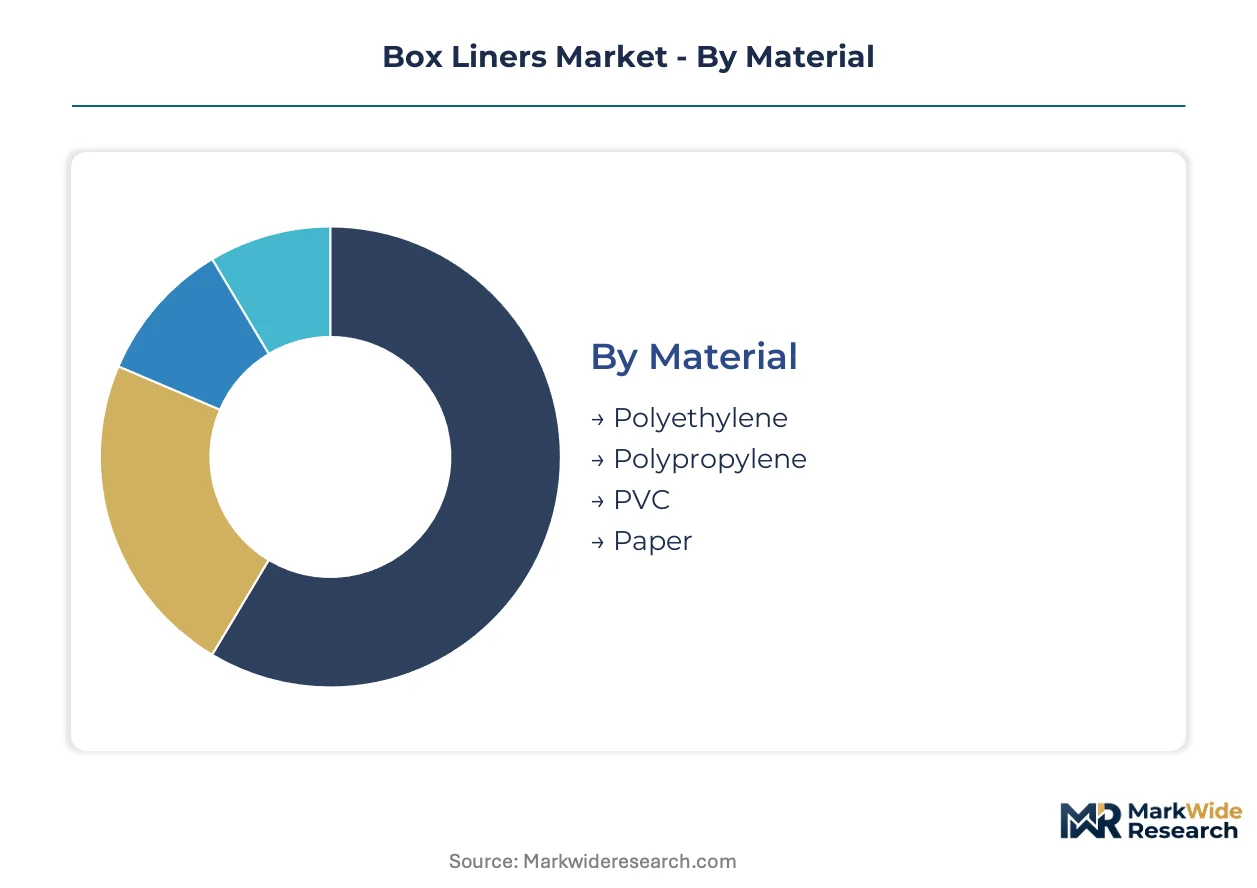
Box liner procurement decisions hinge on regulatory certification requirements that vary sharply across material chemistry and end-use exposure risk. Segmentation reveals where compliance documentation concentrates margin pools and where standard-grade specifications dominate volume.
Material:
FDA food contact substance regulations, EFSA migration limits, and REACH SVHC documentation requirements stratify material selection by end-use exposure tier.
- Polyethylene:Extruded in linear low-density and high-density grades, polyethylene dominates food packaging applications where EFSA migration testing and FDA food contact notification drive supplier qualification. Dairy processors in the Netherlands and meat packers in Germany specify virgin-grade polyethylene with full chain-of-custody REACH documentation, compressing procurement to integrated resin compounders with in-house testing laboratories.
- Polypropylene:Homopolymer and copolymer formulations deliver elevated temperature resistance for chemical and pharmaceutical logistics. Rhine-Ruhr chemical clusters and Swiss pharmaceutical cold chain operators demand heavy-gauge polypropylene with thermal stability data packages, creating specification premiums for converters with multi-layer co-extrusion capability.
- PVC:Phthalate migration concerns and EU Green Deal recyclability mandates are displacing PVC from food contact applications; residual demand concentrates in industrial chemical containment with lower regulatory scrutiny.
- Paper:Grease-resistant and wax-impregnated paper liners serve specialty food segments requiring breathable containment; compostability certifications drive adoption in Nordic retail private-label programs.
Leading the category by volume: Polyethylene. Growing fastest: Polypropylene.
End Use:
Application-specific regulatory frameworks from EMA pharmaceutical guidelines to EPA chemical containment standards determine liner specification complexity and approval timelines.
- Food Packaging:EFSA migration limits and FDA food contact substance regulations mandate virgin-grade materials with documented additive compositions. French cheese processors and Dutch butter packers are piloting 30-50% post-consumer recycled content liners under EU Packaging and Packaging Waste Regulation compliance pathways.
- Pharmaceuticals:EMA Annex 1 containment requirements and Swissmedic cold chain validation protocols drive demand for thermal barrier liners with temperature excursion documentation. Cell and gene therapy logistics in Belgium and Switzerland require validated performance data packages that double pre-commercialization investment.
- Chemicals:REACH SVHC listings and ECHA substance restrictions compel virgin-grade polyethylene documentation for chemical logistics operators in Germany's industrial corridor.
- Electronics:RoHS compliance and static-dissipative requirements govern liner selection for semiconductor and component shipping; specifications concentrate around anti-static polyethylene formulations.
Food Packaging commands the largest volume share. Pharmaceuticals are climbing the fastest as cell and gene therapy logistics expand validated cold chain requirements.
Thickness:
Gauge selection directly correlates with mechanical performance requirements and production run economics, with margin pools concentrating at heavier specifications.
- Heavy:6-8 mil gauges serve chemical and pharmaceutical logistics demanding puncture resistance and elevated temperature stability. German chemical processors specify heavy-gauge polypropylene for Rhine-Ruhr transport corridors, where specialized compounding requirements and longer production runs sustain converter margins.
- Medium:4-6 mil gauges balance cost and performance for food packaging applications; EFSA-compliant formulations dominate French and Dutch dairy segments.
- Thin:2-4 mil gauges address cost-sensitive disposable applications with lower mechanical stress requirements.
- Extra Heavy:Above 8 mil specifications serve bulk chemical containment and specialized pharmaceutical applications with extreme puncture or thermal demands.
Medium gauges lead by volume across food packaging applications. Heavy gauges are gaining share fastest in chemical and pharmaceutical logistics.
Type:
Product architecture determines reuse cycles, end-of-life obligations, and compliance documentation burdens under extended producer responsibility frameworks.
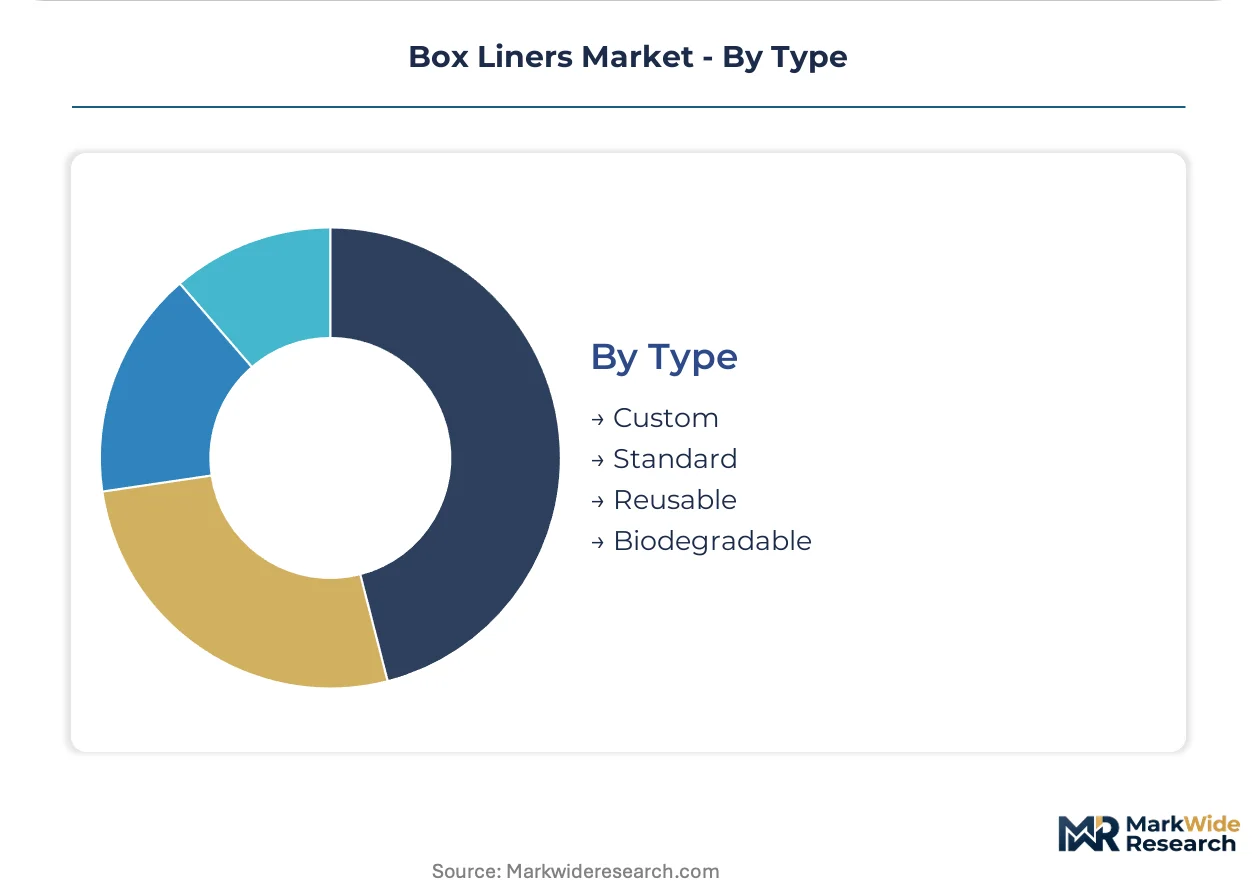
- Standard:Single-use polyethylene and polypropylene liners dominate volume procurement for food and chemical applications where cost minimization outweighs sustainability premiums.
- Custom:Tailored dimensions, multi-layer constructions, and printed branding serve pharmaceutical and specialty chemical segments requiring validated performance documentation.
- Reusable:Durable woven and rigid liner systems address circular economy mandates in EU Green Deal-compliant supply chains; German logistics operators increasingly specify reusable formats as procurement gates.
- Biodegradable:PLA and starch-based formulations serve compostable packaging requirements in Nordic retail and French organic food segments; industrial composting infrastructure availability limits geographic penetration.
Standard liners lead by volume. Reusable formats are expanding most quickly under extended producer responsibility tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany's industrial corridor, where chemical and pharmaceutical logistics clusters drive heavy-gauge polypropylene procurement. Switzerland and Belgium anchor pharmaceutical cold chain requirements. France and the Netherlands pilot food-grade recycled content formulations.
Germany
Rhine-Ruhr chemical processors and pharmaceutical distributors specify virgin-grade polyethylene with full REACH documentation. The EU Packaging and Packaging Waste Regulation compels converters to requalify portfolios around recyclability thresholds. Heavy-gauge polypropylene dominates transport corridors serving BASF and Bayer logistics hubs.
Switzerland
Cell and gene therapy logistics operators demand validated thermal barrier liners with temperature excursion documentation. Swissmedic cold chain validation protocols double pre-commercialization investment timelines. Basel and Zurich pharmaceutical clusters specify premium-grade containment for biologics distribution.
Belgium
EMA pharmaceutical packaging guidelines drive specification-grade liner procurement for vaccine and biologic transport. Port of Antwerp chemical logistics concentrate demand for contamination-resistant containment. Brussels-based regulatory affairs teams coordinate pan-European qualification protocols.
France
Cheese processors in Normandy and dairy cooperatives in Brittany pilot 30-50% post-consumer recycled content liners. EFSA migration limits mandate virgin-grade materials with documented additive compositions. Paris retail buying cooperatives consolidate SKU approval lists, compressing supplier bases by 40-60%.
Netherlands
Butter packers and dairy processors specify medium-gauge polyethylene with EFSA-compliant formulations. Rotterdam chemical logistics clusters require REACH-documented virgin-grade materials for EU-wide distribution. Dutch retail cooperatives mandate mono-material construction for private-label packaging programs.
Box Liners Market Vendor Landscape
North American producers anchor one tier; European specialists hold qualification-intensive segments. The vendor base stratifies across integrated resin compounders, regional extrusion converters, and niche pharmaceutical-grade fabricators. Three archetypes dominate: backward-integrated compounders with captive resin supply, multi-site extrusion operators with geographic coverage, and custom-formulation specialists serving validated pharmaceutical lanes. Competitive moves concentrate on portfolio requalification for EU recyclability mandates and capacity expansion in southern European extrusion corridors.
Among North American fabricators, Plascon Group exemplifies the backward-integrated archetype with in-house resin compounding capability. Thrace Group anchors southern European supply through multi-site extrusion presence. CDF Corporation occupies a position within the specialty chemical and pharmaceutical containment tier, reflecting the qualification-intensive end of the market.
| Leading Market Players |
|---|
| Plascon Group |
| Thrace Group |
| Dolav |
| Champion Plastics |
| IMPAK Corporation |
| CDF Corporation |
| Protective Lining Corp. |
| International Plastics Inc. |
| Berry Global Inc. |
| Others |
Supply Flow & Price Mechanics
Large food retailers and dairy processors in France and the Netherlands concentrate procurement volumes, anchoring a contract-based pricing model where annual offtake agreements lock in medium-gauge polyethylene supply. German chemical logistics clusters in the Rhine-Ruhr region command premium positioning for heavy-gauge polypropylene through validated performance documentation.
Pricing Analysis
Short lead-time premiums of 15-25% apply to pharmaceutical cold chain orders requiring Swissmedic-validated thermal barrier liners with concurrent stability data packages. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale, with EFSA-compliant virgin-grade formulations commanding the top tier. Cost compression in standard-grade polyethylene runs through ethylene feedstock volatility and converter margin pressure. Food packaging buyers exhibit highest price sensitivity, while Swiss pharmaceutical clusters show lowest sensitivity due to regulatory compliance requirements.
Supply Chain Analysis
EMA pharmaceutical packaging guidelines and EU Packaging and Packaging Waste Regulation documentation requirements gate supplier qualification, compressing approved vendor lists to integrated resin compounders with in-house testing laboratories. Extrusion capacity concentrates in Germany, Greece, and Bulgaria, with southern European sites dominating specialty polypropylene supply. Raw material flows draw from naphtha crackers in Rotterdam and Antwerp, plus imported polyethylene resin from Saudi Arabia and the United States. Single-source vulnerability persists in REACH-documented virgin-grade supply chains. Distribution runs through converter-direct relationships with large dairy processors and third-party logistics operators serving chemical corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as converters pursue backward integration into resin compounding to secure margin control and REACH documentation integrity.
For Market Incumbents: Anticipate specification consolidation among Nordic retail cooperatives compressing SKU counts by 40-60%, forcing portfolio rationalization around mono-material recyclable formats. Reinforce southern European extrusion presence to offset geographic concentration risk in specialty polypropylene supply. Prioritize co-extrusion line retrofits for post-consumer recycled content processing to meet EU Green Deal quotas. For New Entrants and Emerging Players: Swiss and Belgian cell and gene therapy logistics operators represent an underserved buyer archetype with unmet demand for validated thermal barrier liners and temperature excursion documentation systems. French cheese processors piloting 30-50% recycled content formulations offer a penetrable entry point through EFSA-compliant compounding partnerships. Lead with digital-physical convergence offerings integrating RFID track-and-trace membranes to differentiate from commodity converters. For Investors and Strategic Acquirers: The window for entry favors backward-integrated compounders with captive resin supply and multi-site extrusion footprints across southern European corridors. Long-term viability hinges on qualification-intensive pharmaceutical-grade capabilities rather than volume-scale food packaging exposure. Monitor EMA guideline revisions on containment requirements as the primary inflection signal for premium specification demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | REACH documentation control secures pharmaceutical qualification pipelines and sustains margin pools. |
| Multi-Site Extrusion Capacity Expansion | Southern European presence reduces geographic vulnerability for northern European converter supply. |
| Post-Consumer Recycled Content Qualification | EU Packaging and Packaging Waste Regulation compliance creates first-mover advantage in retail procurement. |
| RFID-Enabled Track-and-Trace Integration | Swissmedic cold chain validation requirements enable premium pricing in biologics distribution lanes. |
| Pharmaceutical Grade Certification Investment | EMA Annex 1 containment standards double pre-commercialization investment barriers for competitors. |
Methodological Framework
Multi-period observation of EFSA migration limit revisions, REACH SVHC listings, and EU Green Deal packaging quota implementations anchored the trend analysis, supplemented by interviews with resin compounding plant managers, pharmaceutical logistics procurement leads, dairy processor technical directors, and retail category buyers. Secondary validation drew from EMA guideline publications, EU regulatory filings, customs trade data, and SEC disclosures from publicly traded packaging converters. Bottom-up demand modeling across end-use segments triangulated with top-down macroeconomic indicators.
Segment-weighting approaches applied material chemistry, end-use application, thickness gauge, and geographic regulatory cluster dimensions across the projection horizon. CAGRs derived from elasticity-adjusted volume projections incorporating feedstock price sensitivity and qualification timeline compression effects. Pharmaceutical cold chain expansion rates and extended producer responsibility scheme adoption curves served as key forecast inputs.
Revisions become necessary when EMA containment guideline revisions, EU recyclability mandate enforcement intensity, or resin feedstock supply disruptions materialize outside modeled assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Envelope Paper Market
Paper & Paperboard Packaging
Composite Paper Cans Market
Paper & Paperboard Packaging
North America Corrugated Packaging Market
Paper & Paperboard Packaging
Morocco Corrugated Board Market
Paper & Paperboard Packaging
Asia-Pacific Paper Bags Market
Paper & Paperboard Packaging
Parchment Paper Market
Paper & Paperboard Packaging
Japan Paper Packaging Market
Paper & Paperboard Packaging
Binder's Board Market
Paper & Paperboard Packaging
Tea Filter Paper Market
Paper & Paperboard Packaging
Masking Paper Market
Paper & Paperboard Packaging
Macerated Paper Padded Mailers Market
Paper & Paperboard Packaging
Coated Sack Kraft Paper Market
Paper & Paperboard Packaging
United States Paper Packaging Market
Paper & Paperboard Packaging
Postal Tubes Market
Paper & Paperboard Packaging
Desiccant Paper Market
Paper & Paperboard Packaging
Industrial Paper Sacks Market