
 Objective Lens Market | 2026-2036
Objective Lens Market Size, Share, and Industry Trends Forecast 2026-2036
Objective Lens Market Analysis
Aftermarket service revenue for objective lens refurbishment and recalibration is fragmenting across regional service centers and manufacturer-direct channels. Carl Zeiss Microscopy GmbH leverages its captive service network to sustain recurring revenue from installed research microscopy bases. Nikon Instruments Inc. competes through authorized dealer service partnerships that anchor customer loyalty in Asia-Pacific clinical laboratories. Thorlabs, Inc. differentiates by offering modular objective exchange programs that reduce downtime for photonics research users.
An objective lens is an optical element that converges light to form a real image, typically specified by numerical aperture, working distance, and field flatness across defined wavelengths. Manufacturers grind and polish combinations of crown and flint glass, or synthetic fused silica, to achieve diffraction-limited performance for microscopy, lithography, and astronomical observation. Apochromatic objectives command premium positioning in fluorescence microscopy and semiconductor metrology where chromatic aberration correction across multiple wavelengths determines imaging fidelity. Plastic and polycarbonate variants serve cost-constrained projection systems and consumer electronics where thermal stability requirements are less stringent. Anti-reflective coating types dominate material value capture, as multilayer dielectric deposition processes determine transmission efficiency in laser-based applications.
ISO 10110 surface quality standards and EU REACH substance restrictions on coating precursors shape manufacturing compliance costs for objective lens producers. FDA device regulations and EPA chemical handling rules in the United States impose additional testing documentation for clinical microscopy and industrial inspection objectives. Japan's METI maintains JIS standards for optical component interchangeability that influence export qualification protocols. Stakeholders must monitor convergence between semiconductor node shrink requirements and the physical limits of optical resolution as immersion lithography objectives approach theoretical boundaries.
Market Dynamics
Semiconductor node shrink requirements are compressing development cycles for high-NA apochromatic objectives as immersion lithography approaches optical resolution boundaries. EU REACH compliance on optical coating chemistries is simultaneously tightening material sourcing requirements across German precision optics clusters.
Growth Catalysts
- Semiconductor Metrology Demand:Advanced packaging inspection requirements in Taiwan and South Korea are pulling high-numerical-aperture objectives into 24/7 production environments. Sub-7nm node qualification protocols now mandate apochromatic correction across extended wavelength ranges.
- REACH Compliance Deadlines:ECHA substance restriction timelines are accelerating reformulation of anti-reflective coating precursors. Manufacturers qualifying alternative chemistries before 2027 sunset dates capture preferential supplier status with EU-based OEMs.
- Fluorescence Microscopy Expansion:Multi-photon imaging systems in life sciences research are demanding objectives with chromatic correction across 400-900nm ranges. Research institutions in Germany and Japan are prioritizing apochromatic specifications for super-resolution workflows.
Market Restraints
- Synthetic Fused Silica Supply Concentration:High-purity substrate production concentrates among three Japanese and German suppliers. Geopolitical friction or export license delays immediately constrain objective lens throughput for UV-grade applications.
- Physical Resolution Limits:Immersion lithography objectives at 1.35 NA approach theoretical Abbe limits. Further performance gains require computational imaging overlays that extend qualification timelines and capital recovery periods.
- Coating Precursor Cost Volatility:Rare earth dopants and fluoride compounds face price swings tied to Chinese export quotas. Multilayer dielectric deposition processes consume 40-60% of raw material budgets for laser-grade objectives.
Strategic Opportunities
- Modular Exchange Programs:Photonics research facilities are adopting subscription-style objective replacement models that minimize downtime. Thorlabs and regional distributors are piloting inventory-pooling arrangements across US and German university clusters.
- Plastic Objective Penetration:Polycarbonate variants for consumer projection and AR/VR headsets remain underdeveloped relative to glass dominance. Cost-constrained OEMs in China's electronics manufacturing corridor represent untapped volume potential.
- Refurbishment Service Expansion:Aftermarket recalibration and recoating services fragment across regional centers. Captive service networks from established manufacturers face independent competitors offering 30-40% cost reductions for research microscopy bases.
Industry Challenges
- Precision Optics Talent Scarcity:Master optician apprenticeship programs in Germany and Japan graduate fewer practitioners than replacement demand requires. Automated grinding and polishing equipment requires operators with combined mechatronics and metrology competencies that training pipelines underproduce.
- ISO 10110 Certification Timelines:Surface quality verification for diffraction-limited objectives extends 12-18 months for new product introductions. Documentation burdens compound when FDA device regulations apply to clinical microscopy configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Objective Lens Market |
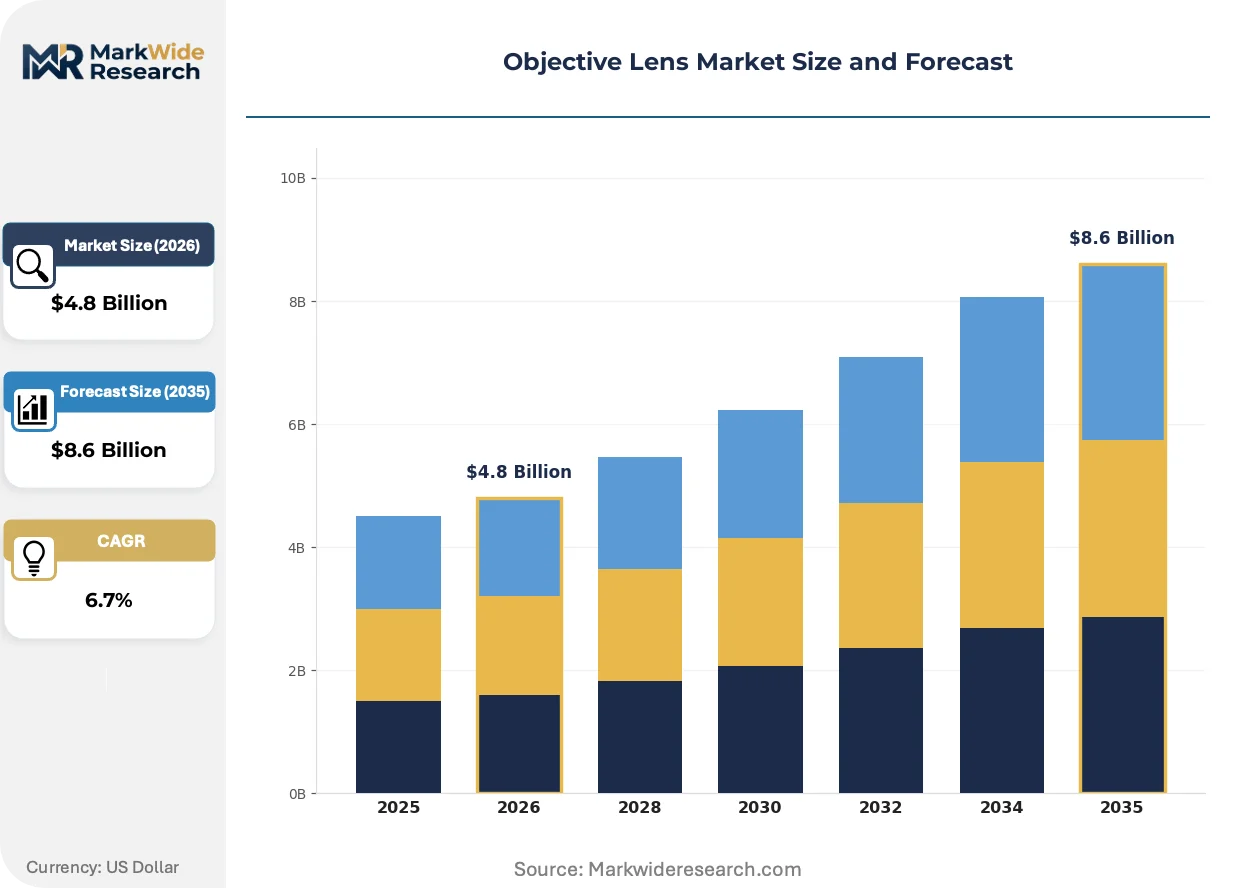
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Monocentric, Apochromatic, Aspheric, Achromatic Application: Photography, Microscopy, Telescopes, Projection Systems Material: Glass, Plastic, Quartz, Polycarbonate Coating Type: Anti-Reflective, Mirror, UV Protection, Scratch Resistant |
| Companies Covered | OLYMPUS CORPORATION, Carl Zeiss Microscopy GmbH, Nikon Instruments Inc., Leica Microsystems, Thermo Fisher Scientific Inc., JENOPTIK AG, Thorlabs, Inc., Mitutoyo Corporation, Newport Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Objective Lens Market Emerging Trajectories
Computational imaging architectures are reshaping how optical performance gets specified and verified. Manufacturers now optimize objectives for algorithmic correction compatibility rather than pure geometric perfection.
Adaptive optics integration is digitizing wavefront correction in live-cell microscopy and semiconductor inspection. Nikon and Zeiss are embedding deformable mirrors directly into objective turrets for real-time aberration compensation. Research laboratories in Germany and California are adopting these systems at 15-20% annual expansion rates, compressing demand for purely passive optical designs.
ECHA's 2024-2027 REACH authorization timeline is restricting chromium trioxide and PFAS-based coating precursors. Objective lens producers are qualifying atomic layer deposition alternatives that sacrifice some transmission efficiency for compliance certainty. Semiconductor metrology segments in the Netherlands and Ireland are absorbing 8-12% cost premiums for REACH-compliant supply chains.
Equipment-as-a-service models are fragmenting traditional capital procurement in clinical and research microscopy. Leasing arrangements with embedded maintenance clauses are displacing outright purchase in US hospital systems and European university consortia. Asia-Pacific distributors report 25-30% of new fluorescence microscope placements now flow through subscription structures rather than direct sales.
Objective Lens Market Segmentation
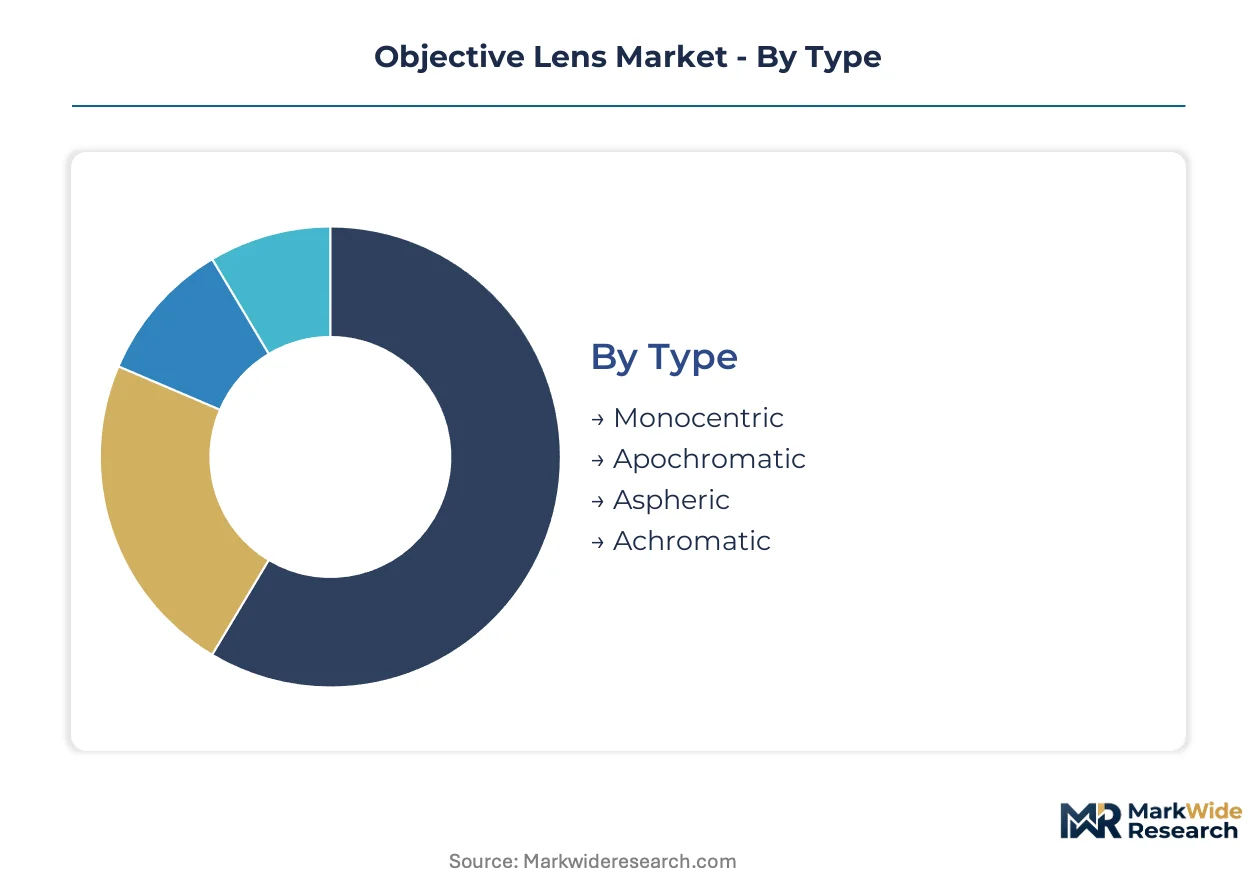
Objective lens specifications diverge sharply across end-use environments, from semiconductor cleanrooms requiring diffraction-limited performance to consumer projection systems prioritizing cost efficiency. Manufacturers configure glass compositions, chromatic correction levels, and coating stacks to match the precision demands of each application tier.
Type:
Use cases span from basic imaging to sub-nanometer metrology, demanding distinct aberration correction architectures.
- Apochromatic:Three or more lens elements with exotic glass formulations eliminate chromatic aberration across 400-900nm wavelengths. Semiconductor inspection equipment in Taiwan and South Korea specifies these for sub-7nm node qualification protocols where imaging fidelity determines yield.
- Achromatic:Two-element designs using crown and flint glass pairs correct chromatic aberration at two wavelengths. Educational microscopy and entry-level astronomical observation in Germany's precision optics cluster absorb steady volume despite compression from computational imaging alternatives.
- Monocentric:Single spherical center of curvature reduces coma and astigmatism in wide-field applications. Military targeting systems and specialized surveillance equipment drive procurement from captive defense suppliers.
- Aspheric:Non-spherical surface profiles minimize spherical aberration without multiple elements. Mobile phone cameras and AR/VR headsets in China's electronics corridor specify molded glass and plastic variants for weight reduction.
The dominant share belongs to Apochromatic, while Aspheric is closing the gap fastest.
Application:
End-use environments dictate thermal stability, environmental sealing, and illumination compatibility requirements.
- Microscopy:Life sciences research and clinical diagnostics demand objectives with extended working distances and fluorescence transmission. Super-resolution workflows in German and Japanese institutions prioritize chromatic correction across visible and near-infrared ranges.
- Photography:Interchangeable lens systems and machine vision modules require compact form factors with consistent MTF performance. Industrial automation deployments in South Korea specify ruggedized variants for factory floor environments.
- Telescopes:Astronomical observation stresses thermal stability and low scatter for faint object detection. Amateur and professional observatories in Chile's Atacama Desert and Hawaii's Mauna Kea drive demand for large-aperture apochromatic designs.
- Projection Systems:Digital cinema and home theater applications prioritize light throughput and thermal durability. Laser-illuminated installations in US commercial cinema chains specify anti-reflective coated objectives for color gamut consistency.
Microscopy commands the largest revenue pool, though Photography is expanding most quickly through machine vision integration.
Material:
Substrate selection trades optical performance against thermal properties and manufacturing cost.
- Glass:Crown, flint, and synthetic fused silica formulations deliver diffraction-limited performance with thermal stability. UV-grade fused silica from Japanese and German suppliers constrains throughput for semiconductor lithography applications.
- Quartz:Crystalline silicon dioxide transmits deep ultraviolet wavelengths for excimer laser systems. Semiconductor metrology equipment in the Netherlands specifies quartz objectives for 193nm immersion lithography inspection.
- Plastic:Molded acrylic and polystyrene variants reduce weight and cost in disposable medical optics. Point-of-care diagnostic devices in India's manufacturing corridor absorb growing volumes despite thermal expansion limitations.
- Polycarbonate:Impact-resistant thermoplastic serves consumer electronics and safety eyewear where mechanical durability outweighs optical precision. AR/VR headset producers in China's Shenzhen cluster specify polycarbonate objectives for mass-market price points.
Glass retains the dominant position, while Polycarbonate is gaining share fastest in consumer electronics applications.
Coating Type:
Surface treatments determine transmission efficiency, laser damage threshold, and environmental durability.
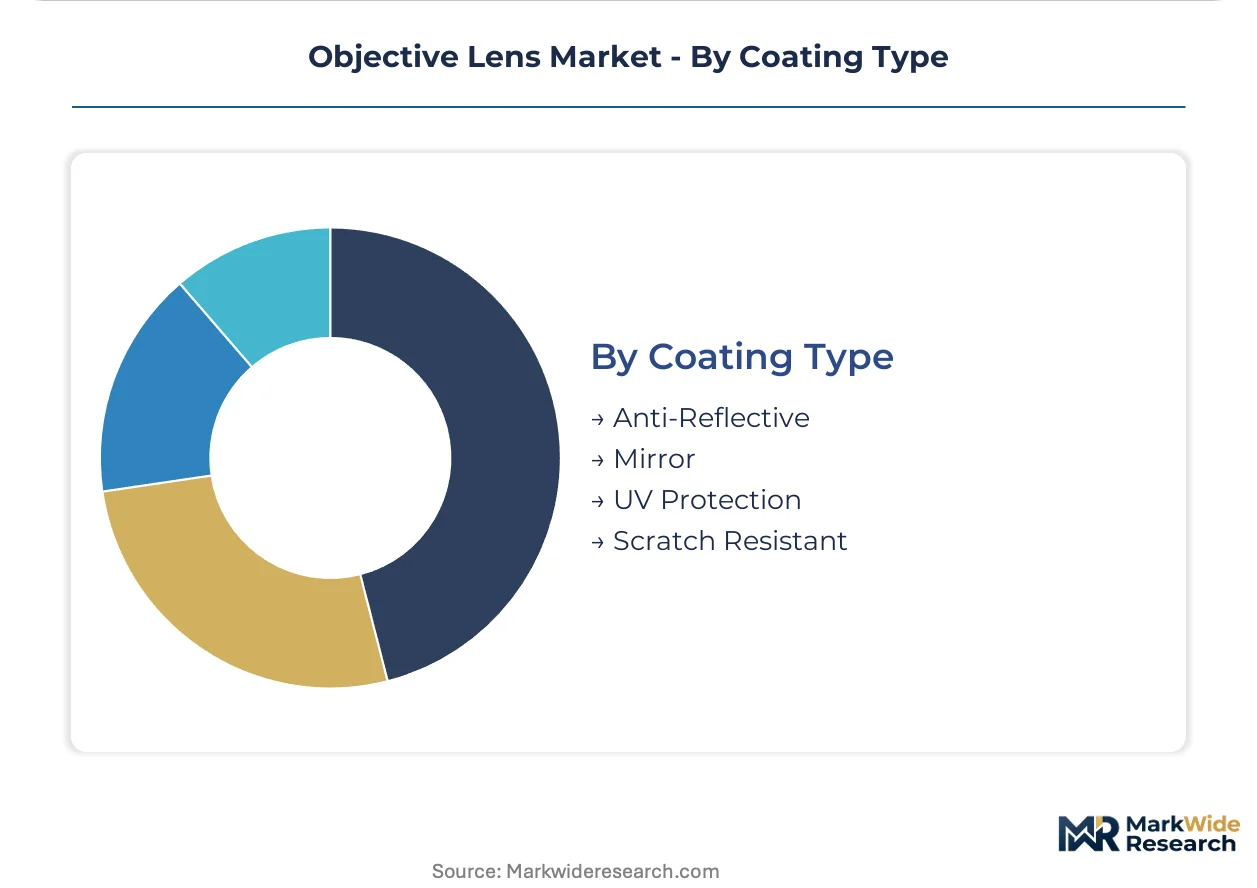
- Anti-Reflective:Multilayer dielectric stacks maximize transmission across specified wavelength bands. EU REACH restrictions on chromium trioxide and PFAS precursors are accelerating reformulation timelines for German coating houses.
- UV Protection:Absorptive and reflective filters block ultraviolet transmission for biological safety and detector preservation. Fluorescence microscopy systems in Japanese research institutions specify these for live-cell imaging protocols.
- Mirror:Metallic and dielectric reflective coatings redirect light paths in folded optical systems. Astronomical telescope producers in the United States specify protected silver coatings for infrared observation capabilities.
- Scratch Resistant:Diamond-like carbon and hardened oxide layers extend objective lifetime in field-deployed equipment. Military and industrial inspection applications in Israel's defense technology cluster mandate these for operational reliability.
Anti-Reflective coatings generate the highest material value capture, with UV Protection seeing the steepest expansion trajectory from life sciences demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and Japan consume high-NA apochromatic objectives for semiconductor metrology, while China and India absorb plastic variants for cost-constrained electronics and medical devices.
United States
Clinical microscopy demand from hospital systems drives apochromatic objective procurement. FDA device regulations impose testing documentation burdens on manufacturers qualifying clinical configurations. Boston and San Diego research clusters absorb premium fluorescence microscopy systems for super-resolution workflows.
Germany
Precision optics manufacturers in Jena and Oberkochen specify high-NA objectives for semiconductor inspection equipment. EU REACH compliance deadlines accelerate reformulation of anti-reflective coating chemistries before 2027 sunset dates. Bavarian coating houses absorb cost premiums for compliant supply chains.
Japan
Synthetic fused silica substrate production concentrates among domestic suppliers constraining UV-grade objective throughput. METI maintains JIS standards for optical component interchangeability influencing export qualification protocols. Nagoya and Tokyo precision optics clusters serve domestic semiconductor equipment manufacturers.
China
Electronics manufacturing corridors in Shenzhen specify polycarbonate objectives for AR/VR headsets and consumer projection systems. NMPA regulations govern medical device optics while MIIT standards shape industrial inspection equipment. Yangtze River Delta photonics research facilities pilot modular objective exchange programs.
South Korea
Advanced packaging inspection requirements pull high-numerical-aperture objectives into 24/7 production environments. MFDS regulates clinical microscopy configurations while national semiconductor programs drive metrology equipment procurement. Busan-Ulsan manufacturing zones anchor demand from memory and logic chip fabricators.
Objective Lens Market Vendor Landscape
Capability concentration sits with German and Japanese precision optics specialists; scale advantage sits with diversified instrumentation conglomerates. The vendor base separates into three tiers: captive optics divisions of microscopy systems houses, independent precision optics fabricators, and modular photonics component suppliers. Dominant competitive moves include strategic partnerships for coating chemistry qualification and geographic expansion through authorized service networks.
Among German precision optics specialists, Carl Zeiss Microscopy GmbH and JENOPTIK AG exemplify the capability-driven tier with deep vertical integration into glass formulation and metrology. Nikon Instruments Inc. represents the diversified systems house archetype, leveraging microscopy equipment placements to anchor recurring objective lens revenue. Thorlabs, Inc. occupies the modular supplier position, serving research photonics users through exchange programs and inventory-pooling arrangements.
| Leading Market Players |
|---|
| OLYMPUS CORPORATION |
| Carl Zeiss Microscopy GmbH |
| Nikon Instruments Inc. |
| Leica Microsystems |
| Thermo Fisher Scientific Inc. |
| JENOPTIK AG |
| Thorlabs, Inc. |
| Mitutoyo Corporation |
| Newport Corporation |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese polycarbonate molding facilities is compressing margins for commodity-grade objectives while tightening supply of UV-grade synthetic fused silica from Japanese and German producers. This utilization divergence splits pricing power between cost-driven consumer electronics tiers and precision-constrained semiconductor metrology segments.
Pricing Analysis
Long-term offtake agreements dominate procurement for high-NA apochromatic objectives in semiconductor metrology, while spot purchasing persists for plastic variants in consumer projection. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with ISO 10110 surface quality tiers commanding substantial premiums. Pricing pressure stems from REACH-compliant coating precursor reformulation costs flowing through German precision optics clusters. Clinical microscopy buyers in US hospital systems exhibit lowest price sensitivity due to bundled service contracts, whereas AR/VR headset manufacturers in Shenzhen absorb aggressive cost compression.
Supply Chain Analysis
Tariff exposure between China and the United States disrupts polycarbonate objective flows for consumer electronics while leaving precision glass supply chains intact. Raw material sourcing concentrates in Japan and Germany for synthetic fused silica substrates, with coating precursor chemicals drawing from domestic EU suppliers and Chinese rare earth processors. Single-source vulnerability pervades UV-grade fused silica production, where three suppliers control global throughput. Distribution runs through authorized dealer networks for research microscopy and direct OEM integration for semiconductor equipment manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges from diverging precision requirements between computational imaging adopters and traditional optical performance buyers. Modular service models and plastic objective penetration create addressable niches outside established German-Japanese strongholds.
For Market Incumbents: Insulate core semiconductor metrology positions through captive synthetic fused silica supply arrangements with Japanese substrate producers. Accelerate REACH-compliant coating chemistry qualification ahead of ECHA sunset deadlines to lock in preferential supplier status with Dutch and Irish OEMs. Counter independent refurbishment competitors by embedding predictive maintenance algorithms into research microscopy service contracts. For New Entrants and Emerging Players: Establish a beachhead in India's point-of-care diagnostic device corridor where plastic objective specifications remain undemanding and regulatory pathways simplify. Target polycarbonate variants for AR/VR headset producers in China's Yangtze River Delta seeking second-source supply security. Deploy inventory-pooling subscription models across German university photonics clusters to differentiate from capital-sale incumbents. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across atomic layer deposition coating facilities as ECHA restrictions displace legacy chemical vapor deposition processes. Five-to-ten year viability favors specialists with backward integration into glass formulation rather than pure coating houses. Acquisition targets should demonstrate qualified alternative chemistries and installed base service contracts. Monitor ECHA authorization timeline adherence as the inflection signal for supplier viability.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Coating Qualification | ECHA sunset deadlines force reformulation investments that determine EU market access. |
| Modular Objective Exchange Programs | Subscription models reduce downtime for photonics researchers at German university clusters. |
| Synthetic Fused Silica Backward Integration | Captive substrate supply secures throughput for UV-grade semiconductor lithography objectives. |
| Plastic Objective Manufacturing Scale-Up | Polycarbonate variants address cost constraints in China's AR/VR headset production corridor. |
| Aftermarket Refurbishment Network Expansion | Independent service centers capture 30-40% cost advantages over manufacturer-direct channels. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with precision optics executives, semiconductor equipment procurement leads, and fluorescence microscopy laboratory directors; and secondary validation through customs trade data, SEC filings from diversified instrumentation conglomerates, ISO standard revision documentation, and ECHA substance restriction timelines. Bottom-up triangulation across objective lens unit economics and top-down cross-checks against semiconductor capital expenditure disclosures anchored volume and value estimates.
Forecast inputs incorporated numerical aperture tier evolution, chromatic correction specification shifts, and coating chemistry transition curves across the projection horizon. Segmentation dimensions modeled include aberration correction architecture, end-use environment thermal requirements, substrate material thermal properties, and surface treatment durability classes. CAGRs derived from installed base replacement cycles, node shrink roadmaps, and research funding trajectories in German and Japanese precision optics clusters.
Sensitivities concentrate around ECHA authorization timeline delays, synthetic fused silica export license friction, and computational imaging adoption rates displacing passive optical performance premiums. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Ring Laser Gyroscope Market
Optical Components
North America Photonic Sensors Market
Optical Components
Co-Packaged Optics Market
Optical Components
Optical Waveguide Market
Optical Components
High Speed Fiber Optic Sensor Market
Optical Components
Coherent Optical Equipment Market
Optical Components
Picosecond and Femtosecond Fiber Lasers Market
Optical Components
Fiber Optic Collimating Lens Market
Optical Components
Optical Cross Connect Market
Optical Components
Mexico Extreme Ultraviolet Lithography (EUVL) Systems Market
Optical Components
Infrared Filter Market
Optical Components
Optical Fiber Array Market
Optical Components
Optical Film Market
Optical Components
LAMEA Lithium Niobate Modulator Market
Optical Components
Integrated Quantum Optical Circuits Market
Optical Components
Fiber-Optic Attenuator Market