
 Industrial Polishing Machine Market | 2026-2036
Industrial Polishing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Polishing Machine Market Analysis
Aftermarket service revenue is tilting toward predictive maintenance contracts as OEMs seek to lock in recurring income beyond initial equipment sales. SINTOKOGIO, LTD. leverages its foundry-equipment heritage to dominate wet-barrel polishing in East Asian metalworking markets. Rösler Oberflächentechnik GmbH anchors its position through captive consumables supply, controlling abrasive media formulations that extend machine performance. EMAG GmbH & Co. KG specializes in integrating polishing modules into turnkey turning-grinding-polishing lines for powertrain manufacturers.
Industrial polishing machines are automated or semi-automated systems that use abrasive belts, wheels, or vibratory media to achieve specified surface roughness values, typically measured in Ra or Rz parameters, for metal, ceramic, or composite workpieces. These systems serve critical functions in manufacturing quality assurance, removing material to precise tolerances while preparing surfaces for subsequent coating, bonding, or corrosion-protection treatments. Belt polishers occupy the largest installed base across heavy fabrication, though orbital polishers represent the fastest-expanding category as robotics integrators demand programmable finishing paths for complex geometries. Electric-drive technology leads unit shipments, yet pneumatic systems retain margin strength in explosive-atmosphere applications governed by ATEX and OSHA directives. Surface preparation applications generate the highest consumables pull-through, while finishing commands premium pricing in aerospace component workflows.
OSHA crystalline silica exposure limits and REACH restrictions on hexavalent chromium compounds are forcing manufacturers to redesign wet-polishing enclosures and filtration architectures. China's MEE enforces wastewater discharge standards that elevate closed-loop system demand in Jiangsu and Zhejiang provinces. ISO 9001 quality-management certification and sector-specific NADCAP accreditation for aerospace suppliers increasingly gate market access for polishing-equipment vendors. Stakeholders must weigh capital intensity against service-annuity potential when configuring go-to-market models for next-generation installations.
Market Dynamics
Automotive electrification is compressing surface-finish tolerances for electric drivetrain housings and battery enclosures, forcing polishing-equipment vendors to integrate force-feedback controls and real-time Ra monitoring into standard machine configurations.
Growth Catalysts
- REACH hexavalent chromium restrictions:European metal finishers are replacing chrome-plating lines with precision polishing systems to achieve comparable corrosion resistance without hazardous electrolytes.
- Yangtze River Delta manufacturing concentration:Jiangsu and Zhejiang provincial environmental mandates are accelerating wet-blasting replacement with closed-loop polishing technologies in China's densest metalworking cluster.
- ISO surface-finish standards for EV powertrains:German and Japanese automotive OEMs are expanding automated polishing lines to meet Ra specifications for electric motor housings and reduction gear casings.
Market Restraints
- Abrasive media supply concentration:Specialty ceramic and synthetic abrasive formulations depend on limited suppliers in East Asia, exposing machine vendors to input cost volatility and freight disruptions.
- ATEX compliance overhead:Pneumatic polishing systems for explosive atmospheres require certified enclosures and spark-resistant components that inflate machine costs by 25-40 percent versus standard electric units.
- Laser surface texturing substitution:Selective laser melting and direct energy deposition are capturing aerospace turbine blade finishing applications previously served by precision belt polishers.
Strategic Opportunities
- India PLI scheme for auto components:Production-linked incentives for advanced automotive manufacturing are attracting polishing-equipment vendors to establish service depots in Tamil Nadu and Gujarat industrial corridors.
- Closed-loop coolant recycling mandates:China's MEE wastewater discharge standards are creating retrofit demand for filtration-integrated polishing systems among existing installed base owners.
- Robotics integrator channel expansion:Collaborative robot arm suppliers are bundling programmable orbital polishers into turnkey finishing cells for small-batch medical device manufacturers.
Industry Challenges
- NADCAP accreditation timelines:Aerospace polishing-equipment vendors face 12-18 month qualification cycles to meet sector-specific surface-preparation standards for flight-critical titanium and nickel superalloy components.
- Legacy wet-blast system integration:Metal finishers seeking to hybridize existing facilities encounter control-architecture incompatibilities between pneumatic blast cabinets and modern servo-driven polishing modules.
- Crystalline silica exposure mitigation:OSHA permissible exposure limits for respirable silica are forcing fabricators to reengineer dry-polishing enclosures with negative-pressure containment and HEPA filtration, extending project commissioning schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Polishing Machine Market |
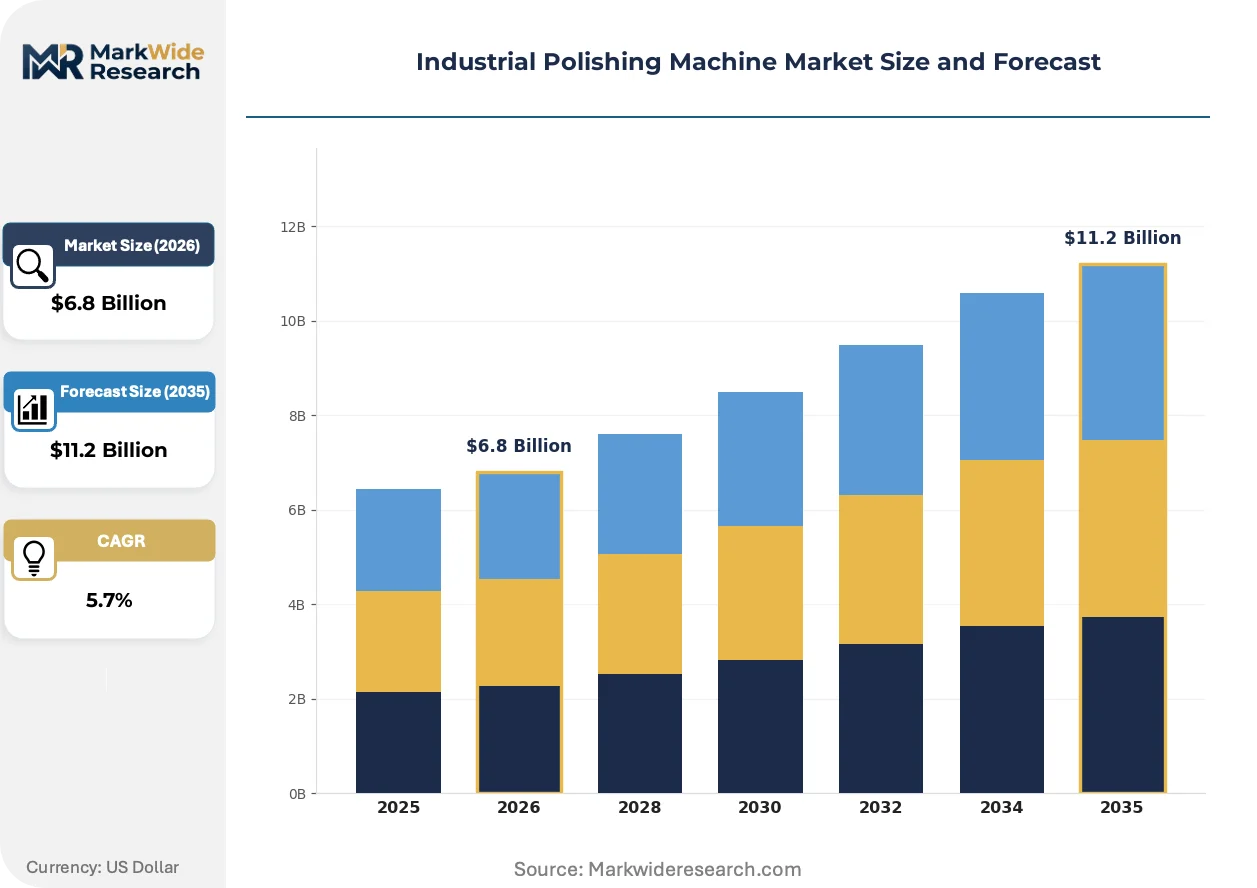
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Belt Polishers, Orbital Polishers, Rotary Polishers, Floor Polishers Technology: Pneumatic, Electric, Hydraulic, Manual End User: Manufacturing, Automotive, Aerospace, Marine Application: Surface Preparation, Finishing, Restoration, Coating |
| Companies Covered | SINTOKOGIO, LTD., GF Machining Solutions AG, Rösler Oberflächentechnik GmbH, Lapmaster Wolters, EMAG GmbH & Co. KG, Walther Trowal GmbH, Ecoclean GmbH, Struers, OTEC Präzisionsfinish GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Polishing Machine Market Emerging Trajectories
Force-controlled robotic polishing is displacing manual finishing in high-mix manufacturing, while regulatory pressure on hazardous compounds accelerates wet-process innovation. These shifts are compressing equipment replacement cycles and rewiring vendor-customer relationships around performance guarantees rather than capital sales.
Adaptive force-feedback polishing heads with six-axis compliance are rendering obsolete fixed-path robotic programs that cannot accommodate casting variability or weld-seam irregularities. Tier-one automotive suppliers in Germany and Japan are deploying these systems for electric drivetrain housing finishing, achieving consistent Ra values below 0.4 micrometers without manual rework. The technology is compressing programming time from days to hours and enabling small-batch production economics previously unattainable with dedicated automation.
REACH Annex XVII restrictions on chromium trioxide in surface treatment are compelling European metal finishers to abandon decorative chrome plating for precision mechanical polishing alternatives. The regulation is redirecting capital expenditure toward multi-stage polishing lines with integrated cleaning and passivation modules. Aerospace component suppliers in France and Italy are most affected, with NADCAP-accredited facilities leading the process requalification effort to maintain OEM approval status.
Power-by-the-hour service contracts are displacing traditional equipment purchase-and-maintain arrangements among capital-constrained metalworking job shops. Polishing-machine vendors are unbundling hardware from consumables and predictive maintenance subscriptions, with revenue concentration shifting toward annuity streams. This model is most visible in the US Midwest automotive supplier base, where private-equity-owned fabricators prioritize operational expenditure flexibility over balance-sheet asset ownership.
Industrial Polishing Machine Market Segmentation
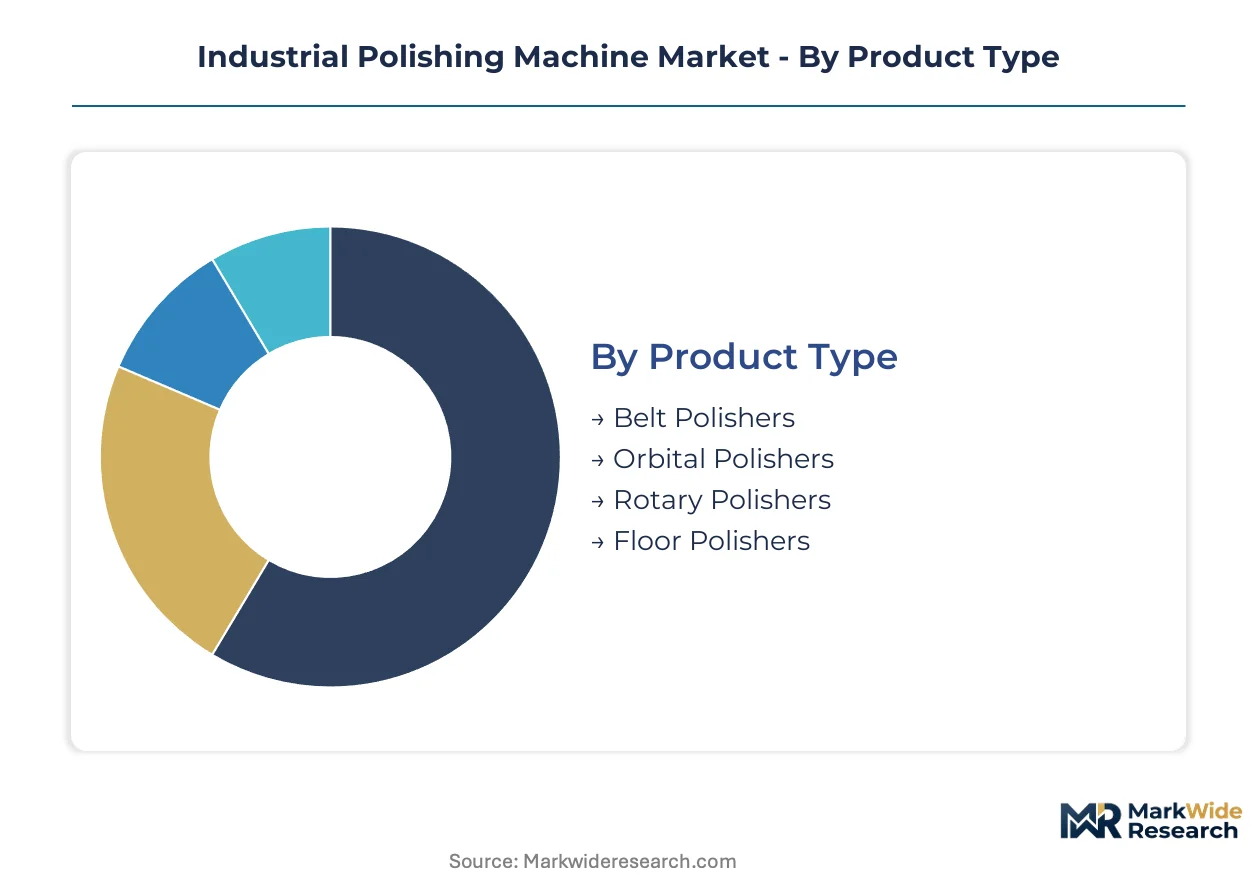
Segmentation in the industrial polishing machine market reveals distinct service-intensity profiles across equipment categories. Aftermarket attach rates vary dramatically by product type and end-use environment, reshaping vendor profitability models and channel investment priorities.
Product Type:
After-sales-service intensity escalates with machine complexity, as automated systems require predictive maintenance contracts and consumables replenishment programs.
- Belt Polishers:Abrasive belt systems dominate heavy fabrication installations across Germany's Ruhr Valley steel processing corridor. German automotive OEMs specify these units for electric drivetrain housing finishing, where ISO Ra tolerances below 0.4 micrometers demand frequent belt replacement and spindle calibration services.
- Orbital Polishers:Random-orbit motion systems with programmable pathing are displacing fixed-path automation in high-mix manufacturing. Robotics integrators in Japan's Aichi Prefecture bundle these into turnkey cells for medical device manufacturers, compressing programming cycles from days to hours.
- Rotary Polishers:Direct-drive rotary tools serve specialized aerospace turbine blade finishing applications.
- Floor Polishers:Walk-behind and ride-on surface restoration equipment concentrate in commercial marine maintenance yards.
Belt polishers hold the largest share; momentum sits with orbital polishers.
Technology:
Power-source selection directly determines regulatory compliance burden and recurring service revenue potential.
- Electric:Servo-motor systems with force-feedback controls command premium pricing in automotive powertrain manufacturing. China's Jiangsu Province environmental mandates favor electric units for closed-loop coolant compatibility, though ATEX-certified variants for explosive atmospheres inflate capital costs substantially.
- Pneumatic:Compressed-air systems retain defensive positioning in oil-and-gas fabrication and chemical processing environments where spark resistance is mandatory. OSHA and ATEX certification requirements extend commissioning schedules and elevate vendor service dependency.
- Hydraulic:High-torque hydraulic drives persist in heavy marine propeller and rudder finishing operations.
- Manual:Hand-held tools survive in restoration and spot-repair applications with minimal automation requirements.
Electric systems dominate unit shipments; pneumatic configurations defend margin strength in hazardous-environment niches.
End User:
Customer-type segmentation exposes divergent procurement patterns between capital-intensive OEMs and maintenance-focused operators.
- Manufacturing:General metalworking fabricators in China's Zhejiang Province drive replacement demand as provincial MEE wastewater standards force wet-blasting system retirement. Power-by-the-hour contracts are displacing traditional purchase arrangements among capital-constrained job shops.
- Automotive:Tier-one suppliers in Japan's Toyota City cluster deploy adaptive force-feedback polishing heads for electric motor housing production. Surface-finish tolerances for battery enclosures and reduction gear casings are compressing equipment replacement cycles.
- Aerospace:NADCAP-accredited facilities in France and Italy face 12-18 month qualification timelines for flight-critical titanium and nickel superalloy component finishing.
- Marine:Shipyard operators in South Korea's Geoje industrial complex prioritize corrosion-protection surface preparation for hull and propulsion systems.
Manufacturing captures the broadest installed base; automotive applications are climbing the fastest.
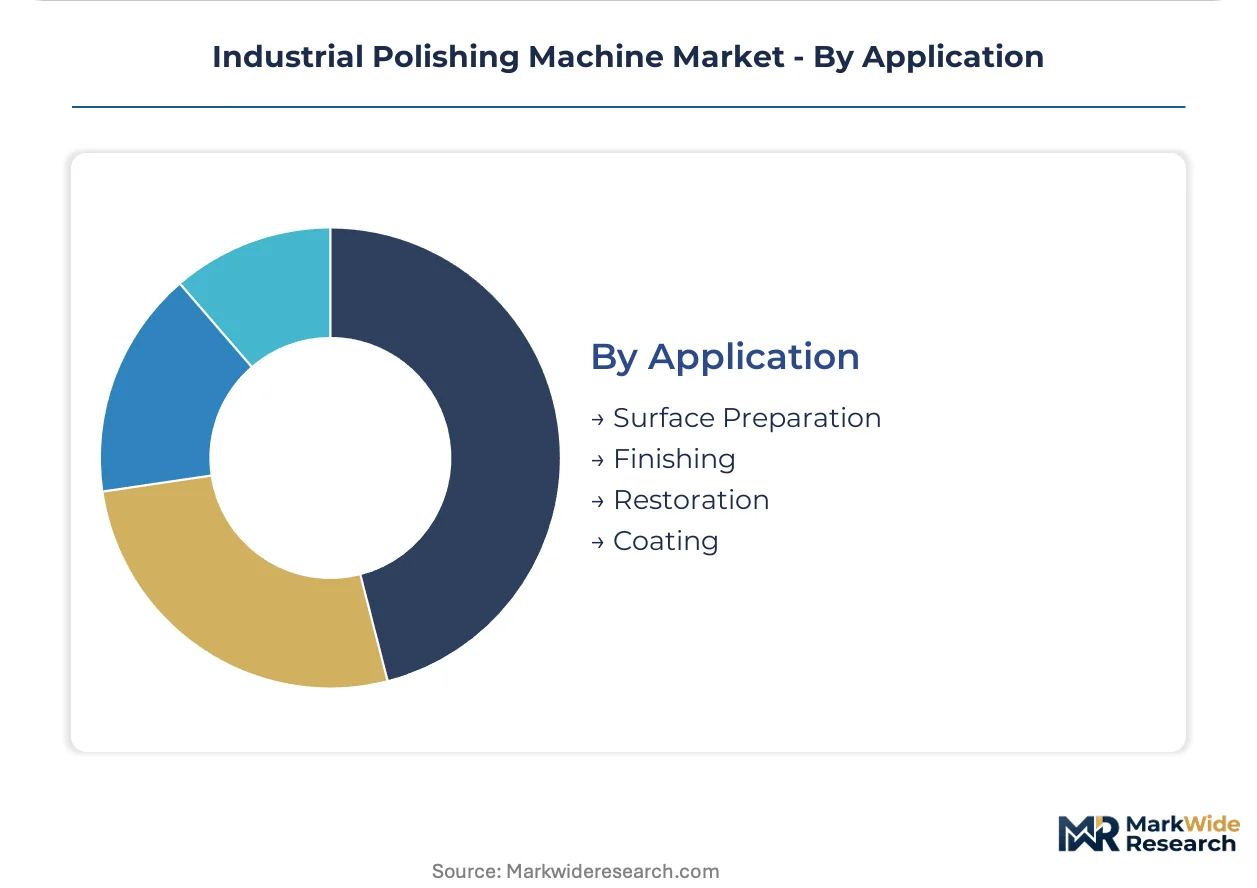
Application:
Workflow-position segmentation determines consumables pull-through intensity and equipment specification requirements.
- Surface Preparation:Aggressive material removal for coating adhesion generates the highest abrasive media consumption rates. REACH hexavalent chromium restrictions are redirecting European capital expenditure from plating lines toward multi-stage polishing with integrated passivation.
- Finishing:Final surface refinement for aesthetic or functional specifications commands premium pricing in aerospace component workflows. Real-time Ra monitoring and force-feedback controls are becoming standard configurations.
- Restoration:Existing surface rehabilitation in marine and infrastructure maintenance drives aftermarket tooling demand.
- Coating:Pre-treatment surface conditioning for thermal spray and PVD deposition applications requires specialized contamination control.
Surface preparation anchors consumables revenue; finishing commands the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. German and Japanese automotive OEMs accept premium pricing for force-feedback systems meeting ISO Ra tolerances below 0.4 micrometers. Chinese metalworking job shops in Jiangsu and Zhejiang provinces prioritize retrofit economics as provincial environmental mandates force wet-blasting replacement.
Germany
Automotive electrification compresses surface-finish specifications for electric drivetrain housings. KBA vehicle-type approval requirements extend to component-level surface preparation documentation. The Ruhr Valley steel processing corridor hosts the densest belt polisher installed base in Europe, with OEMs specifying frequent spindle calibration services.
Japan
Toyota City tier-one suppliers deploy adaptive force-feedback polishing heads for electric motor housing production. METI industrial efficiency standards reward closed-loop coolant recycling retrofits. Aichi Prefecture robotics integrators bundle orbital polishers into turnkey cells for medical device manufacturers, compressing programming cycles.
China
Provincial MEE wastewater discharge standards in Jiangsu and Zhejiang accelerate wet-blasting system retirement. Dual carbon goals favor electric servo-motor systems over pneumatic alternatives in Yangtze River Delta manufacturing clusters. Zhejiang metalworking fabricators drive replacement demand for filtration-integrated polishing systems.
United States
OSHA crystalline silica exposure limits force reengineering of dry-polishing enclosures with negative-pressure containment. Private-equity-owned fabricators in the Midwest automotive supplier base prioritize power-by-the-hour contracts over capital purchases. EPA hazardous waste regulations elevate closed-loop system demand among existing installed base owners.
India
PLI scheme production-linked incentives for advanced automotive manufacturing attract polishing-equipment vendors to establish service depots. BIS certification requirements for imported industrial machinery extend commissioning timelines. Tamil Nadu and Gujarat industrial corridors concentrate new facility investment for export-oriented component production.
Industrial Polishing Machine Market Vendor Landscape
Capability concentration sits with specialized surface-technology vendors; scale advantage sits with diversified industrial equipment conglomerates. The market structures around three tiers: captive consumables suppliers controlling abrasive media formulations, turnkey line integrators bundling polishing modules into multi-stage production systems, and regional service specialists anchoring aftermarket revenue through predictive maintenance contracts. Dominant competitive moves include backward integration into specialty abrasive supply and geographic expansion through robotics integrator channel partnerships.
Within the captive consumables tier, Rösler Oberflächentechnik GmbH exemplifies the model of controlling media formulations that extend machine performance. SINTOKOGIO, LTD. represents East Asian metalworking market presence derived from foundry-equipment heritage. EMAG GmbH & Co. KG occupies a position among turnkey line specialists integrating polishing modules into turning-grinding-polishing sequences for powertrain manufacturers.
| Leading Market Players |
|---|
| SINTOKOGIO, LTD. |
| GF Machining Solutions AG |
| Rösler Oberflächentechnik GmbH |
| Lapmaster Wolters |
| EMAG GmbH & Co. KG |
| Walther Trowal GmbH |
| Ecoclean GmbH |
| Struers |
| OTEC Präzisionsfinish GmbH |
| Others |
Supply Flow & Price Mechanics
Jiangsu Province's dense concentration of abrasive media formulators shapes downstream pricing power for machine vendors serving China's Yangtze River Delta manufacturing cluster. Provincial environmental mandates from MEE accelerate demand for closed-loop systems, compressing retrofit economics while elevating premium pricing for filtration-integrated configurations.
Pricing Analysis
Long-term power-by-the-hour service contracts dominate capital-constrained metalworking job shops, displacing traditional equipment purchase arrangements. Three-tier pricing structure across premium force-feedback systems, standard servo-motor units, and economy pneumatic configurations reflects certification grade and after-sales bundling intensity. Pricing pressure stems from REACH-driven chrome-plating substitution as European finishers redirect capital toward multi-stage polishing lines. Tier-one automotive suppliers in Germany and Japan exhibit lowest price sensitivity, prioritizing ISO Ra compliance below 0.4 micrometers over capital expenditure minimization.
Supply Chain Analysis
Export-control regimes on precision servo-motor technology limit component flows from Japan and Germany to Chinese system integrators, elevating lead times for force-feedback polishing heads. Specialty ceramic and synthetic abrasive formulations draw from concentrated suppliers in China, Japan, and South Korea, exposing machine vendors to input cost volatility. Single-source vulnerability concentrates in high-purity alumina media for aerospace finishing applications. Distribution runs through captive consumables programs anchored by Rösler Oberflächentechnik and regional service specialists deploying predictive maintenance subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial polishing equipment sits in early-cycle expansion as automotive electrification compresses surface-finish tolerances and environmental mandates force wet-blasting system replacement across East Asian metalworking corridors.
For Market Incumbents: Harden defensive positioning through backward integration into specialty abrasive formulations that extend machine performance and lock in consumables revenue. Deepen channel control by embedding predictive maintenance subscriptions into standard equipment configurations. Prioritize NADCAP accreditation investment to capture aerospace qualification timelines stretching 12-18 months for flight-critical titanium finishing. For New Entrants and Emerging Players: Mid-market medical device manufacturers in Japan's Aichi Prefecture represent the most penetrable entry point, as robotics integrators seek programmable orbital polishers for high-mix production cells. India's Tamil Nadu and Gujarat industrial corridors under PLI scheme incentives offer second-mover advantage for service depot establishment. Lead with power-by-the-hour contract structures that match private-equity-owned fabricator preference for operational expenditure flexibility. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial equipment conglomerates with underoptimized surface-technology divisions lacking captive consumables integration. Long-term viability centers on annuity revenue concentration exceeding hardware sales within a 5-10 year window. Monitor NADCAP accreditation backlog as inflection indicator for aerospace segment pricing power recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Abrasive Media | Rösler Oberflächentechnik controls formulations that extend machine performance and consumables pull-through. |
| Force-Feedback Control Integration | EMAG GmbH & Co. KG embeds adaptive polishing heads into turnkey turning-grinding-polishing lines for powertrain OEMs. |
| Closed-Loop Coolant Recycling Retrofit | China's MEE wastewater standards in Jiangsu and Zhejiang accelerate filtration-integrated system replacement demand. |
| Robotics Integrator Channel Partnership | Orbital polisher bundling into turnkey cells compresses programming cycles for medical device manufacturers in Aichi Prefecture. |
| NADCAP Accreditation Investment | Aerospace suppliers in France and Italy face extended qualification timelines for flight-critical titanium finishing equipment. |
Methodological Framework
A standing panel of maintenance directors at Tier 1 automotive suppliers, plant engineers in China's Zhejiang Province metalworking cluster, OEM procurement teams specifying electric drivetrain finishing lines, and aftermarket service heads at captive consumables providers provided ongoing calibration. Primary interviews combined with secondary validation against customs records for abrasive media trade flows, SEC 10-K filings from diversified industrial equipment conglomerates, and MEE wastewater discharge enforcement data. Bottom-up equipment shipment tallies triangulated against top-down capital expenditure surveys across automotive and aerospace manufacturing.
Scenario-bracketing around regulatory enforcement intensity and EV powertrain adoption curves shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology, end-user industry, application workflow position, and regional manufacturing cluster regulatory framework. CAGRs derived from equipment replacement cycle compression analysis and consumables attach rate trajectories. Forecast inputs incorporated OSHA crystalline silica exposure limit implementation timelines and REACH Annex XVII chromium trioxide restriction compliance costs.
Practitioners should monitor MEE enforcement intensity in Jiangsu and Zhejiang, NADCAP accreditation queue lengths, and abrasive media freight disruption indices for early signals. Forecasts reflect assumptions on EV drivetrain housing production ramp schedules and provincial environmental mandate adherence rates. Material shifts in laser surface texturing cost-performance ratios or REACH regulatory scope expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Resistance Spot Welding Machines Market
Industrial Equipment
Mounted Bearing Market
Industrial Equipment
Ceramic Roller Bearings Market
Industrial Equipment
COG Bonder Market
Industrial Equipment
Linear Shaft Motor Market
Industrial Equipment
Machine Mounts Market
Industrial Equipment
North America Industrial Embedded Systems Market
Industrial Equipment
Latin America Explosion-Proof Equipment Market
Industrial Equipment
Air Preparation Equipment (FRL) Market
Industrial Equipment
PCB Punching Machine Market
Industrial Equipment
Diaphragm Coupling Market
Industrial Equipment
Vibration Isolation Tables Market
Industrial Equipment
Global Ultrasonic Cleaning Market
Industrial Equipment
Vertical Centrifugal Separator Market
Industrial Equipment
Laser Marking Machine Market
Industrial Equipment
Global Industrial Weighing Machines Market