
 LED Driver IC Market | 2026-2036
LED Driver IC Market Size, Share, and Industry Trends Forecast 2026-2036
LED Driver IC Market Outlook
Digital dimming architecture is reshaping how LED driver ICs integrate with smart building ecosystems and connected automotive platforms. Infineon Technologies AG leverages its power semiconductor heritage to dominate high-voltage automotive driver segments. Texas Instruments Incorporated sustains broad catalog coverage across industrial and commercial lighting applications. Monolithic Power Systems specializes in compact buck driver solutions for space-constrained consumer electronics backlighting.
An LED driver IC is a dedicated power management integrated circuit that regulates current flow to light-emitting diodes through switching, linear, or hybrid topologies, typically operating across input voltages from 85V AC to 480V AC and output currents from milliamps to several amps to ensure consistent luminous flux and color stability. Switching LED drivers occupy the dominant value share due to superior efficiency in high-power commercial and industrial installations, while digital dimmable variants represent the fastest-expanding technology segment as building automation systems mandate protocol-compatible drivers. Automotive lighting applications command premium margin pools because AEC-Q100 qualification requirements and functional safety standards create substantial barriers to supplier entry.
The EU Ecodesign Directive and CE marking requirements enforce minimum efficacy thresholds and standby power limits for lighting products sold across member states, while China's GB standards and NMPA-equivalent quality certifications shape product specifications for components manufactured in Shenzhen and Dongguan supply clusters. The US Department of Energy maintains voluntary ENERGY STAR specifications that influence procurement decisions among North American commercial retrofit contractors. Stakeholders must monitor evolving interoperability standards between proprietary wireless protocols and emerging Matter-compatible driver platforms to preserve design win trajectories across residential and commercial channels.
Market Dynamics
Digital dimming architecture is compressing design cycles as automotive OEMs and smart building integrators demand protocol-native drivers that eliminate external microcontroller overhead.
Growth Catalysts
- Automotive solid-state lighting mandates:Headlamp electrification in premium and mass-market vehicle segments is accelerating procurement of AEC-Q100 qualified drivers with integrated thermal foldback.
- China's GB 30255 efficacy standards:Tiered efficiency requirements for LED luminaires manufactured in Shenzhen and Dongguan clusters are forcing component upgrades across domestic supply chains.
- Matter protocol convergence:Thread and Zigbee interoperability specifications are unifying previously fragmented residential smart lighting control stacks.
Market Restraints
- Silicon carbide substrate costs:Wide-bandgap material premiums constrain adoption in cost-sensitive consumer backlighting segments.
- East Asian foundry concentration:Frontend fabrication for high-voltage BCD processes clusters in Taiwan and South Korea, exposing supply continuity risks.
- EU Ecodesign standby power limits:Sub-500mW requirements for connected drivers impose additional auxiliary supply complexity.
Strategic Opportunities
- India BIS certification alignment:Domestic manufacturing incentives under the PLI scheme create localized driver assembly opportunities for street and industrial luminaires.
- Horticultural SSL expansion:Tunable white and multi-channel drivers for vertical farming installations represent an emerging high-margin application vertical.
- Digital twin integration:Predictive maintenance telemetry embedded in commercial driver firmware enables recurring software revenue streams.
Industry Challenges
- EMC pre-compliance testing:Conducted and radiated emissions validation for switching topologies extends new product introduction timelines.
- Legacy DALI-1 infrastructure:Backward compatibility requirements complicate firmware architectures for next-generation DALI-2 and wireless-hybrid deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LED Driver IC Market |
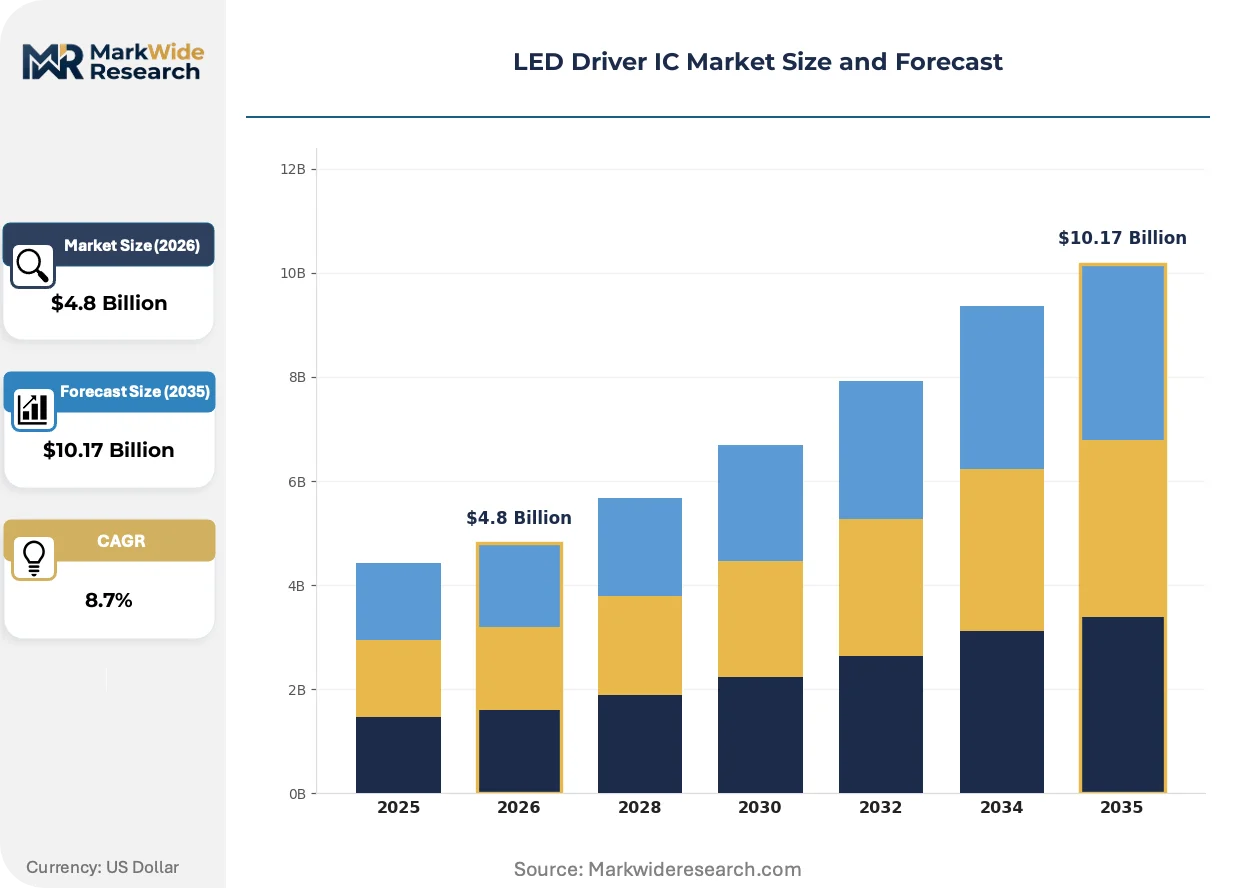
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear LED Drivers, Switching LED Drivers, Constant Current LED Drivers, Buck LED Drivers Technology: Analog, Digital, Dimmable, Non-Dimmable End User: Residential, Commercial, Automotive, Industrial Application: Lighting Fixtures, Automotive Lighting, Backlighting, Display Lighting |
| Companies Covered | Infineon Technologies AG, Diodes Incorporated, Texas Instruments Incorporated, Monolithic Power Systems, Renesas Electronics Corporation, NXP Semiconductors, ON Semiconductor, Analog Devices, STMicroelectronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LED Driver IC Market Strategic Shifts
Power management architectures are converging toward single-chip solutions that merge driver, controller, and communication PHY to reduce BOM count and PCB footprint.
Resonant half-bridge topologies with integrated gallium nitride switches are hybridizing efficiency and density benchmarks previously split between discrete and modular approaches. Data center and high-bay industrial retrofits are adopting these solutions at accelerating rates. The technology is hybridizing the traditional boundary between consumer-grade buck drivers and industrial-grade resonant modules.
The EU Ecodesign Directive's 2023 recast tightens minimum efficacy thresholds and introduces repairability scoring for luminaire-integrated drivers. Component suppliers must now design for field-replaceable driver modules rather than sealed luminaire assemblies. Commercial retrofit contractors across Germany, France, and Italy are prioritizing driver platforms with documented mean-time-to-repair specifications.
Building automation procurement teams are consolidating vendor relationships around platform suppliers offering unified software stacks across indoor, outdoor, and emergency lighting applications. Distributor technical support and inventory positioning are replacing price-only competition in specification-driven segments. This consolidation is most visible in North American commercial new construction and deep energy retrofit channels.
LED Driver IC Market Segmentation
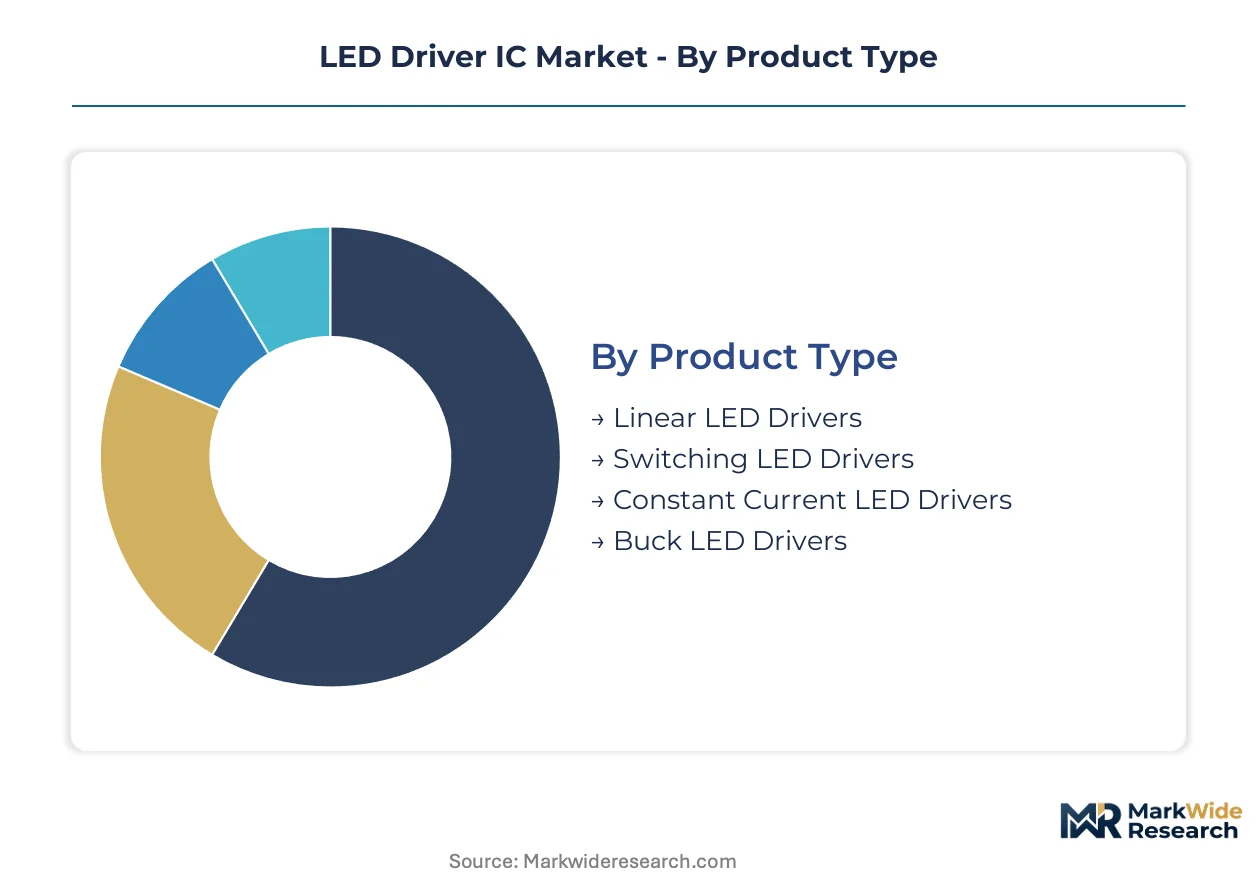
LED driver IC segmentation reveals how power management architectures align with distinct thermal, efficiency, and protocol requirements across automotive, commercial, and consumer installations. Component suppliers configure die geometries and package thermal resistance around these use-case boundaries to optimize bill-of-material economics.
Product Type:
The use-case spectrum spans from low-noise linear regulation in precision instrumentation to high-efficiency switching topologies in high-bay industrial retrofits.
- Switching LED Drivers:Buck, boost, and buck-boost topologies operate at frequencies between 100kHz and 2MHz to achieve efficiency above 90% in 100W+ commercial luminaires. Demand concentrates in German industrial retrofit channels where EU Ecodesign efficacy mandates force upgrades from magnetic ballast legacy systems.
- Linear LED Drivers:These devices regulate current through pass-element voltage drop, eliminating electromagnetic interference concerns in medical imaging and laboratory environments. Cost-sensitive consumer backlighting in Shenzhen manufacturing clusters limits penetration outside noise-critical applications.
- Constant Current LED Drivers:Feedback-loop architectures maintain stable luminous flux across LED junction temperature variations. Automotive headlamp modules in Stuttgart and Wolfsburg production lines specify tight current tolerance for color consistency.
- Buck LED Drivers:Step-down conversion enables direct AC-DC integration in space-constrained bulb replacements. Dongguan assembly houses favor these for cost-optimized residential retrofit shipments to Southeast Asian markets.
Established volume favors switching topologies; emerging adoption favors linear solutions in EMI-sensitive medical and aerospace environments.
Technology:
Cost tier stratification separates premium digital platforms from commodity analog implementations.
- Digital:Microcontroller-integrated drivers execute protocol translation for DALI-2, Zigbee, and Thread networks without external host processors. Smart building deployments in Singapore and Dubai specify these for centralized energy management integration.
- Dimmable:Phase-cut, 0-10V, and wireless-dimming interfaces enable lumen output modulation for circadian lighting and daylight harvesting. Hospitality retrofits across Paris and Milan mandate compatibility with existing TRIAC infrastructure.
- Analog:Discrete comparator and reference circuits deliver lowest unit cost in high-volume consumer electronics. Shenzhen tablet and monitor backlighting contracts specify analog drivers for bill-of-material compression.
- Non-Dimmable:Fixed-output designs serve cost-optimized street lighting and emergency exit signage where lumen modulation provides no operational value. Indian municipal procurement under EESL tenders emphasizes these for lowest first-cost compliance.
Mature cost curves anchor analog volumes; protocol convergence is expanding digital fastest.
End User:
Application margins concentrate in automotive qualification while volume concentrates in commercial construction cycles.
- Automotive:AEC-Q100 Grade 1 qualification requirements and ISO 26262 functional safety compliance create 40-60% gross margin premiums over consumer equivalents. Munich and Ingolstadt OEM assembly lines specify integrated thermal foldback for LED headlamp reliability.
- Commercial:New construction and deep energy retrofit projects across New York, Chicago, and Toronto specify networked drivers with centralized commissioning capabilities. US General Services Administration procurement templates influence specification defaults.
- Industrial:High-bay and hazardous-location luminaires demand wide-input-range drivers surviving voltage sags and swells in factory electrical environments. Houston petrochemical facilities specify these for explosion-proof fixture integration.
- Residential:Retrofit bulb and downlight replacements prioritize cost-per-lumen metrics over advanced features. Amazon and Home Depot private-label sourcing from Ningbo and Zhongshan factories dominates this channel.
Automotive commands margin concentration; commercial delivers volume scale.
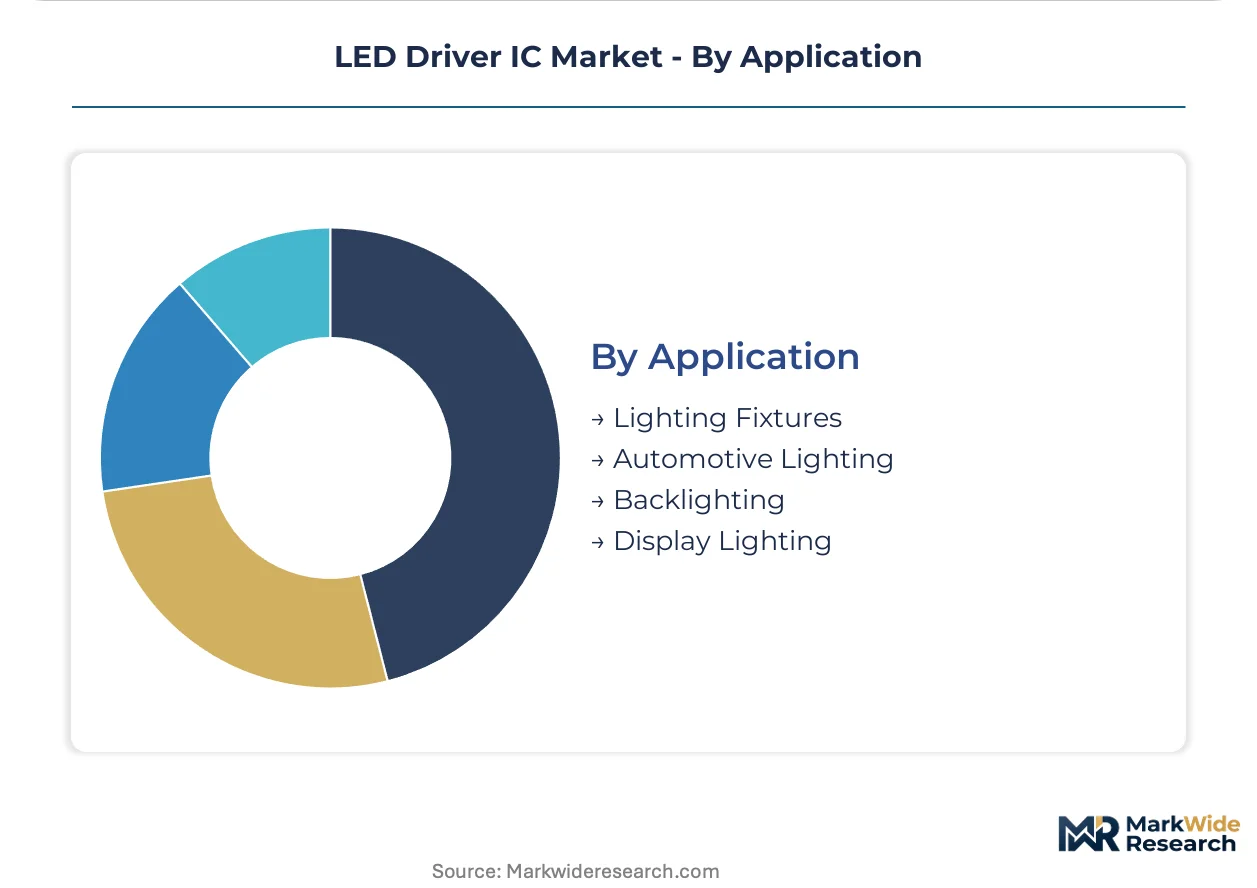
Application:
Customer type differentiation separates specification-driven fixture OEMs from consumer electronics integrators.
- Lighting Fixtures:Driver-integrated luminaire designs require thermal co-optimization between LED arrays and power electronics. Signify and Acuity Brands specification teams in Eindhoven and Atlanta drive platform consolidation around modular driver cartridges.
- Automotive Lighting:Front and rear lamp modules integrate drivers within sealed housings demanding -40°C to 125°C operational ranges. Toyota and Hyundai tier-one suppliers in Aichi and Gyeonggi provinces specify these for platform-standard designs.
- Backlighting:Edge-lit and direct-lit LCD panels in televisions, monitors, and notebooks demand multi-channel current matching for uniform luminance. Seoul and Taipei display panel fabs source these in 50-million-unit annual volumes.
- Display Lighting:Narrow-pixel-pitch LED video walls and transparent display installations require fine-pitch driver integration. Las Vegas entertainment venue installations and London retail flagship stores specify these for architectural media surfaces.
Fixture integration anchors replacement-cycle volumes; display lighting is climbing fastest on digital signage expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports LED driver ICs and luminaire components to Germany, the United States, and Southeast Asian assembly hubs, establishing Shenzhen-to-Stuttgart and Dongguan-to-Detroit corridors as dominant trade arteries.
China
Shenzhen and Dongguan manufacturing clusters supply switching drivers for global luminaire brands. GB 30255 efficacy standards mandate tiered efficiency upgrades across domestic LED lighting production. NMPA-equivalent quality certifications shape export specifications for components bound for European and North American markets.
Germany
Stuttgart and Wolfsburg automotive assembly lines specify AEC-Q100 qualified drivers for LED headlamp modules. EU Ecodesign Directive recasts enforce minimum efficacy thresholds and repairability scoring for luminaire-integrated drivers. Industrial retrofit channels in Bavaria and North Rhine-Westphalia concentrate demand for high-efficiency switching topologies replacing magnetic ballast legacy systems.
United States
New York, Chicago, and Toronto commercial construction cycles drive specification-driven procurement of networked drivers with centralized commissioning. ENERGY STAR specifications from the Department of Energy influence retrofit contractor decisions across North American channels. General Services Administration procurement templates set defaults for federal building lighting upgrades.
Japan
Tokyo and Osaka metropolitan corridors host precision driver design for medical imaging and laboratory applications requiring low-noise linear regulation. METI industrial policy supports domestic semiconductor manufacturing for high-reliability automotive and industrial segments. Aichi prefecture tier-one suppliers integrate drivers into Toyota and Honda platform-standard headlamp designs.
India
Maharashtra and Gujarat industrial zones generate demand for street lighting and emergency exit signage drivers under EESL municipal tenders. BIS certification alignment and PLI scheme incentives create localized assembly opportunities for domestic luminaire manufacturers. Telangana and Karnataka emerging electronics manufacturing clusters attract driver IC packaging investments.
LED Driver IC Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered market layers. The vendor base organizes around three archetypes: diversified semiconductor conglomerates with broad power management portfolios, automotive-qualified specialists leveraging AEC-Q100 certification barriers, and compact-solution focused providers serving consumer electronics backlighting. Dominant competitive moves include strategic partnerships for Matter protocol integration and geographic expansion into India PLI-subsidized manufacturing zones.
Among diversified semiconductor conglomerates, Infineon Technologies AG and Texas Instruments Incorporated occupy positions spanning industrial, automotive, and commercial lighting verticals. STMicroelectronics and NXP Semiconductors exemplify European-based fabricators with automotive heritage extending into LED driver qualification. Monolithic Power Systems represents the compact-solution archetype, anchoring high-volume consumer electronics backlighting segments with space-optimized buck driver architectures.
| Leading Market Players |
|---|
| Infineon Technologies AG |
| Diodes Incorporated |
| Texas Instruments Incorporated |
| Monolithic Power Systems |
| Renesas Electronics Corporation |
| NXP Semiconductors |
| ON Semiconductor |
| Analog Devices |
| STMicroelectronics |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Taiwan's 8-inch BCD foundry nodes is compressing wafer quotes and transferring margin pressure downstream to packaged driver IC suppliers, forcing tier-one vendors to absorb cost erosion or cede socket share to aggressive second-source bidders.
Pricing Analysis
Silicon-based buck driver pricing gaps against emerging GaN resonant alternatives by roughly 30-40% at equivalent power ratings, with analog dimmable SKUs commanding modest premiums over non-dimmable baselines. Pricing stratifies across AEC-Q100 automotive, industrial-grade, and consumer backlighting tiers, with certification grade and volume scale as primary differentiation drivers. Cost compression in consumer buck segments is intensifying because Dongguan assembly houses are consolidating procurement around single-source platform suppliers. Municipal street lighting tenders under India's EESL specifications exhibit highest price sensitivity, while Stuttgart OEM headlamp programs tolerate 60% premiums for ISO 26262-compliant thermal foldback features.
Supply Chain Analysis
Extended payment terms stretching to 90-120 days from German automotive tier-ones are squeezing working capital for Taiwanese foundry services and Shenzhen packaging houses. Frontend fabrication concentrates in Taiwan and South Korea, with silicon wafers, copper leadframes, and epoxy mold compounds as critical input dependencies. Single-source vulnerability around TSMC's BCD process capacity exposes supply continuity risks for high-voltage automotive driver qualification programs. Distribution runs through Arrow and Avnet for North American specification-driven commercial retrofits, while direct OEM relationships dominate automotive and consumer electronics backlighting channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from integrated gallium nitride power stages that threaten to displace silicon-based driver architectures in high-efficiency commercial and industrial retrofits.
For Market Incumbents: Build certification moats around AEC-Q100 Grade 1 and ISO 26262 ASIL-B qualifications that emerging GaN specialists cannot replicate without 24-36 month qualification cycles. Defensive moves center on captive supply of 8-inch BCD capacity through foundry partnerships in Taiwan, plus backward integration into gallium nitride epitaxy to preserve technology optionality against pure-play GaN entrants. For New Entrants and Emerging Players: Build out India PLI-subsidized assembly capacity for street lighting and industrial luminaire drivers where BIS certification alignment creates localized procurement preferences. The most penetrable white space sits in horticultural SSL multi-channel drivers for vertical farming installations in Singapore and Dubai, with go-to-market leverage through agricultural technology distributors already serving controlled-environment agriculture operators. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because automotive qualification barriers and Matter protocol convergence will compress the vendor base from fragmented analog suppliers toward platform-scale digital driver providers. Acquisition targets should exhibit DALI-2 and Thread software stacks with documented design wins in North American GSA procurement channels. The signal to watch is automotive OEM platform standardization announcements from Munich and Ingolstadt that designate approved driver supplier lists.| Strategic Initiative | Industry Significance |
|---|---|
| Matter Protocol Certification | Thread and Zigbee interoperability unlocks smart building specification wins across Singapore and Dubai deployments. |
| AEC-Q100 Grade 1 Qualification | Automotive thermal foldback features command 40-60% gross margin premiums over consumer equivalents. |
| India PLI Manufacturing Footprint | BIS-aligned domestic assembly captures EESL municipal tender volumes in Maharashtra and Gujarat. |
| GaN Resonant Topology Migration | Integrated gallium nitride switches hybridize efficiency benchmarks previously split between discrete and modular approaches. |
| Digital Twin Firmware Integration | Predictive maintenance telemetry embedded in commercial drivers enables recurring software revenue streams. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across the LED driver IC value chain, including automotive platform engineers at Stuttgart and Wolfsburg OEMs, commercial lighting specification teams at Acuity Brands and Signify, procurement managers at Dongguan luminaire assembly houses, and distribution channel partners at Arrow Electronics. Secondary validation drew from SEC 10-K filings of listed semiconductor suppliers, EU Ecodesign Directive recast documentation, China's GB 30255 efficacy standard publications, and ENERGY STAR specification archives. Bottom-up unit demand estimates by application and top-down semiconductor industry revenue triangulation were cross-referenced for convergence.
Calibration against historical shipment data from Taiwan's BCD foundry utilization reports and German automotive production databases anchored volume projections. Segmentation dimensions modeled span product topology, dimming technology, end-user vertical, and regional regulatory cluster, with CAGRs derived from slope analysis of technology substitution curves and efficiency mandate compliance deadlines. Industry-specific forecast inputs include Matter protocol adoption trajectories in North American commercial new construction and AEC-Q100 qualification pipeline visibility from tier-one automotive suppliers.
Stress conditions across Taiwan foundry capacity utilization, EU Ecodesign standby power limit enforcement, and silicon carbide substrate cost trajectories were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions around GB standards compliance timelines and PLI scheme disbursement continuity. Macroeconomic contraction in commercial construction, regulatory delay in Ecodesign recast implementation, or breakthrough GaN cost parity ahead of projected curves would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Programmable ASIC Market
IC (Integrated Circuits)
Communication Special Purpose Logic IC Market
IC (Integrated Circuits)
Global Interface IC Market
IC (Integrated Circuits)
Display Driver IC Market
IC (Integrated Circuits)
Display LSI IC Market
IC (Integrated Circuits)
RFID Reader IC Market
IC (Integrated Circuits)
Global Power Management Integrated Circuit (PMIC) Market
IC (Integrated Circuits)
Comparator IC Market
IC (Integrated Circuits)
Readout Integrated Circuits (ROIC) Market
IC (Integrated Circuits)
South Korea Analog Integrated Circuits Market
IC (Integrated Circuits)
Application Specific Integrated Circuit Market
IC (Integrated Circuits)
Analog and Mixed Signal IP Market
IC (Integrated Circuits)
United States Analog Integrated Circuits Market
IC (Integrated Circuits)
Automotive Integrated Circuit (Ics) Market
IC (Integrated Circuits)
United States Logic Integrated Circuits Market
IC (Integrated Circuits)
Taiwan Integrated Circuits Market