
 Club Store Packaging Tray Market | 2026-2036
Club Store Packaging Tray Market Size, Share, and Industry Trends Forecast 2026-2036
Club Store Packaging Tray Market Analytics
Extended producer responsibility mandates in California and Oregon is expanding recycled content requirements for club store packaging trays. Amcor leverages its global manufacturing footprint to supply certified recyclable trays across multiple warehouse club chains. Smurfit Kappa sustains competitive positioning through integrated paperboard operations that reduce material cost volatility. Huhtamaki anchors its presence with molded fiber technology optimized for bulk produce displays at major membership retailers.
Club store packaging trays are structural containers engineered from corrugated paperboard, thermoformed PET, or expanded polystyrene, designed to withstand pallet-stacking loads of 1,500 pounds while displaying 20-50 pound product volumes in warehouse environments. Their primary purpose centers on unitizing bulk consumer goods for forklift handling and fork-truck accessibility in high-bay retail formats. Plastic trays dominate current procurement volumes due to moisture resistance and reusability in closed-loop distribution systems, while cardboard segments capture expanding share as compostable coatings replace polyethylene barriers. Custom printed customization levels command premium positioning as Costco and Sam's Club deploy tray surfaces as advertising real estate for private-label merchandise.
The US FDA regulates food-contact substances under 21 CFR, while EPA guidelines govern recycled content claims, and state-level packaging extended producer responsibility laws in California, Oregon, and Maine mandate minimum post-consumer recycled thresholds. These frameworks compel tray manufacturers to certify migration limits and recycled content percentages before qualifying for club store vendor programs. Stakeholders must monitor evolving state patchworks of packaging legislation and assess whether centralized or regional production configurations better absorb compliance cost fragmentation.
Market Dynamics
Warehouse club consolidation around private-label merchandise is converting packaging trays into branded advertising surfaces, forcing suppliers to integrate high-resolution printing capabilities that meet Costco and Sam's Club visual standards.
Growth Catalysts
- State Extended Producer Responsibility Laws:California and Oregon mandates for post-consumer recycled content in food-contact packaging are accelerating tray specification changes across North American suppliers.
- Bulk Meat Department Expansion:Warehouse retailers are expanding refrigerated case footage dedicated to value-pack protein, multiplying tray consumption per store location.
- Closed-Loop Reusability Systems:Plastic tray pooling programs between distributors and club stores are reducing per-use costs and locking in material specifications.
Market Restraints
- Resin Price Volatility:PET and expanded polystyrene feedstock costs fluctuate with crude oil indices, compressing manufacturer margins on fixed-price annual contracts.
- Compostable Coating Performance Gaps:Polyethylene barrier replacements in paperboard trays exhibit moisture failure rates above acceptable thresholds for wet produce applications.
- Single-Source Pallet-Stack Certification:Club stores require proprietary load-testing protocols that create vendor lock-in and extend supplier qualification timelines.
Strategic Opportunities
- Mexico Warehouse Club Penetration:Sam's Club and Costco are accelerating store openings in Mexican metropolitan markets, creating demand for localized tray production.
- RFID-Enabled Inventory Tracking:Embedding wireless identification tags in tray structures enables real-time stock monitoring for high-velocity bulk SKUs.
- Molded Fiber Technology Convergence:Combining agricultural waste fibers with advanced forming presses reduces material costs while satisfying compostability mandates.
Industry Challenges
- Migration Testing Expertise Shortage:FDA 21 CFR food-contact substance certification requires specialized analytical chemists that tray manufacturers struggle to recruit.
- Legacy Equipment Retrofit Costs:Converting thermoforming lines to handle recycled PET feedstock demands capital outlays that mid-tier suppliers cannot finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Club Store Packaging Tray Market |
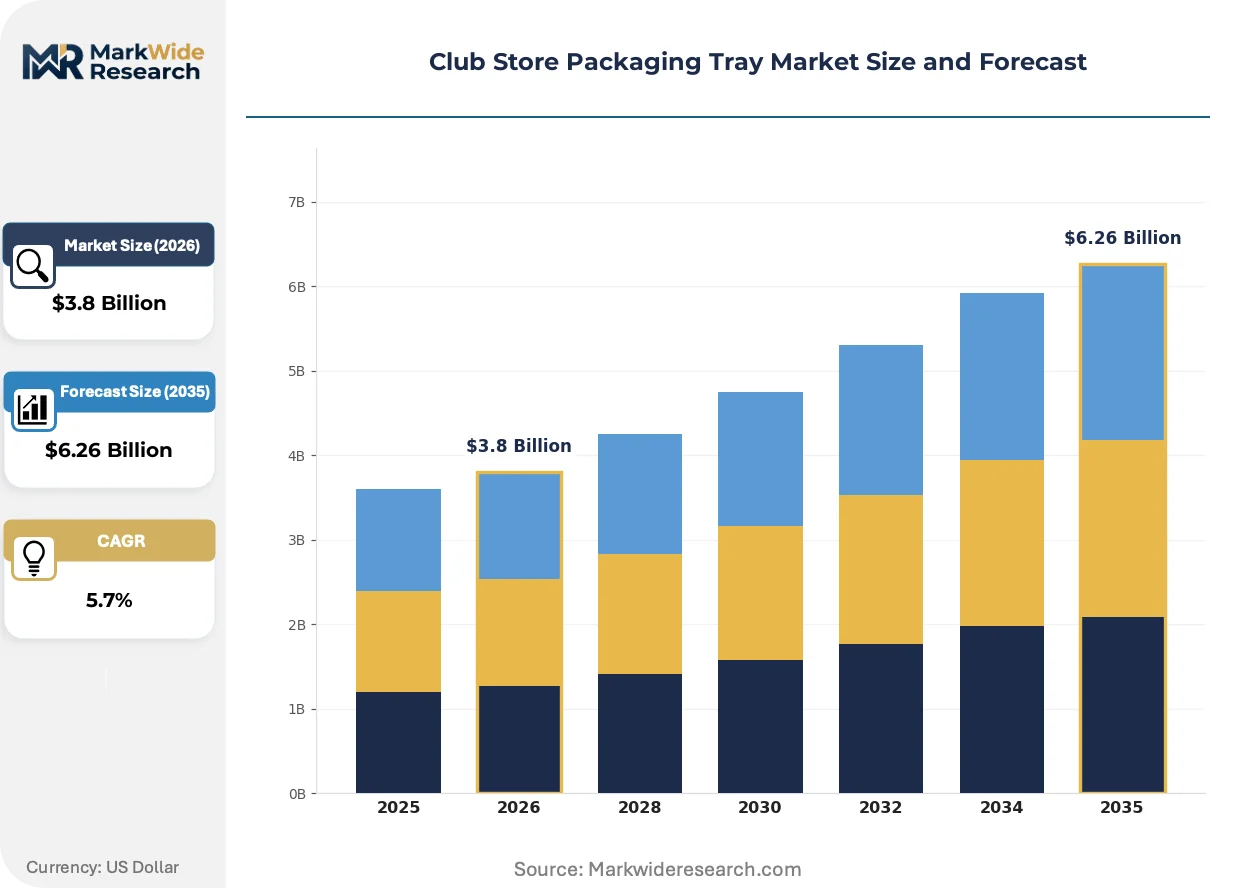
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Cardboard, Plastic, Blister, Display Product Type: Food, Beverage, Cleaning Supplies, Personal Care End User: Retailers, Wholesalers, Distributors, E-commerce Customization Level: Standard, Custom Printed, Eco-friendly, Multi-pack |
| Companies Covered | Amcor, Smurfit Kappa, Huhtamaki, Winpak Ltd., DS Smith, Berry Global, Sonoco Products Company, ProAmpac, Sealed Air, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Club Store Packaging Tray Market Evolving Landscape
Material science breakthroughs and regulatory compliance automation are redefining competitive advantage in club store packaging trays. Suppliers now compete on certification speed and sustainable material credentials rather than unit cost alone.
Barrier-coated molded fiber is overtaking conventional polyethylene-lined paperboard in produce applications. Costco's produce buyers have adopted these trays for organic vegetable displays across Pacific Northwest locations. The shift is overtaking incumbent suppliers who lack thermoforming alternatives to plastic, compressing their addressable market in wet-environment SKUs.
California's extended producer responsibility framework is mandating minimum post-consumer recycled thresholds for food-contact packaging sold through warehouse clubs. Tray manufacturers must certify compliance through third-party auditors before qualifying for vendor programs. The regulation most affects suppliers serving the Los Angeles and San Francisco metropolitan store clusters, where enforcement begins earliest.
Buyer concentration around two dominant membership retailers has compressed switching flexibility for tray suppliers. Sam's Club and Costco now specify proprietary color-matching systems and print registration tolerances that lock in qualified vendors. This consolidation is most visible in the Midwest distribution corridor, where regional tray producers have exited the club store segment entirely rather than absorb compliance costs.
Club Store Packaging Tray Market Segmentation
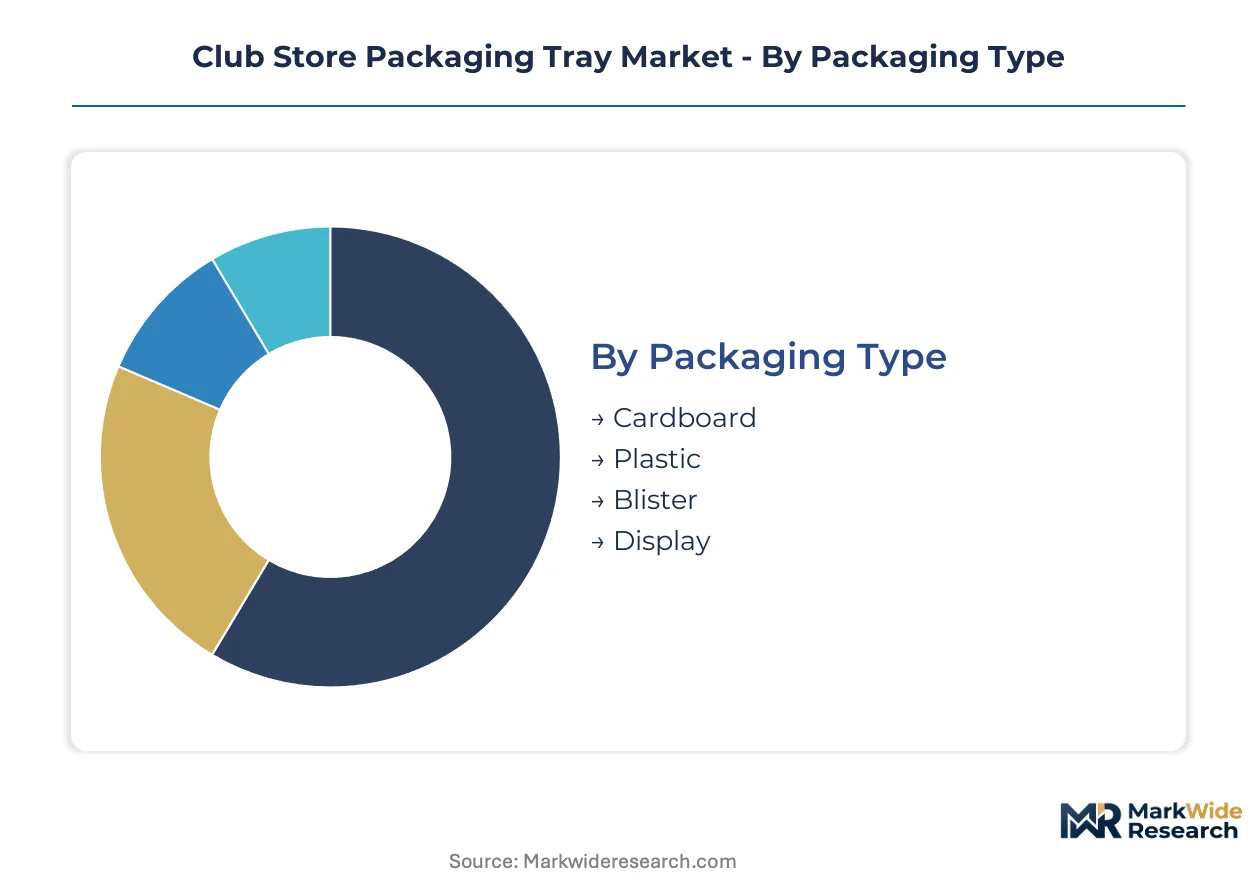
Club store packaging tray procurement decisions pivot on load-bearing requirements, moisture exposure, and print surface area for private-label branding. Segmentation reveals how material science and retail format specifications create distinct competitive arenas for suppliers.
Packaging Type:
Cost tier determines supplier qualification pathways, with capital-intensive plastic operations separating from paperboard converters.
- Plastic:Thermoformed PET and expanded polystyrene structures withstand 1,500-pound pallet stacks and repeated washing in closed-loop pooling systems. Costco and Sam's Club refrigerated meat departments specify these trays for moisture resistance across Midwest and Pacific Northwest distribution corridors.
- Cardboard:Corrugated paperboard with compostable barrier coatings serves dry produce and ambient grocery SKUs where single-use disposal aligns with California extended producer responsibility mandates. Oregon and Maine store clusters are accelerating procurement of these trays as recycled content thresholds tighten.
- Blister:Thermoformed clear films bonded to printed backing cards display small electronics and personal care items in warehouse club impulse zones.
- Display:Shelf-ready corrugated structures integrate stacking strength with high-graphics printing for seasonal merchandise promotions.
Plastic leads on scale; cardboard leads on momentum.
Product Type:
Application environment dictates moisture barriers, with wet-case protein requirements diverging sharply from ambient dry goods.
- Food:Bulk meat and produce departments consume the highest tray volumes per square foot of retail space. FDA 21 CFR food-contact certification is mandatory for all food-facing surfaces, with migration testing for recycled PET feedstock creating vendor qualification bottlenecks.
- Beverage:Multi-pack can and bottle trays require specialized corner posts and compression strength for liquid weight distribution.
- Cleaning Supplies:Chemical resistance specifications exclude certain recycled plastics from bleach and ammonia product lines.
- Personal Care:Premium cosmetic displays command custom printed surfaces with brand-matched color systems.
Food leads on scale; beverage leads on momentum.
End User:
Customer type shapes order cadence and specification stability, with direct retail relationships offering volume predictability.
- Retailers:Costco and Sam's Club dominate procurement volumes, setting proprietary load-testing protocols that lock in qualified suppliers for multi-year contracts. Their private-label merchandise expansion is converting tray surfaces into advertising real estate with exacting print registration standards.
- Wholesalers:Intermediate distributors serving independent grocers and convenience stores purchase standardized trays without custom color matching.
- Distributors:Foodservice redistribution networks specify nestable designs for efficient backhaul logistics.
- E-commerce:Direct-to-consumer bulk fulfillment requires modified dimensions for parcel carrier dimensional weight optimization.
Retailers lead on scale; e-commerce leads on momentum.
Customization Level:
Margin structure stratifies across specification complexity, with visual branding requirements commanding premium positioning.
- Standard:Unprinted brown or white corrugated trays serve commodity produce with minimal branding requirements.
- Custom Printed:High-resolution flexographic and lithographic lamination enables warehouse clubs to deploy tray surfaces as private-label advertising space. Costco's Kirkland Signature and Sam's Club Member's Mark specifications dominate this tier.
- Eco-friendly:Molded fiber and agricultural waste composites satisfy compostability mandates in California, Oregon, and Maine metropolitan enforcement zones.
- Multi-pack:Partitioned structures unitize variety assortments for seasonal gift sets and trial-size promotions.
Custom printed leads on scale; eco-friendly leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Packaging engineers and food safety specialists cluster in metropolitan manufacturing corridors where warehouse club headquarters anchor procurement decisions. FDA migration testing expertise concentrates in Chicago, Minneapolis, and Seattle metro areas.
United States
Costco's Issaquah headquarters and Sam's Club's Bentonville operations drive tray specification standards across North American suppliers. California's extended producer responsibility law mandates minimum post-consumer recycled thresholds for food-contact packaging. The Los Angeles and San Francisco metropolitan store clusters enforce compliance earliest, accelerating vendor qualification bottlenecks.
Canada
Costco's Canadian expansion and Walmart Canada's warehouse format growth multiply tray consumption per store location. Health Canada regulates food-contact materials under the Food and Drugs Act with migration limits paralleling FDA 21 CFR standards. The Greater Toronto Area hosts thermoforming operations supplying cross-border club store distribution networks.
Mexico
Sam's Club and Costco are accelerating store openings in Mexico City, Monterrey, and Guadalajara metropolitan markets. Mexico's national food safety regulator COFEPRIS governs food-contact substance approvals with certification timelines shorter than FDA equivalents. The Bajío Region's automotive manufacturing spillover has built thermoforming equipment maintenance capabilities serving packaging converters.
Germany
European warehouse club formats remain underdeveloped, but German packaging machinery manufacturers supply thermoforming lines to North American tray producers. The EU REACH regulation governs chemical substance registration for exported packaging materials. The Stuttgart industrial corridor hosts forming press manufacturers whose equipment handles recycled PET feedstock.
China
Domestic warehouse club penetration by Costco and Sam's Club joint ventures creates demand for localized tray production. China's SAMR regulates food-contact materials under GB standards with testing protocols distinct from FDA methodologies. The Yangtze River Delta thermoforming cluster supplies barrier-coated molded fiber prototypes for Pacific Northwest produce tray trials.
Club Store Packaging Tray Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across material technology boundaries in the club store packaging tray market. Plastic thermoforming operations require million-dollar tooling investments that separate tier-one suppliers from paperboard converters. Three strategic archetypes dominate: integrated multinational packaging conglomerates, regional specialty converters with proprietary coating formulations, and agricultural fiber processors leveraging waste stream feedstocks. Capacity expansion and certification speed differentiation represent the dominant competitive moves as vendors race to qualify under California's recycled content mandates.
Among integrated multinational suppliers, Amcor leverages its global manufacturing footprint while Smurfit Kappa sustains competitive positioning through integrated paperboard operations. Huhtamaki anchors its presence with molded fiber technology. These three exemplify the capital intensity and certification expertise required to serve warehouse club procurement programs with their proprietary load-testing protocols and visual branding standards.
| Leading Market Players |
|---|
| Amcor |
| Smurfit Kappa |
| Huhtamaki |
| Winpak Ltd. |
| DS Smith |
| Berry Global |
| Sonoco Products Company |
| ProAmpac |
| Sealed Air |
| Others |
Value Network & Pricing Analysis
Thermoforming equipment operators in the Chicago and Minneapolis metropolitan corridors command wage premiums that compress margins for mid-tier tray manufacturers, widening spreads between premium certified suppliers and commodity converters serving secondary wholesale channels.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement between Costco, Sam's Club, and qualified tray vendors, with price differentiation anchored in FDA 21 CFR certification tier and closed-loop reusability system participation. Premium tiers capture vendors with proprietary load-testing protocols and high-resolution print capabilities, while economy tiers serve independent wholesalers with standardized brown corrugated. Cost compression in the recycled PET segment intensifies as resin feedstock volatility outpaces contract escalation clauses. Small regional converters exhibit highest price sensitivity, lacking volume scale to absorb specification-change costs.
Supply Chain Analysis
California's extended producer responsibility mandates are reshaping sourcing patterns, compelling tray manufacturers to certify post-consumer recycled content thresholds through third-party auditors before qualifying for vendor programs. Raw material supply concentrates in the United States, Canada, and Mexico, with thermoforming resin production anchored in Gulf Coast petrochemical corridors and molded fiber operations clustering in Pacific Northwest agricultural waste processing zones. Feedstock dependence on crude oil-indexed PET and expanded polystyrene creates margin vulnerability when resin costs spike. Distribution runs through warehouse club regional distribution centers, with qualified suppliers maintaining dedicated production lines for proprietary color-matching systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The club store packaging tray market functions as a stable compounder, with warehouse club private-label merchandise expansion converting tray surfaces into permanent advertising real estate that locks in multi-year supplier relationships.
For Market Incumbents: Hedge against agricultural fiber substitution by deepening backward integration into compostable coating formulation capabilities, while expanding thermoforming capacity in the Bajío Region to capture Sam's Club and Costco procurement growth in Mexican metropolitan markets. Migration testing expertise scarcity represents the critical bottleneck; recruit FDA 21 CFR analytical chemists before California enforcement timelines accelerate vendor qualification backlogs. For New Entrants and Emerging Players: Launch via RFID-enabled inventory tracking partnerships with warehouse club distribution networks, targeting the e-commerce bulk fulfillment segment where dimensional weight optimization requirements remain underspecified. Molded fiber technology convergence in Pacific Northwest produce applications offers the most penetrable white space, as incumbent plastic thermoformers lack agricultural waste fiber processing capabilities. For Investors and Strategic Acquirers: Packaging conglomerates with integrated paperboard operations are the most active acquirer in this space, seeking regional specialty converters with proprietary barrier coating formulations to fill capability gaps. Acquisition target archetypes include agricultural fiber processors with waste stream feedstock contracts and thermoforming shops with existing Costco or Sam's Club qualification status. Watch California extended producer responsibility enforcement expansion into Los Angeles and San Francisco metropolitan store clusters as the inflection signal for accelerated vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compostable Coating Formulation | Captures margin from barrier technology suppliers serving California EPR compliance deadlines. |
| RFID-Enabled Inventory Tracking Integration | Enables real-time stock monitoring for high-velocity bulk SKUs at Costco and Sam's Club distribution centers. |
| Capacity Expansion in Mexican Metropolitan Markets | Positions suppliers for Sam's Club and Costco store opening acceleration in Mexico City, Monterrey, and Guadalajara. |
| Migration Testing Certification Investment | Resolves FDA 21 CFR food-contact substance bottlenecks that disqualify competitors from warehouse club vendor programs. |
| Agricultural Waste Fiber Supply Agreements | Secures feedstock for molded fiber technology convergence satisfying Oregon and Maine compostability mandates. |
Research Methodology
Coverage spans the United States, Canada, Mexico, Germany, and China, with primary inputs from each market obtained through structured interviews with packaging procurement directors at warehouse club headquarters, thermoforming plant managers, FDA compliance consultants, agricultural fiber processing executives, and secondary validation against SEC 10-K filings, customs and trade data, EPA recycled content claims databases, and state-level extended producer responsibility regulatory filings. Bottom-up tray consumption estimates by store format triangulate against top-down packaging expenditure forecasts.
Rate-of-change decomposition separates volume growth from value growth across the projection horizon, with segmentation dimensions spanning packaging type, product application, end-user category, and customization level. CAGRs derive from regression analysis of historical procurement patterns correlated with warehouse club square footage expansion, private-label merchandise penetration rates, and regulatory compliance cost absorption curves. Industry-specific forecast inputs include resin price indices, recycled PET feedstock availability, and state-level EPR enforcement timelines.
Several conditions sit outside the modeled scope, including abrupt shifts in FDA migration testing protocols, breakthrough barrier coating technologies that eliminate moisture failure rates in paperboard trays, and warehouse club format consolidation beyond current Costco and Sam's Club dominance. Forecasts reflect documented assumptions about regulatory enforcement pacing and resin cost volatility. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Single Wall Jars Market
Containers
Corrugated Bin Boxes Market
Containers
Light Resistant Containers Market
Containers
Asia and Africa Food Cans Market
Containers
Global Container Monitoring Market
Containers
Collapsible Food Packaging Containers Market
Containers
Oblong Container Market
Containers
In-Mold Labelled Containers Market
Containers
Compartment Trays Market
Containers
Jug Shipper Market
Containers
ISO Ocean Containers Market
Containers
Food Grade Stainless Steel Container Market
Containers
Container Stacking Machine Market
Containers
Sanitary Cans Market
Containers
Wire Containers Market
Containers
Tottle Containers Market