
 Club Store Packaging Market | 2026-2036
Club Store Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Club Store Packaging Market Outlook
North American corrugated board producers is pivoting toward high-volume, pallet-ready formats engineered for warehouse club floor displays. WestRock leverages integrated containerboard mills to sustain cost leadership on triple-wall bulk bins. International Paper Company anchors its position through geographic dominance in the US Southeast, where it controls access to virgin and recycled fiber networks. Graphic Packaging Holding Company differentiates via coated recycled board technology optimized for club store shelf-ready cartons.
Club store packaging denotes primary and secondary containment systems designed for bulk retail environments, typically incorporating reinforced stacking strength, tear-resistant hand holes, and pallet-compatible footprints for forklift handling. Corrugated boxes dominate unit volume due to structural integrity requirements for 30-50 pound stock-keeping units, while plastic wraps in LDPE and PET gain traction in produce and chilled meat applications where moisture barrier performance governs shelf life extension. Cartons capture premium margin pools in branded consumer packaged goods, whereas blisters occupy niche positions in electronics and hardware multipacks where product visibility drives purchase conversion.
The US EPA regulates post-consumer recycled content thresholds under evolving solid waste guidelines, while the FTC Green Guides enforce environmental marketing claims on club store shelf labels. California's SB 54 mandates extended producer responsibility for single-use packaging, directly affecting PET and PVC format decisions for suppliers serving West Coast distribution centers. Stakeholders must monitor state-level packaging EPR legislation and fiber sourcing certification requirements as these rules increasingly determine market access for converters and brand owners alike.
Market Dynamics
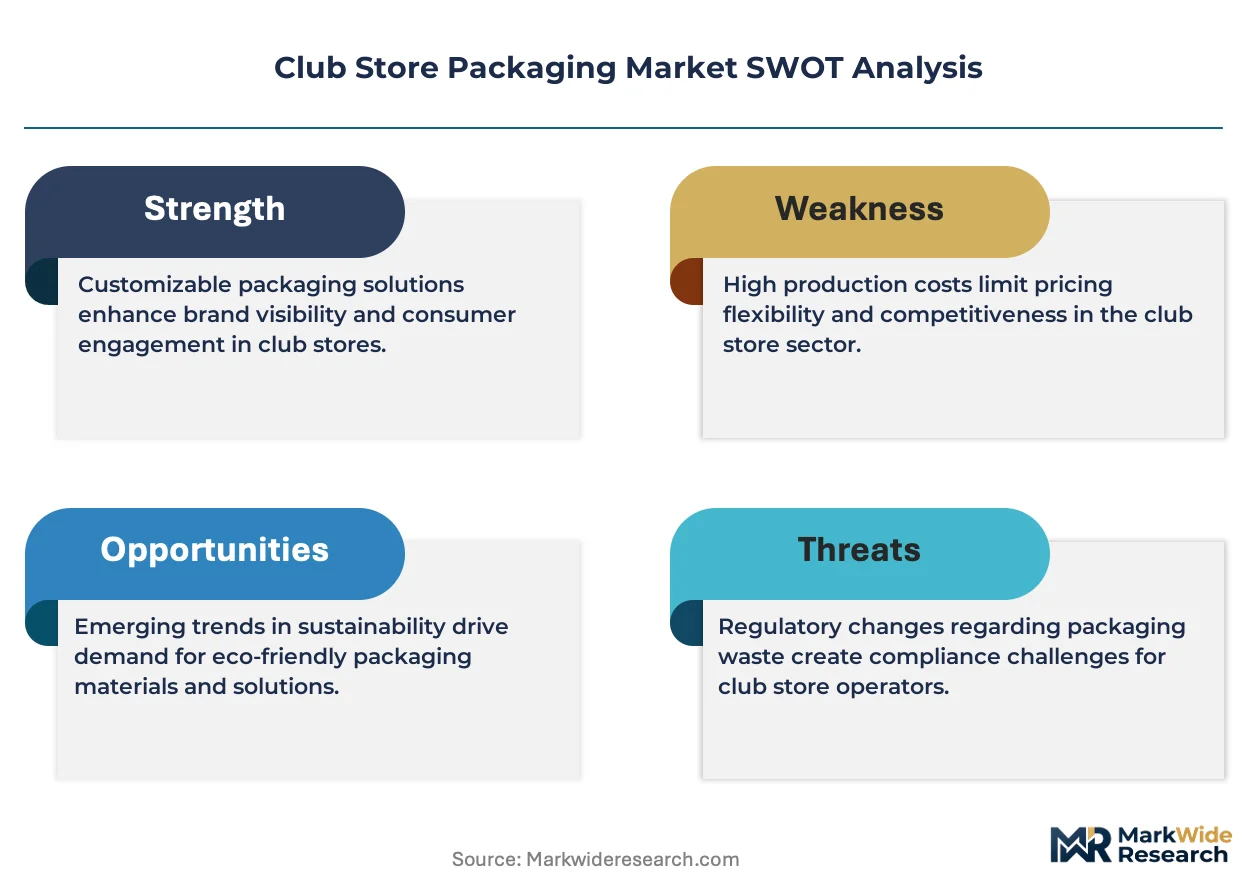
Extended producer responsibility mandates from the EPA and California's SB 54 are forcing converters to redesign substrate specifications across bulk-format packaging lines. Warehouse club retailers now require recycled-content compliance as a baseline procurement threshold.
Growth Catalysts
- California SB 54 Mandates:Extended producer responsibility rules for single-use packaging accelerate demand for fiber-based alternatives in West Coast distribution networks. Suppliers must certify recycled-content thresholds to maintain club store shelf placement.
- Fresh Grocery Expansion:Warehouse clubs are scaling refrigerated produce sections, driving moisture-barrier packaging demand for 30-50 pound stock-keeping units. LDPE and PET formats capture incremental volume in chilled meat applications.
- Pallet-Ready Formats:Triple-wall corrugated bulk bins with reinforced stacking strength reduce handling costs per unit. Club retailers specify forklift-compatible footprints that compress logistics spend.
Market Restraints
- OCC Price Volatility:Old corrugated containerboard input costs swing with municipal recycling collection rates. Converters face margin compression when post-consumer fiber supply tightens.
- Southeast Fiber Concentration:Virgin and recycled fiber networks cluster in the US Southeast, creating geographic supply risk. Hurricane disruption to pulp mills propagates through containerboard pricing.
- Multi-Material Recycling Limits:Coated recycled board with polyethylene barriers fails standard municipal sorting streams. California's SB 54 penalties apply to formats that lack viable end-of-life pathways.
Strategic Opportunities
- Mid-Atlantic Distribution Expansion:BJ's Wholesale Club operates dense store networks in Pennsylvania and New York where corrugated converters maintain underutilized capacity. Regional suppliers can compress delivery lead times against Southeast incumbents.
- Digital Watermark Integration:HolyGrail 2.0 sorting technology converges with club store packaging to enable automated material identification. Sorting facility upgrades create demand for packaging with embedded traceability markers.
- USDA BioPreferred Procurement:Federal purchasing guidelines favor biobased packaging content for foodservice applications. Club store private label suppliers can capture shelf space through certified biobased substrate qualification.
Industry Challenges
- FTC Green Guides Compliance:Environmental marketing claims on club store shelf labels require substantiation that many converters lack documentation to support. Misclassification risk triggers enforcement action.
- Coating Line Retrofit Costs:Transitioning from polyethylene barriers to recyclable alternatives demands capital investment in aqueous coating equipment. Mid-tier converters face financing constraints for asset replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Club Store Packaging Market |
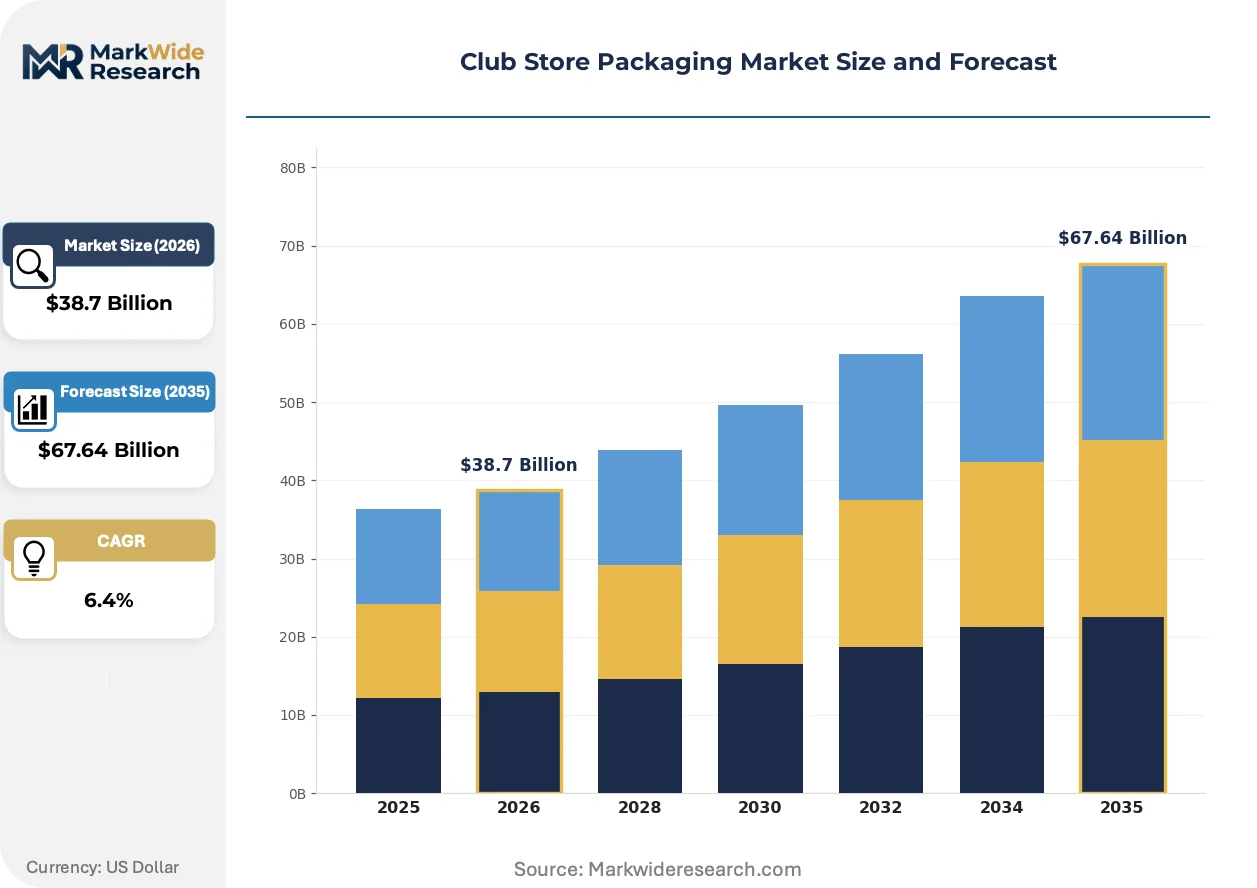
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $67.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Corrugated Boxes, Plastic Wraps, Blisters, Cartons Materials: Cardboard, PET, PVC, LDPE End User: Retail Chains, Wholesale Distributors, E-commerce, Food Service Size: Small, Medium, Large, Bulk |
| Companies Covered | Amcor plc, WestRock, International Paper Company, Graphic Packaging Holding Company, Smurfit WestRock plc, Berry Global, Sonoco, Packaging Corporation of America, Georgia Pacific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Club Store Packaging Market Strategic Shifts
Substrate engineering is converging with automated warehouse requirements as club retailers deploy robotic palletizing systems. Packaging formats must now integrate machine-readable dimensions and compression specifications.
Coated recycled board technology is converging with shelf-ready carton demand from branded consumer packaged goods suppliers. Costco and Sam's Club specify tear-resistant hand holes and display-grade print surfaces for general merchandise aisles. This convergence compresses lead times between converter production and retail floor placement.
The EPA's evolving solid waste guidelines tighten post-consumer recycled content thresholds for packaging sold into federal supply chains. Club store suppliers serving military commissary channels must certify compliance through third-party verification. California's SB 54 enforcement mechanism creates parallel compliance pressure for West Coast distribution center access.
Buyer concentration among three dominant warehouse club chains compresses supplier negotiation leverage. Procurement teams at Costco, Sam's Club, and BJ's Wholesale Club coordinate packaging specification standards that cascade through tier-one and tier-two converter bases. Vendor qualification cycles extend as centralized sourcing functions consolidate approved supplier lists.
Club Store Packaging Market Segmentation
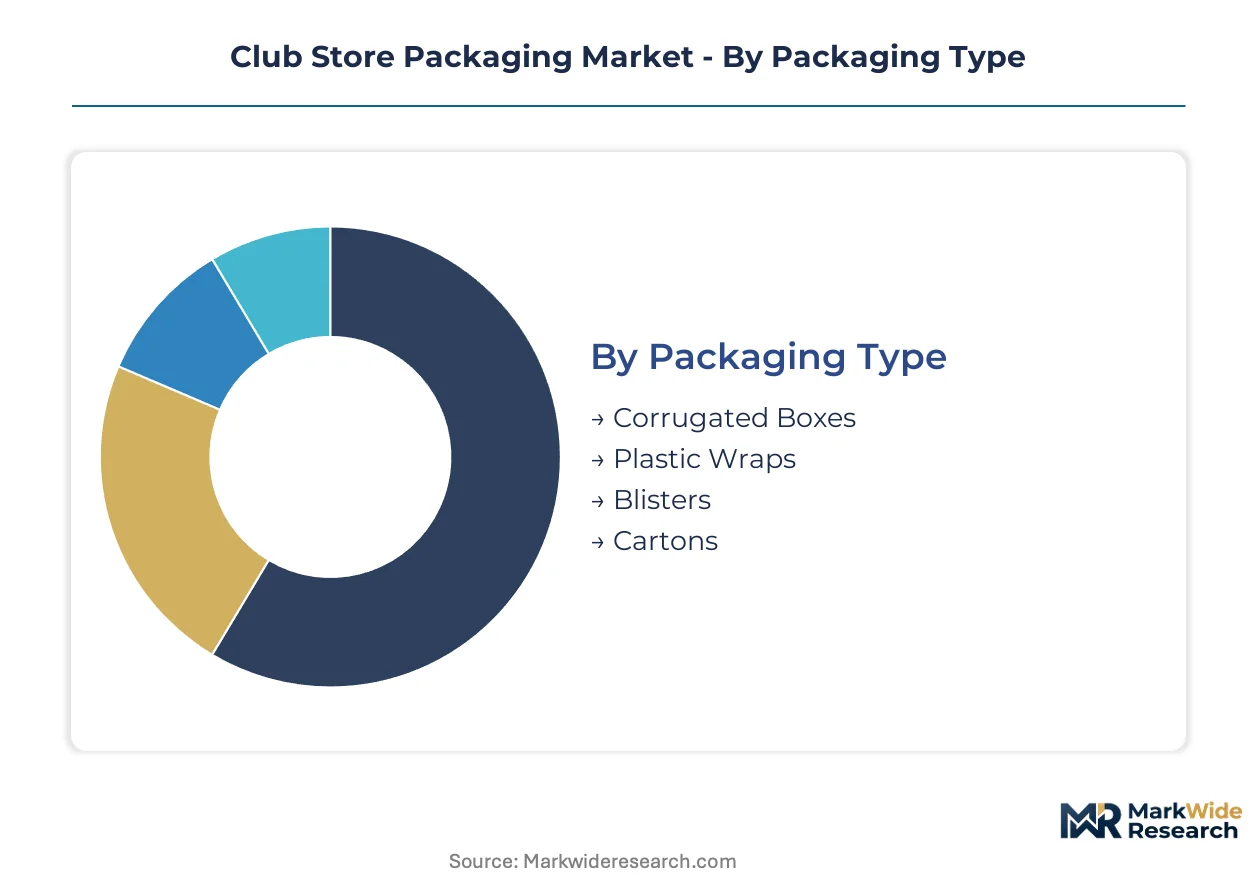
Warehouse club retailers specify packaging formats that cascade through tiered supplier bases. Substrate selection and dimensional standards vary sharply across fresh grocery, general merchandise, and private label channels.
Packaging Type:
Corrugated boxes dominate unit volume for 30-50 pound stock-keeping units, while plastic wraps and cartons split premium-margin applications.
- Corrugated Boxes:Triple-wall bulk bins with reinforced stacking strength handle forklift-compatible pallet loads. Costco and Sam's Club specify these formats for dry grocery and general merchandise aisles where compression resistance governs floor display integrity.
- Plastic Wraps:LDPE and PET formats provide moisture barrier performance for chilled meat and produce sections. West Coast distribution centers favor these substrates under California SB 54 compliance pressure for fiber-alternative pathways.
- Blisters:Clamshell configurations serve electronics and hardware multipacks where product visibility drives purchase conversion at point-of-sale.
- Cartons:Coated recycled board technology supports shelf-ready cartons for branded consumer packaged goods with tear-resistant hand holes and display-grade print surfaces.
Mature deployment sits with corrugated boxes. Newer deployment is concentrated in plastic wraps.
Materials:
Substrate economics divide between virgin fiber dominance in the US Southeast and recycled-content mandates pressing West Coast supply chains.
- Cardboard:Containerboard mills in Georgia and Alabama supply triple-wall and double-wall grades. Hurricane disruption risk concentrates supply vulnerability in this coastal corridor.
- PET:Recycled-content flake integration advances for produce clamshells under extended producer responsibility frameworks. FDA food-contact clearance requirements constrain rapid specification shifts.
- PVC:Rigid formats persist in non-food hardware applications where clarity and impact resistance outweigh recyclability concerns.
- LDPE:Linear low-density films stretch-wrap palletized loads and line corrugated bins for moisture-sensitive chilled categories.
Cardboard commands the deepest supplier integration. PET climbs the fastest on regulatory substitution pressure.
End User:
Procurement concentration among three dominant warehouse club chains compresses converter negotiation leverage across all end-use channels.
- Retail Chains:Costco, Sam's Club, and BJ's Wholesale Club coordinate centralized packaging specifications that propagate through approved supplier lists. Vendor qualification cycles extend as sourcing functions consolidate tier-one and tier-two converter bases.
- Wholesale Distributors:Foodservice redistribution networks demand pallet-ready formats compatible with automated warehouse systems. Machine-readable dimensions and compression specifications integrate with robotic palletizing infrastructure.
- E-commerce:Bulk-format compatibility with parcel carrier dimensional weight pricing constrains format innovation. Last-mile handling requirements diverge from club store floor display priorities.
- Food Service:Military commissary channels require USDA BioPreferred certification and EPA recycled-content verification for federal supply chain access.
Retail chains anchor volume concentration. Food service presents the steepest expansion trajectory on federal procurement preference expansion.
Size:
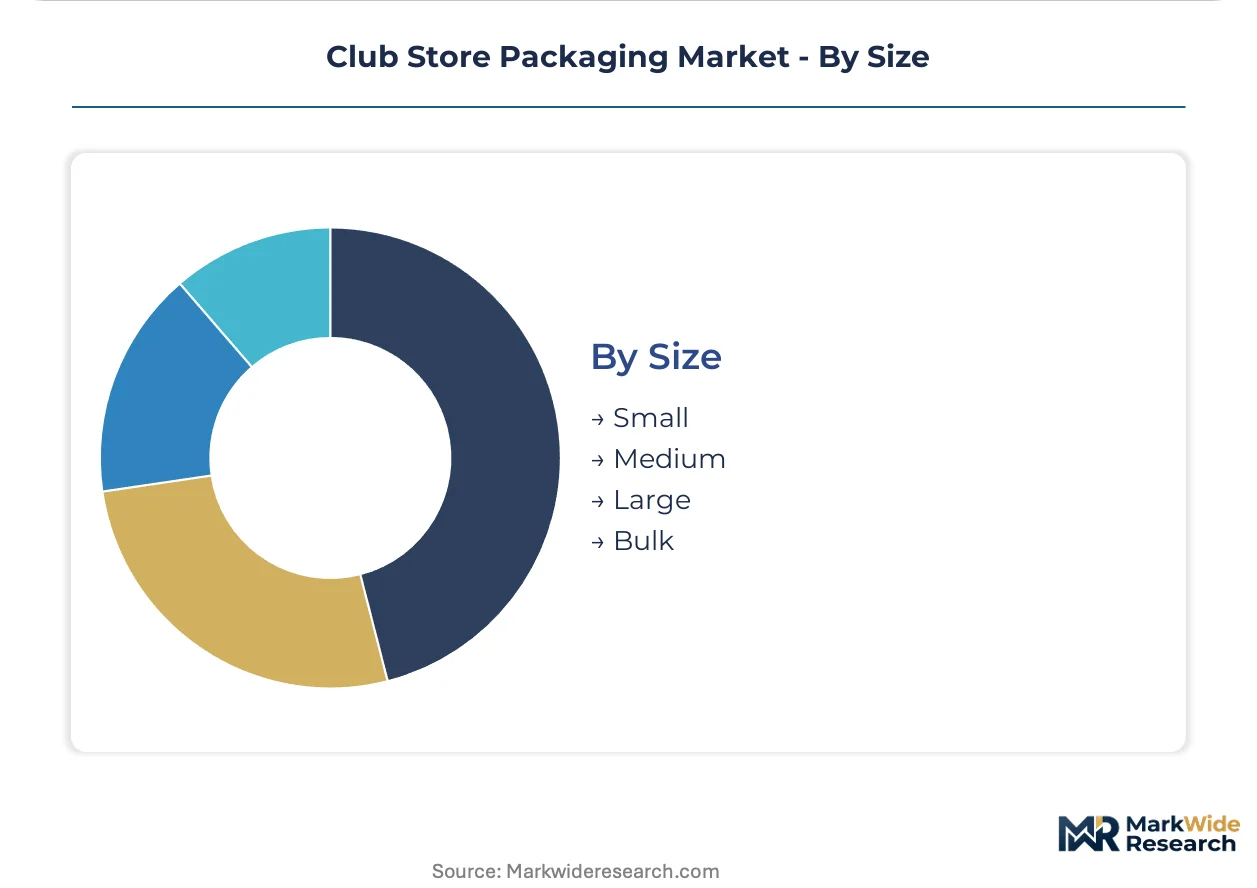
Dimensional standards track stock-keeping unit weight brackets and forklift handling requirements across club store floor configurations.
- Small:Individual-unit containment for electronics accessories and hardware components. Blisters and folding cartons dominate this bracket.
- Medium:Multi-pack configurations for consumer packaged goods with hand-hole reinforcement for consumer carry. Shelf-ready carton demand concentrates here.
- Large:Case-pack formats bridging retail shelf and backroom storage. Corrugated regular slotted containers with die-cut handles serve this transition zone.
- Bulk:Triple-wall pallet bins engineered for 30-50 pound stock-keeping units with display-ready graphics. Forklift entry points and stacking strength specifications are non-negotiable.
Bulk formats command the highest specification engineering. Small formats gain share fastest on electronics multipack expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Virgin containerboard mills in the US Southeast anchor fiber supply for bulk-format packaging serving warehouse club distribution networks. Regional substrate specialization concentrates in coastal corridors vulnerable to hurricane disruption.
United States
Warehouse club retailers in the United States command packaging specification standards that cascade through tiered supplier bases. The EPA regulates post-consumer recycled content thresholds under evolving solid waste guidelines, while California's SB 54 mandates extended producer responsibility for single-use packaging. Containerboard production clusters in Georgia and Alabama supply triple-wall bulk bins to Costco, Sam's Club, and BJ's Wholesale Club distribution centers.
Canada
Canadian corrugated converters serve cross-border warehouse club supply chains with recycled-content board certified for US federal procurement. Health Canada maintains food-contact clearance requirements that constrain rapid specification shifts for chilled meat packaging. Ontario-based mills supply pallet-ready formats to Great Lakes distribution networks serving BJ's Wholesale Club store clusters.
Mexico
Mexican packaging converters supply produce clamshells and corrugated bins for warehouse club fresh grocery expansion. The national environmental regulator enforces emerging extended producer responsibility frameworks for plastic packaging formats. Manufacturing concentration in the Mexico City Metro and Nuevo León regions supports nearshoring demand from US-based club retailers.
Germany
German packaging technology suppliers export automated palletizing systems to warehouse club distribution centers worldwide. ECHA REACH regulations govern chemical safety in coating formulations for shelf-ready cartons. Industrial concentration in Baden-Württemberg and North Rhine-Westphalia yields advanced aqueous coating equipment for recyclable barrier transitions.
China
Chinese converters manufacture LDPE films and PET clamshells for warehouse club private label suppliers at cost-competitive scale. MEE dual carbon goals pressure substrate shifts toward fiber-based alternatives in export-oriented production. Manufacturing gravity in the Yangtze River Delta and Pearl River Delta supplies global club store packaging demand with integrated resin-to-format capabilities.
Club Store Packaging Market Competitive Environment
Global majors compete with regional champions across fiber network access and recycled-content certification capabilities. The market exhibits tiered consolidation with integrated containerboard producers holding supply-side leverage over independent converters. Three archetypes dominate: integrated mill operators with captive fiber supply, specialty converters with coating technology differentiation, and regional players with geographic proximity to dense club store networks. Competitive moves center on capacity expansion in underpenetrated corridors and backward integration into post-consumer fiber collection networks.
Among integrated mill operators, WestRock, International Paper Company, and Graphic Packaging Holding Company exemplify scale-driven positioning. WestRock leverages integrated containerboard mills to sustain cost leadership on triple-wall bulk bins. International Paper Company anchors its competitive stance through geographic dominance in the US Southeast. Graphic Packaging Holding Company occupies a differentiated position via coated recycled board technology optimized for shelf-ready carton applications.
| Leading Market Players |
|---|
| Amcor plc |
| WestRock |
| International Paper Company |
| Graphic Packaging Holding Company |
| Smurfit WestRock plc |
| Berry Global |
| Sonoco |
| Packaging Corporation of America |
| Georgia Pacific |
| Others |
Value Chain & Pricing Dynamics
Centralized procurement teams at Costco, Sam's Club, and BJ's Wholesale Club impose contract-based long-term offtake structures that compress converter margins while locking in volume commitments. This buyer concentration forces suppliers to absorb OCC price volatility through fixed-price arrangements rather than pass-through mechanisms.
Pricing Analysis
Warranty and compliance certification bundles separate premium-tier suppliers from unbundled economy competitors in club store vendor qualification. Three-tier pricing structure across premium, standard, and economy levels tracks recycled-content certification tiers under EPA guidelines and California SB 54 mandates. Cost compression in standard-grade corrugated intensifies because mid-tier converters lack aqueous coating retrofit capital. Private label suppliers exhibit highest price sensitivity due to thin margin pools, while military commissary contractors accept premium pricing for USDA BioPreferred verification.
Supply Chain Analysis
Old corrugated containerboard supply rests on municipal recycling collection networks concentrated in the US Southeast, coastal China, and Germany's industrial corridor. Virgin fiber draws from Georgia and Alabama pulp mills, while recycled flake feeds from post-consumer collection programs in coastal California and the Yangtze River Delta. Hurricane disruption to Southeast containerboard mills creates single-source vulnerability during peak season. Distribution runs through warehouse club regional distribution centers with forklift-compatible pallet specifications mandated at point of receipt.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Containerboard mill capacity constraints in hurricane-exposed coastal corridors prop pricing power for integrated producers with captive fiber supply. Supply tightness persists until mid-tier converters complete aqueous coating line retrofits.
For Market Incumbents: Deploy backward integration into post-consumer fiber collection networks to secure OCC supply against municipal collection rate volatility. WestRock and International Paper Company should accelerate triple-wall bulk bin capacity expansion in underpenetrated Mid-Atlantic corridors where BJ's Wholesale Club maintains dense store networks. California SB 54 enforcement pressure on polyethylene-barrier formats demands immediate aqueous coating qualification to defend shelf placement at West Coast distribution centers. For New Entrants and Emerging Players: California SB 54 in the United States opens a window for fiber-alternative substrate specialists to capture produce clamshell volume from PET incumbents lacking viable end-of-life pathways. Target Pennsylvania and New York corrugated supply gaps where regional converters maintain underutilized capacity against Southeast incumbents. Digital watermark integration for HolyGrail 2.0 sorting compliance offers a differentiated go-to-market angle for mid-tier players seeking tier-two supplier qualification. For Investors and Strategic Acquirers: The window for entry favors specialty converters with coating technology differentiation and USDA BioPreferred certification capabilities. Acquisition targets should demonstrate aqueous barrier R&D pipelines and geographic proximity to dense club store networks in the Mid-Atlantic or Great Lakes regions. Watch California SB 54 enforcement velocity and EPA recycled-content threshold tightening as inflection indicators for fiber-substitution investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiber Collection | Captive OCC supply insulates margins against hurricane disruption to Southeast pulp mills. |
| Aqueous Coating Line Retrofit | California SB 54 compliance unlocks West Coast distribution center access for coated board suppliers. |
| USDA BioPreferred Certification | Military commissary channel qualification commands premium pricing in federal procurement. |
| Digital Watermark Integration | HolyGrail 2.0 traceability markers enable automated sorting compliance for extended producer responsibility frameworks. |
| Mid-Atlantic Capacity Expansion | Proximity to BJ's Wholesale Club dense networks compresses delivery lead times against Southeast incumbents. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with corrugated plant managers, club store procurement directors, coating equipment suppliers, and EPA compliance officers combined with bottom-up shipment data and top-down macroeconomic indicators. Secondary sources included EPA solid waste guideline documents, California SB 54 regulatory filings, USDA BioPreferred procurement databases, and containerboard mill production disclosures. Cross-validation occurred through triangulation across converter shipment reports and warehouse club distribution center receipts.
Data-stream reconciliation aligned volume outputs from substrate-level production tracking with value estimates derived from contract pricing disclosures across the analysis window. Segmentation modeling incorporated packaging type, material substrate, end-user channel, and dimensional size tier as core dimensions. CAGRs were computed from year-over-year growth rate interpolation across the projection horizon. Industry-specific forecast inputs included OCC price index trajectories, hurricane disruption frequency assumptions, and state-level extended producer responsibility adoption schedules.
Caveats apply where California SB 54 enforcement velocity, EPA recycled-content threshold revisions, or hurricane season severity could materially shift the outlook. Forecasts reflect assumptions about aqueous coating technology adoption rates and municipal recycling collection program stability. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retail Packaging
Retail Ready Trays Market
Retail Packaging
Retail E Commerce Packaging Market
Retail Packaging
Retail Ready Packaging (RRP) Market
Retail Packaging
Floor POP Display Market
Retail Packaging
Free Standing Display Units Market
Retail Packaging
Black Friday Packaging Market
Retail Packaging
Table Tent Market
Retail Packaging
Retail Bags Market
Retail Packaging
Global Shoe Packaging Market