
 Middle East Geospatial Analytics Market | 2026-2036
Middle East Geospatial Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Geospatial Analytics Market Insights
Government procurement channels across the Middle East is tilting toward integrated geospatial platforms that bundle satellite imagery with AI-driven analytics. Esri Inc. leverages its ArcGIS ecosystem to anchor long-term enterprise contracts with ministries throughout the Gulf. Hexagon AB competes through specialized sensor-to-software workflows for precision agriculture and urban modeling. Bayanat sustains its position by dominating indigenous mapping capabilities aligned with UAE sovereignty priorities.
Geospatial analytics encompasses the computational processing of location-referenced data from GPS, remote sensing, and LiDAR sources to derive spatial patterns, predictive models, and visualization outputs for operational decision-making. The technology stack processes raster and vector data through coordinate transformation algorithms, spectral analysis, and machine learning classification to support infrastructure lifecycle management and environmental compliance. Remote sensing and GIS technologies lead solution deployment across the Middle East, with LiDAR representing the fastest-growing segment as Gulf states prioritize three-dimensional urban modeling for mega-project planning. Mapping services capture mature, recurring revenue streams from government accounts, while predictive analytics concentrates margin pools where oil and gas operators demand failure-forecasting for critical assets.
SFDA in Saudi Arabia and MOHAP in the UAE shape healthcare facility geolocation standards, while the country's national spatial data infrastructure mandates from Saudi Arabia's General Authority for Survey and Geospatial Information govern cadastral accuracy and cross-border data sharing protocols. These frameworks compel vendors to certify coordinate reference systems and localize data residency to maintain contract eligibility. Stakeholders must monitor how Gulf Cooperation Council harmonization of geospatial standards reshapes vendor qualification requirements and cross-border service delivery permissions.
Market Dynamics
Gulf national oil companies are consolidating procurement around integrated satellite-to-analytics platforms, compressing vendor margins while elevating data sovereignty requirements as the dominant market-shaping force.
Growth Catalysts
- SDG-aligned spatial mandates:Saudi Arabia's General Authority for Survey and Geospatial Information mandates are compelling government digitization of cadastral records and cross-border data protocols, creating mandatory procurement flows.
- Offshore asset monitoring:Pipeline integrity management for subsea infrastructure across UAE and Qatari oil fields is pulling high-resolution synthetic aperture radar subscriptions into long-term enterprise contracts.
- Smart city densification:Dubai's geospatial master planning investments are concentrating demand for three-dimensional urban modeling and real-time mobility analytics.
Market Restraints
- Sensor hardware concentration:LiDAR component supply concentrates among North American and European specialist manufacturers, exposing Gulf integrators to extended lead times and currency volatility.
- Data residency compliance costs:Cross-border geospatial data sharing protocols under Saudi national spatial data infrastructure frameworks impose localization infrastructure burdens on foreign platform vendors.
- Technical talent scarcity:Spectral analysis and coordinate transformation algorithm expertise remains concentrated in academic and government research institutes, constraining commercial deployment velocity.
Strategic Opportunities
- Precision agriculture expansion:Water-stressed cultivation zones across Saudi Arabia's Qassim and Al-Jawf regions present untapped demand for sensor-to-software crop monitoring workflows.
- Healthcare facility geolocation standards:SFDA and MOHAP mandates for emergency response routing and pharmaceutical cold-chain tracking are opening specialized analytics sub-segments.
- AI-satellite convergence:Machine learning classification of multi-spectral imagery combined with predictive maintenance algorithms for critical infrastructure is creating differentiated service tiers.
Industry Challenges
- Legacy GIS integration friction:Established government ministries operate decades-old coordinate reference systems, complicating migration to cloud-native analytics architectures without operational disruption.
- Certification timeline compression:Vendor qualification under evolving Gulf Cooperation Council harmonization standards demands repeated compliance investments without guaranteed contract awards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Geospatial Analytics Market |
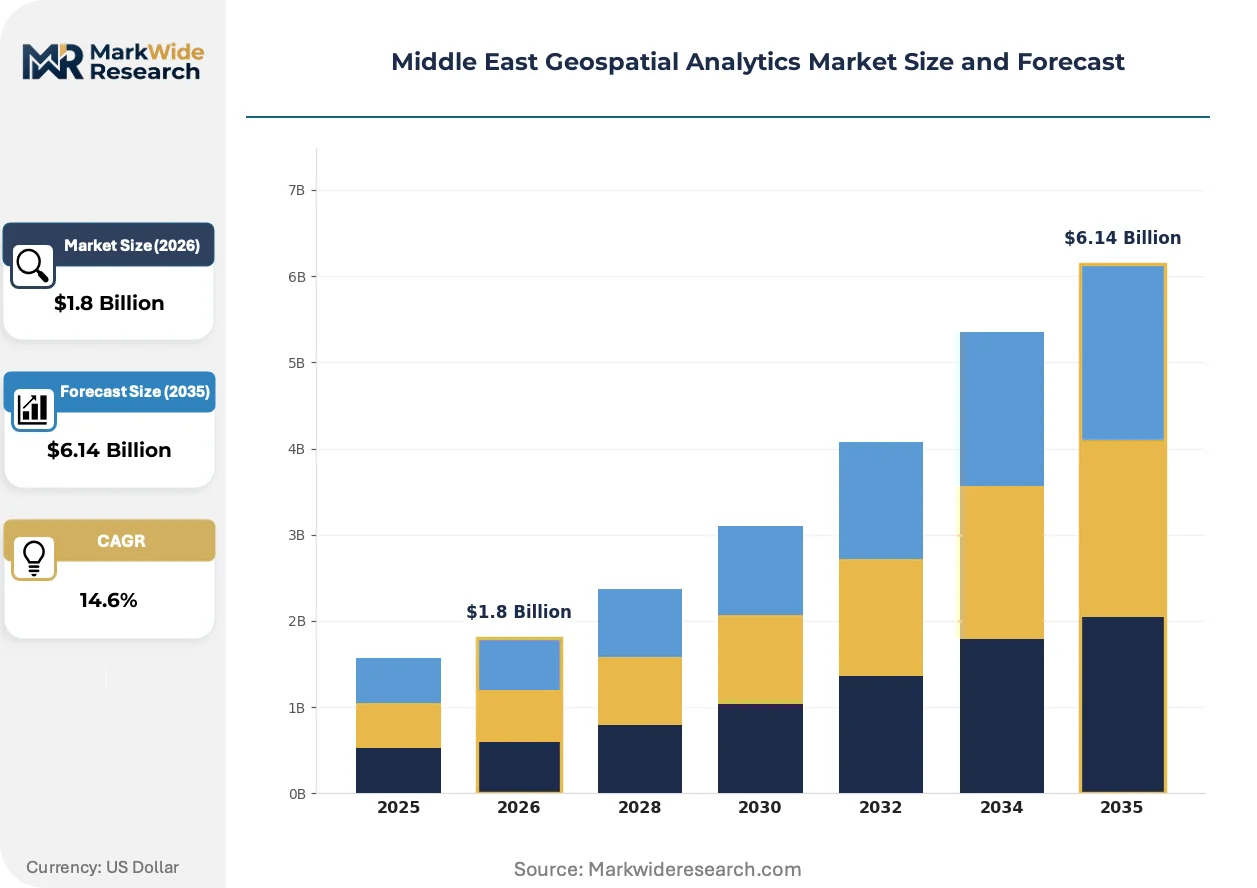
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Urban Planning, Environmental Monitoring, Disaster Management, Infrastructure Development Technology: GPS, Remote Sensing, GIS, LiDAR End User: Government, Construction, Transportation, Defense Solution: Data Visualization, Predictive Analytics, Mapping Services, Spatial Analysis |
| Companies Covered | Trimble Inc., Fugro, Esri Inc., Maxar Technologies, Atkins, Hexagon AB, Autodesk Inc., Bayanat, Bentley Systems Inc., Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Geospatial Analytics Market Trends and Innovations
Computational methods for processing location-referenced data are shifting from batch analytics toward real-time streaming architectures, compressing decision cycles for infrastructure operators and urban planners across Gulf markets.
Digital twin platforms integrating LiDAR point clouds with IoT sensor feeds are rendering obsolete static two-dimensional mapping workflows for mega-project planning. Saudi Aramco and ADNOC are deploying these systems across greenfield developments. The technology is compressing design-validation cycles from months to weeks while elevating accuracy requirements for competing vendors.
Saudi Arabia's General Authority for Survey and Geospatial Information is tightening cadastral accuracy mandates and cross-border data sharing protocols. Foreign platform providers must now certify coordinate reference systems and establish local data residency to maintain contract eligibility. European and North American vendors are responding through joint ventures with indigenous mapping specialists rather than direct market entry.
State-owned oil operators are consolidating vendor relationships around multi-year platform subscriptions that bundle satellite imagery with predictive analytics. Traditional transactional procurement of discrete mapping products is retreating to smaller municipal accounts. This concentration is most visible in Abu Dhabi, where ADNOC's master planning digitization has collapsed its supplier base to three integrated platform providers.
Middle East Geospatial Analytics Market Segmentation
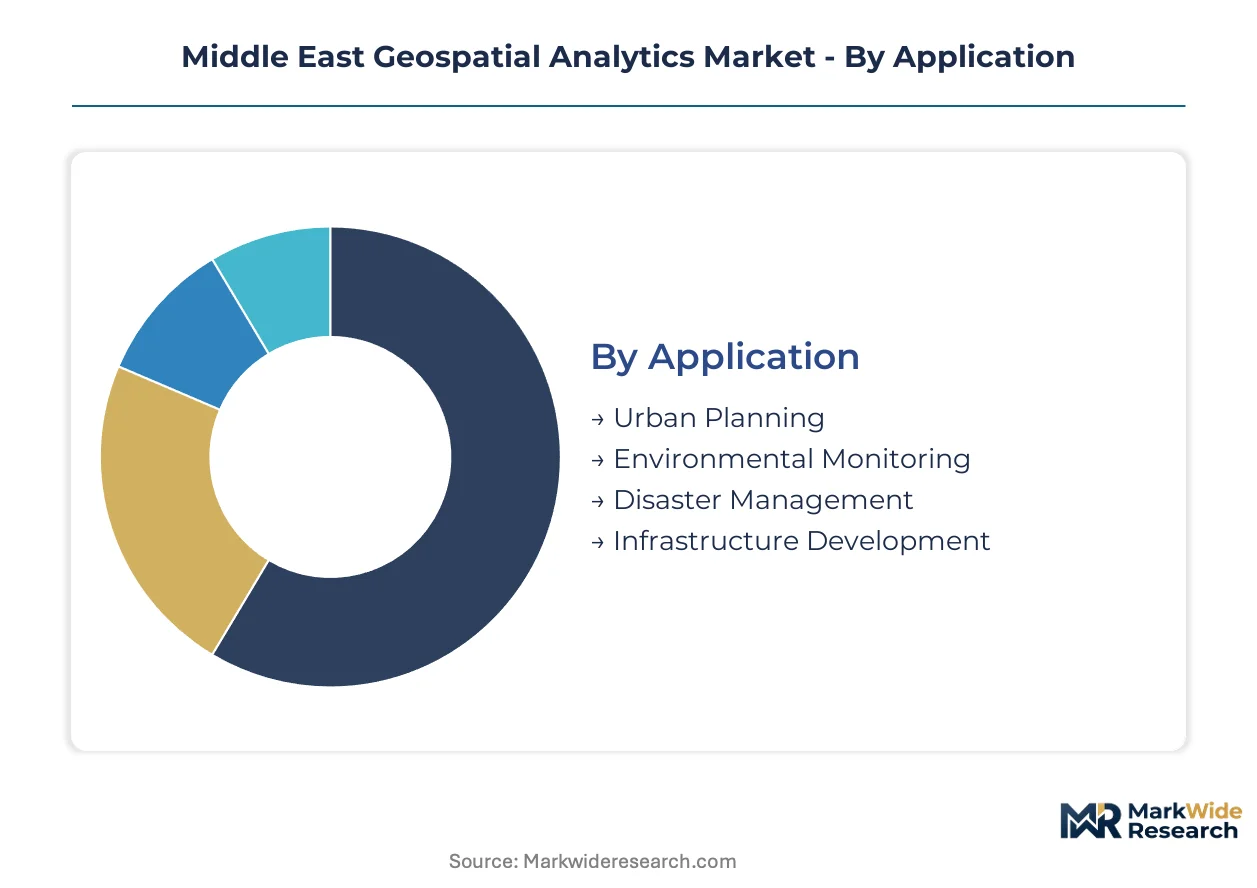
Geospatial procurement across the Middle East fragments across distinct technology stacks and institutional buyers. Each segment carries unique certification requirements and data sovereignty constraints that reshape vendor qualification pathways.
Application:
Use-case spectrum spans sovereign infrastructure mandates to climate adaptation protocols across Gulf states.
- Urban Planning:Three-dimensional modeling workflows support Dubai's smart city densification and Saudi mega-project master planning. Municipal procurement concentrates in UAE and Saudi Arabia where SDG-aligned spatial mandates compel digitization of cadastral systems.
- Environmental Monitoring:Spectral analysis of vegetation stress and coastal erosion tracks compliance with national sustainability frameworks. Water-stressed cultivation zones in Saudi Arabia's Qassim region pull sensor-to-software crop monitoring subscriptions.
- Disaster Management:Emergency response routing systems align with SFDA and MOHAP healthcare facility geolocation standards.
- Infrastructure Development:Pipeline integrity management for subsea oil field assets drives synthetic aperture radar analytics adoption.
Established volume favors Urban Planning; emerging adoption favors Environmental Monitoring.
Technology:
Cost tier stratification separates mature positioning systems from capital-intensive active sensing arrays.
- GPS:Satellite positioning infrastructure underpins fleet management and cadastral surveying across government ministries. Procurement runs through established defense and transportation channels with minimal localization requirements.
- Remote Sensing:Multi-spectral and synthetic aperture radar imagery supports offshore asset monitoring and agricultural yield forecasting. Gulf national oil companies consolidate procurement around multi-year satellite imagery subscriptions with embedded predictive analytics.
- GIS:Coordinate transformation algorithms and vector data management anchor government spatial data infrastructure mandates.
- LiDAR:Active laser scanning generates dense point clouds for three-dimensional urban modeling. Hardware component supply concentrates among North American and European specialist manufacturers, exposing Gulf integrators to extended lead times.
Mature deployment favors GIS; steepest expansion trajectory favors LiDAR.
End User:
Customer type determines contract duration, with sovereign accounts commanding multi-year platform subscriptions.
- Government:National spatial data infrastructure mandates from Saudi Arabia's General Authority for Survey and Geospatial Information govern procurement specifications and data residency requirements. Ministries dominate mapping services and cadastral digitization spend.
- Construction:Mega-project developers deploy digital twin platforms integrating LiDAR point clouds with IoT sensor feeds, compressing design-validation cycles.
- Transportation:Real-time mobility analytics support Dubai's geospatial master planning investments and logistics corridor optimization.
- Defense:Restricted procurement channels prioritize indigenous mapping capabilities aligned with UAE sovereignty priorities.
Contract concentration favors Government; technology sophistication favors Construction.
Solution:
Margin pools concentrate where machine learning classification elevates raw spatial data into predictive operational intelligence.
- Data Visualization:Dashboard rendering of raster and vector outputs serves municipal planning departments with standardized requirements.
- Predictive Analytics:Failure-forecasting algorithms for critical oil and gas infrastructure command premium pricing from ADNOC and Saudi Aramco. Demand clusters where operators demand predictive maintenance for subsea pipeline networks.
- Mapping Services:Recurring revenue streams from government accounts capture mature, stable procurement flows with established coordinate reference system certifications.
- Spatial Analysis:Spectral classification and change detection algorithms support environmental compliance and urban growth monitoring.
Recurring stability favors Mapping Services; margin expansion favors Predictive Analytics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Saudi Arabia's government procurement channels while UAE-based integrators absorb margin compression from data localization mandates. The spatial analytics value chain fragments across Gulf Cooperation Council jurisdictions with divergent certification timelines.
Saudi Arabia
National spatial data infrastructure mandates from the General Authority for Survey and Geospatial Information compel cadastral digitization and cross-border protocol standardization. SFDA healthcare facility geolocation standards create specialized demand for emergency response routing analytics. Riyadh anchors mega-project master planning deployments where digital twin platforms compress design-validation cycles.
United Arab Emirates
Dubai's geospatial smart city investments and Abu Dhabi's master planning digitization generate concentrated procurement pull for three-dimensional urban modeling. MOHAP pharmaceutical cold-chain tracking mandates open specialized analytics sub-segments. Dubai South and Masdar City clusters host integrated platform deployments for real-time mobility analytics.
Qatar
Offshore pipeline integrity management for North Field expansion drives synthetic aperture radar subscription demand. The country's national spatial data framework governs coordinate reference system certifications for foreign vendors. Doha-based infrastructure operators consolidate procurement around predictive maintenance algorithms for subsea assets.
Kuwait
Oil field digitization initiatives pull high-resolution satellite imagery into long-term enterprise contracts with integrated analytics bundles. National mapping agency mandates enforce data residency requirements on platform providers. Ahmadi and Al-Zour industrial zones concentrate deployment of sensor-to-software workflows for asset monitoring.
Oman
Water-stressed agricultural zones in Al-Batinah and Dhofar regions present emerging demand for precision crop monitoring. The country's spatial data infrastructure development lags Saudi and UAE frameworks, extending vendor qualification timelines. Duqm Special Economic Zone anchors greenfield digital twin deployments for port and logistics corridor optimization.
Middle East Geospatial Analytics Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying LiDAR hardware and spectral sensors. The vendor base stratifies between full-stack geospatial platforms securing multi-year government contracts and niche analytics boutiques serving oil field operators. Three archetypes dominate: satellite imagery aggregators with embedded AI classification, indigenous mapping specialists leveraging data sovereignty requirements, and sensor-to-software workflow providers for precision applications. Consolidation pressures manifest through joint ventures with local partners to satisfy residency mandates and long-term subscription bundling that displaces transactional procurement.
Among the platform tier, Esri Inc. and Hexagon AB anchor enterprise positioning through established ministry relationships and specialized urban modeling capabilities. Bayanat occupies a distinct position as the indigenous UAE mapping specialist aligned with federal sovereignty priorities. These three exemplify divergent competitive vectors: foreign platform penetration through compliance adaptation versus domestic capability capture through government mandate alignment.
| Leading Market Players |
|---|
| Trimble Inc. |
| Fugro |
| Esri Inc. |
| Maxar Technologies |
| Atkins |
| Hexagon AB |
| Autodesk Inc. |
| Bayanat |
| Bentley Systems Inc. |
| Others |
Pricing and Supply Chain Analysis
Riyadh's government procurement corridors concentrate pricing power for integrated geospatial platforms, with Saudi Arabia's General Authority for Survey and Geospatial Information mandates forcing foreign vendors to absorb localization infrastructure costs that compress margins across the Gulf vendor base.
Pricing Analysis
Configured-to-order pricing for sovereign-compliant platforms commands substantial premiums over standardized SaaS tiers. Three-tier pricing structure across premium, standard, and economy levels separates enterprise digital twin deployments from municipal mapping subscriptions. Cost compression in standard tiers intensifies because national oil companies consolidate procurement around multi-year bundled subscriptions. Government ministries exhibit lowest price sensitivity given mandate-driven procurement, while municipal planning departments and agricultural operators demonstrate highest elasticity.
Supply Chain Analysis
Upstream laser scanning components and spectral sensors draw from concentrated manufacturing bases in the United States, Germany, and Canada. Gulf integrators source LiDAR hardware, multi-spectral imaging arrays, and coordinate transformation chipsets through specialized North American and European distributors. Single-source vulnerability for active sensing hardware exposes regional deployment timelines to extended lead time volatility. Distribution runs through Dubai-based logistics hubs serving UAE, Saudi Arabia, and Qatar with localized assembly for data residency compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's SDG-aligned spatial mandates are disrupting legacy procurement patterns, creating a high-growth inflection as government digitization compels platform refresh cycles across the Gulf.
For Market Incumbents: Insulate enterprise relationships by deepening in-house production of indigenous mapping capabilities aligned with UAE and Saudi data sovereignty requirements. Bayanat's government mandate alignment demonstrates how localization investment defends against foreign platform penetration. Prioritize certification under evolving Gulf Cooperation Council harmonization standards to maintain contract eligibility.
For New Entrants and Emerging Players: Build out precision agriculture workflows targeting water-stressed cultivation zones in Saudi Arabia's Qassim and Al-Jawf regions, where incumbent presence remains thin. Sensor-to-software crop monitoring subscriptions offer the most penetrable entry point given minimal legacy GIS integration friction. Partner with regional agricultural cooperatives for demonstration-scale deployments that validate failure-forecasting algorithms.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors indigenous mapping specialists with established government relationships and data residency infrastructure. Long-term viability hinges on capture of recurring platform subscriptions rather than transactional project revenue. Watch for Gulf Cooperation Council standard harmonization announcements as the signal indicating vendor qualification timeline compression and accelerated consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Joint Venture with Indigenous Mapping Specialist | Satisfies Saudi and UAE data residency mandates while accelerating government contract access. |
| LiDAR Hardware Localization Facility | Reduces lead time exposure from North American and European component manufacturers. |
| AI-Satellite Convergence Platform Launch | Captures predictive maintenance demand from ADNOC and Saudi Aramco subsea asset operators. |
| Precision Agriculture Workflow Acquisition | Secures sensor-to-software capabilities for Saudi water-stressed cultivation zones. |
| Healthcare Facility Geolocation Certification | Aligns with SFDA and MOHAP emergency response routing mandates for specialized analytics. |
Research Methodology
Cross-validation between primary interviews with geospatial platform executives and secondary validation through regulatory filings anchors the qualitative findings. The research program incorporated structured conversations with government procurement officers at Saudi Arabia's General Authority for Survey and Geospatial Information, national oil company digital transformation leads, municipal planning directors, and precision agriculture operators. Secondary sources included customs records for LiDAR and spectral sensor imports, SEC filings from listed platform vendors, and Gulf Cooperation Council standard harmonization documents. Bottom-up deployment tracking across Dubai, Riyadh, and Doha clusters was triangulated against top-down government budget allocation analysis.
Calibration against historical procurement velocity and announced mega-project timelines shaped the analytical framework. The model segmented volume and value across application, technology, end user, and solution dimensions, with additional stratification by data sovereignty compliance tier and coordinate reference system certification status. CAGRs were derived from trend extrapolation of satellite imagery subscription growth and digital twin platform adoption curves, with cross-checks against national spatial data infrastructure investment announcements and smart city densification schedules.
Sensitivities concentrate around Gulf Cooperation Council harmonization timeline delays and LiDAR component supply disruptions. Forecasts reflect assumptions regarding continued government mandate enforcement and national oil company procurement consolidation. Cross-checking against disclosed platform subscription values from Esri Inc. and Hexagon AB public filings is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Audio and Video Analytics Software Market
Analytics
Global Graph Analytics Market
Analytics
Data Wrangling Market
Analytics
Face Analytics Market
Analytics
Global Visual Analytics Market
Analytics
Customer Data Platform Market
Analytics
Asia-Pacific Crowd Analytics Market
Analytics
India Big Data Analytics Market
Analytics
Global Mobile BI Market
Analytics
North America Speech Analytics Market
Analytics
Europe Data Monetization Market
Analytics
Global Data Fusion Market
Analytics
Global Data Analysis Software Market
Analytics
Big Data in Automotive Market
Analytics
Personal Analytics Market
Analytics
Multi-Touch Attribution Market