
 Canada Location-Based Services Market | 2026-2036
Canada Location-Based Services Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Location-Based Services Market Insights
Channel partnerships between telecom infrastructure providers and enterprise software vendors is rewriting how location-based solutions reach Canadian buyers. Google LLC leverages its mapping API ecosystem to anchor cloud-native positioning services for mid-market retailers. Ericsson Inc. competes through its 5G network slicing capabilities, which sustain ultra-low-latency geolocation for autonomous vehicle trials in Ontario and Quebec. IBM Corporation differentiates by embedding AI-driven spatial analytics into hybrid deployment models that dominate security-conscious government contracts.
Location-based services encompass software and hardware systems that determine, track, and analyze the geographic position of users or assets through satellite navigation, wireless signal triangulation, or sensor fusion, typically achieving spatial accuracy from centimeter-grade RTK-GPS to room-level Wi-Fi fingerprinting. These systems serve commercial and industrial purposes ranging from consumer wayfinding to mission-critical emergency dispatch routing. GPS technology leads the technology dimension due to its ubiquity in smartphones and fleet telematics, while Wi-Fi positioning represents the fastest-growing segment as retailers deploy Bluetooth beacon mesh networks for sub-meter indoor navigation. Cloud-based deployment models capture expanding margin pools as Canadian enterprises prioritize scalable subscription architectures over capital-intensive on-premise infrastructure.
Health Canada regulates location-aware medical devices under the Medical Devices Regulations, requiring clinical validation for patient-tracking systems deployed in hospitals. The Office of the Privacy Commissioner of Canada enforces PIPEDA compliance for consumer geolocation data collection, forcing platforms to implement granular consent frameworks. Innovation, Science and Economic Development Canada manages spectrum allocation for 5G positioning networks, shaping infrastructure rollout timelines. Stakeholders must monitor forthcoming amendments to federal privacy legislation that could mandate explicit opt-in protocols for commercial geofencing applications.
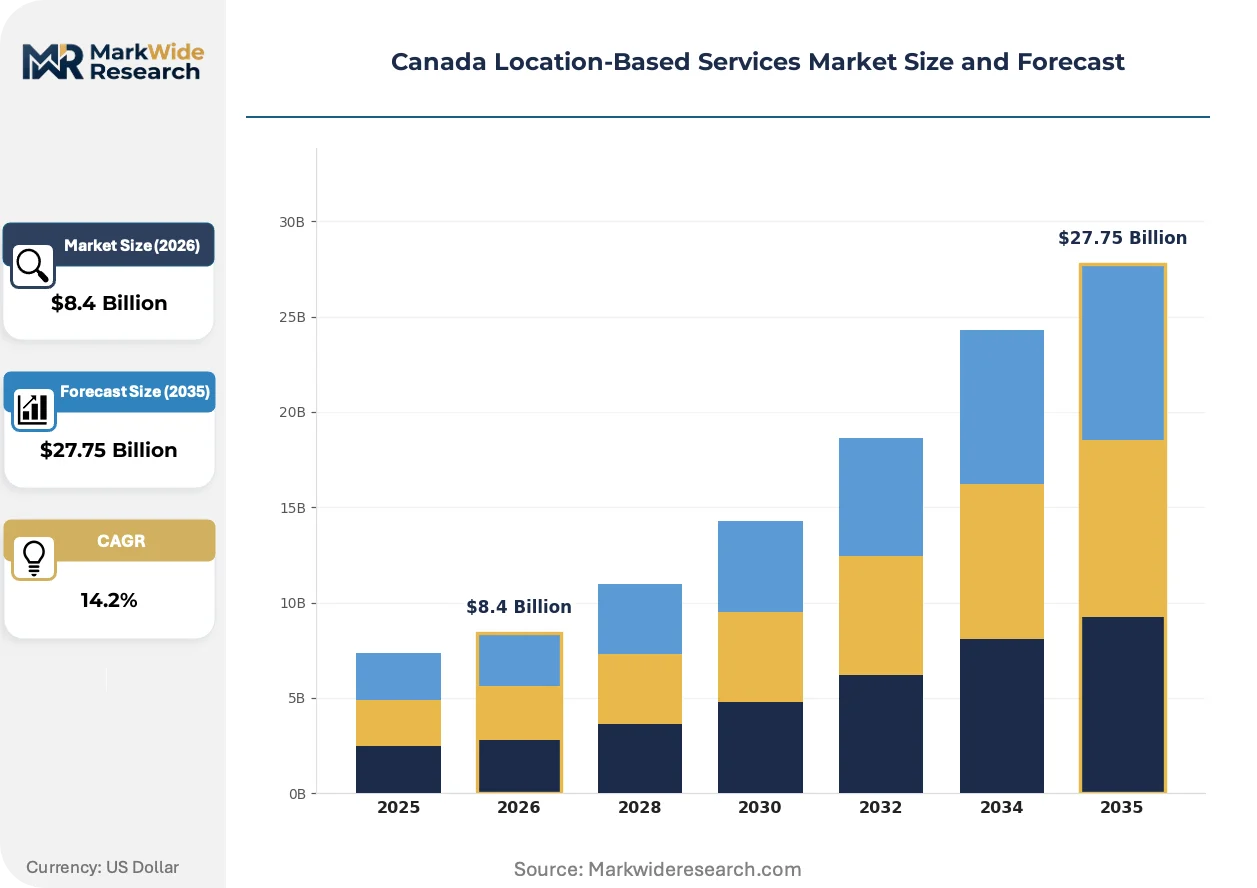
Market Dynamics
Health Canada's tightening Medical Devices Regulations for location-aware patient monitoring systems are forcing domestic vendors to restructure compliance workflows, while 5G network slicing investments by telecom carriers create new infrastructure layers for ultra-low-latency positioning services.
Growth Catalysts
- Smart city infrastructure mandates:Ontario's municipal procurement frameworks prioritize real-time asset tracking and geofencing platforms for urban mobility optimization in the Greater Toronto Area.
- Bluetooth beacon mesh proliferation:Canadian retailers deploy sub-meter indoor navigation systems to optimize foot traffic analytics and inventory placement strategies.
- PIPEDA consent framework evolution:Granular geolocation data collection protocols enable compliant consumer tracking applications across retail and healthcare verticals.
Market Restraints
- Spectrum allocation bottlenecks:Innovation, Science and Economic Development Canada's 5G positioning network timelines delay infrastructure rollout in secondary urban markets.
- Clinical validation costs:Health Canada's patient-tracking system requirements impose capital-intensive validation cycles on hospital deployment projects.
- Cloud migration inertia:Security-conscious government contracts sustain hybrid deployment preferences that compress margin pools for pure-cloud vendors.
Strategic Opportunities
- Autonomous vehicle trials:Ontario and Quebec testbeds create concentrated demand for centimeter-grade RTK-GPS and sensor fusion platforms.
- Fleet telematics modernization:Logistics hub density in the Greater Toronto Area accelerates GPS-integrated subscription service adoption.
- AI-driven spatial analytics convergence:Machine learning integration with Wi-Fi fingerprinting enables predictive positioning for emergency dispatch routing.
Industry Challenges
- RTK-GPS technician scarcity:Specialized calibration expertise for centimeter-grade systems limits deployment velocity in remote Canadian markets.
- Legacy on-premise integration friction:Government security requirements force complex middleware architectures that extend implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Location-Based Services Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $27.75 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application Type: Navigation, Tracking, Mapping, Fleet Management Technology: GPS, RFID, Wi-Fi Positioning, Cellular Triangulation End User: Retail, Transportation, Healthcare, Emergency Services Deployment Model: On-Premise, Cloud-Based, Hybrid, Mobile |
| Companies Covered | Cisco Systems Inc., IBM Corporation, Google LLC, Ericsson Inc., Esri Technologies Ltd, Zebra Technologies Corporation, HPE Aruba Inc., ALE International, Maxar Technologies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Location-Based Services Market Trends and Innovations
Sensor fusion architectures combining Wi-Fi fingerprinting with Bluetooth beacon mesh networks are compressing deployment economics for indoor positioning, while regulatory pressure on geolocation consent frameworks reshapes platform design priorities.
Ultra-wideband (UWB) chipsets delivering sub-10-centimeter spatial accuracy are rendering obsolete traditional Wi-Fi trilateration for retail inventory tracking. Department store chains in Ontario are piloting UWB-enabled shelf-level analytics to reduce stockout incidents. The technology is rendering obsolete room-level positioning budgets in favor of item-level granularity that directly ties to loss prevention ROI.
Health Canada's forthcoming amendments to federal privacy legislation mandate explicit opt-in protocols for commercial geofencing applications. Platform vendors must rebuild consent collection interfaces to capture granular permission states before location processing. Hospital systems deploying patient-tracking infrastructure face the steepest compliance retrofit requirements as clinical use cases intersect with consumer-grade geolocation frameworks.
Subscription-based positioning service contracts are displacing perpetual license sales in Canadian enterprise procurement. Mid-market retailers favor consumption-scaled SaaS architectures that align costs with seasonal foot traffic volatility. Quebec's municipal fleet operators exhibit the strongest preference shift, bundling real-time asset tracking with predictive maintenance modules under unified service agreements.
Canada Location-Based Services Market Segmentation
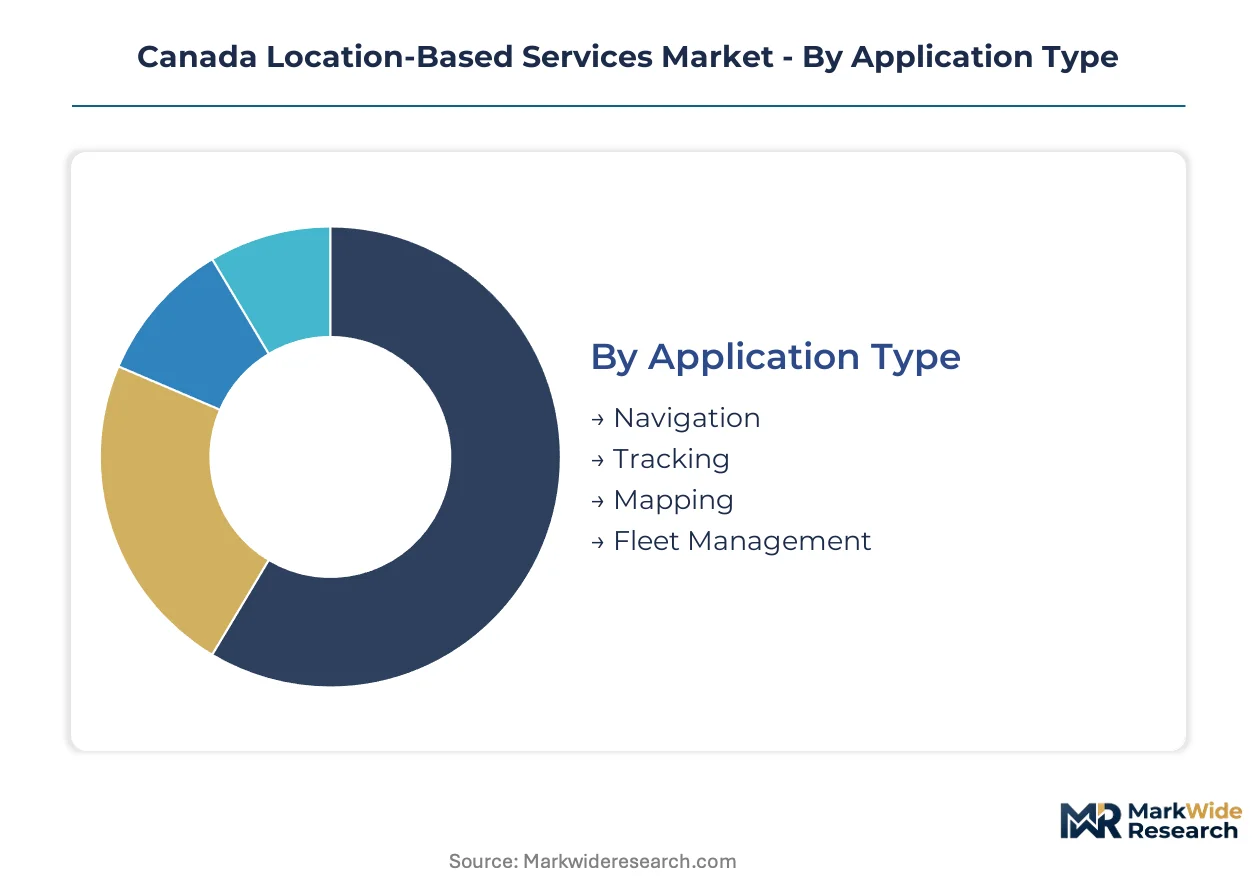
Canada Location-Based Services Market segmentation reveals how positioning technologies align with distinct operational requirements across verticals. Deployment choices and technology selection vary sharply between Ontario's smart city corridors and resource-dependent provinces where connectivity constraints dominate.
Application Type:
Application type captures the functional purpose driving procurement decisions across Canadian enterprise buyers.
- Navigation:Consumer-facing wayfinding systems leverage smartphone GPS and Wi-Fi fingerprinting to deliver turn-by-turn guidance in urban cores. Toronto's PATH underground network and Montreal's RESO deploy these systems to manage pedestrian flow through complex indoor environments where satellite signals fail.
- Tracking:Real-time asset positioning systems combine cellular triangulation with Bluetooth beacon mesh networks to monitor high-value equipment and personnel. Mining operations in Northern Ontario and Alberta's oil sands deploy these systems for worker safety compliance in remote terrain where traditional connectivity infrastructure remains sparse.
- Mapping:Spatial data collection platforms generate centimeter-grade topographic surveys for infrastructure planning and environmental monitoring.
- Fleet Management:GPS-integrated telematics platforms optimize route efficiency and regulatory compliance for commercial vehicle operators.
Navigation holds installed capacity. Tracking is rotating up the share rankings.
Technology:
Technology dimension reflects the positioning accuracy and infrastructure investment trade-offs facing Canadian deployers.
- GPS:Satellite-based positioning achieves meter-grade accuracy through smartphone and vehicle-integrated receivers, dominating outdoor commercial applications. Fleet telematics providers across the Greater Toronto Area rely on GPS as the foundational layer for subscription-based logistics optimization services.
- Wi-Fi Positioning:Signal fingerprinting and access point triangulation deliver room-level indoor accuracy without dedicated hardware deployment. Quebec retailers and Ontario healthcare facilities favor this approach for rapid deployment cycles where Bluetooth beacon infrastructure remains capital-prohibitive.
- RFID:Passive and active radio-frequency tags enable proximity-based identification for inventory and access control systems.
- Cellular Triangulation:Network-based positioning leverages existing 5G infrastructure to estimate location where GPS signals degrade.
GPS holds installed capacity. Wi-Fi Positioning is rotating up the share rankings.
End User:
End user segmentation aligns platform capabilities with sector-specific regulatory and operational requirements.
- Transportation:Logistics operators and autonomous vehicle testbeds demand centimeter-grade RTK-GPS and sensor fusion for lane-level positioning. Ontario's Highway 407 corridor and Quebec's Montreal-Sherbrooke autonomous trucking routes concentrate procurement of ultra-low-latency positioning infrastructure.
- Healthcare:Hospital systems deploy location-aware patient monitoring under Health Canada's Medical Devices Regulations, requiring clinical validation for tracking systems used in acute care settings. Toronto's University Health Network and Vancouver Coastal Health lead procurement of compliant indoor positioning for asset and patient flow optimization.
- Retail:Department stores and mall operators leverage foot traffic analytics to optimize lease rates and inventory placement.
- Emergency Services:Dispatch routing systems require sub-second location updates for first responder coordination.
Transportation holds installed capacity. Healthcare is rotating up the share rankings.
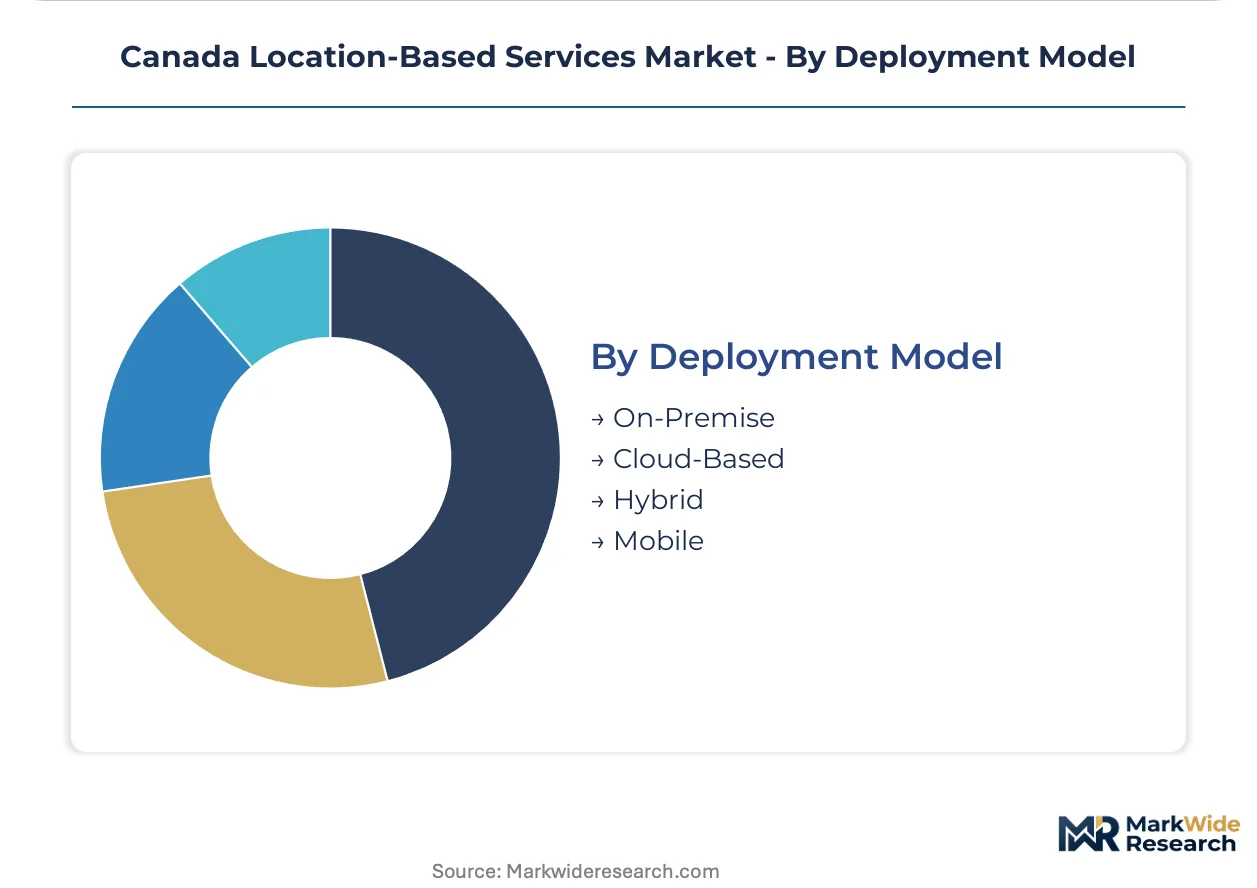
Deployment Model:
Deployment model reflects capital structure preferences and data sovereignty requirements across Canadian buyer segments.
- Cloud-Based:Scalable subscription architectures enable mid-market retailers to align positioning costs with seasonal demand volatility. Quebec municipal fleet operators and Ontario logistics hubs favor consumption-scaled SaaS contracts that bundle real-time tracking with predictive maintenance modules.
- Hybrid:On-premise edge processing with cloud analytics satisfies security-conscious government contracts requiring data residency compliance. Federal procurement frameworks and provincial healthcare authorities mandate this architecture for sensitive geolocation data handling.
- On-Premise:Capital-intensive perpetual license models persist in defense and critical infrastructure applications.
- Mobile:Smartphone-native positioning leverages existing device penetration for consumer-facing applications.
Hybrid holds installed capacity. Cloud-Based is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Ontario's Greater Toronto Area, where smart city infrastructure budgets and logistics hub density command premium deployment rates. Secondary markets in Atlantic Canada and the Prairie Provinces face compressed margins due to connectivity infrastructure gaps and dispersed demand.
Ontario
Autonomous vehicle trials along Highway 407 and dense logistics corridors drive demand for centimeter-grade RTK-GPS and sensor fusion platforms. Health Canada's Medical Devices Regulations tighten compliance for patient-tracking systems deployed in Toronto's University Health Network. The PATH underground pedestrian network anchors indoor positioning deployments combining Wi-Fi fingerprinting with Bluetooth beacon mesh networks.
Quebec
Municipal fleet operators in Montreal exhibit strong preference shifts toward subscription-based real-time asset tracking bundled with predictive maintenance modules. Innovation, Science and Economic Development Canada manages spectrum allocation timelines that shape 5G positioning network rollout in secondary urban markets. Montreal-Sherbrooke autonomous trucking routes concentrate procurement of ultra-low-latency geolocation infrastructure.
British Columbia
Vancouver Coastal Health leads procurement of compliant indoor positioning for asset and patient flow optimization in acute care settings. The Office of the Privacy Commissioner of Canada enforces PIPEDA compliance frameworks that force granular consent collection interface rebuilds for commercial geofencing applications. Vancouver's port logistics cluster accelerates GPS-integrated telematics adoption for regulatory compliance and route efficiency.
Alberta
Oil sands operations deploy real-time asset positioning systems for worker safety compliance in remote terrain with sparse traditional connectivity infrastructure. Health Canada's forthcoming privacy legislation amendments mandate explicit opt-in protocols that reshape platform design priorities for industrial applications. Calgary's municipal procurement frameworks prioritize hybrid deployment models satisfying data residency requirements for sensitive geolocation handling.
Canada Location-Based Services Market Competitive Landscape
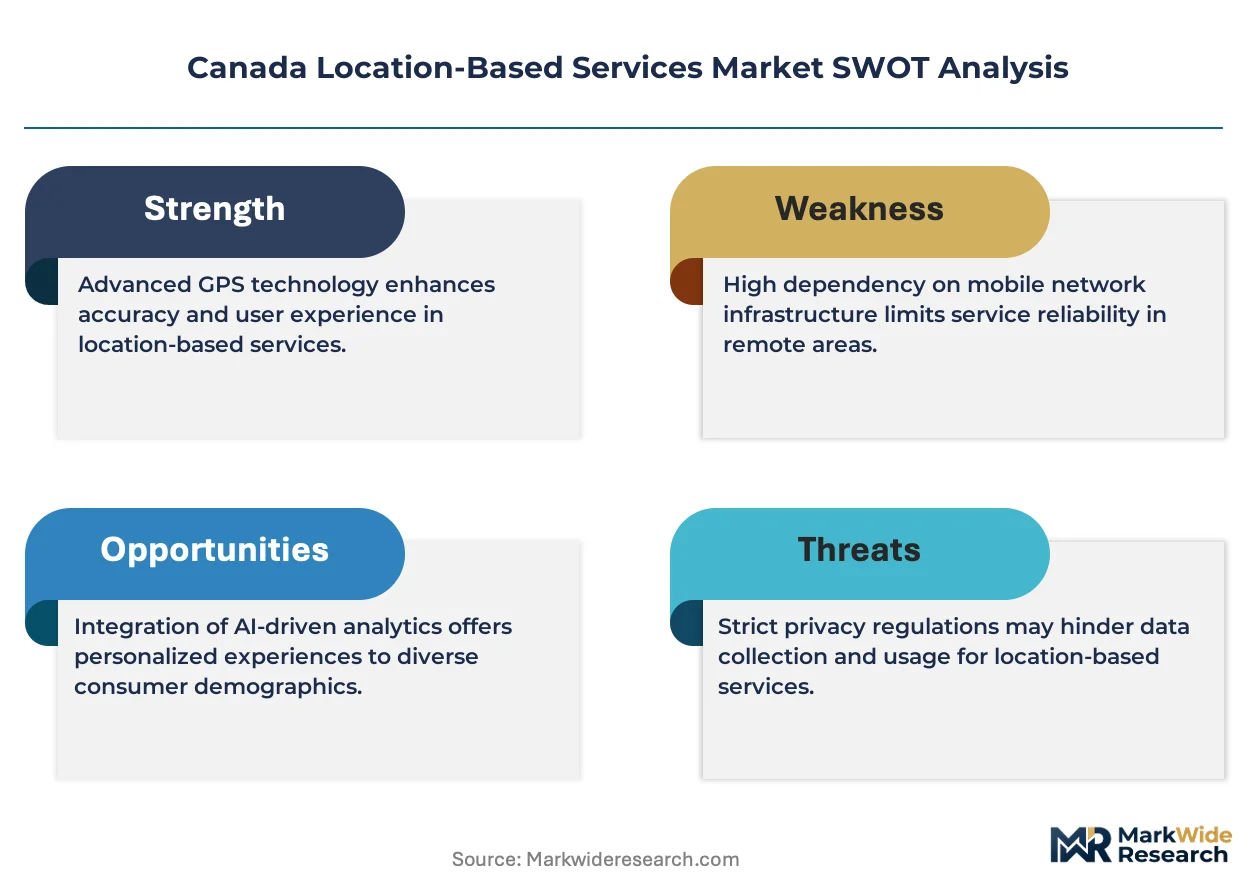
Platform integrators command the system tier; component specialists sit upstream in the positioning technology stack. The vendor base organizes around three strategic archetypes: cloud-native mapping API providers, 5G infrastructure-anchored telecom vendors, and AI-embedded spatial analytics specialists. Consolidation pressures favor channel partnerships between telecom infrastructure providers and enterprise software vendors. Competitive moves concentrate on hybrid deployment architecture development and subscription-based service model migration.
Within the platform integrator tier, Google LLC and IBM Corporation exemplify divergent positioning strategies. Google leverages its mapping API ecosystem to anchor cloud-native services for mid-market retail segments. IBM occupies a position embedding AI-driven spatial analytics into hybrid deployment models that dominate security-conscious government contracts. Ericsson Inc. represents the telecom-anchored archetype, competing through 5G network slicing capabilities that sustain ultra-low-latency geolocation for autonomous vehicle trials. Cisco Systems Inc. and HPE Aruba Inc. sit within the enterprise networking convergence space, bridging Wi-Fi positioning infrastructure with enterprise security frameworks.
| Leading Market Players |
|---|
| Cisco Systems Inc. |
| IBM Corporation |
| Google LLC |
| Ericsson Inc. |
| Esri Technologies Ltd |
| Zebra Technologies Corporation |
| HPE Aruba Inc. |
| ALE International |
| Maxar Technologies |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in specialized RTK-GPS calibration expertise across remote Canadian markets tightens supplier pricing power while compressing margins for standardized Wi-Fi positioning hardware. Health Canada's clinical validation requirements for location-aware medical devices further stratify procurement economics between compliant hospital systems and price-sensitive retail deployers.
Pricing Analysis
The customization-premium spread between configured-to-order hybrid deployments and standard cloud-native subscriptions defines pricing architecture across Canadian enterprise buyers. Subscription-based SaaS models dominate mid-market retail procurement, while three-tier pricing structure across premium, standard, and economy levels prevails in government contracts where data residency requirements command certification premiums. Price differentiation hinges on Health Canada compliance tier and geographic delivery cost to remote mining operations. Cost compression in standardized Bluetooth beacon hardware intensifies because Chinese manufacturing scale floods commodity positioning components. Municipal fleet operators exhibit highest price sensitivity, while hospital systems under Medical Devices Regulations absorb premium pricing for validated patient-tracking infrastructure.
Supply Chain Analysis
Tariff exposure between the United States and China dominates component sourcing risk for Canadian location-based service vendors assembling positioning hardware. Semiconductor fabrication concentrates in Taiwan, South Korea, and the United States, while UWB chipset production draws from Chinese and South Korean foundries. Supply chain risk centers on single-source vulnerability for centimeter-grade GPS modules essential to autonomous vehicle testbeds in Ontario and Quebec. Distribution runs through telecom infrastructure partnerships that bundle 5G network slicing with enterprise software vendor platforms, compressing direct procurement channels for standalone positioning hardware.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canada's location-based services market represents high-growth disruption as 5G network slicing investments by Ericsson Inc. and domestic carriers create infrastructure layers for ultra-low-latency positioning services previously technically infeasible.
For Market Incumbents: Insulate installed base through backward integration into RTK-GPS calibration service networks, addressing technician scarcity that limits deployment velocity in remote markets. Deepen Health Canada compliance workflows to extend validation moats against cloud-native entrants lacking clinical infrastructure. Prioritize hybrid deployment architecture development to defend government contract share against pure-cloud competitors. For New Entrants and Emerging Players: Pursue Atlantic Canada and Prairie Provinces where connectivity infrastructure gaps create whitespace for sensor-fusion platforms bypassing 5G dependency. Target municipal fleet operators in Quebec exhibiting strongest preference shift toward subscription-based asset tracking bundled with predictive maintenance. Deploy channel partnerships with regional telecom carriers as primary go-to-market angle rather than direct enterprise sales. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-native mapping API providers serving mid-market retail segments with consumption-scaled contracts. Long-term viability over the next decade rests on regulatory compliance capabilities as Health Canada amendments mandate explicit opt-in protocols reshaping platform design. Acquisition target archetype: AI-embedded spatial analytics specialists with hybrid deployment expertise and existing hospital system relationships. Monitor 5G spectrum allocation timelines from Innovation, Science and Economic Development Canada as inflection indicator for infrastructure rollout velocity in secondary urban markets.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Google LLC's mapping API ecosystem anchors cloud-native positioning services for Ontario retailers. |
| Strategic Partnership | Ericsson Inc.'s 5G network slicing capabilities sustain ultra-low-latency geolocation for Quebec autonomous vehicle trials. |
| Acquisition of Specialist Firm | IBM Corporation embeds AI-driven spatial analytics into hybrid deployment models dominating federal contracts. |
| Geographic Expansion | Vancouver Coastal Health procurement of compliant indoor positioning extends vendor footprint into British Columbia healthcare. |
| Product Launch | UWB-enabled shelf-level analytics pilot programs in Ontario department stores reduce stockout incidents. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with platform engineers, hospital biomedical engineers, municipal fleet procurement officers, and telecom infrastructure planners; and secondary validation against Innovation, Science and Economic Development Canada spectrum filings, Health Canada Medical Devices Regulations guidance documents, Office of the Privacy Commissioner PIPEDA enforcement actions, and hyperscaler cloud service capex disclosures. Bottom-up and top-down triangulation cross-validated deployment model adoption rates against provincial procurement database patterns.
Forecast inputs considered technology segmentation across GPS, Wi-Fi positioning, and sensor fusion architectures; deployment model preferences spanning cloud-based, hybrid, and on-premise; and end-user verticals including transportation, healthcare, retail, and emergency services across the analysis window. CAGRs derived from weighted regression against infrastructure investment timelines and regulatory compliance cycle lengths. Industry-specific forecast inputs incorporated 5G network slicing rollout schedules and Health Canada validation pipeline throughput.
Macroeconomic conditions sit as an overlay; deviation in municipal infrastructure budgets, spectrum auction pricing, and cross-border semiconductor tariff regimes would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory amendment timing and carrier capital commitment sustainability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Geographic Information Systems (GIS)
Geographic Information System Analytics Market
Geographic Information Systems (GIS)
Business Mapping Software Market
Geographic Information Systems (GIS)
Spain Location-Based Services Market
Geographic Information Systems (GIS)
US Location-Based Services Market
Geographic Information Systems (GIS)
Geomarketing Market
Geographic Information Systems (GIS)
Geographic Information System (GIS) Software Market
Geographic Information Systems (GIS)
Japan Geographic Information System (GIS) Market
Geographic Information Systems (GIS)
Location-Based Marketing Software Market
Geographic Information Systems (GIS)
Italy Location-Based Services Market
Geographic Information Systems (GIS)
India Location-Based Services Market
Geographic Information Systems (GIS)
Europe Geographic Information System (GIS) Market
Geographic Information Systems (GIS)
Mobile Mapping Market
Geographic Information Systems (GIS)
Cloud GIS Market
Geographic Information Systems (GIS)
Japan Location-Based Services Market
Geographic Information Systems (GIS)
Nigeria Geospatial Analytics Market
Geographic Information Systems (GIS)
Location Based Advertising Market