
 Virtual Client Computing Software Market | 2026-2036
Virtual Client Computing Software Market Size, Share, and Industry Trends Forecast 2026-2036
Virtual Client Computing Software Market Intelligence
Enterprise IT administrator talent is collapsing across North America and Western Europe, forcing organizations toward managed virtual desktop services that reduce on-premise complexity. Microsoft leverages its Azure Virtual Desktop ecosystem to anchor cloud-native delivery, while Dell sustains endpoint-hardware integration with its VDI-optimized workstation portfolio. Nutanix competes through hyperconverged infrastructure that collapses compute and storage layers for streamlined virtual desktop deployment.
Virtual Client Computing Software encompasses technologies that abstract desktop operating systems, applications, and data from local hardware, streaming encrypted pixel streams or application sessions to endpoint devices over standard network protocols. The architecture typically employs broker services, connection gateways, and profile management layers to maintain session state across intermittent connectivity. Desktop as a Service leads commercial adoption due to minimal capital requirements and elastic scaling, while Virtual Desktop Infrastructure retains dominance in regulated sectors where direct infrastructure control preserves audit trails. Session-based Virtualization captures cost-sensitive education deployments through shared server resources that maximize concurrent user density.
The EU AI Act, GDPR, and ISO 27001 standards collectively reshape product requirements by mandating data sovereignty, encryption granularity, and audit logging within virtual client platforms. HIPAA in the US imposes comparable constraints on healthcare implementations, restricting multi-tenant architectures without documented business associate agreements. Stakeholders must evaluate whether hybrid cloud orchestration or dedicated sovereign instances better satisfy diverging jurisdictional compliance thresholds as workforce distribution becomes permanent.
Market Dynamics
Enterprise IT departments face a structural talent shortage that collapses on-premise infrastructure expertise across North America and Western Europe. This compression forces organizations toward managed service delivery models that externalize complexity while preserving compliance posture.
Growth Catalysts
- EU AI Act compliance mandates:Healthcare delivery networks in Germany and France deploy sovereign cloud-hosted virtual desktops to satisfy algorithmic transparency and data residency requirements under the EU AI Act.
- Hyperconverged infrastructure maturation:Nutanix and Dell deployments collapse compute-storage layers, reducing virtual desktop provisioning time from weeks to hours for mid-market enterprises.
- HIPAA audit trail preservation:US hospital systems retain Virtual Desktop Infrastructure over Desktop as a Service to maintain direct infrastructure control and documented business associate agreements.
Market Restraints
- GPU supply concentration:NVIDIA's dominance in graphics virtualization silicon creates single-source dependency for GPU-accelerated virtual desktop workloads.
- Network latency thresholds:Session-based virtualization performance degrades below 50ms round-trip latency, excluding rural broadband deployments in Australia and Canada.
- GDPR cross-border data friction:Multi-tenant cloud architectures face operational restrictions without documented adequacy decisions between EU member states and third countries.
Strategic Opportunities
- India's PLI scheme for data centers:Production-linked incentives attract hyperscaler investment in Mumbai and Chennai, creating captive sovereign cloud capacity for regional virtual desktop delivery.
- Edge computing convergence:5G network slicing combined with micro data centers enables sub-20ms virtual desktop streaming for manufacturing floor applications.
- ISO 27001 certification acceleration:Managed service providers automate audit logging and encryption granularity to capture financial services compliance budgets.
Industry Challenges
- Broker service integration complexity:Legacy Citrix environments resist migration to cloud-native connection gateways without forklift infrastructure replacement.
- Profile management skill scarcity:IT administrators with FSLogix or VMware App Volumes expertise command premium compensation, constraining mid-market adoption velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Virtual Client Computing Software Market |
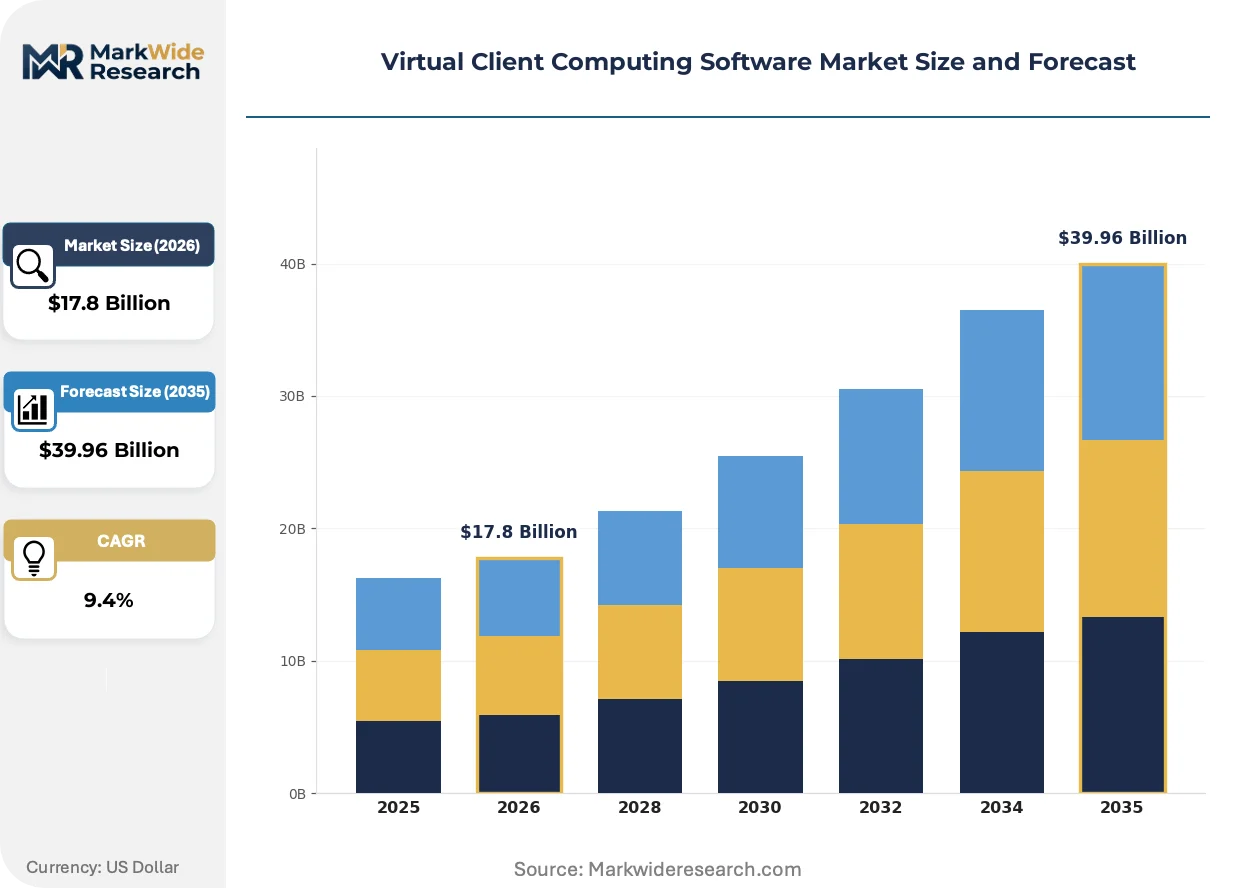
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $39.96 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desktop as a Service, Virtual Desktop Infrastructure, Remote Application Access, Session-based Virtualization Deployment: Public Cloud, Private Cloud, Hybrid Cloud, On-premises End User: Small Enterprises, Large Enterprises, Education Sector, Government Agencies Solution: Security Management, Data Management, User Management, Network Optimization |
| Companies Covered | Cisco Systems, Dell, Microsoft, Nutanix, Hewlett Packard Enterprise Development, Broadcom, Amazon Web Services, Hitachi, Cloud Software Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Virtual Client Computing Software Market Strategic Shifts & Innovations
Virtual client computing architectures are fragmenting into specialized delivery models as regulatory sovereignty requirements collide with workforce mobility demands. This tension generates parallel innovation tracks in cloud-native abstraction and on-premise control planes.
GPU virtualization technology is bifurcating market structure. NVIDIA vGPU and AMD MxGPU now partition physical graphics silicon into discrete virtual instances for CAD and media workloads. Engineering firms in Germany and Japan adopt these partitions at scale for remote workstation replacement. The technology is bifurcating vendor strategies between high-performance dedicated allocations and cost-optimized shared resources.
REACH chemical restrictions and F-Gas Regulation in Europe constrain cooling system designs for data centers hosting virtual desktop infrastructure. Dell and HPE reformulate thermal management to eliminate restricted refrigerants from server deployments. German manufacturing facilities face accelerated hardware refresh cycles to satisfy environmental compliance timelines.
Subscription-based consumption is displacing perpetual licensing for virtual desktop software. Healthcare and financial services buyers in the US and UK consolidate vendor relationships under enterprise agreements with committed annual volumes. Channel partners in London and New York pivot from resale margins to managed service annuity streams.
Virtual Client Computing Software Market Segmentation
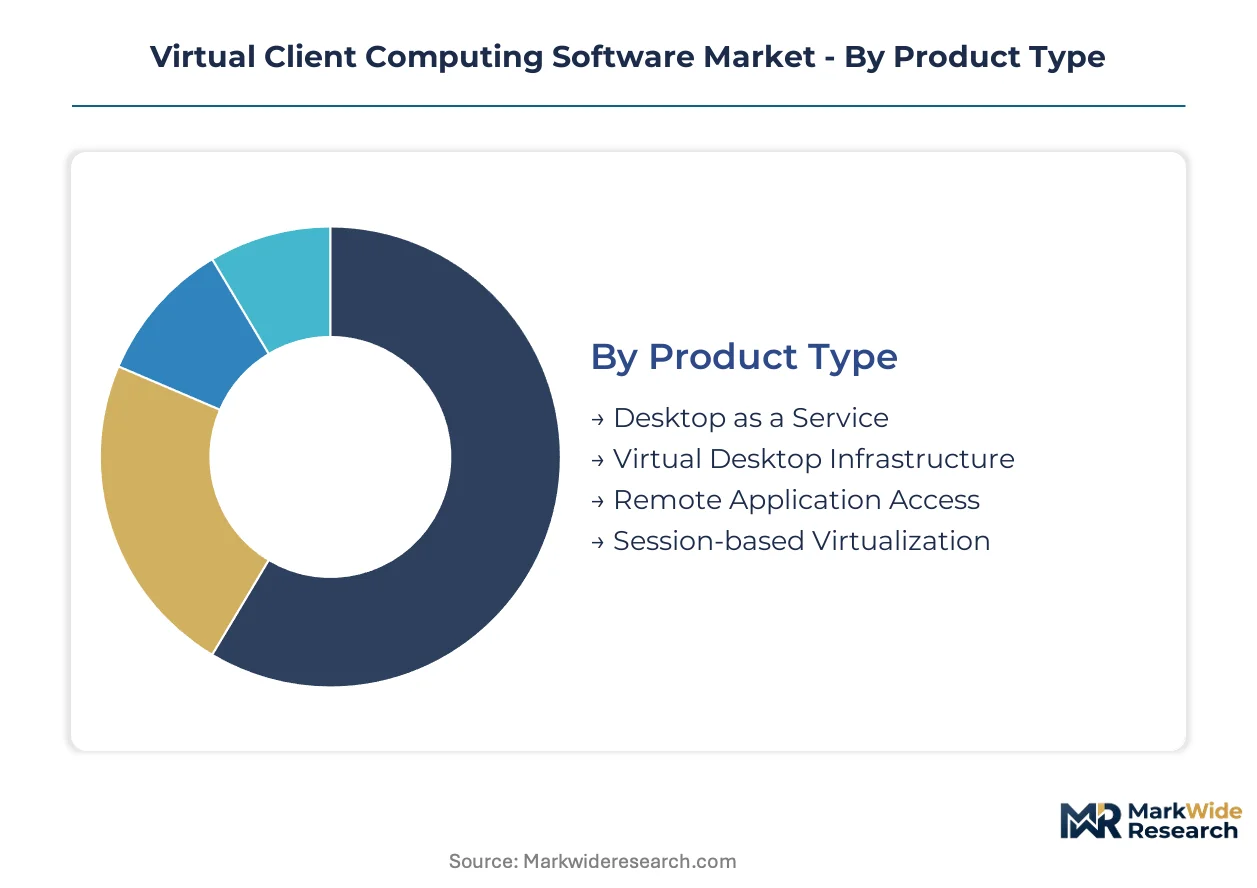
Segmentation in virtual client computing software reveals how architectural choices lock in margin structures and compliance postures. Product type and deployment mode determine whether vendors capture recurring service revenue or one-time license fees.
Product Type:
Margin pools concentrate in managed service delivery where infrastructure complexity is externalized, while perpetual license models face compression from cloud-native alternatives.
- Desktop as a Service:Cloud-native architecture streams encrypted desktop sessions from hyperscaler infrastructure with zero client-side capital expenditure. Healthcare networks in Germany and France deploy DaaS to satisfy EU AI Act data residency mandates without building sovereign data centers. DaaS holds installed capacity. Session-based Virtualization is rotating up the share rankings.
- Virtual Desktop Infrastructure:On-premise hypervisor clusters host persistent desktop VMs with direct infrastructure control and full audit trail preservation. US hospital systems retain VDI under HIPAA to maintain documented business associate agreements and eliminate multi-tenant risk exposure.
- Remote Application Access:Application streaming isolates software execution from endpoint hardware through protocol-level pixel transmission. Manufacturing facilities in Japan deploy this for secure CAD tool access without full desktop replacement.
- Session-based Virtualization:Shared server resources host concurrent user sessions through terminal services architecture, maximizing density for cost-sensitive deployments. Education sector buyers in India leverage this for computer lab standardization at minimal per-seat cost.
VDI retains the largest installed base among regulated industries. DaaS is climbing the fastest in commercial sectors prioritizing workforce mobility.
Deployment:
Cost tiering separates hyperscaler consumption from captive infrastructure, with hybrid architectures capturing premium pricing for workload portability.
- Public Cloud:Multi-tenant hyperscaler resources deliver elastic scaling with usage-based billing and managed security patching. Financial services firms in London adopt public cloud VDI for development environment agility while accepting shared-tenant compliance documentation.
- Private Cloud:Dedicated single-tenant infrastructure maintains physical isolation with customized security controls and sovereign data boundaries. German automotive suppliers deploy private cloud to satisfy GDPR Article 44 cross-border transfer restrictions.
- Hybrid Cloud:Orchestration layers distribute workloads across on-premise and cloud resources based on sensitivity, latency, and cost thresholds. This architecture commands implementation premiums for policy-driven workload placement.
- On-premises:Fully captive data center infrastructure preserves maximum control over hardware, network, and physical security boundaries. Government agencies in the US specify on-premise deployment for classified information processing under federal security requirements.
On-premises retains dominance in classified and regulated workloads. Hybrid Cloud is gaining share fastest as enterprises balance sovereignty with elasticity.
End User:
Volume concentration sits with large enterprises, while education and government segments drive standardization requirements that reshape product roadmaps.
- Large Enterprises:Multi-thousand seat deployments with dedicated IT operations teams and formal procurement processes. These buyers negotiate enterprise agreements with committed annual volumes and demand ISO 27001 certified delivery.
- Small Enterprises:Limited IT staff drives preference for fully managed services with minimal configuration overhead. Channel partners in Mumbai target this segment with packaged DaaS offerings.
- Education Sector:Extreme cost sensitivity and seasonal usage patterns favor session-based virtualization with shared resource pools. K-12 districts in Texas standardize on this model for standardized testing and computer lab access.
- Government Agencies:Mandatory compliance frameworks including FedRAMP, GDPR, and national security classifications dictate architecture choices. These buyers require documented data residency and encryption granularity.
Large Enterprises anchor current revenue. Government Agencies are expanding fastest as sovereign cloud mandates proliferate.
Solution:
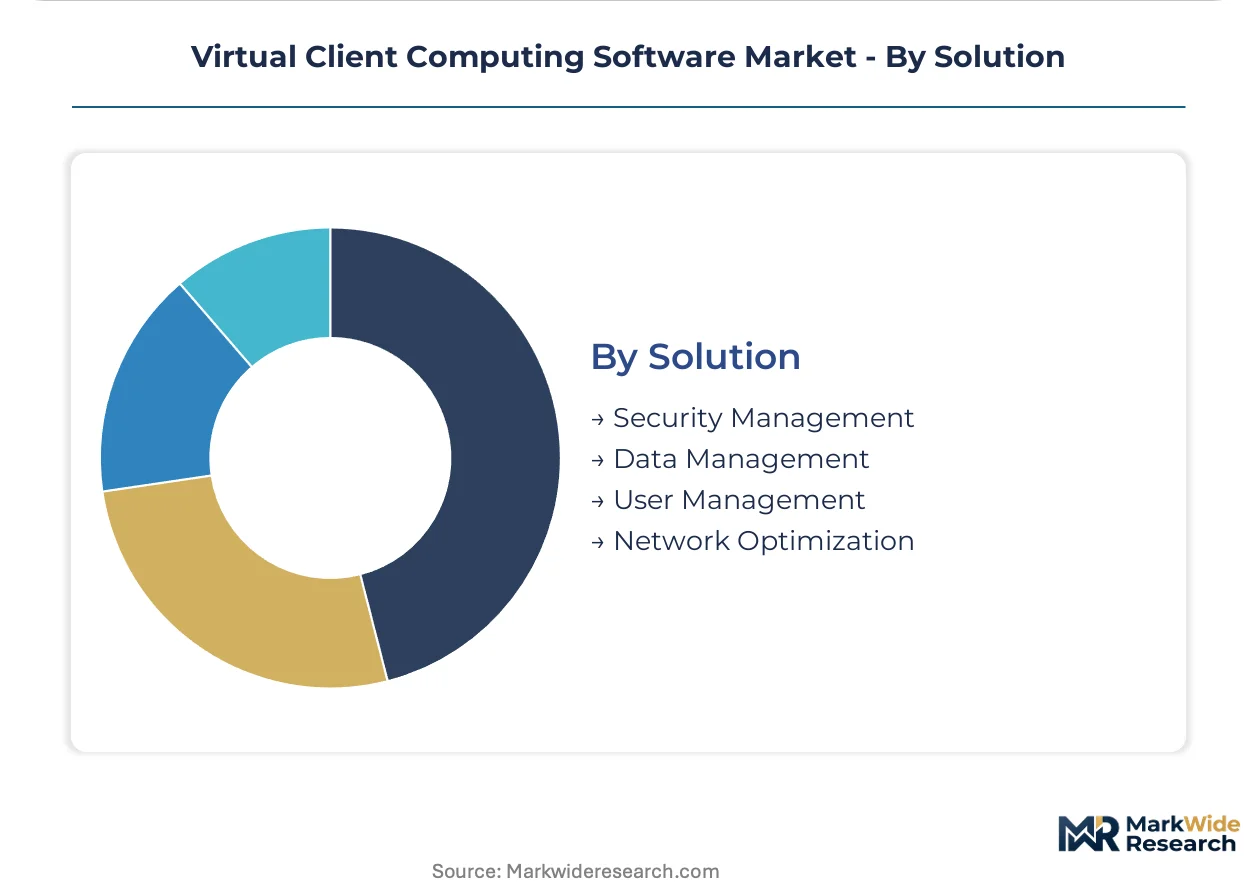
Application focus determines whether vendors capture infrastructure, security, or optimization spend within the virtual desktop stack.
- Security Management:Multi-factor authentication, conditional access policies, and endpoint detection integration protect against credential theft and session hijacking. This layer captures premium pricing as breach consequences escalate.
- Data Management:Profile containerization, application layering, and storage tiering maintain user state across sessions and devices. FSLogix and similar technologies reduce storage costs while improving logon performance.
- User Management:Identity federation, role-based access control, and self-service portals reduce administrative overhead for distributed workforces. Enterprises in the UK consolidate these functions under single sign-on architectures.
- Network Optimization:Adaptive codecs, bandwidth detection, and connection brokering maintain session quality over variable network conditions. This capability enables virtual desktop deployment across rural broadband and mobile networks.
Security Management commands the highest margin attachment. Network Optimization is rotating up the priority rankings as distributed workforces strain last-mile connectivity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Federal Office for Information Security anchors European demand through sovereign cloud mandates that reshape procurement across the continent. The EU AI Act and GDPR compliance frameworks concentrate investment in data-resident virtual desktop infrastructure. Country-level differentiation now determines vendor selection.
Germany
Automotive suppliers and healthcare networks drive demand for private cloud VDI under GDPR Article 44 cross-border restrictions. The BSI's IT-Grundschutz certification requirements filter vendor eligibility for federal contracts. Munich and Stuttgart clusters host sovereign cloud deployments for engineering workstation virtualization.
United States
Hospital systems and defense contractors sustain on-premise VDI dominance for HIPAA audit trails and classified data handling. FedRAMP authorization requirements constrain multi-tenant cloud adoption in federal agencies. Northern Virginia and Dallas-Fort Worth data center corridors expand hyperscaler capacity for hybrid virtual desktop orchestration.
France
Public sector digitization and financial services compliance accelerate sovereign cloud-hosted desktop deployments. ANSM and CNIL guidance on health data processing reinforces data localization requirements. Paris and Lyon financial districts consolidate vendor relationships under enterprise DaaS agreements with committed volumes.
India
IT services exporters and education institutions expand session-based virtualization for cost-sensitive scale deployments. The PLI scheme for data centers attracts hyperscaler investment in Mumbai and Chennai captive infrastructure. Bangalore and Hyderabad technology corridors consume GPU-partitioned virtual workstations for remote engineering delivery.
Japan
Manufacturing facilities deploy remote application access for secure CAD tool streaming without full desktop replacement. METI's cybersecurity framework for critical infrastructure shapes vendor certification requirements. Tokyo and Nagoya industrial clusters adopt GPU virtualization for remote workstation replacement at engineering headquarters.
Virtual Client Computing Software Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in virtual client computing software. Cloud hyperscalers and infrastructure incumbents capture premium pricing through bundled ecosystem delivery, while pure-play virtualization vendors compete on deployment velocity and workload-specific optimization. Two strategic archetypes dominate: platform consolidators integrating compute, storage, and brokering layers; and workload optimizers specializing in graphics-intensive or compliance-bound use cases. Competitive moves concentrate on hybrid cloud orchestration partnerships and sovereign cloud capacity expansion to satisfy data residency mandates.
Within the platform consolidator tier, Microsoft and Amazon Web Services anchor cloud-native delivery through hyperscale infrastructure integration. Dell occupies a position spanning endpoint hardware and VDI-optimized workstation portfolios. Nutanix exemplifies the hyperconverged infrastructure archetype that collapses compute-storage layers for streamlined mid-market deployment velocity.
| Leading Market Players |
|---|
| Cisco Systems |
| Dell |
| Microsoft |
| Nutanix |
| Hewlett Packard Enterprise Development |
| Broadcom |
| Amazon Web Services |
| Hitachi |
| Cloud Software Group |
| Others |
Cost & Logistics Intelligence
Ninety-day GPU provisioning lead times for NVIDIA vGPU silicon concentrate pricing power among hyperscaler integrators while compressing margins for mid-market channel partners lacking strategic inventory positions. This inventory tension separates vendors who can pre-position graphics virtualization hardware from those forced into spot-market premiums.
Pricing Analysis
German automotive suppliers pay 15-25% premiums over US healthcare buyers for equivalent private-cloud VDI capacity due to GDPR-mandated sovereign hosting requirements and localized engineering support. The market runs on subscription-tiered SaaS pricing stratified across premium sovereign-cloud, standard multi-tenant, and economy session-based tiers. Price differentiation rests on ISO 27001 certification grade and committed annual seat volume. Cost compression in the economy tier intensifies as Indian education sector buyers consolidate procurement under state-level frameworks. Small enterprises exhibit highest price sensitivity, while defense contractors accept premium pricing for FedRAMP-authorized delivery.
Supply Chain Analysis
Strategic stockpiling of GPU accelerators and hyperconverged nodes dominates vendor behavior, displacing just-in-time procurement as NVIDIA allocation uncertainty persists. Supply concentrates in Taiwan for GPU silicon, China for server motherboard assembly, and Ireland for EU sovereign cloud capacity. Raw material dependencies include high-bandwidth memory modules, specialized cooling refrigerants constrained by REACH regulations, and encryption-capable network processors. Single-source vulnerability in NVIDIA graphics virtualization silicon creates systemic risk for GPU-accelerated workloads. Distribution runs through hyperscaler direct sales organizations and London-based systems integrators serving regulated European buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The collapse of on-premise VDI administration expertise across North America and Western Europe creates a structural capability gap that favors ecosystem-integrated platform vendors over point-solution specialists. Organizations now purchase bundled competence rather than discrete software licenses.
For Market Incumbents: Consolidate broker service integration layers to capture Citrix migration cycles, locking in healthcare and financial services accounts facing forklift infrastructure replacement decisions. Deepen vertical integration into sovereign cloud capacity in Germany and France ahead of EU AI Act enforcement timelines. Channel control through certified managed service partnerships represents the critical defensive lever against hyperscaler direct engagement.
For New Entrants and Emerging Players: Anchor in India's PLI-driven data center corridor, where production-linked incentives create captive infrastructure cost advantages for session-based virtualization targeting education and IT services export segments. The most penetrable white-space sits with small enterprises in Mumbai and Chennai lacking dedicated IT operations. A packaged DaaS offering through local channel partners bypasses incumbent enterprise sales cycles.
For Investors and Strategic Acquirers: Long-term, this sits as a compliance-anchored infrastructure play because regulatory sovereignty mandates are permanently embedding virtual client computing into enterprise architecture. Target acquisition profiles emphasize managed service providers with ISO 27001 automation tooling and established BSI IT-Grundschutz certification pathways in Germany. The signal to watch is sovereign cloud capacity utilization rates crossing threshold levels that trigger hyperscaler regional expansion commitments.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Microsoft Azure Virtual Desktop ecosystem bundling captures healthcare migration from legacy Citrix environments under HIPAA pressure. |
| Geographic Expansion | Nutanix hyperconverged deployments in Mumbai and Chennai exploit India's PLI scheme for mid-market VDI velocity. |
| Strategic Partnership | Dell workstation-hardware integration with sovereign cloud providers satisfies German automotive GDPR Article 44 requirements. |
| Acquisition of Specialist Firm | FSLogix profile management capability commands premium valuations as IT administrator scarcity intensifies. |
| Product Launch | GPU-partitioned virtual workstations target Japan METI cybersecurity framework compliance for remote CAD delivery. |
Research Approach
The analysis maps Desktop as a Service, Virtual Desktop Infrastructure, session-based virtualization, and remote application access architectures, each validated through CTOs at large enterprises, IT procurement officers at healthcare networks, channel partners in London and Mumbai, platform engineers at hyperscalers, and integration specialists serving regulated financial services. Primary interview findings triangulate against SEC filings from infrastructure vendors, hyperscaler capex disclosures, GDPR enforcement action databases, and hospital procurement records. Bottom-up seat-count modeling reconciles with top-down addressable market sizing across deployment modes and end-user segments.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. The analytical framework models deployment mode, organization size, vertical industry, integration complexity, and regional regulatory adoption pattern as core segmentation dimensions. CAGRs derive from installed base evolution curves and replacement cycle analysis. Forecast inputs include GPU virtualization penetration rates in engineering workloads and sovereign cloud capacity buildout timelines in Germany and France.
Material uncertainties — regulatory enforcement intensity, GPU supply allocation shifts, and broadband infrastructure deployment pace — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding workforce mobility permanence and compliance framework harmonization. Revision becomes warranted when sovereign cloud capacity utilization crosses thresholds that trigger hyperscaler pricing recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Computer Backup Software Market
Software & Services
Global Investor Relationship Management Software Market
Software & Services
Supplier Quality Management Applications Market
Software & Services
Asia-Pacific Digital Signage Software Market
Software & Services
Computational Medicine and Drug Discovery Software Market
Software & Services
Preventive Maintenance Software Market
Software & Services
Social Software As a Collaborative ERP Tool Market
Software & Services
Global Decision Making Software Market
Software & Services
Ad Creation Software Market
Software & Services
Adaptive Learning Software Market
Software & Services
Global Cloud-Based Call Center Software Market
Software & Services
Cloud Business Process Management (BPM) Software Market
Software & Services
Email Optimization Software Market
Software & Services
Preschool Education Software Market
Software & Services
Network Bandwidth Management Software Market
Software & Services
Document Capture Software Market