
 Germany Geospatial Imagery Analytics Market | 2026-2036
Germany Geospatial Imagery Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Geospatial Imagery Analytics Market Insights
Buyer concentration among German municipal planning departments and federal environmental agencies is rebalancing toward cloud-based procurement frameworks. Hexagon AB leverages its sensor-to-software stack to anchor large-scale infrastructure monitoring contracts across German Länder. Esri Deutschland GmbH specializes in localized geospatial platform deployment, while Planet Labs PBC competes through high-frequency satellite revisit rates for agricultural clients in northern Germany.
Germany geospatial imagery analytics encompasses the extraction of spatial intelligence from remote sensing data through computational algorithms, processing spectral signatures from satellite, aerial, and LiDAR sources to generate actionable geographic information. Satellite imaging dominates current deployment volumes due to falling launch costs and expanding European Space Agency data access, while LiDAR maintains premium positioning in precision forestry and infrastructure corridor mapping where centimeter-scale elevation accuracy proves essential. Environmental assessment applications draw accelerating investment as German utilities and regulators mandate ecosystem monitoring for renewable energy siting compliance.
Germany's Federal Agency for Cartography enforces INSPIRE directive harmonization standards that dictate metadata interoperability across public-sector geospatial platforms. The Federal Data Protection Act and GDPR constrain cross-border imagery processing workflows, pushing vendors toward domestic cloud infrastructure certification. Stakeholders must weigh the trade-off between AI-enabled automated feature extraction capabilities and emerging EU AI Act transparency requirements for high-risk geospatial decision-support systems.
Market Dynamics
Cloud-native processing architectures are compressing deployment timelines for German municipal geospatial platforms, forcing legacy on-premise vendors to restructure service delivery models around domestic data residency requirements.
Growth Catalysts
- INSPIRE Directive harmonization:Metadata standardization mandates across German federal agencies are accelerating platform consolidation and interoperability investments.
- Precision agriculture:Satellite-based crop monitoring in Lower Saxony and Brandenburg is driving recurring subscription demand among large-scale farming cooperatives.
- LiDAR corridor mapping:Deutsche Bahn and Autobahn GmbH infrastructure digitization programs require centimeter-scale elevation datasets for predictive maintenance scheduling.
Market Restraints
- Domestic cloud certification costs:GDPR-compliant data center accreditation under Germany's Federal Data Protection Act adds 15-20% overhead to vendor operating expenses.
- Optical sensor supply concentration:German system integrators depend on single-source suppliers for high-resolution multispectral detectors, creating procurement vulnerability.
- AI Act transparency requirements:Automated feature extraction algorithms face documentation burdens that slow deployment of high-risk geospatial decision-support systems.
Strategic Opportunities
- Bavarian municipal digitization:Urban planning departments in Munich, Nuremberg, and Augsburg are tendering integrated satellite-analytics platforms for zoning compliance automation.
- EU Green Deal ecosystem monitoring:Renewable energy siting mandates require continuous vegetation and hydrology surveillance, opening recurring service contracts for environmental consultancies.
- Edge-AI and 5G convergence:Real-time imagery processing at cellular base stations enables low-latency disaster response coordination for German civil protection agencies.
Industry Challenges
- Geospatial data science talent scarcity:German universities produce insufficient graduates combining remote sensing expertise with machine learning implementation skills.
- Legacy CAD system integration:Municipal engineering departments resist migrating from established AutoCAD workflows to cloud-native geospatial platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Geospatial Imagery Analytics Market |
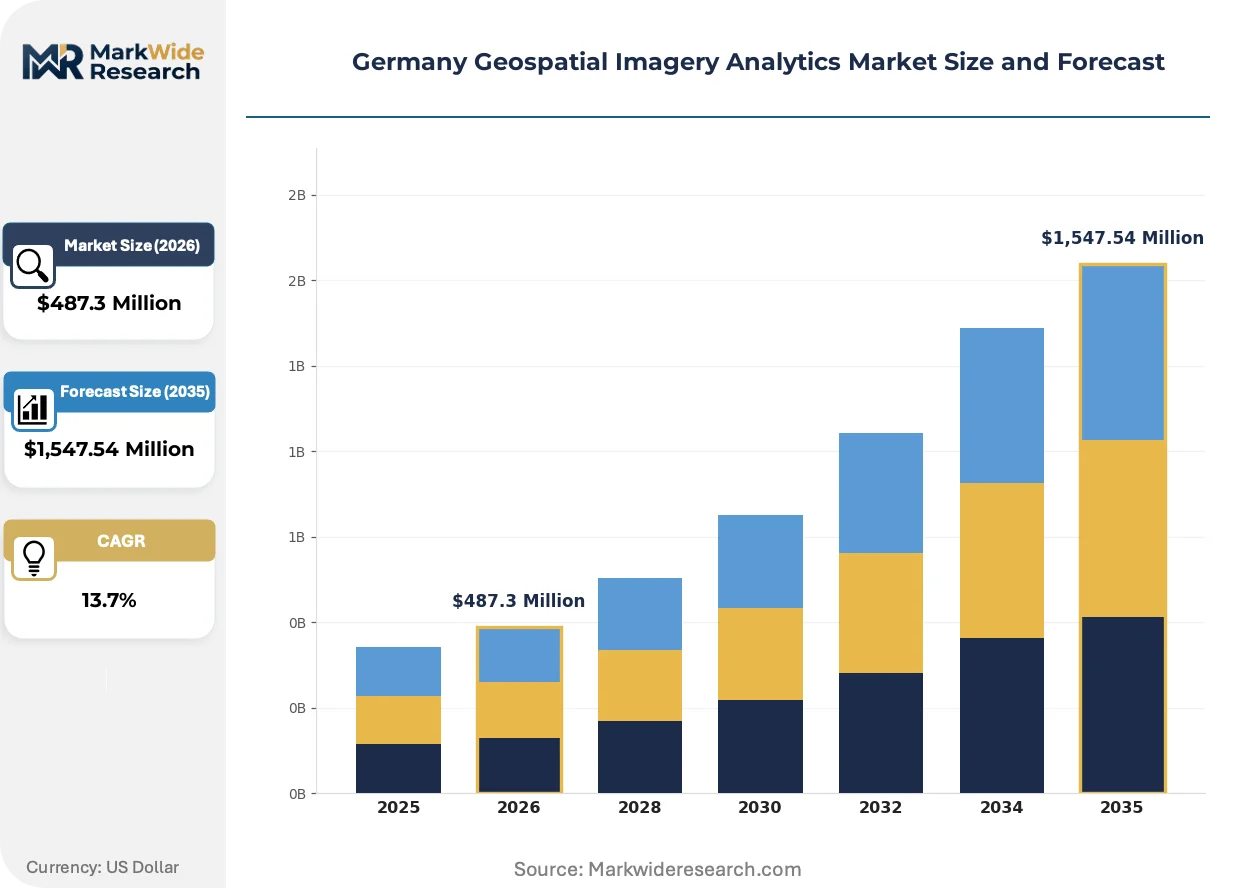
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,547.54 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: LiDAR, Photogrammetry, Satellite Imaging, 3D Mapping Application: Urban Planning, Agriculture Monitoring, Disaster Management, Environmental Assessment End User: Government, Research Institutions, Construction Companies, Transportation Deployment: Cloud-Based, On-Premises, Hybrid, Mobile |
| Companies Covered | TomTom International BV, Oracle Corporation, Hexagon AB, Maxar Technologies, BAE Systems, Esri Deutschland GmbH, Planet Labs PBC, Microsoft Corporation, Airbus SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Geospatial Imagery Analytics Market Trends and Innovations
Synthetic aperture radar interoperability standards are unlocking all-weather imaging capabilities that optical platforms cannot match, reshaping competitive positioning around sensor fusion architectures rather than single-source data provision.
Deep learning-based change detection algorithms are electrifying automated infrastructure monitoring workflows. German railway operators now process terabyte-scale archives to identify trackbed deformation patterns without manual image interpretation. This compression of analysis timelines from weeks to hours is enabling predictive maintenance contracts that were previously uneconomical.
The EU AI Act's risk-classification framework for geospatial decision-support systems is forcing vendors to restructure algorithm documentation and human-in-the-loop protocols. High-risk applications including automated building-permit screening now require conformity assessments that extend sales cycles. Bavarian planning departments are piloting hybrid workflows that preserve manual override capabilities to satisfy audit requirements.
Subscription-based platform access is displacing perpetual license arrangements across German public-sector procurement. Municipal IT departments favor operational expenditure models that bundle software, data, and processing into single vendor relationships. This preference shift concentrates contract value with integrated sensor-to-software providers and marginalizes standalone data resellers in northern Germany's agricultural analytics segment.
Germany Geospatial Imagery Analytics Market Segmentation
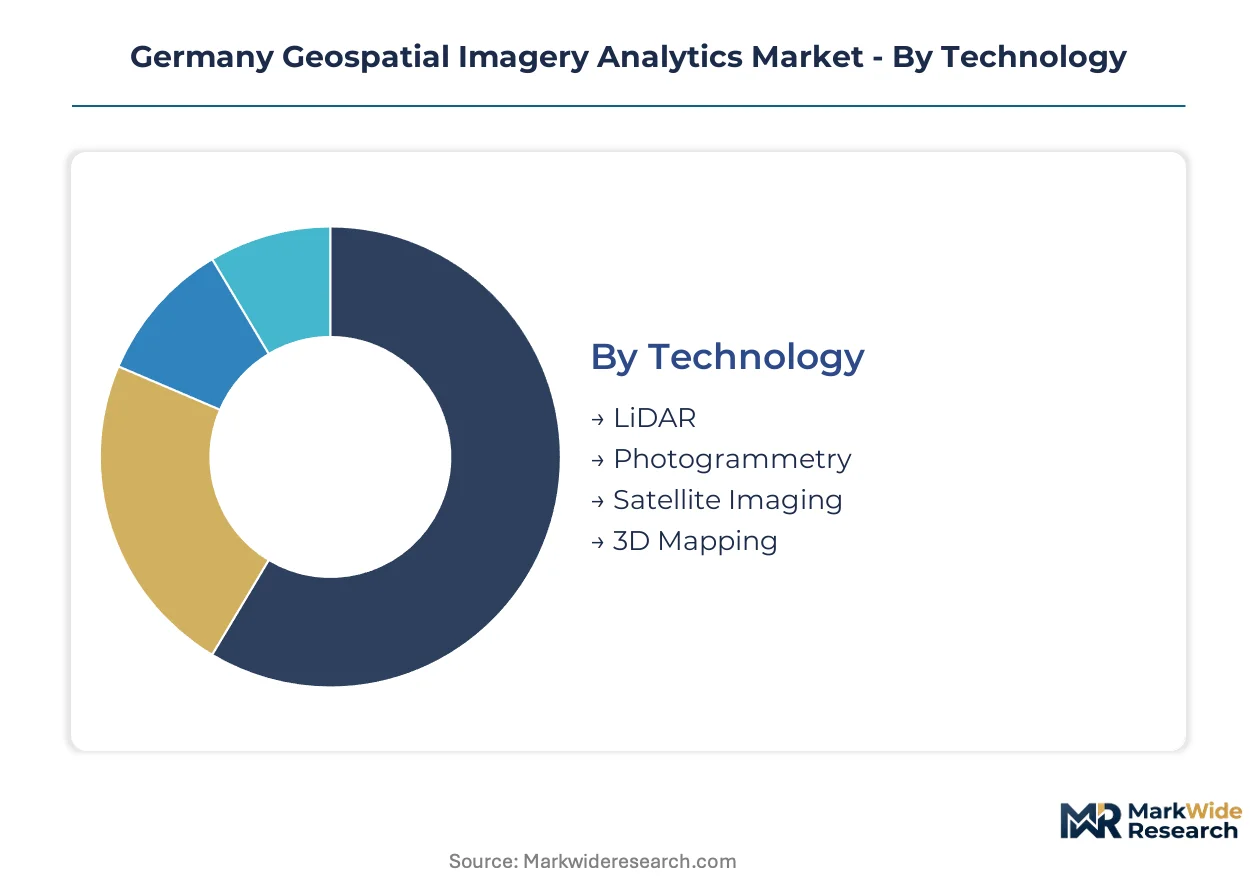
German procurement frameworks under the Federal Data Protection Act and INSPIRE directive create divergent compliance burdens across technology and deployment categories. Vendors must map segment-specific certification requirements to bid eligibility criteria.
Technology:
INSPIRE metadata harmonization and GDPR data residency rules impose distinct validation protocols on each sensing modality, with airborne platforms facing stricter Bundesamt für Kartographie accreditation than satellite-derived products.
- Satellite Imaging:Multispectral and synthetic aperture radar data streams from European Space Agency programs and commercial constellations. Procurement concentrates in Lower Saxony and Brandenburg farming cooperatives seeking subscription-based crop monitoring, with falling launch costs compressing per-kilometer pricing.
- LiDAR:Airborne laser scanning generating centimeter-scale elevation point clouds for corridor mapping. Deutsche Bahn and Autobahn GmbH infrastructure digitization mandates in Bavaria and North Rhine-Westphalia drive demand, though single-source detector supply creates procurement vulnerability.
- Photogrammetry:Aerial image triangulation for orthophoto generation and volumetric measurement. Municipal planning departments in Munich and Hamburg deploy these tools for zoning compliance automation under hybrid cloud-on-premise architectures.
- 3D Mapping:Integrated mesh generation combining multiple sensor inputs for digital twin construction. Urban modeling contracts in Nuremberg and Augsburg require Bundesamt für Kartographie interoperability certification.
Satellite Imaging sits at the top of the volume ranking, with LiDAR climbing the fastest.
Application:
End-use demand intensity correlates with regulatory enforcement timelines, where renewable energy siting mandates and railway safety directives concentrate near-term spending.
- Precision Agriculture:Satellite-based crop health monitoring, yield prediction, and input optimization for large-scale farming cooperatives. Subscription models dominate in Lower Saxony and Brandenburg, with automated feature extraction reducing manual interpretation overhead.
- Urban Planning:Zoning compliance, building permit screening, and infrastructure capacity modeling. Bavarian municipal governments in Munich, Nuremberg, and Augsburg tender integrated platforms requiring EU AI Act conformity assessments for automated decision-support.
- Environmental Assessment:Ecosystem monitoring for renewable energy siting compliance and habitat protection. German utilities mandate continuous vegetation and hydrology surveillance, opening recurring service contracts for environmental consultancies.
- Disaster Management:Flood inundation mapping, wildfire perimeter tracking, and post-event damage assessment. Civil protection agencies pilot edge-AI and 5G convergence for real-time coordination.
Urban Planning commands the largest contract values, though Environmental Assessment is expanding most quickly under EU Green Deal enforcement.
End User:
Budget cycle timing and procurement authorization thresholds segment buyer behavior, with federal agencies consolidating vendor relationships while municipal departments favor pilot-to-scale transitions.
- Government:Federal environmental agencies and Länder planning departments procuring through cloud-based frameworks. INSPIRE directive harmonization accelerates platform consolidation across Bundesamt für Kartographie-coordinated systems.
- Transportation:Deutsche Bahn and Autobahn GmbH infrastructure operators requiring predictive maintenance datasets. Centimeter-scale elevation accuracy specifications favor LiDAR corridor mapping contracts.
- Construction Companies:Earthwork volume calculation, site progress monitoring, and as-built documentation. Resistance to migrating from AutoCAD workflows slows cloud-native platform adoption.
- Research Institutions:Academic and applied research programs accessing European Space Agency data archives. Talent scarcity in combined remote sensing and machine learning expertise constrains project scaling.
Government accounts anchor procurement volume, with Transportation gaining share fastest through infrastructure digitization programs.
Deployment:
Data residency requirements and latency sensitivity determine architecture selection, with domestic cloud certification costs adding overhead that reshapes total cost of ownership calculations.
- Cloud-Based:Fully managed platforms with processing and storage on GDPR-compliant domestic infrastructure. Municipal IT departments favor operational expenditure models bundling software, data, and analytics.
- Hybrid:Sensitive data processing on-premise with archival and collaborative functions in certified cloud environments. Bavarian planning departments deploy this architecture to satisfy audit requirements while enabling inter-agency sharing.
- On-Premises:Legacy installations in defense and critical infrastructure settings requiring air-gapped security. Maintenance overhead and upgrade inertia marginalize this option outside classified applications.
- Mobile:Field-deployable tablets and drones with lightweight processing for real-time decision support. German civil protection agencies test 5G-enabled edge processing for disaster response coordination.
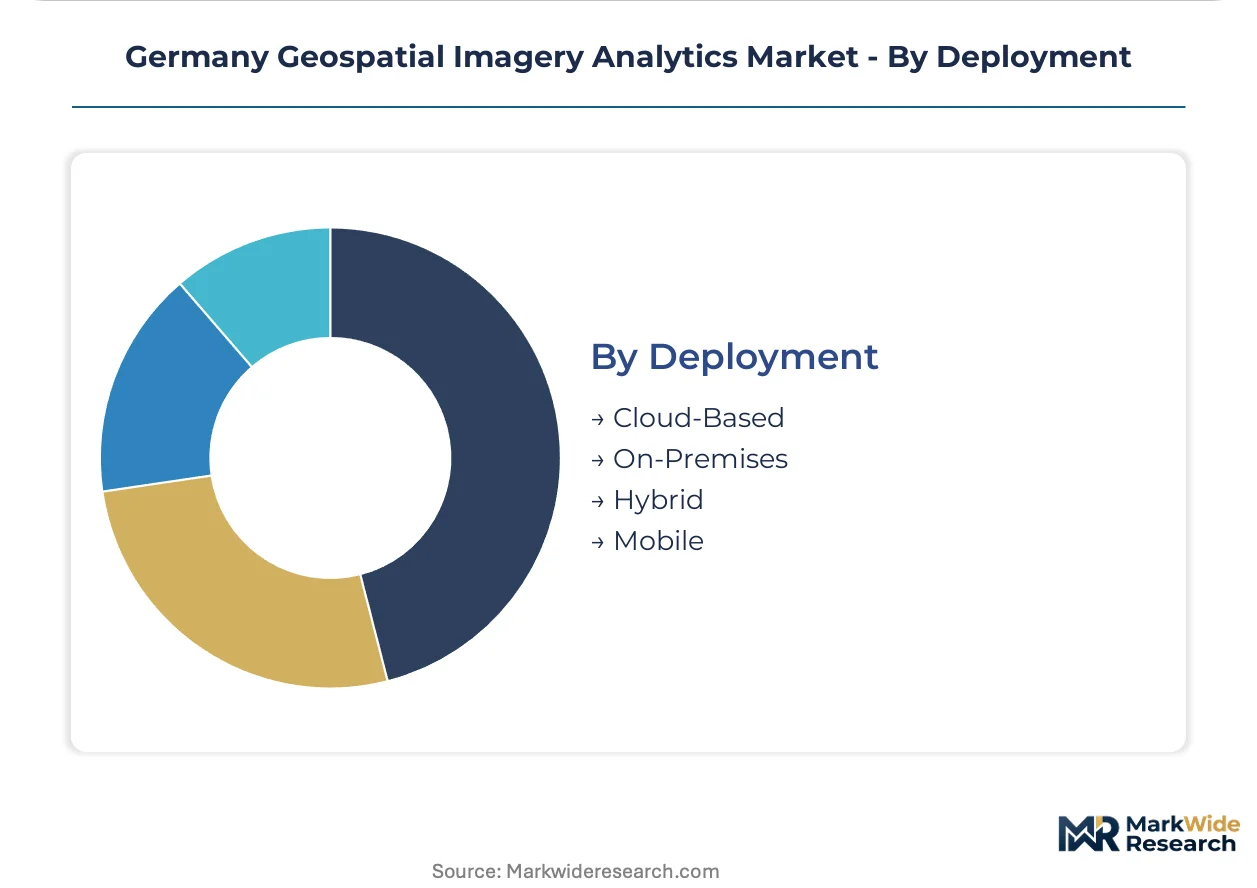
Cloud-Based deployment holds the dominant position, with Hybrid architectures showing the steepest expansion trajectory as departments balance compliance and collaboration needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany outpaces France in satellite-based agricultural analytics deployment, while the United Kingdom accelerates urban digital twin investments. Regulatory divergence across these three markets creates distinct vendor certification burdens.
Bavaria
Munich, Nuremberg, and Augsburg municipal governments tender integrated satellite-analytics platforms for zoning compliance automation. The Federal Data Protection Act and EU AI Act transparency requirements shape vendor selection criteria for automated building-permit screening. Bavarian infrastructure digitization programs favor hybrid cloud-on-premise architectures that preserve manual override capabilities.
Lower Saxony
Large-scale farming cooperatives drive recurring subscription demand for satellite-based crop health monitoring and yield prediction. INSPIRE directive metadata harmonization accelerates platform consolidation across regional agricultural data systems. The concentration of precision agriculture demand in Hanover and Braunschweig corridors attracts sensor-to-software providers seeking operational expenditure contracts.
North Rhine-Westphalia
Deutsche Bahn and Autobahn GmbH infrastructure operators require centimeter-scale elevation datasets for predictive maintenance scheduling. LiDAR corridor mapping contracts favor vendors with Bundesamt für Kartographie accreditation. The Cologne-Düsseldorf-Ruhr industrial belt concentrates demand for continuous vegetation and hydrology surveillance tied to renewable energy siting compliance.
Brandenburg
Environmental consultancies secure recurring service contracts for ecosystem monitoring under EU Green Deal enforcement timelines. Satellite imaging services dominate procurement volumes due to falling launch costs and expanding European Space Agency data access. The Berlin-Brandenburg metropolitan region pilots edge-AI and 5G convergence for real-time disaster response coordination.
Baden-Württemberg
Automotive and industrial machinery clusters generate demand for 3D mapping and digital twin construction in Stuttgart and Karlsruhe. GDPR-compliant domestic cloud infrastructure certification adds overhead to vendor operating expenses. Research institutions accessing European Space Agency data archives face talent scarcity in combined remote sensing and machine learning expertise.
Germany Geospatial Imagery Analytics Market Competitive Landscape
Swedish producers anchor one tier; American specialists hold high-frequency revisit capabilities. The vendor base concentrates around integrated sensor-to-software stacks and cloud-native platform providers. Three archetypes dominate: legacy mapping conglomerates with cartography heritage, satellite constellation operators with proprietary data streams, and enterprise software vendors embedding geospatial modules. Competitive moves center on domestic cloud infrastructure certification and AI Act conformity assessment acceleration.
Within the integrated platform tier, Hexagon AB and Esri Deutschland GmbH exemplify sensor-to-software consolidation strategies. Planet Labs PBC occupies a position among high-frequency data providers competing through revisit rate differentiation. These three entities represent the competitive spectrum from hardware-anchored systems to pure-play analytics subscriptions.
| Leading Market Players |
|---|
| TomTom International BV |
| Oracle Corporation |
| Hexagon AB |
| Maxar Technologies |
| BAE Systems |
| Esri Deutschland GmbH |
| Planet Labs PBC |
| Microsoft Corporation |
| Airbus SE |
| Others |
Pricing and Supply Chain Analysis
Geospatial data science talent concentration in Berlin-Brandenburg universities creates labor-cost differentials that widen pricing-tier spreads between premium sensor-to-software stacks and economy-grade analytics subscriptions.
Pricing Analysis
Capacity additions in French and Finnish commercial satellite constellations are reshaping price floors for multispectral imagery across German agricultural cooperatives. Subscription-based SaaS-tiered pricing dominates municipal procurement, with price differentiation driven by INSPIRE certification grade and volume-scale commitments. Cost compression in standard-tier crop monitoring intensifies because European Space Agency data access expands free baseline offerings. Small-scale farming cooperatives in Lower Saxony exhibit highest price sensitivity, while Deutsche Bahn infrastructure contracts show lowest sensitivity due to centimeter-scale accuracy requirements.
Supply Chain Analysis
High-resolution multispectral detector supply rests on single-source German and Japanese specialty sensor producers, creating procurement vulnerability for system integrators. Optical component sourcing draws from Germany, Japan, and the United States, while cloud processing infrastructure feeds from domestic GDPR-certified data centers. Tariff exposure on Japanese detector imports presents structural risk amid trade policy uncertainty. Distribution runs through Bundesamt für Kartographie-accredited system integrators serving Länder procurement frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, where EU AI Act enforcement timelines for automated geospatial decision-support systems accelerate platform replacement cycles.
For Market Incumbents: Cement domestic cloud infrastructure certification advantages to lock out non-compliant foreign competitors. Accelerate AI Act conformity assessment capabilities to extend sales cycle leads over emerging cloud-native entrants. Prioritize backward integration into synthetic aperture radar sensor production to reduce optical detector supply vulnerability.
For New Entrants and Emerging Players: Edge-AI processing modules for 5G cellular base stations offer a technology-first wedge into disaster response coordination contracts. Target Brandenburg environmental consultancies with lightweight subscription tools for EU Green Deal ecosystem monitoring. Pursue partnership-first go-to-market angles with established Bundesamt für Kartographie-accredited integrators to bypass lengthy certification timelines.
For Investors and Strategic Acquirers: Defense contractors seeking dual-use geospatial capabilities are the most active acquirer in this space. Five-to-ten-year viability hinges on regulatory compliance moats rather than raw technical differentiation. Acquisition target archetypes include mid-cap sensor-to-software specialists with existing INSPIRE certification. Watch EU AI Act high-risk system enforcement intensity as the key inflection signal for platform consolidation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Cloud Infrastructure Certification | GDPR-compliant data center accreditation locks out foreign competitors from German federal procurement. |
| AI Act Conformity Assessment Acceleration | Streamlined documentation protocols shorten sales cycles for automated building-permit screening platforms. |
| Sensor-to-Software Stack Integration | Combined hardware-software offerings capture operational expenditure contracts displacing standalone data resellers. |
| Edge-AI and 5G Convergence Development | Real-time processing at cellular base stations enables low-latency civil protection agency disaster response. |
| Synthetic Aperture Radar Capability Addition | All-weather imaging interoperability unlocks infrastructure monitoring contracts beyond optical platform limitations. |
Research Methodology
Bottom-up precision agriculture and urban planning modeling reconciled against top-down satellite constellation capacity tracking forms the analytical core. Primary interviews with municipal planning officers, federal environmental agency procurement leads, agricultural cooperative data managers, and Bundesamt für Kartographie certification specialists combined with secondary validation against European Space Agency program disclosures, INSPIRE directive implementation reports, German federal procurement databases, and EU AI Act regulatory filings. Triangulation between demand-side subscription data and supply-side launch manifests grounds volume estimates.
Historical trendline analysis across technology deployment trajectories and application penetration curves informs projection frameworks. Segmentation dimensions modeled include sensing modality, end-use application, deployment architecture, and Länder-level regulatory adoption patterns. CAGRs derive from fitted growth curves calibrated against infrastructure digitization program timelines and renewable energy siting mandate enforcement schedules. Forecast inputs incorporate Deutsche Bahn predictive maintenance contract awards and Bavarian municipal platform tender volumes.
The model holds under steady EU regulatory enforcement; deviation in AI Act risk-classification interpretations or INSPIRE harmonization delays would shift platform consolidation timelines. Forecasts reflect documented assumptions regarding cloud migration rates and satellite data cost curves. Regulatory uncertainty around cross-border imagery processing permissions and detector supply chain reshoring initiatives warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Geographic Information Systems (GIS)
Europe Geographic Information System (GIS) Market
Geographic Information Systems (GIS)
Cloud GIS Market
Geographic Information Systems (GIS)
Mobile Map Market
Geographic Information Systems (GIS)
Mobile Mapping Market
Geographic Information Systems (GIS)
India Location-Based Services Market
Geographic Information Systems (GIS)
Global GIS Market
Geographic Information Systems (GIS)
Business Mapping Software Market
Geographic Information Systems (GIS)
High Definition (HD) Maps Market
Geographic Information Systems (GIS)
Global GIS in Telecom Sector Market
Geographic Information Systems (GIS)
South Korea Location-Based Services Market
Geographic Information Systems (GIS)
India Satellite Imagery Services Market
Geographic Information Systems (GIS)
Japan Location-Based Services Market
Geographic Information Systems (GIS)
Electronic Cartography Market
Geographic Information Systems (GIS)
Germany Location-Based Services Market
Geographic Information Systems (GIS)
US Location-Based Services Market
Geographic Information Systems (GIS)
Sales Mapping System Market