
 IO-Link Technology Market | 2026-2036
IO-Link Technology Market Size, Share, and Industry Trends Forecast 2026-2036
IO-Link Technology Market Foresight
IEC 61131-9 certification for master-device interoperability is collapsing the vendor landscape, forcing smaller suppliers into compliance investments or exit. Siemens AG leverages its TIA Portal ecosystem to anchor premium pricing for integrated IO-Link master modules. Rockwell Automation, Inc. competes through its Logix platform, sustaining North American factory retrofit demand with embedded IO-Link configuration tools. Hans Turck GmbH & Co. KG dominates discrete sensor connectivity, specializing in compact M12 IO-Link hubs for space-constrained assembly stations.
IO-Link technology constitutes a standardized point-to-point serial communication protocol operating at 230.4 kbit/s over unshielded three-conductor cables, enabling bidirectional data exchange between sensors, actuators, and automation controllers. Its primary industrial purpose is delivering process data, service data, and event notifications from field devices to higher-level control systems without analog signal degradation. Wired IO-Link masters currently occupy the largest installed base, though wireless extensions are gaining traction in mobile robotics applications where cable fatigue limits operational uptime. Gateways represent a concentrated margin pool, as protocol translation between IO-Link and EtherNet/IP or PROFINET demands specialized ASIC development and firmware certification.
FCC Part 15 emissions rules in the United States constrain wireless IO-Link device architectures, while EU REACH compliance adds material disclosure burdens for connector housings and cable sheathing. Japan's METI safety standards for factory automation equipment create additional type-approval requirements for vendors targeting automotive end users. Stakeholders must monitor IEC standard revision cycles and semiconductor lead times as dual sourcing strategies for IO-Link transceiver chips become critical to production continuity.
Market Dynamics
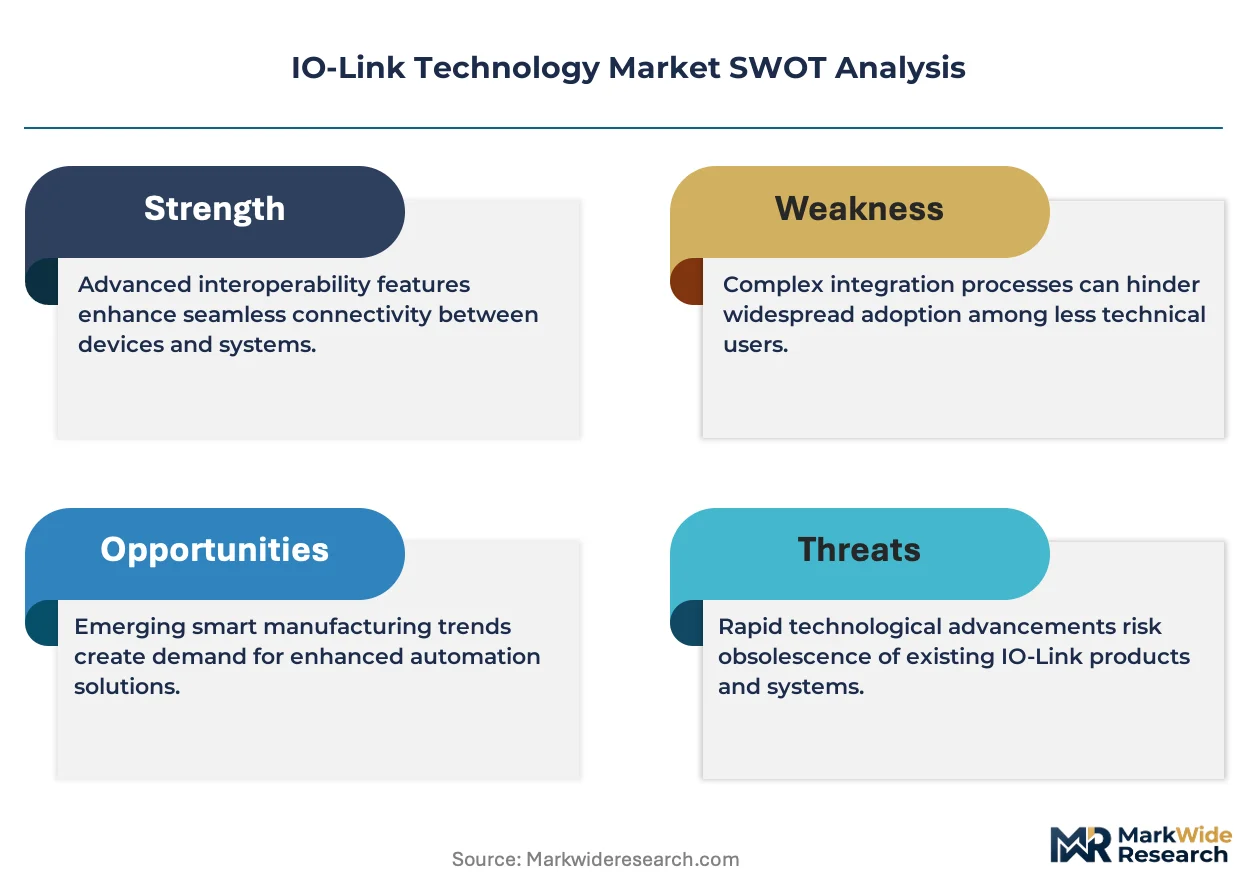
IEC 61131-9 compliance mandates are compressing the vendor landscape as master-device interoperability requirements force consolidation investments across component suppliers. Semiconductor lead times for IO-Link transceiver chips have extended sourcing cycles, amplifying dual-sourcing imperatives for production continuity.
Growth Catalysts
- Predictive maintenance mandates:Automotive assembly lines in Germany and Japan are mandating sensor-level diagnostics to minimize unplanned downtime. IO-Link's bidirectional data exchange enables condition monitoring without analog signal degradation.
- REACH compliance:EU material disclosure requirements for connector housings are accelerating replacement of legacy sensor networks with certified IO-Link devices that ship with full substance documentation.
- Smart factory retrofits:China's eastern manufacturing corridor is executing wholesale sensor network upgrades as municipal industrial policies prioritize digital transformation in legacy facilities.
Market Restraints
- ASIC development costs:Protocol translation gateways for EtherNet/IP and PROFINET demand specialized firmware certification that concentrates margin capture among semiconductor foundries with established automation relationships.
- FCC Part 15 constraints:United States emissions rules limit wireless IO-Link architectures to specific frequency bands, constraining antenna design flexibility for mobile robotics applications.
- Cable fatigue economics:Unshielded three-conductor cable replacement cycles in high-vibration environments create lifecycle cost penalties that favor wireless alternatives despite higher upfront hardware expense.
Strategic Opportunities
- Mobile robotics integration:Automated guided vehicle fleets in Japanese automotive plants are piloting wireless IO-Link extensions to eliminate cable maintenance overhead in continuous-loop operations.
- EU Green Deal alignment:Energy efficiency reporting requirements under CSRD are creating demand for IO-Link-enabled power monitoring at the sensor level to document Scope 2 emissions reductions.
- Convergence with 5G-TSN:Time-sensitive networking overlays on private cellular infrastructure are opening deterministic communication pathways that IO-Link masters can bridge to cloud analytics platforms.
Industry Challenges
- Embedded firmware expertise scarcity:IO-Link stack implementation requires specialized protocol engineering talent that concentrates in German automation hubs, constraining vendor expansion timelines.
- Legacy PLC integration friction:Retrofitting IO-Link masters into existing Siemens S7 or Rockwell ControlLogix architectures demands custom gateway configurations that extend commissioning cycles.
- Certification queue bottlenecks:Japan's METI type-approval process for factory automation equipment creates 6-12 month validation windows that delay product launches for automotive end-use targeting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IO-Link Technology Market |
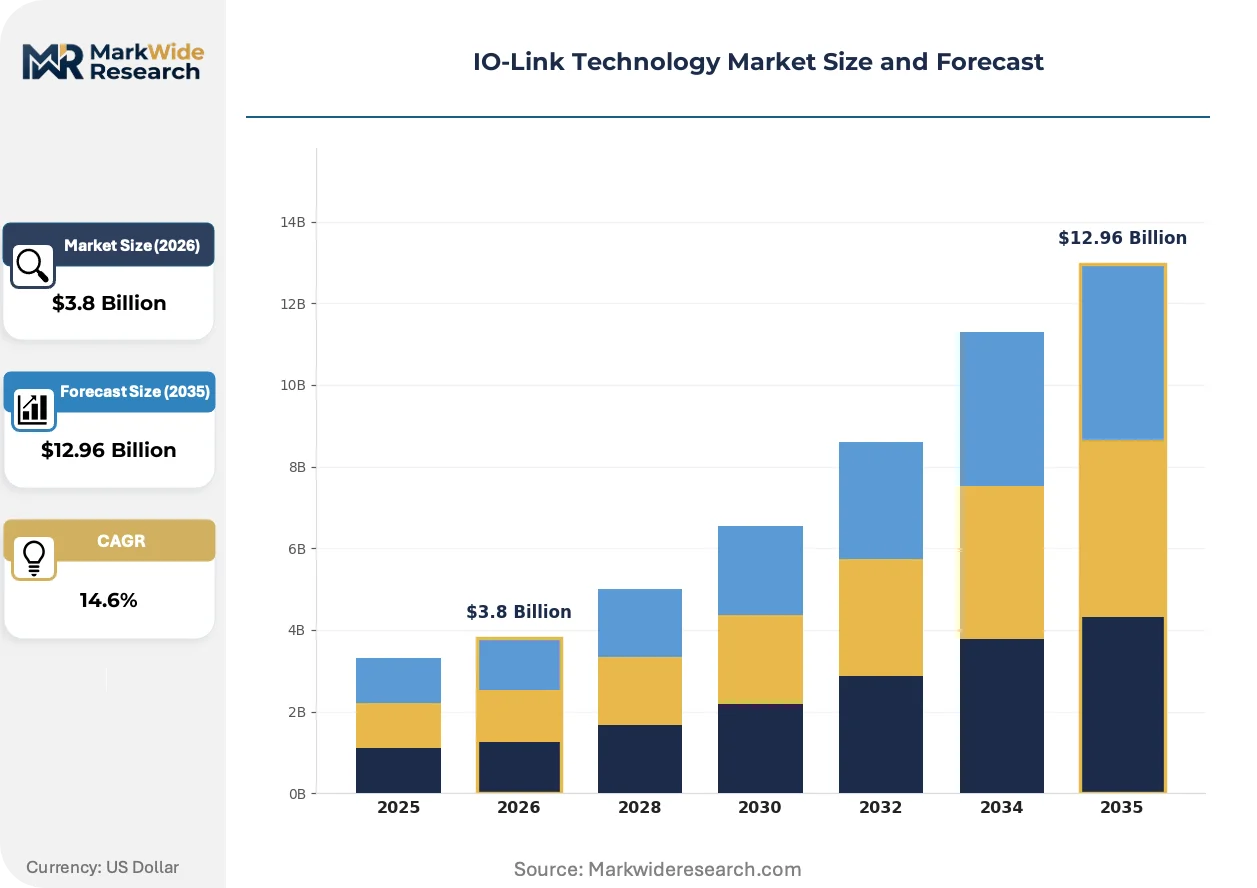
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sensor, Actuator, Gateway, Connector Technology: Wired, Wireless, Hybrid, Digital End User: Manufacturing, Automotive, Oil & Gas, Food & Beverage Application: Industrial Automation, Process Control, Robotics, Smart Grids |
| Companies Covered | Siemens AG, Rockwell Automation, Inc., OMRON Corporation, Hans Turck GmbH & Co. KG, Balluff GmbH, ifm electronic GmbH, Pepperl+Fuchs, SICK AG, Festo SE & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IO-Link Technology Market Shifts & Advancements
Wireless IO-Link extensions are migrating from pilot deployments to production architectures as cable fatigue costs accumulate in continuous-motion applications. Three interconnected developments are restructuring competitive positioning and procurement patterns.
Wireless IO-Link masters operating in the 2.4 GHz ISM band are supplanting wired configurations in mobile robotics cells where cable replacement downtime exceeds $50,000 per hour. Automotive tier-one suppliers in Stuttgart and Toyota City are deploying these units for tooling changeover stations. The shift is compressing maintenance staffing ratios while expanding addressable applications beyond fixed automation.
EU REACH substance disclosure rules are tightening material traceability requirements for M12 connector housings and cable sheathing compounds. Vendors must now document SVHC content across supply tiers to maintain CE marking eligibility. German sensor manufacturers are responding by qualifying alternative thermoplastic elastomers that reduce compliance documentation burden.
Sensor-as-a-service contracting is displacing capital purchase models for high-value IO-Link device installations. Machine builders in China's Yangtze River Delta are piloting per-output-unit pricing for vibration and temperature monitoring arrays. The model transfers obsolescence risk to component suppliers while aligning vendor incentives with uptime outcomes.
IO-Link Technology Market Segmentation
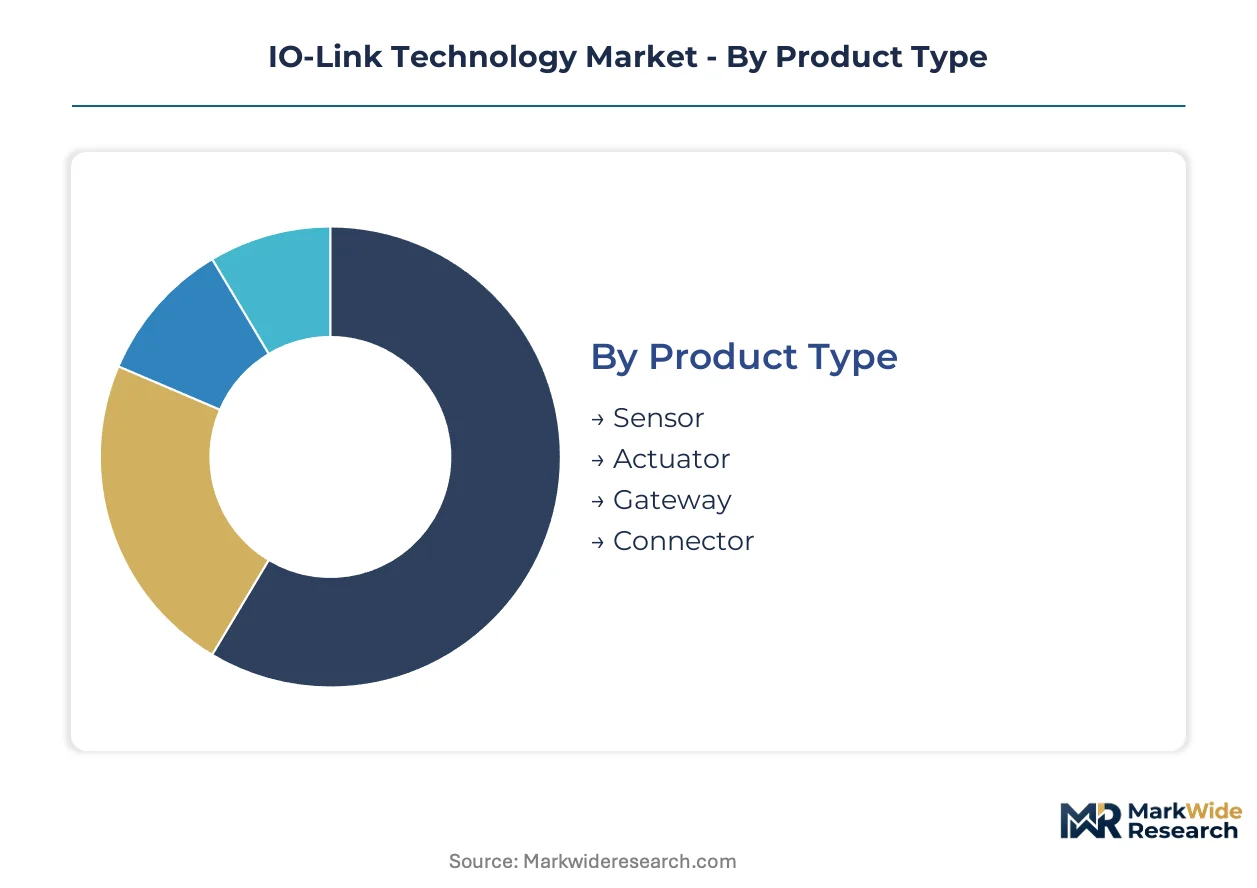
IO-Link technology segments according to four intersecting dimensions that determine procurement priorities, certification burdens, and integration complexity. Each category carries distinct regulatory footprints and margin structures that reshape vendor positioning.
Product Type:
EU REACH substance disclosure rules and IEC 61131-9 interoperability mandates create divergent compliance costs across hardware categories, concentrating margin capture among certified suppliers.
- Sensor:Photoelectric, proximity, and pressure variants dominate installed volume. German automotive plants in Stuttgart and Wolfsburg mandate sensor-level diagnostics for predictive maintenance, compressing replacement cycles and sustaining premium pricing for certified units with full SVHC documentation.
- Gateway:Protocol translation devices bridge IO-Link to EtherNet/IP, PROFINET, and Modbus TCP. ASIC development costs and firmware certification requirements concentrate production among semiconductor foundries with established automation relationships, creating margin pools that reward early certification investments.
- Actuator:Valve terminals and motor starters execute control commands from IO-Link masters. Demand concentrates in process industries requiring precise positioning feedback.
- Connector:M12 and M8 cable assemblies with IO-Link compatibility. Material traceability requirements for thermoplastic elastomers are accelerating qualification of alternative compounds.
Sensor modules handle the majority of throughput; Gateway is expanding most quickly on share as protocol convergence accelerates.
Technology:
Cost tier differentiation separates capital-intensive wired infrastructure from wireless alternatives carrying higher upfront hardware expense but reduced lifecycle maintenance.
- Wired:Standard point-to-point serial communication at 230.4 kbit/s over unshielded three-conductor cables. China's eastern manufacturing corridor executes wholesale retrofits of legacy analog networks, sustaining volume leadership despite cable fatigue penalties in high-vibration environments.
- Wireless:2.4 GHz ISM band extensions eliminating cable maintenance overhead. Japanese automotive plants in Toyota City pilot these units for automated guided vehicle fleets where continuous-loop operations exceed $50,000 per hour in downtime costs.
- Hybrid:Configurations combining wired backbone with wireless edge nodes. Appeals to facilities with mixed fixed and mobile automation requirements.
- Digital:Fully digital signal paths without analog conversion stages. Emerging architectures for greenfield smart factory deployments.
Wired configurations retain volume dominance; Wireless is climbing the fastest as cable replacement economics deteriorate.
End User:
Application maturity varies sharply by sector, with automotive and food processing presenting opposing regulatory and operational constraints.
- Automotive:Assembly line predictive maintenance mandates in Germany and Japan drive sensor network density requirements. METI type-approval processes create 6-12 month validation windows that delay product launches for equipment targeting this sector.
- Manufacturing:General industrial automation spanning discrete and process operations. China's Yangtze River Delta municipalities prioritize digital transformation subsidies for legacy facility upgrades.
- Oil & Gas:Hazardous area classifications demand intrinsically safe IO-Link variants with specialized housing and isolation requirements.
- Food & Beverage:Hygienic design standards and washdown compatibility constrain connector selection and material specifications.
Automotive absorbs the highest unit value per installation; Manufacturing represents the broadest addressable base.
Application:
Customer type segmentation reveals divergent procurement patterns between capital-project buyers and operational-technology managers with distinct budget cycles.
- Industrial Automation:Factory floor sensor-actuator integration for discrete manufacturing. German machine builders specify IO-Link masters embedded in TIA Portal ecosystems, anchoring premium pricing through configuration tool lock-in.
- Robotics:End-effector and joint-level feedback for collaborative and mobile systems. Cable fatigue in continuous-motion cells is accelerating wireless IO-Link adoption for tooling changeover stations.
- Process Control:Continuous manufacturing monitoring with emphasis on signal integrity and diagnostic depth.
- Smart Grids:Energy infrastructure sensor networks for distribution automation and condition monitoring.
Industrial Automation commands the largest deployment base; Robotics is gaining share fastest as mobile fleet expansion accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive manufacturers and industrial automation buyers concentrate procurement authority in Germany, Japan, and China, with regulatory compliance investments diverting budget toward certified IO-Link suppliers in each jurisdiction.
Germany
Stuttgart and Wolfsburg automotive clusters mandate sensor-level diagnostics for predictive maintenance on assembly lines. REACH substance disclosure rules from ECHA tighten material traceability for M12 connector housings. Bavarian machine builders specify IO-Link masters embedded in TIA Portal ecosystems, anchoring premium pricing through configuration tool lock-in.
Japan
Toyota City automotive plants pilot wireless IO-Link extensions for automated guided vehicle fleets where continuous-loop downtime exceeds $50,000 per hour. METI safety standards create 6-12 month type-approval validation windows for factory automation equipment. Chubu region suppliers concentrate embedded firmware expertise for IO-Link stack implementation.
China
Yangtze River Delta municipalities execute wholesale sensor network retrofits as industrial policies prioritize digital transformation in legacy facilities. MIIT standards alignment accelerates smart factory certifications for domestic equipment vendors. Shanghai and Suzhou machine builders pilot sensor-as-a-service contracting with per-output-unit pricing models.
United States
North American factory retrofit demand sustains volume for embedded IO-Link configuration tools in legacy PLC architectures. FCC Part 15 emissions rules constrain wireless IO-Link device architectures to specific frequency bands. Midwest automotive corridors and Gulf Coast process industries drive gateway demand for EtherNet/IP protocol translation.
Italy
Lombardy and Emilia-Romagna packaging machinery exporters integrate IO-Link sensors for food and beverage washdown compatibility requirements. CE marking eligibility demands full SVHC documentation across supply tiers. Turin-area automotive suppliers compress replacement cycles for certified units with alternative thermoplastic elastomer qualifications.
IO-Link Technology Market Competitive Landscape
Player mix skews toward diversified automation conglomerates with embedded configuration ecosystems and specialized sensor connectivity vendors with compact form-factor expertise. Market structure concentrates margin capture among semiconductor foundries with established firmware certification relationships and master-device suppliers with IEC 61131-9 compliance investments. Strategic archetypes include ecosystem-anchored platform vendors, discrete sensor specialists, and protocol translation gateway developers. Competitive moves center on dual-sourcing strategies for transceiver chip supply continuity and ASIC development partnerships for EtherNet/IP and PROFINET integration.
Within the ecosystem-anchored tier, Siemens AG and Rockwell Automation, Inc. represent platform vendors leveraging configuration tool integration to sustain premium positioning. Hans Turck GmbH & Co. KG exemplifies the discrete sensor specialist archetype, occupying a position concentrated on compact M12 hub form factors for space-constrained assembly stations. These three companies anchor the competitive structure, with Turck representing German sensor connectivity expertise against the diversified automation portfolios of Siemens and Rockwell.
| Leading Market Players |
|---|
| Siemens AG |
| Rockwell Automation, Inc. |
| OMRON Corporation |
| Hans Turck GmbH & Co. KG |
| Balluff GmbH |
| ifm electronic GmbH |
| Pepperl+Fuchs |
| SICK AG |
| Festo SE & Co. KG |
| Others |
Supply & Pricing Matrix
Long-term capacity reservation contracts with semiconductor foundries lock in IO-Link transceiver chip supply while fixing material cost exposure against volatile silicon wafer pricing. These arrangements anchor procurement visibility for German automation vendors navigating extended IEC 61131-9 certification cycles.
Pricing Analysis
Cost-plus contracts indexed to silicon wafer spot prices dominate IO-Link master module procurement between tier-one automotive assemblers and certified suppliers. Three-tier pricing structure across IEC 61131-9 certified premium, standard compliance-grade, and uncertified economy levels separates vendors by interoperability guarantee depth. Cost compression in economy-tier sensor modules is intensifying because Chinese domestic suppliers are qualifying alternative ASIC sources. Automotive OEMs in Stuttgart exhibit lowest price sensitivity due to unplanned downtime costs, while packaging machinery exporters in Italy face acute margin pressure from CE marking documentation burdens.
Supply Chain Analysis
Strategic stockpiling of IO-Link transceiver chips has displaced just-in-time preferences as semiconductor lead time volatility disrupts production continuity for master-device vendors. Supply concentrates in Taiwan for specialized ASIC fabrication, Germany for firmware-integrated modules, and China for connector assembly. Raw material dependencies span silicon wafers, thermoplastic elastomers for M12 housings, and copper for three-conductor cable sheathing. Single-source vulnerability in 40nm process node capacity at Taiwanese foundries threatens gateway production timelines. Distribution runs through authorized automation distributors with IEC certification audit requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wireless sensor networks and 5G-TSN convergence pose credible substitution threats to wired IO-Link architectures, forcing incumbents to defend installed base through protocol extension strategies.
For Market Incumbents: Secure dual-sourcing arrangements for IO-Link transceiver chips across Taiwanese and European foundries to eliminate single-source production risk. Deepen backward integration into firmware stack development to offset scarcity of embedded protocol engineering talent concentrated in German automation hubs. For New Entrants and Emerging Players: IEC 61131-9 fast-track certification through accredited test houses in Japan opens automotive supply chain access without 6-12 month METI validation delays. Target wireless IO-Link extension pilots in Japanese automated guided vehicle fleets where cable fatigue costs exceed $50,000 per hour. Pursue sensor-as-a-service contracting models in China's Yangtze River Delta to transfer obsolescence risk from capital-constrained machine builders. For Investors and Strategic Acquirers: Compact M12 hub specialists with established thermoplastic elastomer qualifications and full SVHC documentation represent prime acquisition targets as EU REACH compliance costs escalate. Long-term viability hinges on wireless protocol extension capabilities bridging to 5G-TSN infrastructure. Watch for inflection when private cellular network deployments in German automotive plants accelerate deterministic IO-Link-to-cloud pathways.| Strategic Initiative | Industry Significance |
|---|---|
| ASIC Dual-Sourcing Partnership | Eliminates single-foundry dependency for IO-Link transceiver supply continuity. |
| IEC 61131-9 Fast-Track Certification | Compresses validation windows for automotive supplier qualification in Japan. |
| Wireless Protocol Extension Development | Captures mobile robotics applications where cable fatigue limits uptime. |
| Sensor-as-a-Service Platform Launch | Aligns vendor economics with uptime outcomes in Chinese smart factory retrofits. |
| 5G-TSN Gateway Integration | Bridges deterministic field communication to cloud analytics platforms. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with automation engineering directors, plant maintenance managers, semiconductor procurement leads, and IO-Link master device product managers; and secondary validation through IEC standard revision documents, ECHA SVHC substance databases, METI type-approval registries, and SEC filings from listed automation conglomerates. Bottom-up sensor deployment estimates across German, Japanese, and Chinese automotive facilities were triangulated against top-down gateway revenue segmentation.
Across the projection horizon, the analytical framework modeled volume and value outputs through intersecting dimensions of product type (sensor, gateway, actuator, connector), technology tier (wired, wireless, hybrid, digital), end-use sector (automotive, manufacturing, oil and gas, food and beverage), and application (industrial automation, robotics, process control, smart grids). CAGRs were derived from regression analysis of historical sensor network upgrade cycles and municipal digital transformation subsidy trajectories. Forecast inputs incorporated semiconductor capacity expansion announcements and private 5G spectrum allocation timelines.
The analysis sits within stated boundaries; outcomes outside sustained automotive capital expenditure levels and stable semiconductor foundry utilization would require recalibration. Forecasts reflect assumptions regarding IEC standard stability, REACH substance list continuity, and absence of acute trade restrictions on ASIC components. Revision becomes warranted when wireless IO-Link pilot conversion rates in Japanese automotive plants cross commercial deployment thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Voice Sounders Market
Sensors
Automatic Number Plate Recognition (ANPR) Market
Sensors
Portable Iris Recognition Scanner Market
Sensors
Transportation Sensors Market
Sensors
Telemetric Devices Market
Sensors
IO Link Market
Sensors
Digital Olfaction Products Market
Sensors
Europe RFID Market
Sensors
Global Radio Frequency Identification (RFID) Smart Cabinet Market
Sensors
GNSS-Enabled Consumer Device Market
Sensors
Lidar in Construction Market
Sensors
Yield Monitoring Systems Market
Sensors
Asia Pacific RFID Market
Sensors
Digital Compass (E-Compass) Market
Sensors
Asset Tracking Market
Sensors
Indoor Location Market