
 Safety Motion Control System Market | 2026-2036
Safety Motion Control System Market Size, Share, and Industry Trends Forecast 2026-2036
Safety Motion Control System Market Outlook
Buyer concentration among tier-one automotive OEMs is expanding as vehicle electrification programs consolidate supplier rosters. Rockwell Automation Inc. leverages its integrated safety platform to anchor long-term contracts with North American automakers. Siemens AG competes through its TIA Portal ecosystem, which unifies safety and standard control architectures. ABB Ltd differentiates via its Ability Digital Powertrain, extending predictive maintenance into safety-critical motion loops.
A safety motion control system integrates servo drives, safety-rated encoders, and certified controllers to achieve SIL 3 or PLe performance levels per IEC 61800-5-2, ensuring machinery halts or maintains safe speed under fault conditions. The primary purpose is eliminating hazardous energy release during human-machine collaboration in automated production environments. Safety controllers currently occupy the largest product margin pool due to firmware complexity and recertification barriers, while robotics applications are outpacing machine tool deployments in absolute growth terms. Drive technology leads technology spending as motor-inverter integration reduces cabinet footprint and wiring points.
The European Machinery Directive, enforced through notified bodies under CE marking protocols, mandates validated safety functions for cross-border equipment placement. OSHA lockout-tagout standards in the United States and Japan's JIS B 9700 series for mechanical safety create parallel compliance obligations that shape regional product configurations. China's GB standards, administered by SAMR, are converging toward ISO harmonization, altering import certification pathways for foreign suppliers. Stakeholders must monitor whether functional safety certification becomes a procurement gate rather than a post-sale checkbox across industrial verticals.
Market Dynamics
Vehicle electrification programs in Germany and Japan are consolidating supplier rosters around integrated safety architectures, forcing machinery OEMs to recertify entire control ecosystems rather than retrofit legacy components. This structural pressure is compressing procurement cycles and elevating firmware complexity to a competitive differentiator.
Growth Catalysts
- IEC 62061 Compliance Mandates:European Union machinery OEMs face tightening functional safety requirements that invalidate legacy installations, creating replacement demand for SIL 3-certified architectures.
- East Asian Industrial Cluster Expansion:Manufacturing corridors in South Korea and coastal China are embedding safety-rated motion loops into new greenfield assembly lines.
- Servo-Motor Integration:Motor-inverter consolidation reduces cabinet footprint and wiring points, accelerating adoption in space-constrained automotive body shops.
Market Restraints
- Rare Earth Magnet Volatility:Neodymium supply concentration in Chinese processing facilities exposes drive manufacturers to input cost swings and export quota uncertainty.
- Recertification Barriers:Firmware updates trigger full SIL reassessment under IEC 61508, locking OEMs into incumbent suppliers and retarding competitive entry.
- Pneumatic Substitution in Light Loads:Low-force pick-and-place operations in consumer electronics assembly increasingly deploy air-driven actuators rather than electric servo systems.
Strategic Opportunities
- Indian Automotive Greenfield Investment:Tamil Nadu and Gujarat manufacturing hubs lack legacy safety infrastructure, permitting native SIL 3 deployment without migration costs.
- Predictive Maintenance Convergence:Integration of vibration analytics with safety-rated encoders enables condition monitoring without compromising functional safety integrity.
- Japan JIS B 9700 Harmonization:Alignment with ISO 13849-1 simplifies cross-border certification for suppliers targeting Japanese robotics OEMs.
Industry Challenges
- Functional Safety Engineer Scarcity:TÜV-certified professionals capable of SIL 3 validation command premium compensation and extend project timelines.
- Legacy Fieldbus Migration:PROFIsafe and CIP Safety protocols require hardware replacement in brownfield installations, disrupting production schedules.
- Intellectual Property Fragmentation:Encoder resolution algorithms and safety controller architectures are encumbered by overlapping patent estates across Japanese and European assignees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Safety Motion Control System Market |
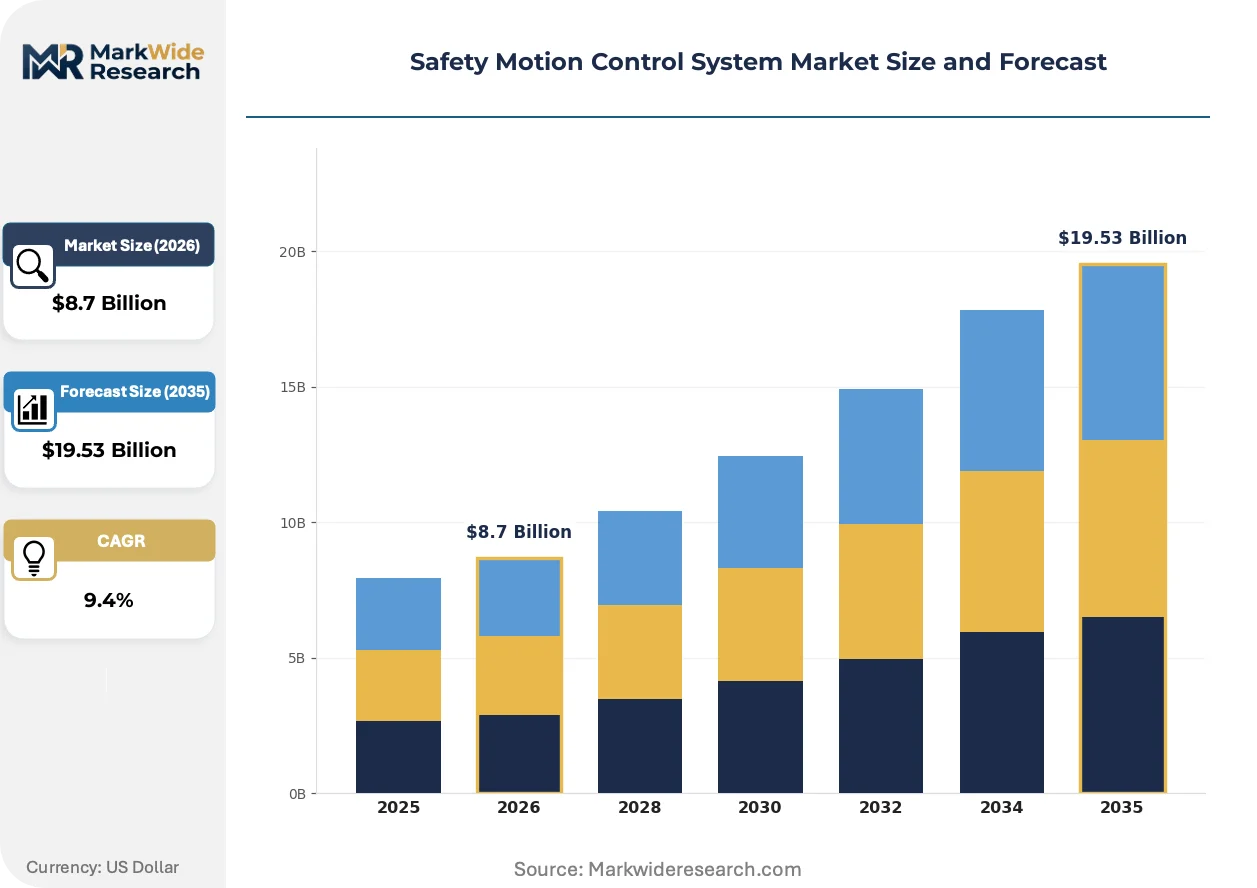
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Safety Sensors, Safety Controllers, Actuators, Safety Relays Application: Industrial Automation, Robotics, Packaging, Machine Tool Technology: Drive Technology, Control Technology, Feedback Systems, Networking End User: Manufacturing, Healthcare, Automotive, Aerospace |
| Companies Covered | Rockwell Automation Inc., ABB Ltd, Schneider Electric SE, Mitsubishi Electric Corporation, Siemens AG, Bosch Rexroth AG, Yaskawa Electric Corporation, FANUC Corporation, Omron Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Safety Motion Control System Market Strategic Shifts
Motion control architectures are shedding their historical separation between standard and safety-rated domains, compressing hardware layers and rewriting procurement specifications. This convergence is redrawing competitive boundaries between traditional automation suppliers and emerging integrated platform vendors.
Single-chip safety processors with embedded dual-core lockstep architecture are unifying SIL 3 logic execution and standard motion control on unified silicon. Automotive battery module assembly lines in South Korea are adopting these consolidated controllers to halve cabinet space. The technology is unifying what were previously distinct supplier relationships into sole-source platform commitments.
China's GB standards administered by SAMR are converging toward ISO 13849 harmonization, eliminating previous technical barriers to foreign equipment import. This regulatory alignment is forcing domestic Chinese machinery builders to redesign safety circuits for international certification equivalence. European suppliers targeting Chinese automotive joint ventures are accelerating localized firmware development to capture this transition window.
Automotive OEM procurement departments are compressing supplier qualification cycles from 18 months to 9 months as electrification timelines accelerate. Tier-one drivetrain manufacturers are displacing traditional distributor channels with direct engineering engagement models. This behavioral shift is most pronounced in German and Japanese automotive corridors where platform consolidation rewards early design-in commitment.
Safety Motion Control System Market Segmentation
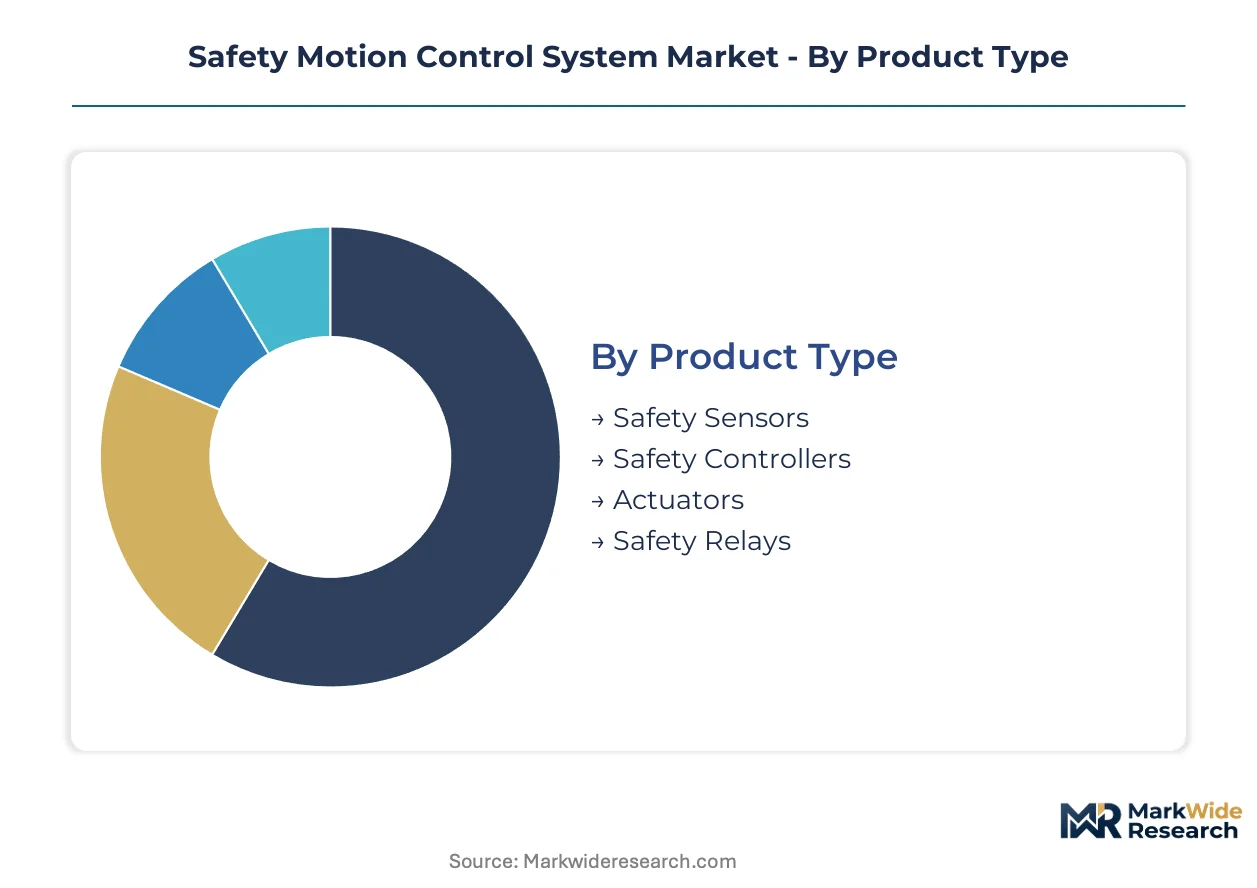
Segmentation in safety motion control systems reveals how technical specifications, application environments, and end-user compliance requirements fragment procurement patterns. Each axis carries distinct margin profiles and certification barriers that reshape supplier positioning across industrial verticals.
Product Type:
Technical sophistication and firmware complexity determine margin stratification across hardware categories.
- Safety Controllers:These units execute SIL 3 logic through dual-core lockstep processors with embedded diagnostic routines. Automotive assembly lines in Germany specify these for integrated safety architectures, with recertification barriers locking OEMs into incumbent suppliers.
- Safety Sensors:Photoelectric, laser scanner, and capacitive variants detect human presence in collaborative robot workspaces. Demand concentrates in South Korean battery module facilities where space constraints favor compact light curtain configurations.
- Actuators:Electromechanical safety-rated drives convert control signals into constrained mechanical motion under fault conditions.
- Safety Relays:These devices provide force-guided contact redundancy for emergency stop circuits in legacy machinery retrofits.
Mature deployment sits with Safety Relays in brownfield industrial sites. Newer deployment is concentrated in Safety Controllers within greenfield automotive electrification programs.
Application:
Operational tempo and human-machine proximity dictate performance requirements across use cases.
- Robotics:Collaborative and industrial robot installations require continuous position monitoring and safe torque-off capabilities per IEC 61800-5-2. Japanese automotive OEMs embed these systems in compact body shop cells where operators work inside robot envelopes.
- Industrial Automation:Conveyor systems, pick-and-place modules, and automated storage systems deploy distributed safety I/O architectures. Coastal Chinese manufacturing corridors drive volume for modular safety PLC configurations in electronics assembly.
- Packaging:High-speed carton handling and palletizing operations demand rapid safe stop response times under 250 milliseconds.
- Machine Tool:Milling centers and lathes integrate safe speed monitoring for spindle maintenance access modes.
Packaging applications retain the most standardized safety configurations. Robotics installations exhibit the steepest expansion trajectory as collaborative platforms penetrate assembly operations.
Technology:
Hardware integration intensity separates capital expenditure tiers across the technology stack.
- Drive Technology:Servo amplifiers and motor-inverter combinations with integrated safety functions reduce cabinet footprint and wiring complexity. German machinery OEMs specify these for automotive press lines where space optimization yields layout efficiency gains.
- Control Technology:Safety PLCs and dedicated safety processors execute certified function blocks for emergency stop, safe operating stop, and safely limited speed. Demand clusters in Tamil Nadu automotive greenfield sites lacking legacy infrastructure migration burdens.
- Feedback Systems:Safety-rated encoders and resolvers provide position verification for closed-loop motion control.
- Networking:PROFIsafe, CIP Safety, and FSoE protocols transmit safety data over standard industrial Ethernet.
Control Technology dominates replacement cycles in regulated European installations. Drive Technology commands the largest share of new capital deployment in East Asian greenfield construction.
End User:
Compliance stringency and operational risk profiles differentiate procurement specifications across verticals.
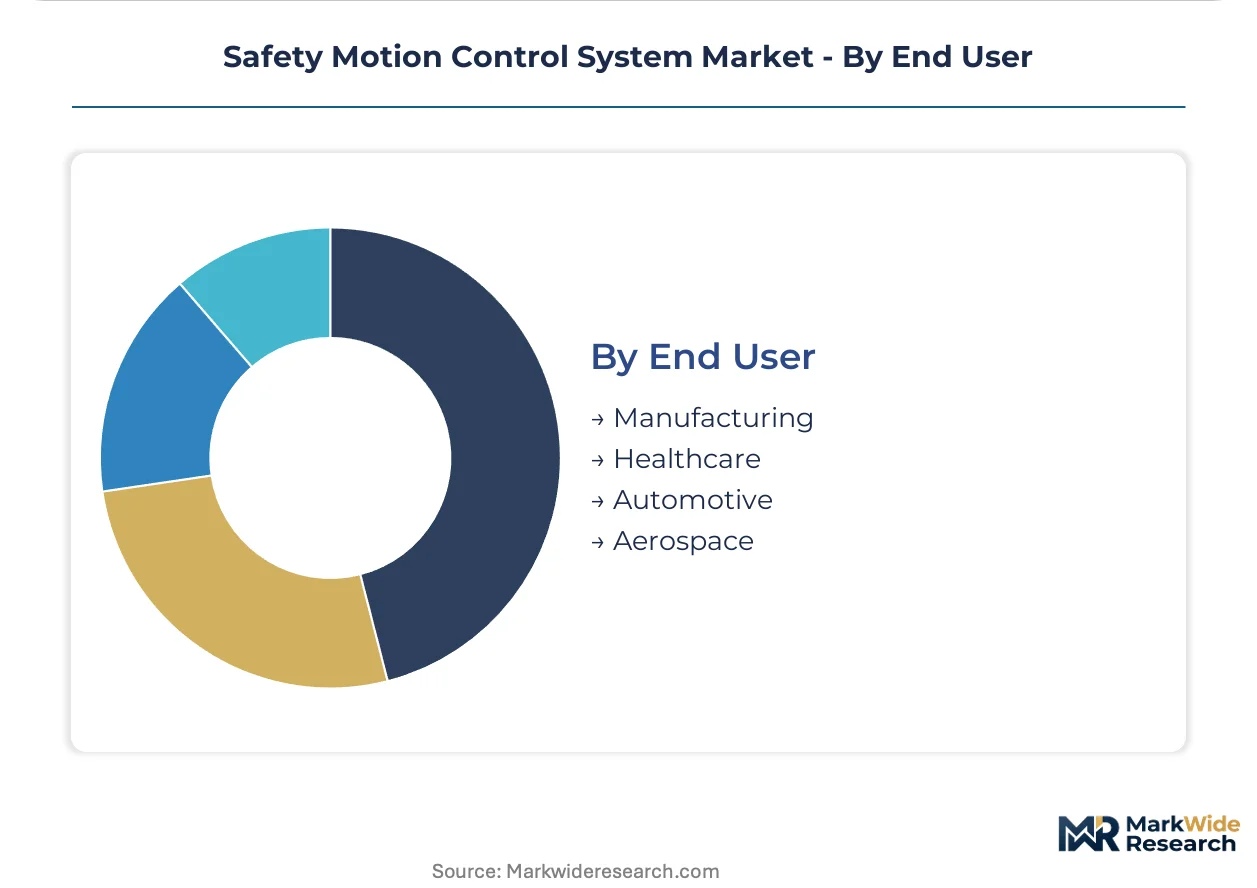
- Automotive:Vehicle electrification programs in Germany and Japan mandate SIL 3 architectures for battery module assembly and electric drivetrain production. Tier-one suppliers face compressed qualification cycles as OEMs consolidate platform sourcing.
- Manufacturing:General machinery builders across diverse industrial segments balance functional safety requirements against cost constraints. Chinese domestic equipment manufacturers accelerate adoption as GB standards converge toward ISO 13849 harmonization.
- Healthcare:Medical device manufacturing and hospital automation deploy safety systems under distinct risk management frameworks.
- Aerospace:Aircraft component machining and assembly operations impose additional traceability and documentation requirements beyond standard industrial safety mandates.
Healthcare maintains the most specialized certification pathways. Manufacturing presents the broadest addressable base as standardization reduces deployment friction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Neodymium processing concentration in Chinese facilities anchors supply-side geography for permanent magnet servo motors, while demand-side deployment clusters around German automotive electrification programs and East Asian battery manufacturing corridors.
Germany
Vehicle electrification programs at BMW and Volkswagen consolidate supplier rosters around SIL 3-certified architectures. The Machinery Directive enforced through CE marking protocols mandates validated safety functions for cross-border equipment placement. Stuttgart and Munich industrial clusters drive specification authority for automotive press line safety controllers.
China
Coastal manufacturing corridors in Jiangsu and Guangdong embed safety-rated motion loops into greenfield electronics assembly lines. GB standards administered by SAMR converge toward ISO 13849 harmonization, eliminating previous technical barriers to foreign equipment import. Shanghai automotive joint ventures accelerate localized firmware development to capture certification transition windows.
Japan
Collaborative robot installations in Toyota and Honda body shop cells require continuous position monitoring and safe torque-off capabilities. JIS B 9700 series standards for mechanical safety align with ISO 13849-1, simplifying cross-border certification pathways. Nagoya and Osaka industrial zones concentrate demand for compact safety sensor configurations.
United States
North American automakers specify integrated safety platforms for electric drivetrain production lines. OSHA lockout-tagout standards create parallel compliance obligations that shape regional product configurations. Michigan and Tennessee manufacturing hubs drive procurement for distributed safety I/O architectures in battery module assembly.
South Korea
Automotive battery module assembly lines adopt single-chip safety processors with embedded dual-core lockstep architecture. MFDS-equivalent industrial safety oversight operates through KOSHA for machinery certification. Gyeonggi-do and Ulsan industrial corridors concentrate greenfield deployment of consolidated motor-inverter safety systems.
Safety Motion Control System Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue integrated platform consolidation. The supplier base concentrates around three to five dominant automation conglomerates with cross-border certification authority. Strategic archetypes include integrated platform vendors unifying safety and standard control, component specialists defending encoder resolution franchises, and regional system integrators capturing localized compliance expertise. Competitive moves center on sole-source platform commitments through early design-in engagement and firmware localization for regulatory transition windows.
Among German-based industrial automation conglomerates, Siemens AG and Bosch Rexroth AG exemplify integrated platform vendors with unified safety and motion control ecosystems. Rockwell Automation Inc. represents North American anchor positioning through direct OEM engineering engagement. Japanese specialists including Yaskawa Electric Corporation and Mitsubishi Electric Corporation occupy positions within the precision servo and robotics safety tier.
| Leading Market Players |
|---|
| Rockwell Automation Inc. |
| ABB Ltd |
| Schneider Electric SE |
| Mitsubishi Electric Corporation |
| Siemens AG |
| Bosch Rexroth AG |
| Yaskawa Electric Corporation |
| FANUC Corporation |
| Omron Corporation |
| Others |
Value Chain & Pricing Dynamics
Motor-inverter consolidation into single-axis servo drives is compressing hardware layers and simultaneously shifting procurement economics toward firmware-intensive suppliers with captive silicon development. This technical transition concentrates pricing power among semiconductor-integrated automation vendors while exposing tier-two drive manufacturers to margin erosion from input cost volatility.
Pricing Analysis
Warranty and firmware-update bundling separates premium-tier safety controller suppliers from unbundled component vendors serving cost-sensitive machinery retrofit markets. Pricing stratifies across SIL 3-certified integrated platforms, modular safety PLC configurations, and discrete safety relay replacements. Cost compression in discrete component tiers is intensifying because pneumatic substitution in light-load electronics assembly erodes electric servo addressable volume. Chinese domestic equipment manufacturers exhibit highest price sensitivity due to GB standard convergence pressures, while German automotive OEMs prioritize design-in commitment over unit economics.
Supply Chain Analysis
Neodymium magnet supply rests on Chinese rare earth processing concentration, Japanese advanced ceramic substrate production, and German precision winding equipment fabrication. Safety-rated encoder manufacturing draws from Japanese optical component specialists, Swiss MEMS foundries, and Taiwanese semiconductor packaging facilities. Single-source vulnerability concentrates in Chinese rare earth export quota administration. Distribution runs through direct OEM engineering engagement models displacing traditional industrial distributor channels in German and Japanese automotive corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Single-chip safety processors with embedded dual-core lockstep architecture are displacing discrete safety controller and standard motion control hardware stacks, compressing supplier relationships and rewriting procurement specifications.
For Market Incumbents: Deploy firmware localization investments to capture Chinese GB standard harmonization transition windows before domestic competitors achieve certification parity. Anchor sole-source platform commitments through early design-in engagement with German and Japanese automotive OEMs consolidating electrification supplier rosters. Vertical integration into safety-rated encoder resolution algorithms defends against emerging Asian component specialists patenting around legacy European assignee estates. For New Entrants and Emerging Players: Capture Tamil Nadu and Gujarat automotive greenfield sites lacking legacy safety infrastructure migration burdens, where native SIL 3 deployment avoids incumbent recertification lock-in. Target Indian machinery OEMs with predictive maintenance convergence offerings integrating vibration analytics with safety-rated feedback systems. Pursue direct engineering engagement models bypassing distributor channel margin extraction. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated automation conglomerates seeking to fill safety motion control portfolio gaps. Long-term viability favors suppliers with certified firmware platforms and cross-border regulatory authority spanning IEC, ISO, and converging GB standard regimes. Watch JIS B 9700 harmonization completion as signal for Japanese robotics OEM procurement specification standardization enabling scale economics.| Strategic Initiative | Industry Significance |
|---|---|
| Firmware Localization Investment | Captures Chinese GB standard convergence transition before domestic competitors achieve parity. |
| Safety-Rated Encoder Backward Integration | Defends resolution algorithm franchises against emerging Asian component patent circumvention. |
| Direct OEM Engineering Engagement | Displaces distributor channels as German and Japanese automakers compress qualification cycles. |
| Predictive Maintenance Convergence | Integrates vibration analytics with SIL 3 feedback systems for condition monitoring differentiation. |
| Single-Chip Safety Processor Development | Unifies lockstep architecture and motion control on unified silicon for cabinet space reduction. |
Study Parameters
Document review covered IEC 61800-5-2 certification databases, SAMR GB standard harmonization notices, and automotive OEM electrification procurement specifications, complemented by interviews with plant engineers at German press line operators, Tier 1 supplier procurement teams in Japanese automotive corridors, and safety controller firmware developers. Secondary validation drew from SEC filings of listed automation conglomerates, TÜV certification registries, and customs trade data for servo drive component flows. Bottom-up installation counts and top-down industrial automation capex allocations were triangulated to establish market sizing.
Historical certification velocity was cross-referenced against expert panel input on electrification program timelines to derive expansion trajectories across the projection horizon. Segmentation modeling incorporated product type hierarchies, application environments, technology integration intensity, and end-user compliance stringency. CAGRs were derived from installed base turnover rates and greenfield construction pipelines. Forecast inputs included neodymium price volatility assumptions and TÜV-certified functional safety engineer availability constraints.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Chinese rare earth export policy shifts and Japanese-European patent estate litigation developments. Forecasts reflect documented assumptions regarding IEC 62061 enforcement intensity and automotive electrification program consolidation pace. A small set of named triggers warrants ongoing watch: JIS B 9700 harmonization completion, SAMR GB standard implementation deadlines, and single-chip safety processor adoption inflection in South Korean battery module assembly.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Wireless Occupancy Sensors Market
Sensors
Digital Compass (E-Compass) Market
Sensors
Global Load Monitoring System (LMS) Market
Sensors
IO-Link Technology Market
Sensors
Machine Health Monitoring Market
Sensors
Vision Positioning System Market
Sensors
Mobile Mapping Systems Market
Sensors
Vibration Monitoring Market
Sensors
Voice Sounders Market
Sensors
Underground Utility Mapping Market
Sensors
Near Field Communication (NFC) Tags Market
Sensors
Body Area Network Market
Sensors
Global Remote Tank Monitoring System Market
Sensors
Asset Tags Market
Sensors
Indoor Positioning and Navigation Market
Sensors
RFID Smart Cabinet Market