
 Cloud Analytics Market | 2026-2036
Cloud Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Analytics Market Intelligence
Data engineering talent scarcity is reorganizing how enterprises contract for analytics capabilities, forcing greater reliance on managed services and platform ecosystems. Microsoft leverages its Azure Synapse and Fabric portfolios to anchor enterprise data estates across hybrid environments. Amazon Web Services sustains momentum through Redshift and QuickSight integrations that dominate cloud-native data warehousing spend. Google competes on AI-infused analytics, differentiating BigQuery with embedded Gemini capabilities that reduce query complexity for business users.
Cloud analytics denotes the delivery of data processing, statistical modeling, and business intelligence functions through remote, elastic infrastructure operating on shared or dedicated server clusters with sub-second query response thresholds. Its primary commercial purpose is to transform raw operational data into actionable intelligence without capital-intensive on-premises hardware. Hybrid cloud deployments now capture the largest share of enterprise commitments as organizations balance latency-sensitive workloads against burst capacity needs. Predictive analytics and real-time analytics represent the fastest-expanding solution types, with financial services and telecom operators driving demand for streaming anomaly detection and dynamic customer scoring.
FDA guidelines on algorithmic transparency for healthcare analytics, EU AI Act risk classifications for automated decision systems, and SEC disclosure rules on material cybersecurity incidents collectively elevate governance requirements across cloud analytics procurement. These frameworks compel vendors to embed audit trails, explainability modules, and data residency controls directly into platform architectures. Stakeholders must evaluate whether their current cloud analytics contracts anticipate forthcoming algorithmic accountability mandates before renewal cycles lock in multi-year obligations.
Market Dynamics
Hybrid cloud architectures dominate enterprise commitments as organizations reconcile latency-sensitive workloads against elastic burst capacity, forcing vendors to engineer seamless data sovereignty controls across distributed infrastructure.
Growth Catalysts
- EU AI Act compliance mandates:European banks and insurers require governed, auditable cloud analytics architectures with embedded explainability modules and algorithmic transparency controls.
- Real-time streaming analytics:Telecom operators deploy sub-second anomaly detection for network optimization and dynamic customer scoring across 5G infrastructure.
- Defense sector modernization:United States federal cloud smart directives sustain large-scale deployments with stringent data residency and security classification requirements.
Market Restraints
- Specialized data engineering talent scarcity:Shortage of professionals skilled in distributed query optimization and lakehouse architecture limits platform adoption velocity.
- Cross-border data transfer friction:GDPR territorial restrictions and Schrems II rulings complicate multi-region analytics deployments for multinational enterprises.
- Legacy system integration complexity:Proprietary on-premises data warehouses resist API-native connectivity, extending migration timelines and inflating professional services costs.
Strategic Opportunities
- FDA algorithmic transparency pathways:Healthcare providers seek compliant cloud analytics platforms for clinical decision support with embedded audit trails and model documentation.
- Edge-to-cloud analytics convergence:Manufacturing facilities combine IoT sensor streams with centralized machine learning training for predictive maintenance at scale.
- SEC cybersecurity disclosure rules:Public companies require incident response analytics with automated materiality assessment and board-level reporting capabilities.
Industry Challenges
- Query performance engineering expertise:Organizations struggle to optimize cost-performance ratios across serverless and provisioned compute tiers in multi-engine environments.
- Multi-cloud governance standardization:Divergent IAM frameworks and metadata protocols across hyperscaler platforms complicate unified data catalog implementation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Analytics Market |
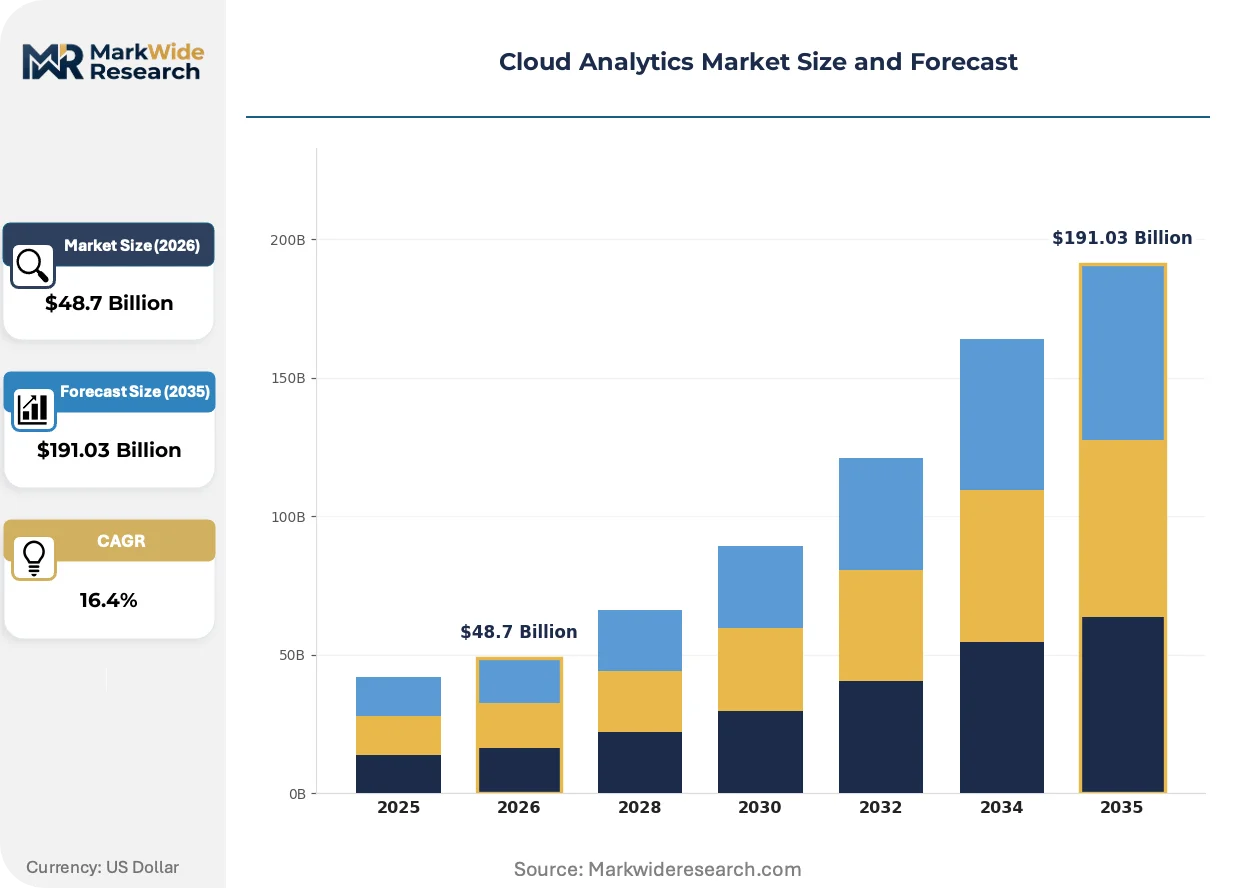
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $191.03 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Community Cloud Solution Type: Data Visualization, Predictive Analytics, Data Warehousing, Real-Time Analytics, Customer Analytics Use Case: Risk Management, Fraud Detection, Customer Segmentation, Supply Chain Optimization, Demand Forecasting End User Industry: BFSI, Telecom, Manufacturing, Government, Media & Entertainment |
| Companies Covered | Microsoft, Amazon Web Services, Google, IBM, Oracle, SAP, Salesforce, SAS Institute, Teradata, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Analytics Market Strategic Shifts & Innovations
Natural language interfaces and embedded generative capabilities are compressing the technical barrier between raw data assets and business decision-makers, reconstituting platform value around accessibility rather than infrastructure scale alone.
Large language model integration into SQL generation and data visualization is bifurcating the analytics vendor landscape. Business users at financial services firms now construct complex queries through conversational prompts, bypassing traditional BI specialist intermediaries. This capability compression threatens incumbent differentiation rooted in query optimization engines while elevating platforms with superior semantic layer architecture.
The EU AI Act risk classification framework for automated decision systems imposes documentation and human oversight obligations on high-risk deployments. Cloud analytics vendors must embed model cards, bias detection, and intervention mechanisms directly into platform workflows. European banking and insurance procurement teams now mandate these capabilities as table stakes for vendor qualification.
Consumption-based pricing with granular resource attribution is displacing fixed-capacity licensing across enterprise data warehousing contracts. Procurement teams at North American retailers and healthcare systems negotiate spend-commitment structures tied to actual compute utilization rather than provisioned clusters. This shift transfers infrastructure risk to vendors while demanding sophisticated cost governance tooling from buyers.
Cloud Analytics Market Segmentation
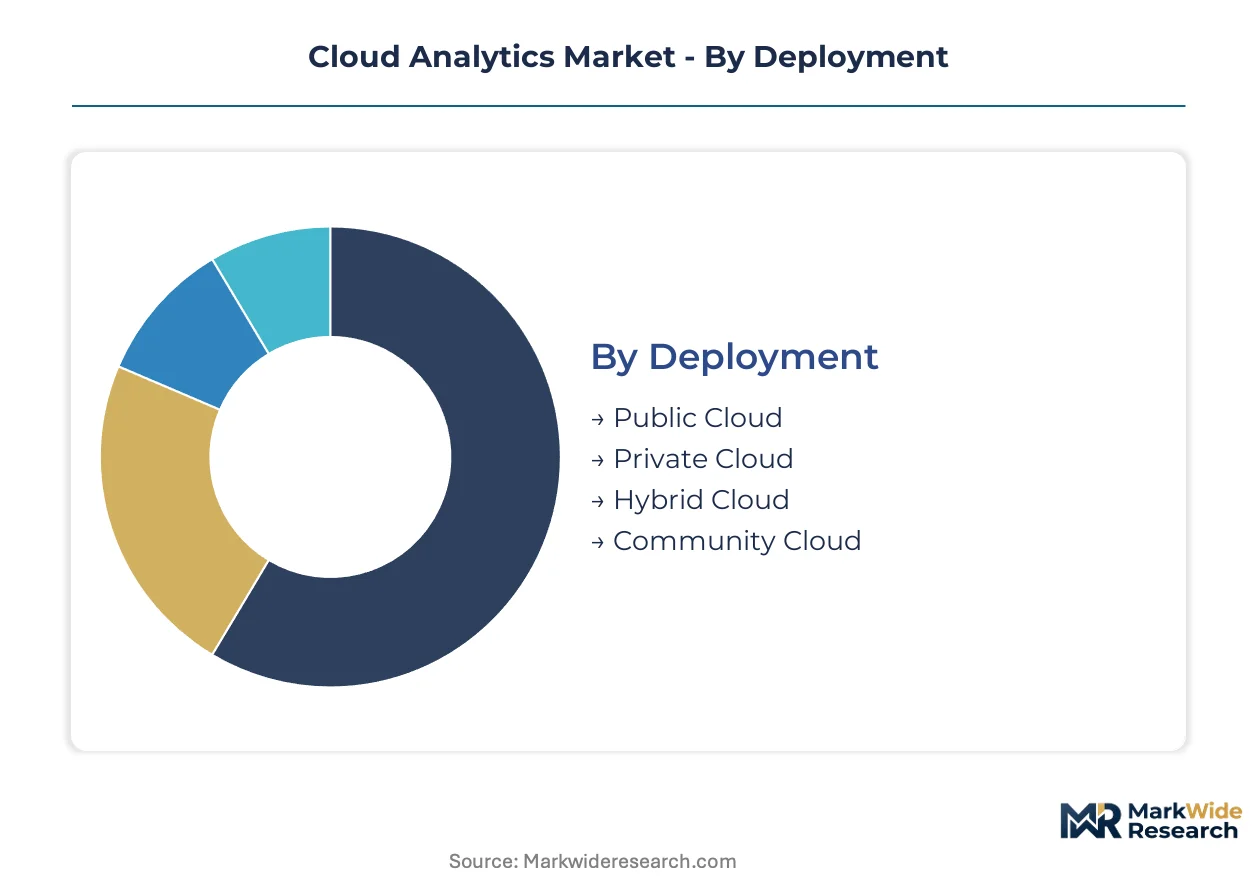
Cloud analytics procurement patterns diverge sharply across deployment models and solution architectures. Buyers select configurations based on data sovereignty requirements, latency constraints, and regulatory exposure rather than feature parity alone.
Deployment:
Channel mix varies dramatically by deployment topology—hyperscaler marketplaces dominate public cloud transactions, while private and hybrid deployments route through systems integrators and managed service providers.
- Public Cloud:Multi-tenant infrastructure delivers elastic compute without capital commitment. North American retailers and SaaS providers drive consumption for burst workloads and development environments where data residency requirements remain permissive.
- Private Cloud:Dedicated single-tenant environments isolate compute and storage for regulated workloads. European banks and insurers mandate private deployments for core banking analytics under GDPR territorial restrictions and EU AI Act risk classification protocols.
- Hybrid Cloud:Unified orchestration across on-premises and cloud resources. Manufacturing firms combine edge inference with centralized model training for predictive maintenance pipelines.
- Community Cloud:Shared infrastructure serving organizations with common compliance profiles. Healthcare consortiums in the United States deploy community models to satisfy HIPAA business associate requirements without individual capital expenditure.
Hybrid cloud dominates installed base. Public cloud is where expansion concentrates.
Solution Type:
Application context determines solution selection—operational teams prioritize real-time ingestion while strategic functions emphasize predictive modeling.
- Data Visualization:Self-service dashboards and interactive reporting interfaces. Marketing departments at media conglomerates deploy embedded visualization to democratize audience analytics across non-technical stakeholders.
- Predictive Analytics:Statistical and machine learning models forecasting future states. Telecom operators leverage subscriber churn prediction and network capacity planning across 5G infrastructure deployments.
- Data Warehousing:Centralized repositories for structured analytical workloads. Government agencies consolidate multi-source administrative data for policy evaluation and citizen service optimization.
- Real-Time Analytics:Sub-second processing of streaming data feeds. Fraud detection systems at payment processors analyze transaction patterns with millisecond latency to block suspicious activity.
- Customer Analytics:Behavioral segmentation and lifetime value modeling. BFSI institutions embed next-best-action engines into digital banking channels for personalized product recommendations.
Data warehousing anchors legacy migration spending. Real-time analytics is climbing the fastest.
Use Case:
Functional requirements shape procurement authority—risk and compliance officers control fraud and risk management budgets, while operations executives own supply chain and demand forecasting investments.
- Risk Management:Quantification and monitoring of operational, credit, and market exposures. Basel III implementation at European banks drives stress testing analytics with granular asset-level modeling.
- Fraud Detection:Anomaly identification across transactions, claims, and identity verification. Insurance carriers deploy behavioral biometrics and network analysis to flag coordinated fraud rings.
- Customer Segmentation:Clustering algorithms for targeting and personalization. Streaming platforms segment viewership by content affinity and engagement patterns to optimize acquisition spend.
- Supply Chain Optimization:Demand sensing and inventory positioning across distributed networks. Automotive manufacturers balance just-in-sequence delivery with buffer stock minimization.
- Demand Forecasting:Time-series projection for production and procurement planning. Consumer packaged goods companies integrate promotional calendars and external signals to reduce forecast error.
Risk management captures the largest compliance-driven contracts. Fraud detection shows steepest expansion trajectory.
End User Industry:
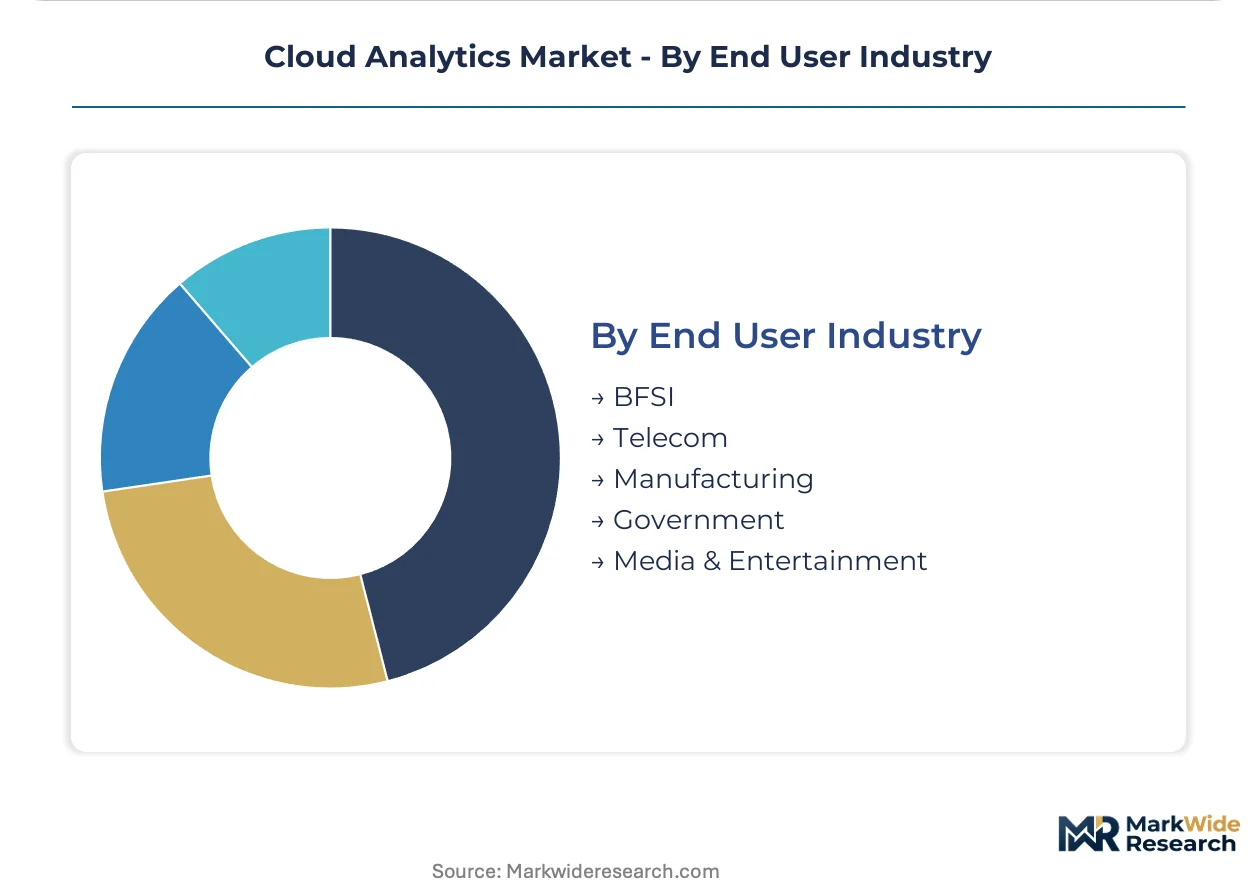
Industry verticals exhibit distinct maturity curves—BFSI and telecom lead operational deployment, while government and media accelerate from pilot phases.
- BFSI:Trading analytics, regulatory reporting, and algorithmic decision systems. United States federal cloud smart mandates accelerate modernization at money center banks and federal credit unions.
- Telecom:Network performance optimization and subscriber intelligence. 5G rollout investments correlate directly with real-time analytics infrastructure commitments.
- Manufacturing:Quality control, predictive maintenance, and digital twin simulation. Industrial IoT sensor density determines analytics platform scale requirements.
- Government:Public health surveillance, tax compliance analytics, and emergency response coordination. Census and statistical agencies modernize legacy batch systems with cloud-native pipelines.
- Media & Entertainment:Content recommendation engines and advertising yield optimization. Streaming wars intensify investment in personalization infrastructure.
BFSI holds the deepest analytics penetration. Government represents the most underpenetrated vertical with highest contract growth potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States while European procurement teams extract governance concessions that compress vendor margins. Federal cloud smart mandates and defense sector modernization sustain premium contract values across American deployments. GDPR territorial restrictions and EU AI Act compliance requirements force vendors to absorb architectural complexity costs without corresponding price recovery.
United States
Defense sector modernization and federal cloud smart directives sustain large-scale deployments with stringent data residency requirements. SEC disclosure rules on material cybersecurity incidents elevate governance requirements for public company procurement. Money center banks in New York and federal credit unions across the Southeast anchor operational analytics penetration.
Germany
Automotive manufacturers and industrial conglomerates drive demand for edge-to-cloud analytics convergence in predictive maintenance applications. EU AI Act risk classifications for automated decision systems impose documentation and human oversight obligations on high-risk deployments. Industrial clusters in Bavaria and Baden-Württemberg combine IoT sensor density with centralized machine learning training.
United Kingdom
Financial services firms embed predictive models into core trading and risk management operations. GDPR compliance requirements and emerging algorithmic accountability standards shape procurement specifications. London-based asset managers and Edinburgh-based insurers represent concentrated demand for real-time streaming analytics infrastructure.
India
Telecom operators deploy sub-second anomaly detection across 5G infrastructure rollouts while IT services firms build delivery capabilities for Western enterprise clients. RBI guidelines on data localization and cybersecurity frameworks influence platform architecture decisions. Bengaluru and Hyderabad clusters anchor hyperscaler region expansion with specialized data engineering talent pools.
Japan
Manufacturing facilities combine digital twin simulation with quality control analytics across automotive and electronics supply chains. METI industrial data sharing initiatives and cybersecurity standards shape vendor qualification criteria. Industrial concentrations in Nagoya and Osaka drive edge analytics deployment for predictive maintenance at scale.
Cloud Analytics Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, producing a tiered competitive structure where hyperscalers anchor infrastructure scale and specialized vendors capture premium analytics workloads. The vendor base organizes around three strategic archetypes: hyperscale platform providers with integrated cloud-native stacks, enterprise software incumbents with hybrid deployment capabilities, and vertical specialists with industry-specific model libraries. Dominant competitive moves include strategic partnerships between hyperscalers and systems integrators to accelerate enterprise migration, plus portfolio diversification into adjacent data governance and AI governance tooling.
Within the hyperscale tier, Microsoft and Amazon Web Services occupy positions that exemplify platform ecosystem dominance through integrated data estate and warehousing offerings. Google represents the AI-infused analytics archetype with embedded generative capabilities that reduce query complexity. IBM anchors the enterprise hybrid deployment position with governance-heavy architectures suited to regulated verticals.
| Leading Market Players |
|---|
| Microsoft |
| Amazon Web Services |
| IBM |
| Oracle |
| SAP |
| Salesforce |
| SAS Institute |
| Teradata |
| Others |
Cost & Logistics Intelligence
Consumption-based pricing with granular resource attribution locks in supply access and price visibility for cloud analytics procurement teams, transferring infrastructure risk to vendors while demanding sophisticated cost governance tooling from buyers navigating multi-year commitments.
Pricing Analysis
The customization-premium spread between configured-to-order private deployments and standard public cloud tiers compresses vendor margins in European markets while sustaining premium capture in United States federal segments. Subscription and consumption-based hybrid structures dominate enterprise contracts, with price differentiation driven by data residency certification levels and vertical-specific compliance modules. Pricing pressure intensifies in the mid-market segment due to hyperscaler price competition, while government and defense buyers exhibit lowest price sensitivity given security classification requirements.
Supply Chain Analysis
The United States and Ireland anchor hyperscaler data center infrastructure for North American and European cloud analytics workloads, while India and Singapore sustain delivery capabilities for Asia-Pacific deployments. Compute hardware draws from Taiwan and South Korea for GPU acceleration, with specialized networking equipment sourced from China and Japan. Single-source vulnerability concentrates in advanced AI accelerator supply, with distribution running through hyperscaler direct sales organizations and systems integrator channels for hybrid deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud analytics represents a high-growth disruption as embedded generative capabilities compress technical barriers between raw data assets and business decision-makers, while EU AI Act compliance mandates reconstitute procurement specifications around algorithmic transparency.
For Market Incumbents: Fortify platform differentiation through embedded explainability modules and model documentation workflows that anticipate EU AI Act enforcement. Deepen vertical integration into specialized data engineering talent pools via acquisition of boutique lakehouse architecture consultancies, defending against margin erosion from open-source query engines. For New Entrants and Emerging Players: Lead with edge-to-cloud analytics convergence targeting manufacturing facilities in Germany and Japan where IoT sensor density outpaces incumbent platform penetration. Position around predictive maintenance pipelines and digital twin simulation as the most penetrable application layer, leveraging channel partnerships with industrial automation vendors for scaled distribution. For Investors and Strategic Acquirers: Boutique compliance tooling vendors with pre-built EU AI Act risk classification modules represent priority acquisition targets given regulatory velocity and enterprise procurement mandate alignment. Long-term viability hinges on platform stickiness through semantic layer architecture rather than infrastructure scale alone; watch for inflection signals in natural language query adoption rates among non-technical business users.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Microsoft Azure Fabric unifies data engineering and BI workflows across hybrid estates. |
| Strategic Partnership | Systems integrator alliances accelerate enterprise migration from legacy data warehouses. |
| Acquisition of Specialist Firm | Lakehouse architecture boutiques address scarcity in distributed query optimization talent. |
| Geographic Expansion | Hyperscaler region buildout in India and Japan satisfies data localization mandates. |
| Product Launch | Embedded Gemini capabilities in BigQuery reduce SQL complexity for business analysts. |
Research Approach
Desk research of hyperscaler capex disclosures, SEC filings, and EU regulatory frameworks preceded structured interviews with CTOs, IT procurement officers, platform engineers, and channel partners across North America, Europe, and Asia-Pacific. Secondary validation drew from customs data on data center equipment imports, Gartner and IDC enterprise software tracking, and national statistical agency digital economy indicators. Bottom-up deployment estimates triangulated against top-down vendor revenue attribution across the analysis window.
Variance-decomposition across deployment models, solution architectures, organization size tiers, and regional adoption patterns structured the analytical framework. CAGRs derived from segment-level growth rate reconciliation with macroeconomic technology spend indicators, incorporating hyperscaler infrastructure expansion timelines and regulatory implementation schedules as industry-specific forecast inputs throughout the projection horizon.
Forecasts assume regulatory continuity in EU AI Act implementation and SEC cybersecurity disclosure regimes; material policy shifts or enforcement delays would require re-modeling. Specific risks include cross-border data transfer restriction expansion, algorithmic accountability mandate acceleration, and hyperscaler market concentration regulatory intervention. Recalibration cycles align with material shifts in compliance requirement enforcement and generative capability integration adoption curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Data Analysis Tools Market
Analytics
Supply Chain Analytics Market
Analytics
Customer Analytics in E-Commerce Market
Analytics
Speech Analytics Market
Analytics
Face Analytics Market
Analytics
Global Analytics Market
Analytics
Israel ICT Market
Analytics
Text Analytics Market
Analytics
SME Big Data Market
Analytics
Statistical Analytics Market
Analytics
Load (ETL) Market
Analytics
Edge Analytics Market
Analytics
Sales Intelligence Market
Analytics
Network Analysis Module (NAM) Market
Analytics
Global Cognitive Analytics Market
Analytics
Data Analytics Outsourcing Market