
 Digital Olfaction Products Market | 2026-2036
Digital Olfaction Products Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Olfaction Products Market Outlook
Sensor miniaturization and AI-driven pattern recognition is fragmenting the traditional gas detection technology stack into modular, software-defined olfaction platforms. Bosch Sensortec leverages its MEMS manufacturing scale to dominate compact sensor supply for consumer electronics integration. Aryballe anchors its position through proprietary bio-inspired photonic technology that differentiates odor signatures without chemical consumables. Alpha MOS sustains R&D intensity across food and beverage quality control applications where regulatory compliance requirements are tightening.
Digital olfaction products encompass electronic nose systems, gas sensors, olfactory displays, and aroma synthesizers that detect, analyze, reproduce, or digitize volatile organic compound signatures using arrays of chemical sensors coupled with machine learning algorithms. These systems typically operate at parts-per-billion sensitivity thresholds and convert complex odor matrices into standardized digital fingerprints for industrial quality control, environmental safety, or diagnostic screening. Electronic nose platforms lead current revenue contribution due to established deployment across food manufacturer quality lines, while machine learning integration represents the fastest-expanding technology layer as pattern recognition accuracy improves and training datasets expand. Healthcare diagnostics applications are emerging as a concentrated margin pool where bioinformatics-enabled wave sensors command premium positioning against conventional chromatography methods.
The FDA regulates diagnostic-oriented olfaction devices under medical device pathways, while the EU AI Act imposes conformity requirements on machine learning components used in automated decision systems including environmental monitoring networks. REACH compliance shapes material selection for sensor substrates and coatings, directly affecting manufacturing cost structures and supplier qualification timelines. Stakeholders must monitor convergence between medical device classification frameworks and emerging AI governance standards to anticipate certification burdens that will determine market access velocity for next-generation platforms.
Market Dynamics
Machine learning integration is compressing the traditional separation between hardware sensing layers and software analytics, forcing vendors to restructure R&D allocation toward bioinformatics-enabled pattern recognition platforms.
Growth Catalysts
- EU AI Act compliance mandates:Automated decision systems in environmental monitoring networks must meet conformity requirements, accelerating replacement cycles for legacy sensor arrays.
- Food manufacturer quality line expansion:Electronic nose deployment across packaged goods inspection is tightening tolerance thresholds for volatile organic compound detection.
- MEMS manufacturing scale:Semiconductor foundry capacity for miniaturized sensor substrates is reducing unit economics for consumer electronics integration.
Market Restraints
- Specialized coating material costs:REACH-compliant sensor substrates require qualified supplier networks with extended procurement timelines.
- Training dataset scarcity:Pattern recognition accuracy depends on proprietary odor signature libraries that remain concentrated among incumbent developers.
- Chromatography substitution threat:Gas chromatography-mass spectrometry retains reference standard status in pharmaceutical quality control applications.
Strategic Opportunities
- Healthcare diagnostics white space:Bioinformatics-enabled wave sensors command premium positioning against conventional laboratory methods in early disease screening.
- German industrial automation cluster:Advanced research institution networks in Munich and Berlin accelerate pilot-to-production pathways for automotive quality applications.
- Photonic-olfactory convergence:Bio-inspired optical sensing arrays eliminate chemical consumable dependencies while expanding detection specificity.
Industry Challenges
- Cross-functional talent scarcity:Machine learning engineers with domain expertise in chemosensory signal processing command compensation premiums that strain mid-cap R&D budgets.
- Dual certification complexity:Devices spanning environmental monitoring and diagnostic applications must satisfy both FDA medical device pathways and EPA environmental sensor standards.
- Legacy system integration friction:Existing quality control infrastructure in food manufacturing requires customized middleware development for digital olfaction platform connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Olfaction Products Market |
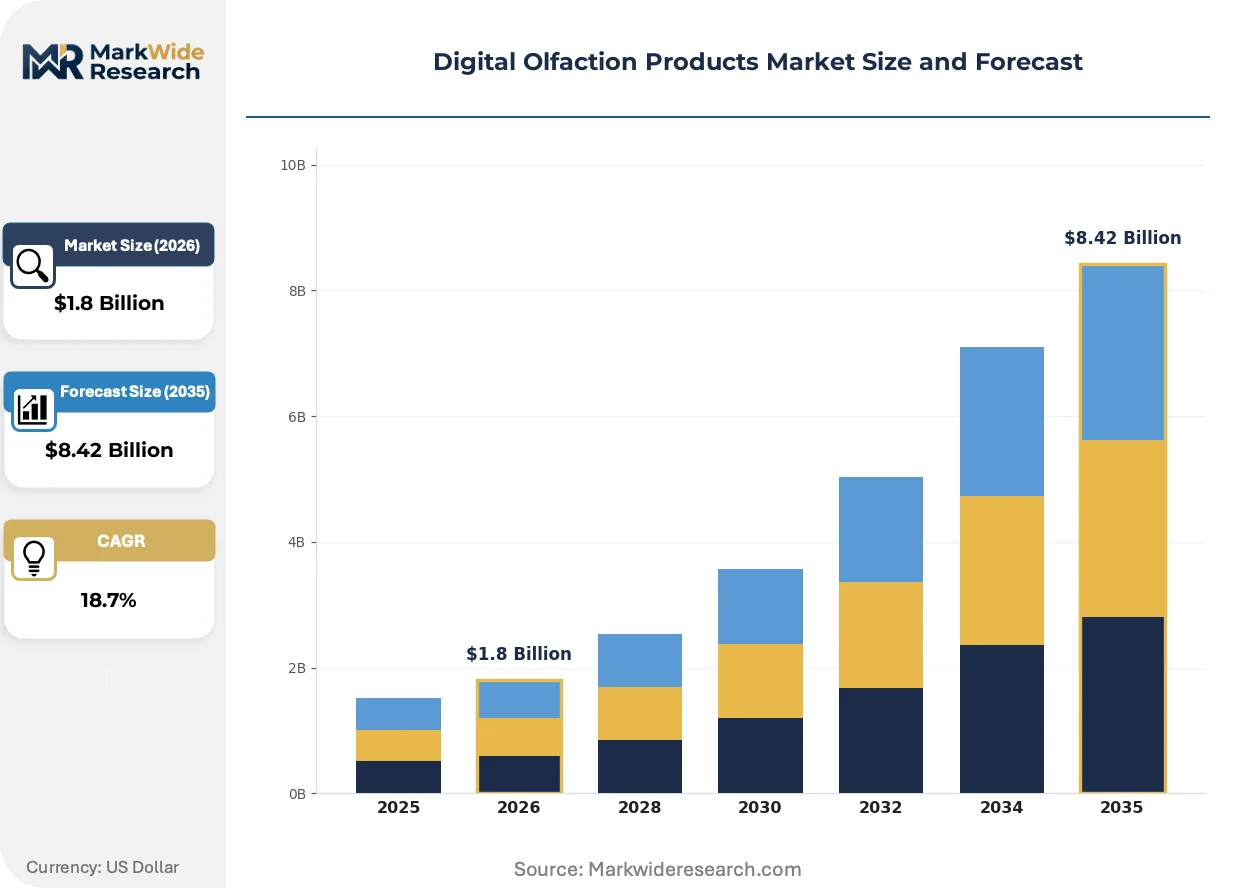
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.42 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronic Nose, Gas Sensor, Olfactory Display, Aroma Synthesizer Application: Food & Beverage Quality, Environmental Monitoring, Healthcare Diagnostics, Home Automation End User: Food Manufacturers, Research Institutions, Healthcare Providers, Retailers Technology: Gas Chromatography, Machine Learning, Bioinformatics, Wave Sensors |
| Companies Covered | Aroma Bit, Bosch Sensortec, Aryballe, NEW COSMOS ELECTRIC, Panasonic, Osmo, Alpha MOS, SmartNanotubes Technologies, Moodify, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Olfaction Products Market Strategic Shifts
Software-defined sensing architectures are dissolving the historical boundary between discrete hardware components and cloud-native analytics, enabling odor fingerprint standardization across distributed industrial networks.
Photonic sensing arrays are migrating from laboratory research environments into compact field-deployable configurations. Automotive cabin air quality monitoring programs are piloting solid-state optical sensors at accelerated validation cycles. The technology is migrating from chromatography-dependent reference methods toward real-time spectral analysis platforms that compress quality assurance timelines from hours to seconds.
REACH substance restrictions are reshaping coating chemistry selection for sensor substrates. Manufacturers must reformulate polymer membranes to eliminate restricted phthalate plasticizers while maintaining parts-per-billion sensitivity thresholds. German industrial sensor suppliers are responding by qualifying alternative fluoropolymer formulations through accelerated aging protocols.
Food and beverage procurement departments are consolidating vendor relationships around integrated platform providers rather than discrete sensor suppliers. Long-term service contracts bundling hardware, calibration, and predictive maintenance analytics are displacing transactional equipment purchases. This concentration is most visible in German dairy processing cooperatives where quality standardization across distributed facilities favors single-source digital olfaction deployments.
Digital Olfaction Products Market Segmentation
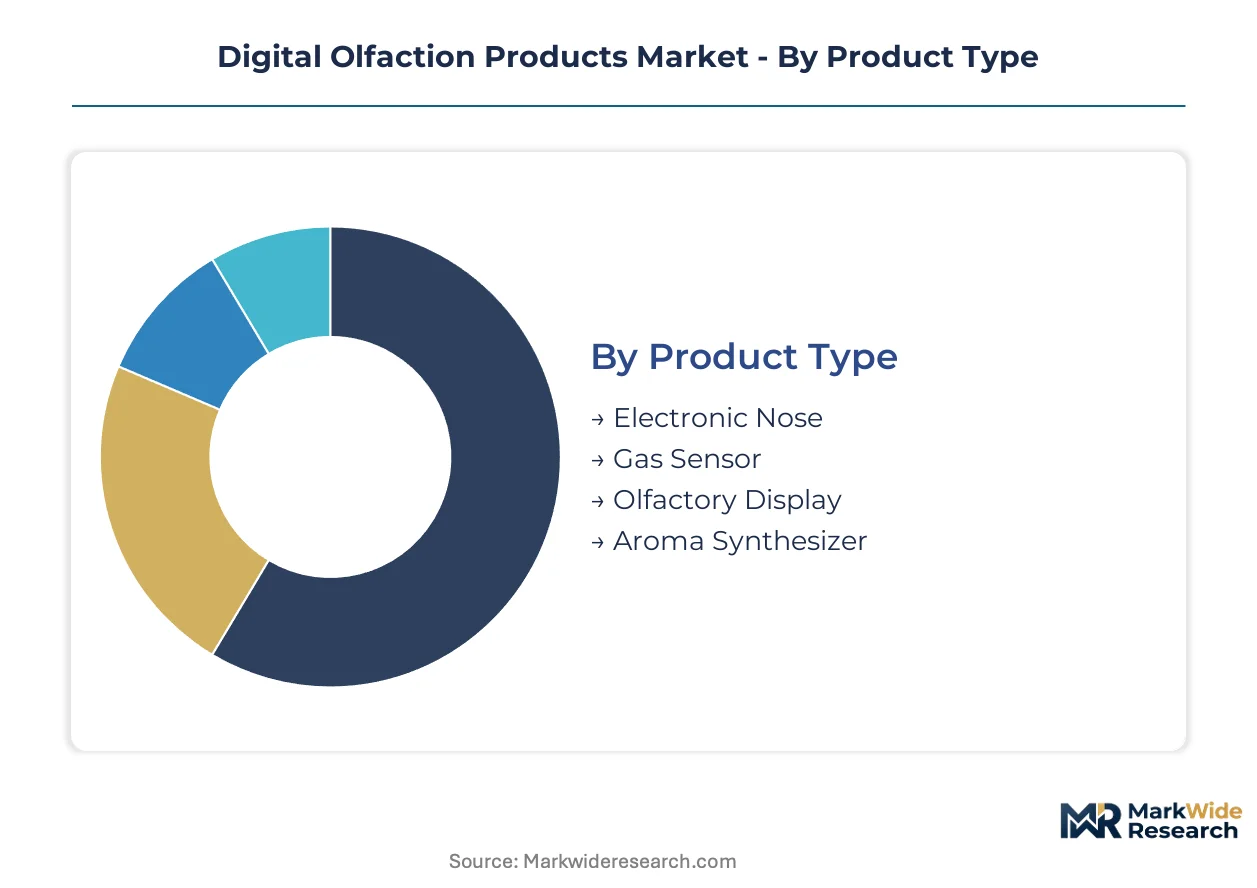
Segmentation in digital olfaction reveals divergent replacement cycles across hardware layers versus software integration tiers. Product type stratification shows electronic nose systems commanding extended depreciation schedules while emerging photonic platforms accelerate refresh rates. Application-level segmentation exposes healthcare diagnostics as the concentrated margin pool against environmental monitoring's volume-driven procurement patterns.
Product Type:
Cycle times vary dramatically: gas sensors turn over fastest at consumer electronics cadences, while electronic nose platforms sustain decade-long operational lifespans in industrial quality lines.
- Electronic Nose:Array-based systems integrating multiple chemical sensors with pattern recognition software for complex odor fingerprint analysis. Food manufacturers in Germany anchor demand through quality line standardization mandates under EFSA guidelines. Extended calibration intervals and modular sensor head architectures protect installed base longevity.
- Gas Sensor:Discrete detection elements measuring specific volatile organic compounds through metal oxide or electrochemical transduction. MEMS miniaturization from Bosch Sensortec and rival foundries compresses replacement cycles to 18-24 months in smartphone and wearable integrations. REACH-compliant substrate qualification extends procurement lead times for industrial-grade variants.
- Olfactory Display:Actuator arrays releasing controlled scent compositions for immersive media and retail environments.
- Aroma Synthesizer:Precision blending systems reproducing target odor profiles from digital recipes for food formulation and fragrance development.
Electronic nose systems dominate installed base. Gas sensors represent where expansion concentrates most rapidly.
Application:
Cost tier stratification separates premium-positioned diagnostic screening from commoditized environmental compliance monitoring.
- Food & Beverage Quality:Inline inspection systems detecting spoilage markers, packaging integrity failures, and batch consistency deviations. German dairy cooperatives consolidate procurement around single-source platform providers bundling predictive maintenance analytics. EU AI Act conformity requirements for automated decision systems accelerate legacy array replacement.
- Healthcare Diagnostics:Breath-based biomarker detection for early disease screening using bioinformatics-enabled wave sensors. FDA medical device pathway classification imposes dual certification burdens alongside EPA environmental standards for multi-use platforms. Premium pricing persists against chromatography reference methods due to real-time turnaround compression.
- Environmental Monitoring:Distributed sensor networks tracking industrial emissions, urban air quality, and workplace safety thresholds.
- Home Automation:Consumer-grade air quality and scent personalization systems integrating with smart home ecosystems.
Food & Beverage Quality commands current revenue contribution. Healthcare Diagnostics is climbing the fastest as regulatory frameworks mature.
End User:
Customer type segmentation tracks procurement sophistication from transactional equipment purchases to long-term service contracting.
- Food Manufacturers:Industrial quality departments with consolidated vendor relationships and standardized tolerance specifications across distributed facilities. German packaging goods producers pilot photonic sensing arrays to eliminate chemical consumable dependencies. Outcome-based contracts bundling hardware, calibration, and analytics displace capital expenditure models.
- Research Institutions:Academic and government laboratories advancing bio-inspired sensing architectures and expanding training datasets for pattern recognition algorithms. Munich and Berlin clusters accelerate pilot-to-production pathways through proximity to automotive quality applications.
- Healthcare Providers:Hospital systems and diagnostic laboratories integrating olfaction platforms into clinical workflows.
- Retailers:Scent marketing deployments and consumer product testing facilities.
Food Manufacturers anchor volume procurement. Research Institutions concentrate technology development investment.
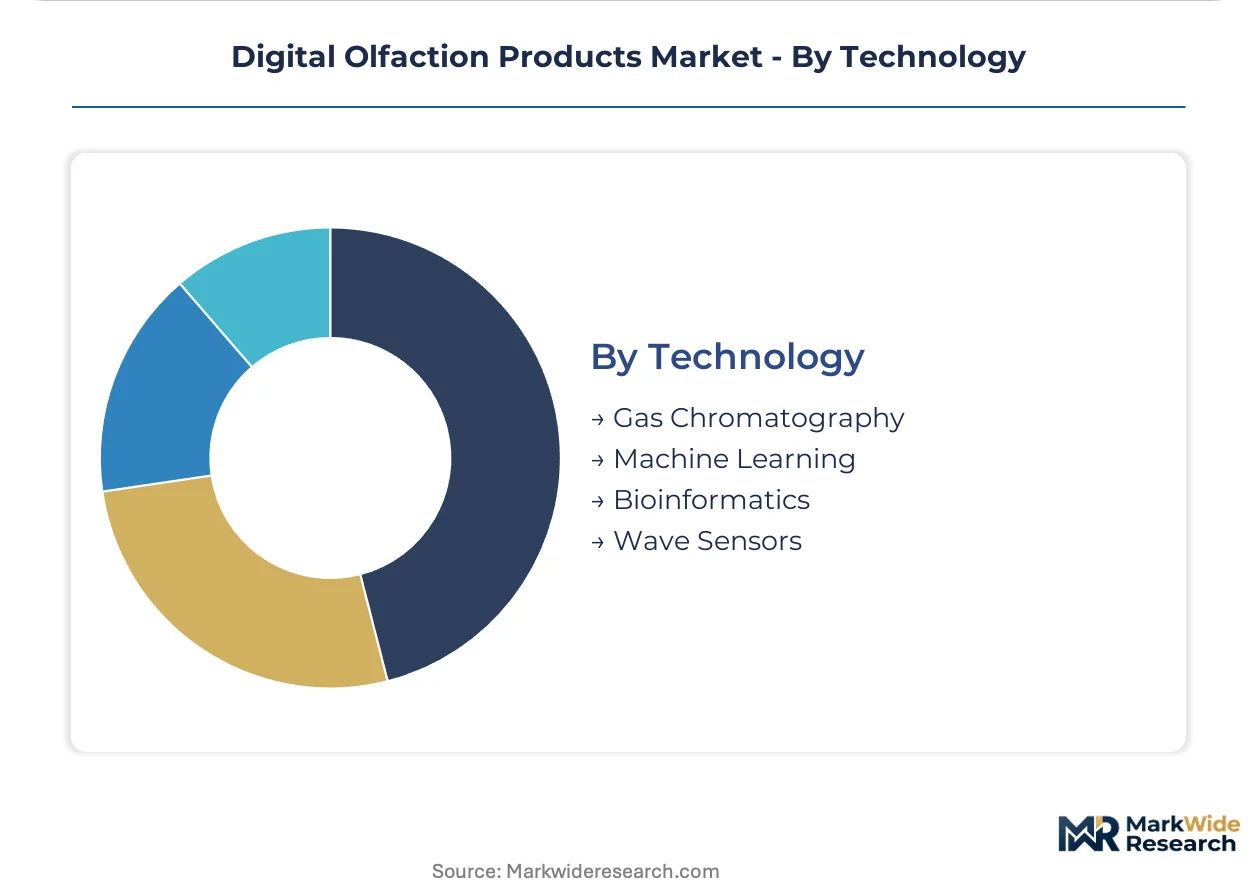
Technology:
Maturity curves separate established chromatography methods from emerging bioinformatics platforms competing on speed and consumable elimination.
- Machine Learning:Pattern recognition algorithms converting sensor array outputs into standardized odor fingerprints through neural network architectures. Training dataset scarcity concentrates competitive advantage among incumbent developers with proprietary signature libraries. Cloud-native analytics integration enables distributed network standardization.
- Bioinformatics:Computational biology approaches to chemosensory signal processing and biomarker identification. Wave sensor coupling commands premium positioning in healthcare diagnostics against conventional laboratory methods. Cross-functional talent scarcity strains mid-cap R&D budgets.
- Gas Chromatography:Reference standard separation techniques retaining pharmaceutical quality control certification.
- Wave Sensors:Photonic transduction elements detecting molecular vibrations through spectral analysis without chemical reagents.
Gas Chromatography dominates reference standard status. Machine Learning is gaining share fastest through software-defined sensing convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German sensor manufacturers export electronic nose platforms to food processing facilities across France and Italy. Cross-border R&D partnerships between Munich research clusters and Swiss precision instrumentation firms accelerate photonic sensing commercialization.
United States
FDA medical device pathway classification drives diagnostic olfaction platform development in Boston and San Francisco health-tech corridors. EPA environmental sensor standards create dual certification requirements for multi-use devices. Pittsburgh's advanced manufacturing institutes pilot solid-state optical sensors for industrial emissions monitoring.
Germany
EFSA quality standardization mandates expand electronic nose deployment across dairy and packaged goods cooperatives. EU AI Act conformity requirements accelerate replacement of legacy sensor arrays in automated decision systems. Munich and Berlin research institution networks compress pilot-to-production timelines for automotive cabin air quality applications.
France
ANSM medical device oversight shapes diagnostic platform certification strategies for breath-based biomarker detection. REACH substance restrictions force reformulation of polymer sensor membranes to eliminate restricted phthalate plasticizers. Paris-Saclay research cluster advances bio-inspired photonic architectures for laboratory-to-field migration.
Japan
METI industrial automation incentives support integration of compact gas sensors into smart factory quality lines. PMDA regulatory frameworks govern clinical validation requirements for healthcare diagnostic deployments. Osaka-Kobe manufacturing belt concentrates MEMS foundry capacity for consumer electronics miniaturization.
China
GB standards for air quality monitoring expand procurement of distributed sensor networks in industrial zones. MIIT semiconductor self-sufficiency programs accelerate domestic MEMS substrate manufacturing scale. Yangtze River Delta electronics manufacturing clusters absorb miniaturized olfaction modules for smartphone integration.
Digital Olfaction Products Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented supply tiers. MEMS foundries and semiconductor houses leverage manufacturing scale against bio-inspired technology developers with proprietary photonic architectures. Three archetypes dominate: integrated platform providers bundling hardware and analytics, component specialists supplying sensor substrates, and application-focused developers targeting healthcare diagnostics. Competitive moves concentrate on strategic partnerships for training dataset expansion and technology licensing for photonic-olfactory convergence.
Within the integrated platform tier, Bosch Sensortec exemplifies scale-driven MEMS manufacturing, while Aryballe occupies a position representing bio-inspired photonic differentiation. Alpha MOS anchors the application-focused archetype through sustained presence across food and beverage quality control segments.
| Leading Market Players |
|---|
| Aroma Bit |
| Bosch Sensortec |
| Aryballe |
| NEW COSMOS ELECTRIC |
| Panasonic |
| Osmo |
| Alpha MOS |
| SmartNanotubes Technologies |
| Moodify |
| Others |
Value Chain & Pricing Dynamics
Munich's MEMS foundry cluster anchors sensor substrate supply for consumer electronics integration, translating semiconductor manufacturing scale into downstream pricing leverage for gas sensor modules. REACH-compliant coating chemistry qualification extends procurement timelines, compressing margin buffers for mid-tier electronic nose platform assemblers competing against integrated providers.
Pricing Analysis
Prior-generation metal oxide gas sensors trade at commodity rates against next-generation photonic arrays commanding certification premiums. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared diagnostic platforms from industrial quality line systems and consumer-grade air quality modules. Price differentiation centers on calibration interval guarantees and predictive maintenance bundling. Cost compression in standard-tier electronic nose systems is intensifying because German dairy cooperatives consolidate procurement around single-source platform providers.
Supply Chain Analysis
Export controls on advanced photonic sensing components limit flows from Swiss precision instrumentation firms to non-allied manufacturing zones. Germany, Japan, and South Korea concentrate MEMS substrate fabrication for miniaturized sensor elements. Supply chains draw from fluoropolymer membrane suppliers, semiconductor foundry capacity, and rare-earth doped optical materials. Single-source vulnerability concentrates in qualified coating chemistry providers meeting REACH substance restrictions. Distribution runs through integrated platform providers bundling hardware, calibration, and cloud-native analytics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as EU AI Act compliance mandates displace legacy sensor arrays, creating niches for bioinformatics-enabled pattern recognition specialists between incumbent integrated platforms and component suppliers.
For Market Incumbents: Pre-empt photonic-olfactory convergence by acquiring bio-inspired optical sensing startups before reference standard status shifts from chromatography. Lock in German automotive cabin air quality programs through outcome-based contracts bundling predictive maintenance analytics. Defend against MEMS commoditization by deepening proprietary training dataset moats. For New Entrants and Emerging Players: Pursue healthcare diagnostics white space where FDA medical device pathway complexity deters generalist entrants. Target breath-based biomarker detection applications requiring bioinformatics-enabled wave sensors against chromatography reference methods. Open with research institution partnerships in Munich and Berlin clusters to compress pilot-to-production timelines. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors application-focused developers with healthcare regulatory clearance over hardware-agnostic software layers. Five-to-ten year viability rests on dual certification capability spanning FDA medical device and EPA environmental sensor standards. Signal to watch: consolidation of German dairy cooperative procurement around single-source platform providers indicating tipping point for integrated versus modular architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Photonic Sensor Commercialization | Migrates bio-inspired optical arrays from laboratory research into compact field-deployable configurations for automotive quality applications. |
| Training Dataset Expansion Partnership | Proprietary odor signature libraries concentrate competitive advantage among incumbent developers with pattern recognition scale. |
| REACH-Compliant Coating Qualification | Alternative fluoropolymer formulations extend procurement timelines while eliminating restricted phthalate plasticizers from sensor substrates. |
| Dual Certification Investment | Simultaneous FDA medical device and EPA environmental sensor clearance opens multi-use platform revenue streams in diagnostics and monitoring. |
| Cloud-Native Analytics Integration | Software-defined sensing architectures enable odor fingerprint standardization across distributed industrial networks for food manufacturers. |
Study Parameters
The analysis maps electronic nose systems, gas sensors, olfactory displays, and aroma synthesizers, each validated through quality control directors at food manufacturers, biomedical engineers at healthcare providers, procurement leads at research institutions, and sensor platform CTOs. Primary interviews with these stakeholders combined with secondary validation from FDA 510(k) filings, EFSA guidance documents, EU AI Act conformity assessment procedures, and REACH substance restriction databases. Bottom-up unit economics modeling triangulated against top-down market sizing across technology layers.
Assumptions held fixed include EU AI Act implementation timelines and REACH substance restriction enforcement intensity, while sensor miniaturization cost curves and pattern recognition accuracy improvements varied across sensitivity analyses. Segmentation dimensions modeled encompass product type, application vertical, end-user procurement sophistication, and technology maturity tier. CAGRs derived from installed base replacement cycle analysis and emerging application penetration curves. Forecast inputs incorporated MEMS foundry capacity expansion announcements and healthcare diagnostic regulatory pathway completion rates.
Sensitivities concentrate around EU AI Act enforcement intensity altering legacy sensor array replacement velocity and FDA medical device classification shifts for multi-use platforms. Forecasts reflect these documented assumptions and acknowledged risk factors. Material shifts in photonic sensing reference standard adoption or REACH substance restriction scope expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Asset Tags Market
Sensors
Lidar Market
Sensors
Digital Compass (E-Compass) Market
Sensors
NB-IoT Smart Gas Meter Market
Sensors
Weigh-In-Motion System Market
Sensors
Mobile Laser Scanning Market
Sensors
RFID Smart Cabinet Market
Sensors
Yield Monitoring Systems Market
Sensors
Global Load Monitoring System (LMS) Market
Sensors
Global Tunnel Monitoring System Market
Sensors
Low Power Geolocation Market
Sensors
Global Smart Leak Detection Solutions Market
Sensors
Global Equipment Monitoring Market
Sensors
Smart Barcode Readers Market
Sensors
Mobile Mapping Systems Market
Sensors
Transport Monitoring System Market