
 Global Real-Time Locating Systems (RTLS) Market | 2026-2036
Global Real-Time Locating Systems (RTLS) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Real-Time Locating Systems (RTLS) Market Foresight
Modular sensor-to-software bundling is restructuring how healthcare and logistics buyers evaluate RTLS procurement. Zebra Technologies Corporation leverages its end-to-end hardware portfolio to dominate enterprise asset visibility deployments. Impinj, Inc. sustains its position through RAIN RFID silicon specialization for high-density inventory environments. CenTrak, Inc. anchors clinical-grade location accuracy through proprietary infrared-ultrasound fusion architectures.
Real-Time Locating Systems comprise networked hardware and software platforms that calculate precise spatial coordinates for tagged objects or individuals using radio frequency, infrared, ultrasound, or ultra-wideband signaling with sub-meter accuracy in controlled environments. These systems primarily enable automated asset accountability, workflow orchestration, and safety compliance across physically complex operations. Active RTLS and Ultra-Wideband segments command premium positioning due to real-time latency requirements in surgical suite tracking and autonomous mobile robot coordination. Bluetooth Low Energy deployments are expanding fastest in warehousing facilities where lower infrastructure cost outweighs centimeter-grade precision needs. RFID Systems retain mature, high-volume economics in supply chain optimization where line-of-sight interrogation satisfies pallet-level visibility.
FDA device traceability rules and the EU AI Act are reshaping data governance obligations for location-aware systems processing patient or personnel identifiers. EMA medical device regulations and FCC spectrum allocations for ultra-wideband operation further constrain hardware certification pathways and cross-border deployment timelines. Stakeholders must monitor evolving interoperability mandates between IEEE 802.15.4z and Bluetooth SIG standards bodies to preserve technology roadmap optionality.
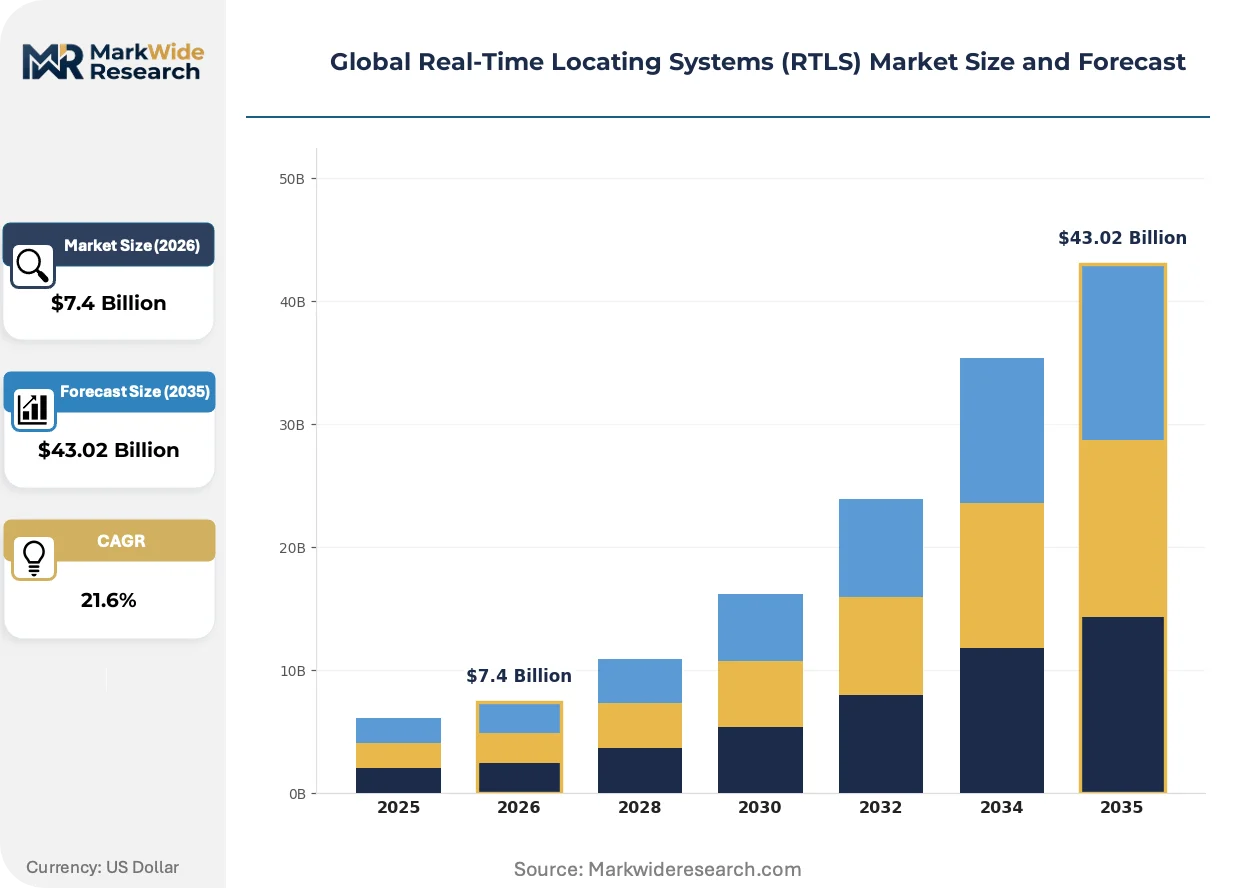
Market Dynamics
Modular sensor-to-software bundling is restructuring how healthcare and logistics buyers evaluate RTLS procurement, compressing vendor selection cycles and elevating system integrators above component specialists. The FDA device traceability mandate and EU AI Act are tightening location-data governance requirements, forcing buyers to prioritize certified platforms over point solutions.
Growth Catalysts
- FDA device traceability rules:Healthcare providers in the United States must deploy location-aware systems for surgical instrument accountability, accelerating hospital RTLS procurement timelines.
- Ultra-wideband spectrum allocation:FCC rulings on 6.5-8.5 GHz operation enable centimeter-grade precision for autonomous mobile robot coordination in semiconductor logistics.
- Japan METI smart hospital initiative:Patient flow optimization mandates drive RTLS deployment across Tokyo and Osaka medical clusters for bed management automation.
Market Restraints
- Silicon supply concentration:RAIN RFID chip fabrication concentrates in Taiwan and South Korea, exposing hardware vendors to geopolitical disruption risk.
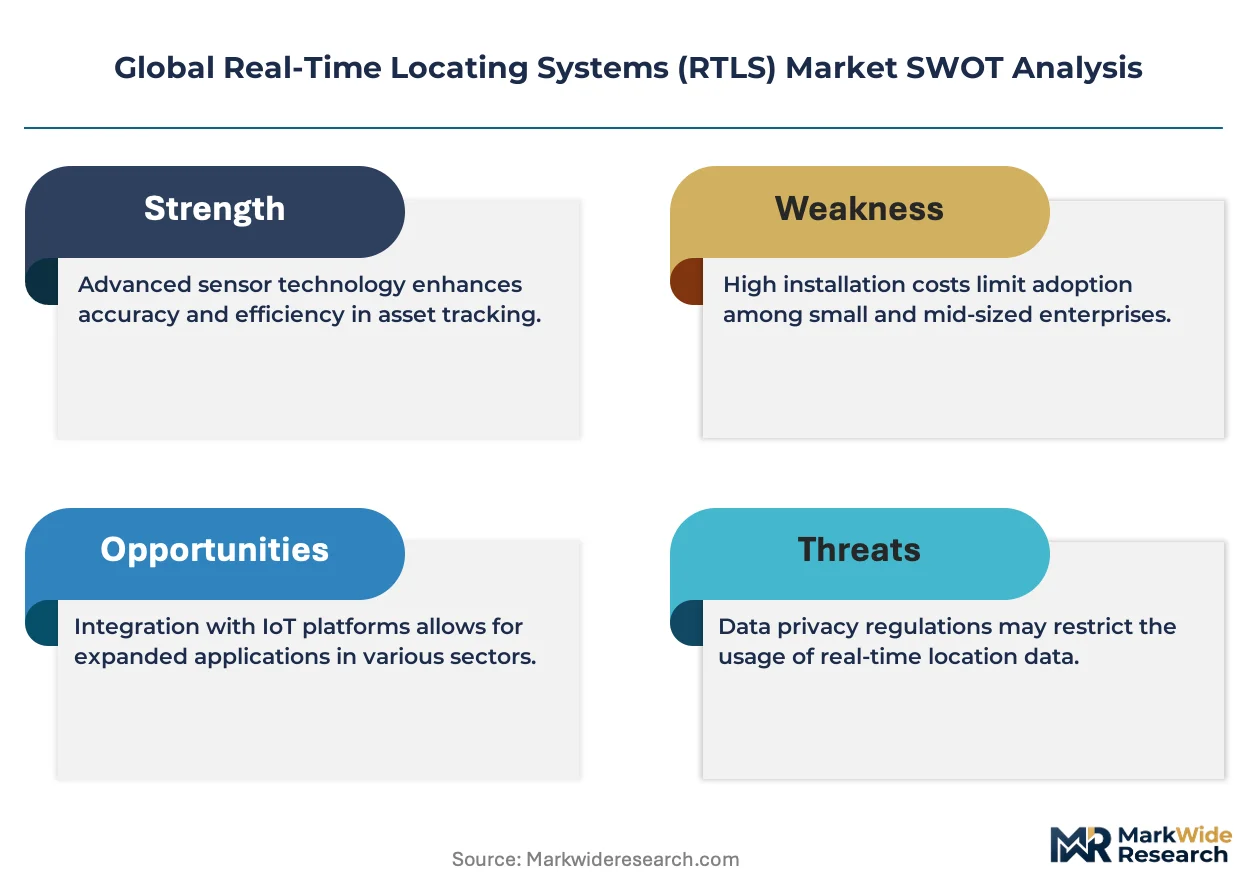
- Ultra-wideband hardware costs:Precision anchoring infrastructure requires 3-4x the sensor density of Bluetooth Low Energy alternatives, constraining warehouse adoption.
- EU MDR certification timelines:Medical device regulations extend hardware approval cycles to 18-24 months for clinical-grade location systems.
Strategic Opportunities
- India PLI scheme for electronics:Manufacturing incentives attract RTLS hardware assembly to Tamil Nadu and Karnataka, reducing import dependency for domestic logistics buyers.
- AI Act location-data governance:Compliance mandates create certified-platform premiums for vendors offering embedded anonymization and audit trails.
- 5G private network convergence:Integration with campus-scale 5G slicing enables single-infrastructure positioning for industrial asset tracking.
Industry Challenges
- RF engineering talent scarcity:Ultra-wideband system design requires specialized antenna and propagation expertise concentrated in Boston and Austin technology clusters.
- Legacy WMS integration complexity:Warehouse management systems from the 2010s lack native API support for real-time location feeds, demanding custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Real-Time Locating Systems (RTLS) Market |
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $43.02 Billion |
| CAGR (2026 – 2036) | 21.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active RTLS, Passive RTLS, Hybrid RTLS, Ultra-Wideband, RFID Systems Technology: Infrared, Ultrasound, Wi-Fi, Bluetooth Low Energy, Zigbee, Ultrasonic Application: Asset Management, Personnel Tracking, Supply Chain Optimization, Safety Monitoring, Inventory Control End User: Manufacturing Plants, Warehousing Facilities, Healthcare Providers, Logistics Companies, Educational Institutions |
| Companies Covered | Zebra Technologies Corporation, Impinj, Inc., CenTrak, Inc., Securitas AB, Ubisense Group, TeleTracking Technologies, Inc., Savi Technology, Sewio Networks, Sonitor Technologies AS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Real-Time Locating Systems (RTLS) Market Shifts & Advancements
Three forces are actively compressing RTLS procurement and deployment models: precision-grade positioning is migrating to software-defined architectures, regulatory data governance is hardening into product requirements, and buyer evaluation criteria are shifting from hardware specs to outcome guarantees.
Ultra-wideband chipsets with integrated angle-of-arrival calculation are rewriting the economics of sub-meter positioning. German automotive manufacturers and Austin semiconductor fabs are adopting these system-on-chip solutions for tool tracking and automated guided vehicle coordination. The technology is compressing infrastructure costs by eliminating separate antenna arrays and signal processing hardware.
EU AI Act location-data governance mandates are reshaping product architecture requirements for any system processing patient or personnel identifiers. Vendors must now embed purpose limitation, data minimization, and audit trail capabilities at the firmware level to serve European healthcare buyers. Clinical-grade RTLS deployments in Germany and France are prioritizing platforms with pre-certified compliance modules over retrofitting legacy installations.
Subscription-based outcome contracts are displacing capital expenditure procurement for large-scale warehouse deployments. Third-party logistics operators in the United States and Japan are negotiating per-location-event pricing rather than upfront hardware purchases, transferring infrastructure risk to RTLS vendors. This model concentrates fastest among e-commerce fulfillment networks facing seasonal volume volatility.
Global Real-Time Locating Systems (RTLS) Market Segmentation
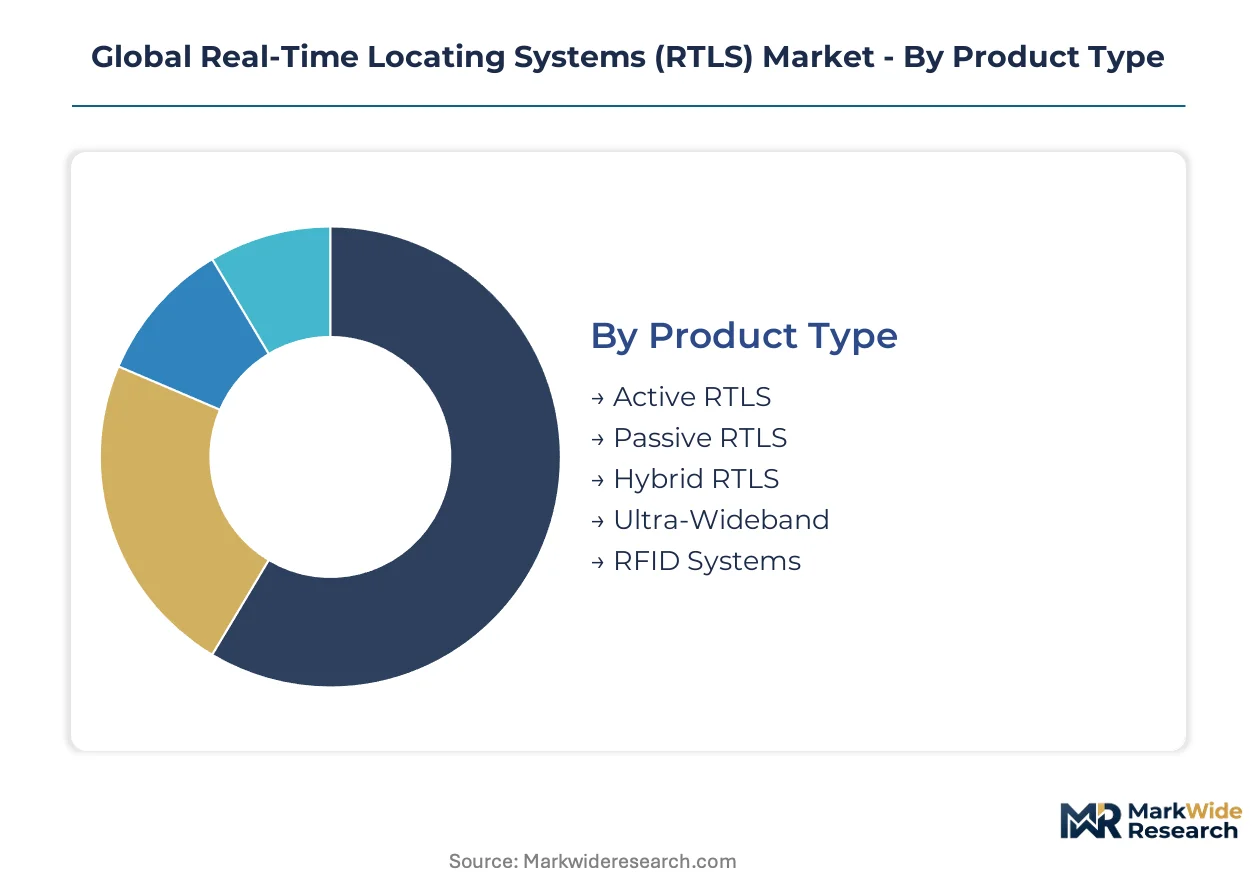
RTLS procurement diverges sharply across precision requirements, infrastructure cost thresholds, and regulatory compliance burdens. Buyers in semiconductor logistics and surgical suites demand centimeter-grade accuracy, while warehouse operators prioritize scalable coverage over absolute precision.
Product Type:
Technology specifications determine infrastructure density, latency tolerance, and total cost of ownership across deployment scenarios.
- Active RTLS:Battery-powered tags transmit continuous location beacons to networked receivers, enabling real-time visibility for surgical instruments and high-value manufacturing tools. German hospitals and Austin semiconductor fabs concentrate procurement here due to FDA traceability mandates and autonomous robot coordination requirements.
- Ultra-Wideband:Pulse-radio signaling in the 6.5-8.5 GHz band delivers sub-30-centimeter precision through time-of-flight calculation. Japanese automotive manufacturers and Boston medical technology clusters drive adoption for tool tracking and patient flow optimization where FCC spectrum allocations permit operation.
- Passive RTLS:Reader-interrogated tags without onboard power suit pallet-level supply chain visibility at lowest per-tag cost.
- Hybrid RTLS:Multi-technology fusion architectures combine infrared, ultrasound, or RFID signaling for redundant coverage in complex RF environments.
- RFID Systems:Mature RAIN RFID deployments dominate high-volume logistics corridors where line-of-sight interrogation satisfies inventory accountability needs.
RFID Systems lead on scale; Ultra-Wideband leads on momentum.
Technology:
Signal propagation characteristics and spectrum licensing costs segment buyers by precision-versus-economy tradeoffs.
- Bluetooth Low Energy:2.4 GHz mesh networks enable rapid warehouse deployment at one-third the sensor density of ultra-wideband alternatives. Third-party logistics operators in the United States and Japan negotiate outcome-based contracts around BLE infrastructure for seasonal e-commerce fulfillment volatility.
- Infrared:Line-of-sight optical signaling delivers room-level certainty for patient bed management and operating suite workflow orchestration. German healthcare providers specify infrared-ultrasound fusion to satisfy EU AI Act data governance requirements for personnel location tracking.
- Ultrasound:Low-frequency acoustic positioning penetrates RF-dense hospital environments without electromagnetic interference.
- Wi-Fi:Leverages existing enterprise wireless infrastructure for coarse-grained asset zone location without dedicated hardware overlay.
- Zigbee:IEEE 802.15.4 mesh protocols serve industrial sensor networks requiring low-power, multi-hop connectivity.
- Ultrasonic:High-frequency acoustic ranging supports specialized applications in cleanroom and explosive atmosphere environments.
Bluetooth Low Energy captures volume growth; Infrared commands clinical premiums.
Application:
Use-case complexity and regulatory exposure determine platform selection and vendor qualification depth.
- Asset Management:Automated accountability for mobile medical equipment and manufacturing tooling drives recurring location query volumes. Healthcare providers across Germany, Japan, and the United States expand deployments to reduce capital equipment duplication and improve utilization rates.
- Personnel Tracking:Staff duress alerting and workflow optimization require anonymization capabilities and audit trail documentation under EU AI Act mandates. French and German hospital systems prioritize pre-certified compliance modules over retrofitting legacy installations.
- Supply Chain Optimization:Pallet and container visibility across multimodal logistics networks leverages mature RFID economics.
- Safety Monitoring:Lone worker protection and evacuation mustering demand reliable indoor positioning in GPS-denied environments.
- Inventory Control:Cycle count automation and shrinkage reduction concentrate in high-velocity distribution centers.
Asset Management anchors installed base; Personnel Tracking faces steepest compliance escalation.
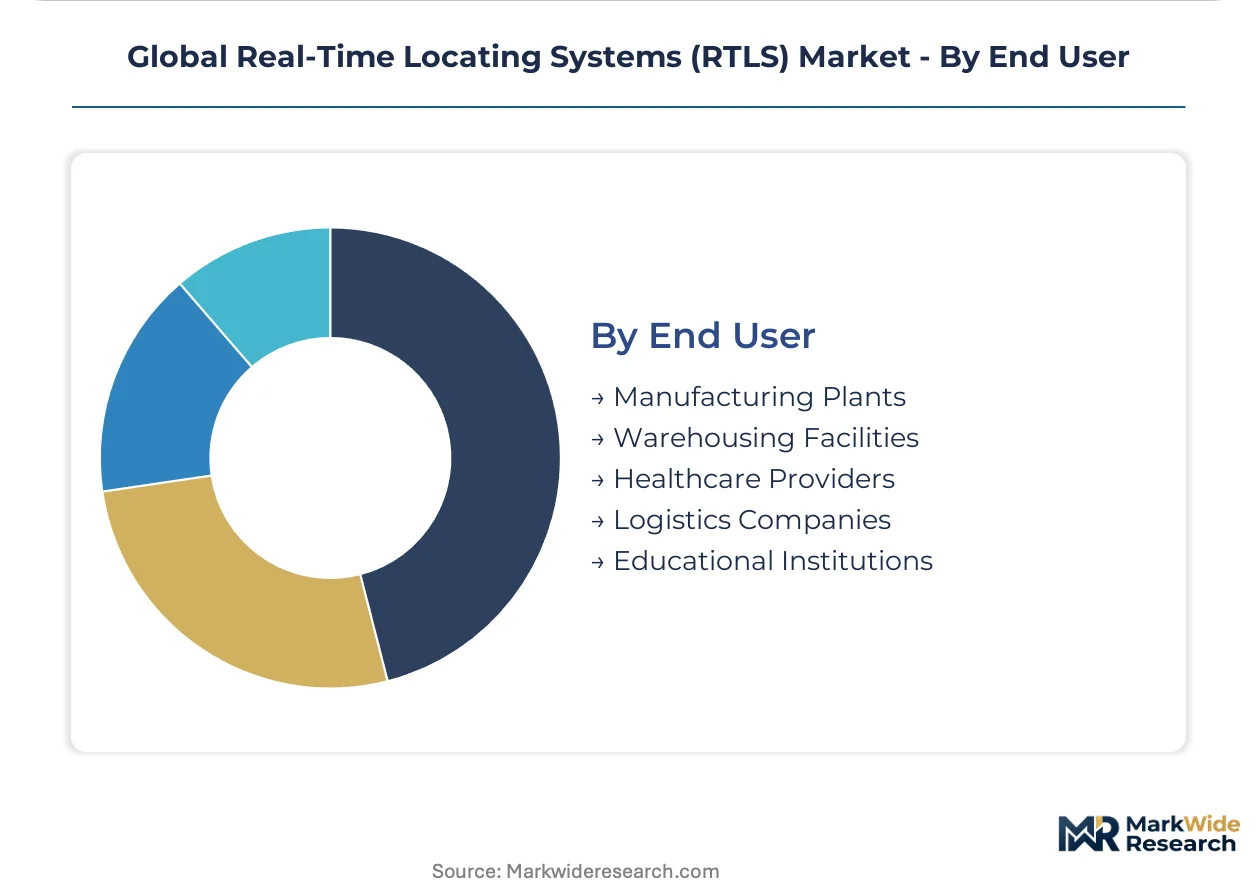
End User:
Operational scale and technology maturity segment procurement authority and integration complexity.
- Healthcare Providers:Hospital systems in Boston, Tokyo, and Munich deploy clinical-grade systems for patient flow optimization and surgical instrument traceability. FDA device traceability rules and EMA medical device regulations compress vendor selection toward certified platforms with embedded governance capabilities.
- Manufacturing Plants:German automotive producers and Austin semiconductor fabs adopt ultra-wideband system-on-chip solutions for automated guided vehicle coordination and precision tool tracking.
- Warehousing Facilities:E-commerce fulfillment networks in the United States and Japan negotiate subscription-based outcome contracts transferring infrastructure risk to RTLS vendors.
- Logistics Companies:Third-party operators prioritize interoperability with legacy warehouse management systems lacking native API support for real-time location feeds.
- Educational Institutions:Campus safety and resource scheduling applications drive smaller-scale deployments with simplified integration requirements.
Healthcare Providers concentrate premium procurement; Warehousing Facilities expand fastest through risk-transfer contracting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Real-Time Locating Systems originated in United States defense and aerospace applications during the 1990s before migrating into commercial healthcare and logistics. The technology's spread followed semiconductor manufacturing corridors and medical device clusters where precision positioning created measurable operational value. Today deployment intensity correlates with regulatory pressure for asset traceability and autonomous system coordination.
United States
FDA device traceability mandates accelerate hospital procurement for surgical instrument accountability. FCC rulings on 6.5-8.5 GHz ultra-wideband spectrum enable centimeter-grade precision for autonomous mobile robot coordination. Boston's medical technology cluster and Austin's semiconductor logistics corridor concentrate domestic demand for clinical-grade and industrial positioning systems.
Germany
EMA medical device regulations compress vendor selection toward certified platforms with embedded governance capabilities. EU AI Act data minimization requirements reshape product architecture for personnel tracking deployments. Munich and Frankfurt hospital systems prioritize infrared-ultrasound fusion systems for patient flow optimization and bed management automation.
Japan
METI smart hospital initiative mandates patient flow optimization across Tokyo and Osaka medical clusters. PMDA medical device regulations extend hardware approval cycles for clinical-grade location systems. Automotive manufacturers in Nagoya and semiconductor fabricators in Kyushu adopt ultra-wideband system-on-chip solutions for precision tool tracking.
China
MIIT industrial internet policies promote asset tracking integration within smart factory frameworks. GB standards for radio frequency equipment constrain cross-border technology transfer and hardware certification pathways. Yangtze River Delta manufacturing hubs and Pearl River Delta logistics corridors drive warehouse automation demand for Bluetooth Low Energy deployments.
India
PLI scheme for electronics manufacturing attracts RTLS hardware assembly to Tamil Nadu and Karnataka. CDSCO medical device regulations create compliance barriers for imported clinical-grade systems. Domestic logistics buyers in Maharashtra and Telangana reduce import dependency through localized hardware sourcing and system integration partnerships.
Global Real-Time Locating Systems (RTLS) Market Competitive Landscape
Premium-margin players sit above commodity-margin players across precision-grade positioning capabilities and regulatory certification depth. The vendor base stratifies between end-to-end platform providers, component specialists, and system integrators. Three archetypes dominate: hardware-software bundlers capturing enterprise contracts, silicon specialists supplying high-density inventory environments, and clinical-grade accuracy providers serving hospital accreditation requirements. Competitive moves concentrate on strategic partnerships with warehouse management system vendors and technology licensing for 5G private network convergence.
Within the hardware-software bundler tier, Zebra Technologies Corporation and Impinj, Inc. occupy positions reflecting different specialization vectors. Zebra Technologies Corporation exemplifies the enterprise asset visibility archetype through its end-to-end portfolio breadth. Impinj, Inc. represents the RAIN RFID silicon specialization model for high-density inventory environments. CenTrak, Inc. anchors the clinical-grade accuracy segment through proprietary fusion architectures serving hospital accreditation requirements.
| Leading Market Players |
|---|
| Zebra Technologies Corporation |
| Impinj, Inc. |
| CenTrak, Inc. |
| Securitas AB |
| Ubisense Group |
| TeleTracking Technologies, Inc. |
| Savi Technology |
| Sewio Networks |
| Sonitor Technologies AS |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up hardware specialists now dominate mid-tier RTLS component supply, concentrating bargaining power with Taiwanese and South Korean foundries while enforcing rigid price discipline on downstream system integrators. This ownership pattern compresses margin buffers for European and American buyers facing EU AI Act compliance premiums and FDA certification costs.
Pricing Analysis
Subscription-based outcome contracts now anchor enterprise procurement, with third-party logistics operators negotiating per-location-event pricing that transfers infrastructure risk to vendors. Price differentiation rests on FCC ultra-wideband certification tier and embedded data governance module depth, with clinical-grade platforms commanding substantial premiums over warehouse BLE alternatives. Cost compression in Bluetooth Low Energy infrastructure is intensifying because sensor commoditization outpaces firmware innovation. Warehouse operators exhibit highest price sensitivity, while German hospital systems prioritize pre-certified compliance over unit economics.
Supply Chain Analysis
Dual-sourcing requirements now mandate multi-supplier qualification for RAIN RFID silicon, with buyers qualifying both Taiwanese and South Korean foundries to mitigate geopolitical disruption exposure. Component fabrication concentrates in Taiwan, South Korea, and China, with final assembly migrating to Tamil Nadu and Karnataka under India's PLI scheme. Raw material dependencies span gallium arsenide substrates, FR-4 laminates, and lithium coin cells. Single-source vulnerability concentrates in advanced UWB system-on-chip designs where only two vendors maintain qualified production. Distribution runs through authorized system integrators serving Boston medical clusters and Austin semiconductor corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The RTLS market reads as a late-cycle quality story where FDA traceability mandates and EU AI Act governance requirements concentrate procurement toward certified platforms with embedded compliance architectures. Demand is shifting decisively toward premium specifications that bundle hardware, firmware, and audit-trail capabilities.
For Market Incumbents: Extend platform bundling depth to capture subscription-based outcome contracts before emerging cloud-native entrants displace capital-expenditure procurement models. Prioritize backward integration into UWB system-on-chip design to reduce dependency on Taiwanese foundry allocation. Reinforce channel control through exclusive partnerships with warehouse management system vendors lacking native API support for real-time location feeds. For New Entrants and Emerging Players: System integrators serving mid-tier Indian logistics operators represent the most accessible entry vector, as domestic buyers reduce import dependency through localized hardware sourcing. Target Bluetooth Low Energy deployments in Maharashtra and Telangana warehousing corridors where price sensitivity outweighs precision requirements. Pursue white-label partnerships with established German healthcare distributors to bypass EMA certification timeline barriers. For Investors and Strategic Acquirers: Enterprise software conglomerates pursuing industrial IoT platform consolidation are the most active acquirer in this space, particularly those seeking to embed location intelligence into existing ERP and WMS offerings. Acquisition targets should display certified-platform status under FDA and EU AI Act frameworks plus installed base concentration in surgical suite or semiconductor fab applications. Watch for inflection when 5G private network slicing achieves commercial scale in campus-scale industrial deployments.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Combines UWB positioning with existing WMS stacks to eliminate middleware development costs for Austin semiconductor logistics operators. |
| Regulatory Certification Pathway | EMA pre-certification modules accelerate hospital procurement cycles in Munich and Frankfurt systems facing EU AI Act deadlines. |
| Strategic Partnership | System integrator alliances with Boston medical technology clusters embed RTLS into surgical instrument traceability workflows. |
| Geographic Expansion | Tamil Nadu assembly operations under India's PLI scheme reduce landed cost for domestic logistics buyers in Telangana. |
| Acquisition of Specialist Firm | UWB system-on-chip designers in Austin and Boston concentrate antenna expertise scarce across broader RF engineering talent pools. |
Research Methodology
Direct dialogue with hospital biomedical engineers, GPO contracts managers, semiconductor fab operations directors, and third-party logistics procurement leads grounded qualitative assessments in operational reality. Secondary validation drew from FDA 510(k) filings, EMA medical device registration databases, FCC equipment authorization records, and hyperscaler warehouse automation capex disclosures. Bottom-up and top-down triangulation reconciled unit economics from component vendors with aggregate demand signals from end-user procurement cycles.
Bottom-up modeling segmented volume and value across technology type, precision grade, regulatory certification tier, and end-use vertical throughout the forecast period. CAGRs derived from installed base expansion rates, replacement cycle compression, and pricing trajectory analysis for subscription versus capital expenditure models. Industry-specific inputs included surgical instrument traceability mandate compliance timelines, ultra-wideband spectrum allocation rulings, and smart hospital initiative funding flows from Japan METI.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to geopolitical disruption in Taiwanese foundry operations, evolving IEEE 802.15.4z interoperability mandates, and 5G private network convergence adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Asset Tags Market
Sensors
North America Eye Tracking Solutions Market
Sensors
Temperature Data Loggers Market
Sensors
Refrigeration Monitoring Market
Sensors
Drain Camera Market
Sensors
Lidar Market
Sensors
Industrial Barcode Scanners Market
Sensors
Europe Lidar Market
Sensors
Global Remote Tank Monitoring System Market
Sensors
Digital Olfaction Products Market
Sensors
RFID Smart Cabinet Market
Sensors
APAC Wireless Sensors Market
Sensors
Lidar in Construction Market
Sensors
Facial Tracking Solution Market
Sensors
Global Weather Monitoring Solutions and Services Market
Sensors
Digital Compass (E-Compass) Market