
 Cloud Backup and Recovery Market | 2026-2036
Cloud Backup and Recovery Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Backup and Recovery Market Analysis
Managed service provider channels is tilting toward hybrid delivery models that blend on-premises appliances with public cloud vaults. Microsoft Corporation leverages its Azure Stack integration to anchor enterprise workloads across regulated industries. Veeam Software specializes in virtual machine backup software that competes directly with native hypervisor tools. IBM Corporation extends its mainframe heritage into cloud-native disaster recovery orchestration for financial services clients.
Cloud backup and recovery encompasses automated data replication, snapshot management, and granular restoration services operating across distributed infrastructure with recovery point objectives typically measured in minutes. The technology protects against ransomware encryption, site failures, and accidental deletion by maintaining immutable copies in geographically separated repositories. Disaster Recovery as a Service commands premium pricing from enterprises requiring sub-hour failover guarantees for revenue-critical applications. Multi-Cloud deployment models are gaining traction as buyers seek to avoid single-vendor lock-in and exploit regional price arbitrage across AWS, Azure, and Google Cloud platforms.
GDPR data sovereignty mandates from European regulators, SEC cybersecurity disclosure rules from US authorities, and ISO 27001 certification requirements collectively shape vendor product roadmaps and customer procurement criteria. HIPAA business associate agreements impose specific encryption and access audit standards on healthcare cloud backup implementations. Stakeholders must evaluate whether their recovery architectures satisfy emerging cross-border data transfer restrictions before committing to long-term cloud storage contracts.
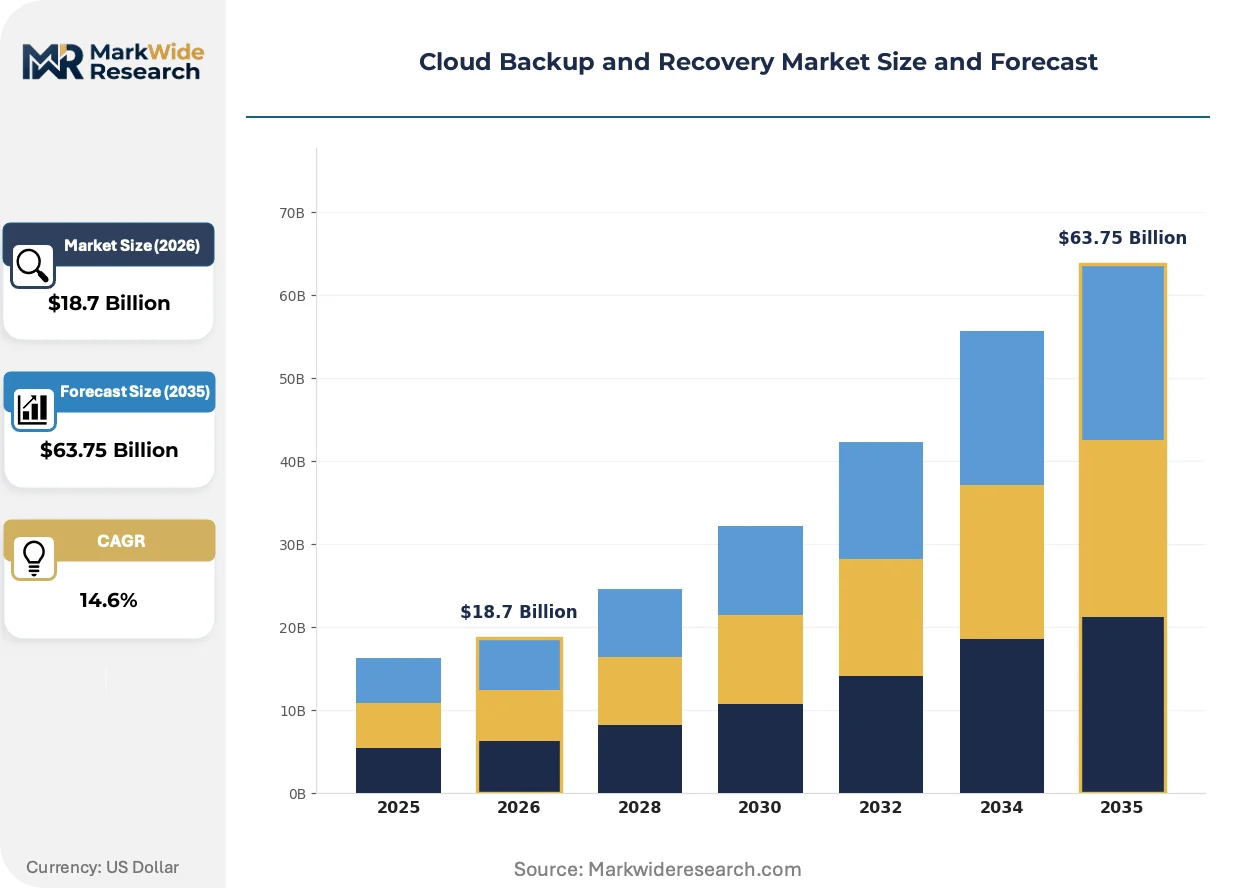
Market Dynamics
Ransomware frequency is forcing enterprises to abandon tape-based archival systems in favor of immutable cloud object storage with air-gapped recovery capabilities. This threat vector has compressed backup refresh cycles from five-year hardware rotations to continuous software-defined architectures.
Growth Catalysts
- GDPR Article 32 mandates:European data controllers must demonstrate restoration capability within specific timeframes, driving automated disaster recovery orchestration investments across German automotive and French pharmaceutical supply chains.
- Healthcare digitization:Hospital systems migrating electronic health records to cloud infrastructure require HIPAA-compliant backup architectures with business associate agreement audit trails for protected health information.
- AI training data protection:Machine learning pipelines generating proprietary datasets demand versioned snapshot management to prevent model corruption and enable experiment rollback.
Market Restraints
- Egress bandwidth economics:Cloud storage retrieval fees from hyperscale providers create unpredictable cost spikes during large-scale recovery events, particularly for media and entertainment archives exceeding petabyte scale.
- Encryption key sovereignty:Cross-border data residency requirements in Switzerland, Germany, and France prevent centralized key management, fragmenting operational workflows across national boundaries.
- Legacy mainframe dependencies:Financial institutions maintaining COBOL-based core banking systems face integration gaps with API-native cloud backup platforms, extending hybrid infrastructure complexity.
Strategic Opportunities
- Edge manufacturing sites:Industrial IoT deployments at remote production facilities in India and Brazil lack local backup infrastructure, creating demand for converged appliance-plus-cloud gateway solutions.
- EU AI Act documentation requirements:High-risk AI system operators must maintain training data lineage records, expanding addressable market for governance-integrated backup platforms with immutable audit logs.
- Container-native protection:Kubernetes stateful workload backup remains underserved by incumbent tools, opening whitespace for persistent volume snapshot automation in DevOps environments.
Industry Challenges
- Immutable storage expertise:Shortage of architects proficient in object-lock configurations and write-once-read-many implementations delays enterprise deployment timelines.
- Multi-cloud orchestration complexity:Heterogeneous API standards across AWS, Azure, and Google Cloud platforms force custom integration development for unified recovery workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Backup and Recovery Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $63.75 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Backup as a Service, Disaster Recovery as a Service, Hybrid Backup, Managed Backup Deployment Model: Public Cloud, Private Cloud, Multi-Cloud, On-Premises End User: SMEs, Large Enterprises, Government Agencies, Educational Institutions Solution: File Backup, Image-Based Backup, Continuous Data Protection, Tape Backup |
| Companies Covered | Amazon Web Services, Microsoft Corporation, Google LLC, IBM Corporation, Dell Technologies, Veeam Software, Commvault Systems, Veritas Technologies, Acronis International GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Backup and Recovery Market Emerging Trajectories
Backup infrastructure is fragmenting from monolithic appliances toward composable software stacks that embed directly into workload orchestration layers. This architectural shift is compressing vendor margins while expanding addressable surface area for automation and policy-driven data management.
Immutable object storage is hybridizing with traditional block-based replication to create tiered protection architectures. Healthcare providers in the United States are deploying this combination to satisfy HIPAA encryption requirements while maintaining sub-minute recovery point objectives for emergency department systems. The convergence is collapsing the historical separation between primary storage and backup silos, forcing incumbent vendors to reposition around data mobility rather than point-in-time capture.
SEC cybersecurity disclosure rules are mandating incident reporting timelines that exceed manual recovery capabilities. Publicly traded enterprises must now document material cybersecurity events within four business days, compelling investment in automated forensics and pre-staged recovery environments. Financial services firms in New York and London are responding by integrating backup telemetry directly into security operations centers for real-time compromise detection.
Subscription consumption models are displacing perpetual license procurement for mid-market buyers. Managed service providers in Germany and the Netherlands are packaging backup-as-a-service with endpoint detection and response, consolidating vendor relationships for customers below five hundred employees. This bundling is shifting pricing power toward distributors with multi-vendor integration capabilities and compressing standalone software margins.
Cloud Backup and Recovery Market Segmentation
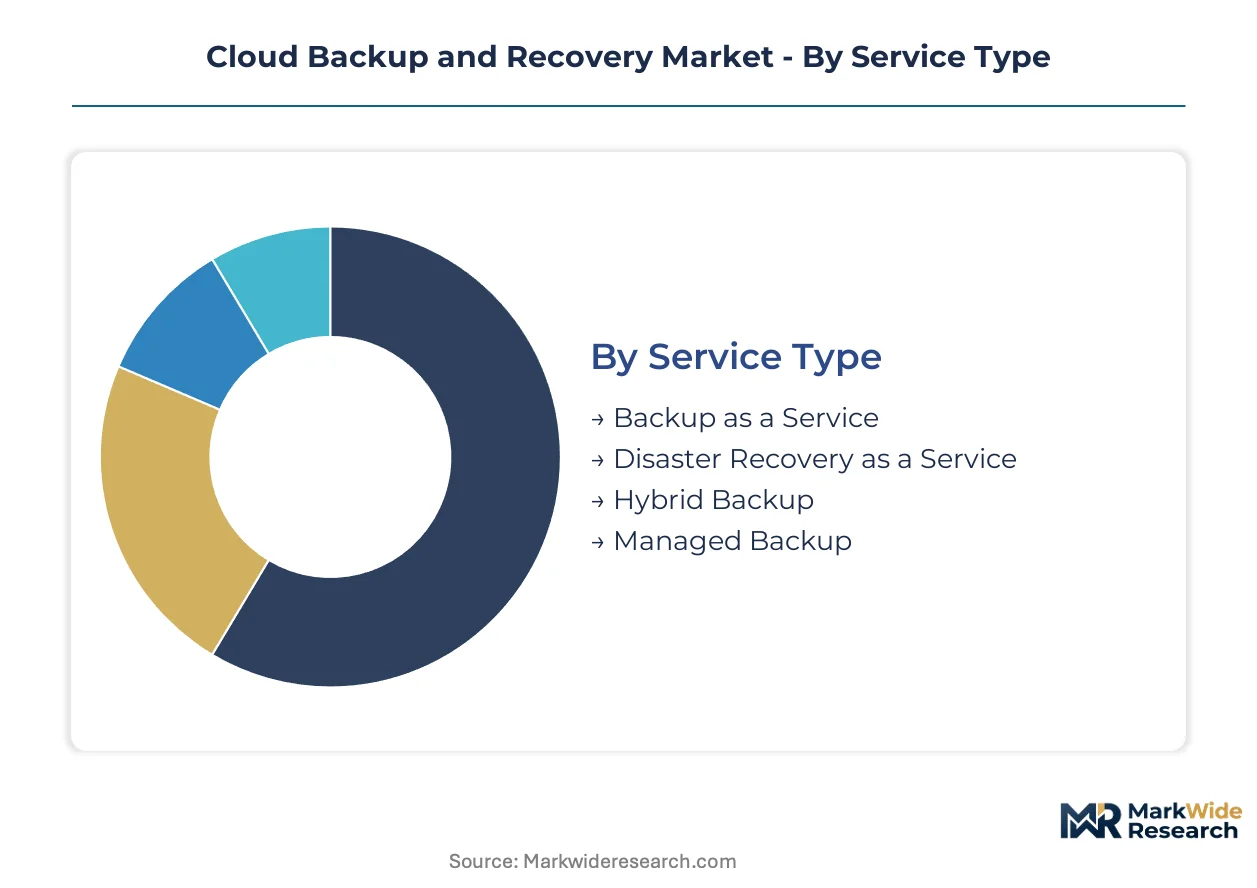
Cloud backup and recovery vendors architect product portfolios around recovery velocity requirements, compliance postures, and infrastructure heterogeneity. Segment boundaries blur as hybrid architectures collapse traditional distinctions between primary storage and protection tiers.
Service Type:
Backup as a Service refreshes fastest with quarterly feature releases, while Managed Backup contracts lock in three-year cycles. Disaster Recovery as a Service commands the longest sales cycles due to failover certification requirements.
- Backup as a Service:Automated agent-based replication to cloud object storage with policy-driven retention. Healthcare providers in Germany adopt this model to satisfy GDPR Article 32 restoration mandates without capital expenditure.
- Disaster Recovery as a Service:Orchestrated failover to pre-staged cloud environments with sub-hour recovery time objectives. Financial services firms in New York and London pay premium pricing for guaranteed availability of trading platforms.
- Hybrid Backup:Combines local appliance caching with cloud vault tiering for bandwidth efficiency. Industrial manufacturers deploy this architecture to protect proprietary CAD files at edge facilities.
- Managed Backup:Third-party operational responsibility for backup scheduling, verification, and restoration testing. Mid-market buyers below five hundred employees consolidate this with endpoint security services.
Backup as a Service dominates installed base. Disaster Recovery as a Service is where expansion concentrates.
Deployment Model:
Cost tiers separate commodity public cloud storage from sovereign private deployments. Multi-Cloud strategies command implementation premiums of forty to sixty percent over single-vendor alternatives.
- Public Cloud:Shared infrastructure with consumption-based pricing and hyperscale redundancy. Media archives exceeding petabyte scale exploit AWS Glacier Deep Archive and Azure Archive Storage for cold tier economics.
- Private Cloud:Dedicated tenant environments with single-tenancy isolation for regulated workloads. Swiss banks mandate this model to satisfy FINMA data residency requirements for client portfolios.
- Multi-Cloud:Active-active replication across AWS, Azure, and Google Cloud to eliminate single-vendor dependency. Enterprises with cross-border operations deploy this to navigate divergent national data sovereignty laws.
- On-Premises:Air-gapped infrastructure with physical network isolation for ransomware protection. Critical infrastructure operators in energy and water utilities maintain this as immutable last-resort recovery.
Public Cloud captures volume leadership. Multi-Cloud is gaining share fastest among enterprises with complex regulatory footprints.
End User:
Customer type determines solution complexity and sales channel. Large Enterprises negotiate custom service level agreements, while SMEs purchase through managed service provider bundles.
- SMEs:Standardized backup-as-a-service packages with limited customization and self-service restoration portals. German automotive suppliers with fewer than two hundred employees procure through regional MSPs.
- Large Enterprises:Global deployments with centralized policy management and federated recovery orchestration. Pharmaceutical multinationals require this scale to protect distributed R&D datasets.
- Government Agencies:Classified or sensitive workloads with FedRAMP or equivalent certification requirements. Defense contractors in the United States maintain separate enclaves for controlled unclassified information.
- Educational Institutions:Research data protection with grant-mandated retention periods and student privacy compliance. University hospital systems in France integrate this with CNIL audit requirements.
Large Enterprises dominate installed base. SMEs represent the steepest expansion trajectory as MSP channel penetration deepens.
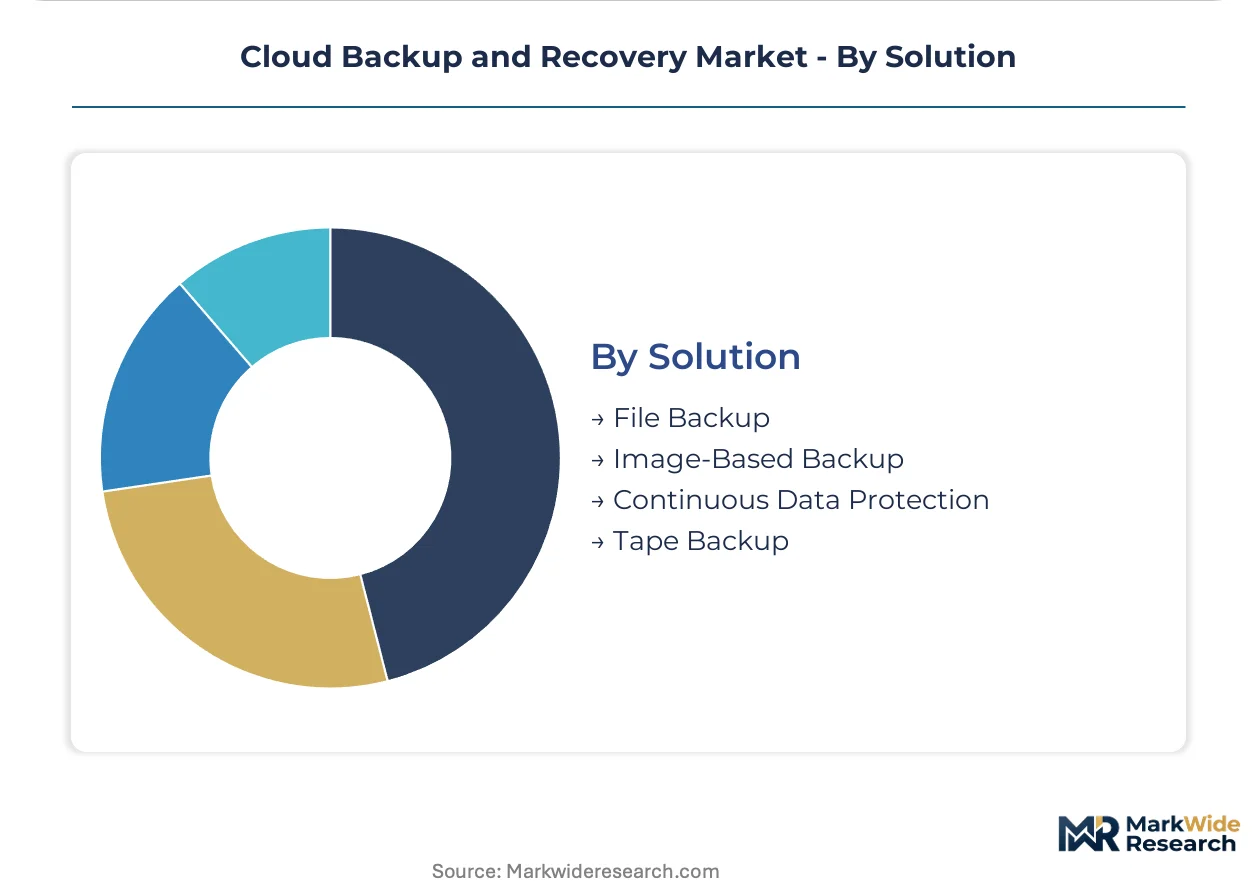
Solution:
Technology maturity spans decades, from tape's forty-year heritage to container-native continuous protection. Margin profiles invert this timeline, with newer methods commanding premium pricing.
- File Backup:Granular restoration of individual documents and directories through incremental scanning. Legal departments in London deploy this for litigation hold and e-discovery compliance.
- Image-Based Backup:Full-system capture including operating system, applications, and configuration state. Manufacturing floor controllers with embedded Windows installations require this for bare-metal recovery.
- Continuous Data Protection:Journal-based replication with point-in-time recovery granularity measured in seconds. Trading floors in Singapore implement this to eliminate data loss windows for transaction databases.
- Tape Backup:Offline magnetic media with thirty-year archival stability for regulatory retention. Healthcare systems in the United States maintain this for HIPAA-mandated long-term patient record preservation despite cloud migration.
File Backup dominates installed base. Continuous Data Protection is where expansion concentrates as recovery point objectives compress.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Transatlantic fiber corridors landing at Bude and Bilbao anchor Europe's data sovereignty architecture. Submarine cable density determines latency thresholds for synchronous replication across national boundaries.
Germany
Automotive suppliers in Stuttgart and Munich demand sub-hour recovery point objectives for CAD vaults. GDPR Article 32 mandates documented restoration capability within specific timeframes. Frankfurt's financial district hosts redundant cloud zones satisfying FINMA cross-border requirements.
United States
Healthcare systems migrating Epic deployments require HIPAA-compliant immutable storage. SEC cybersecurity disclosure rules compress incident reporting to four business days. New York trading floors and Silicon Valley hyperscale campuses drive premium DRaaS pricing.
United Kingdom
Legal services firms in London implement litigation-hold backup for e-discovery compliance. The Information Commissioner's Office enforces strict breach notification timelines. Manchester's media production cluster exploits cold-tier economics for petabyte-scale archives.
France
Pharmaceutical multinationals near Paris maintain training data lineage for EU AI Act documentation. CNIL audits impose granular access logging on cloud implementations. Lyon and Toulouse aerospace suppliers protect proprietary simulation datasets.
Switzerland
Private banking in Zurich mandates FINMA-certified single-tenancy isolation for client portfolios. Cross-border key management fragmentation complicates centralized orchestration. Geneva commodity traders require jurisdictional separation of trade execution logs.
Cloud Backup and Recovery Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in the protection stack. Hyperscale cloud providers anchor consolidated infrastructure layers while independent software vendors fragment across workload-specific niches. Two strategic archetypes dominate: vertically integrated stacks spanning compute through recovery orchestration, and best-of-breed point solutions embedding into DevOps pipelines. Competitive moves concentrate on API-native partnerships and sovereign cloud certification acquisition.
Within the enterprise software tier, Veeam Software and Commvault Systems exemplify divergent architectural philosophies. Microsoft Corporation anchors hybrid delivery through Azure Stack integration across regulated verticals. These three occupy positions spanning virtualization-native protection through cloud-native orchestration, reflecting the market's bifurcation between workload-optimized tools and platform-extensible frameworks.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Corporation |
| Google LLC |
| IBM Corporation |
| Dell Technologies |
| Veeam Software |
| Commvault Systems |
| Veritas Technologies |
| Acronis International GmbH |
| Others |
Supply Flow & Price Mechanics
Overcapacity in hyperscale cloud infrastructure across Virginia and Frankfurt is compressing storage pricing tiers while forcing vendors toward value-added orchestration layers. This utilization dynamic rewards buyers with consumption elasticity but squeezes margin capture for undifferentiated capacity providers.
Pricing Analysis
Volume-discount tiering structures stratify across enterprise commitment levels, with reserved capacity contracts commanding thirty to fifty percent reductions against on-demand rates. Price differentiation hinges on recovery time objective guarantees and GDPR compliance certification tiers. Pricing pressure stems from hyperscale providers absorbing margin to capture workload gravity. Mid-market buyers exhibit highest price sensitivity, while financial services firms accept premium positioning for sub-hour failover assurances.
Supply Chain Analysis
Export-control regimes limiting cryptographic technology flows shape hardware security module sourcing and key management appliance distribution. Supply concentrates in Taiwan for semiconductor components, China for assembly capacity, and Ireland for EU data residency infrastructure. Raw material dependencies include NAND flash memory, specialized encryption processors, and fiber-optic transmission gear. Single-source vulnerability runs through Taiwan's foundry concentration. Distribution runs through hyperscale direct contracts and managed service provider channel partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market exhibits cyclical recovery characteristics as ransomware frequency refreshes replacement cycles and regulatory mandates force compliance-driven procurement. Enterprise refresh waves typically follow three to five year patterns tied to infrastructure depreciation schedules.
For Market Incumbents: Insulate recurring revenue streams by embedding backup orchestration deeper into customer DevOps pipelines. Acquire container-native protection capabilities to counter Kubernetes-focused challengers. Pursue sovereign cloud certifications in Germany, France, and Switzerland to preempt regulatory fragmentation.
For New Entrants and Emerging Players: Pursue edge manufacturing sites in India and Brazil where converged appliance-plus-cloud solutions face minimal incumbent saturation. Target container-native persistent volume snapshot automation as the most penetrable whitespace. Lead with API-first integration positioning to bypass entrenched channel relationships.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across software-defined backup platforms as subscription models displace appliance-heavy delivery. Long-term viability favors orchestration-layer specialists over capacity-centric vendors. Acquisition targets should demonstrate multi-cloud API abstraction capabilities. Watch hyperscale provider backup service expansion as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Immutable Storage Certification | FedRAMP and FINMA certifications unlock regulated financial services procurement pipelines. |
| Kubernetes-Native Protection Launch | Container workload backup addresses underserved DevOps environments with persistent volume automation. |
| Multi-Cloud Orchestration Partnership | API integration across AWS, Azure, and Google Cloud eliminates single-vendor dependency for enterprises. |
| Edge Appliance Distribution Expansion | Converged gateway solutions capture remote manufacturing sites lacking local backup infrastructure. |
| AI Training Data Lineage Integration | EU AI Act documentation requirements expand addressable market for governance-embedded backup platforms. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of hyperscaler capex disclosures, SEC cybersecurity incident filings, and GDPR enforcement action records. Primary interviews engaged chief information security officers, cloud infrastructure architects, healthcare IT compliance leads, and managed service provider operations directors. Secondary sources included hyperscaler service documentation, regulatory enforcement databases, and industry association breach reports. Bottom-up sizing triangulated against top-down IT spending allocation models.
Forecast inputs incorporate deployment model migration rates, regulatory mandate implementation timelines, and ransomware incident frequency trends. Segmentation dimensions span service type, deployment architecture, organization size tier, solution technology maturity, and vertical regulatory intensity. CAGRs derive from weighted scenario analysis across adoption curve projections. Industry-specific inputs include GDPR Article 32 enforcement velocity and SEC cybersecurity disclosure compliance cost estimates.
Macroeconomic conditions sit as an overlay; deviation in enterprise IT budget allocation or hyperscale pricing aggression would shift the trajectory. Forecasts assume continued regulatory tightening without material relaxation. Material shifts in cross-border data transfer restrictions or hyperscale provider backup service bundling would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Europe Digital Shipyard Market
Digital Solutions
Inventory Management Market
Digital Solutions
Global DDI Market
Digital Solutions
Digital Clothing Market
Digital Solutions
Mobile Collaboration Market
Digital Solutions
Email Marketing Market
Digital Solutions
Decision Management Applications Market
Digital Solutions
Global Digital Asset Management Software Market
Digital Solutions
Supply Chain Digital Twin Market
Digital Solutions
Global Sharing Economy Market
Digital Solutions
North America Product Design and Development Services Market
Digital Solutions
North America Smart Card Market
Digital Solutions
IT Asset Management Market
Digital Solutions
Docketing Solution Market
Digital Solutions
Search Engine Optimization Services Market
Digital Solutions
Automatic Identification and Data Capture Market