
 Cloud API Market | 2026-2036
Cloud API Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud API Market Intelligence
Cloud-native engineering talent scarcity is bifurcating vendor strategies between full-stack platform consolidation and specialized API toolchains. Microsoft Corporation leverages its enterprise installed base to anchor hybrid deployment API services across Azure ecosystems. Google LLC competes through Kubernetes-native API management and deep open-source integration with developer workflows. Amazon Web Services, Inc. dominates infrastructure-level API primitives that underpin serverless compute and storage orchestration.
Cloud APIs are programmatic interfaces that expose cloud infrastructure services, application functions, or data resources through standardized protocols such as REST, GraphQL, or gRPC, enabling automated resource provisioning, service composition, and cross-platform interoperability. Public cloud deployment leads volume adoption while hybrid cloud configurations capture expanding margin pools from regulated enterprises requiring on-premises data sovereignty. Authentication APIs and data integration APIs sustain the fastest growth as zero-trust security architectures and real-time analytics pipelines proliferate across IT consultancies and managed service providers.
EU GDPR and the EU AI Act impose strict data residency and algorithmic transparency requirements that shape API gateway design and cross-border data flow architectures. NIST cybersecurity frameworks in the United States and BIS cloud security guidelines in India further segment compliance obligations by jurisdiction. Stakeholders must monitor evolving interoperability mandates and sovereignty regulations to determine API platform investment sequencing and geographic rollout prioritization.
Market Dynamics
Enterprise migration from monolithic architectures to microservices is fragmenting API consumption patterns and forcing gateway vendors to support polyglot protocol meshes.
Growth Catalysts
- Open Banking Mandates:PSD2 in Europe and UPI expansion in India compel financial institutions to expose core banking functions through standardized REST interfaces, accelerating API gateway procurement cycles.
- Zero-Trust Security Architectures:NIST frameworks in the United States mandate continuous authentication flows, driving demand for OAuth 2.0 and OIDC token management services across federal contractors.
- Serverless Compute Proliferation:Function-as-a-service deployments require fine-grained API triggers for event-driven orchestration, expanding addressable use cases beyond traditional enterprise integration.
Market Restraints
- Data Residency Compliance Costs:GDPR Article 44 and EU AI Act algorithmic transparency rules impose redundant infrastructure requirements for cross-border API traffic, elevating total cost of ownership.
- Gateway Vendor Concentration:Critical API management capabilities cluster among hyperscale cloud providers, creating single-point-of-failure exposure for multi-cloud enterprises.
- GraphQL Performance Overhead:Complex query resolution patterns consume disproportionate compute resources compared to REST implementations, limiting adoption in latency-sensitive industrial IoT deployments.
Strategic Opportunities
- Regulated Industry Cloud Sovereignty:Germany's Gaia-X initiative and India's MeitY data localization directives create captive demand for API infrastructure deployed within national jurisdictional boundaries.
- Healthcare Interoperability:HIPAA-mandated FHIR APIs in the United States open reimbursement-linked data exchange workflows previously locked behind proprietary EHR silos.
- Edge-Native API Meshes:Convergence of 5G network slicing and lightweight WASM runtimes enables sub-10ms API response times for autonomous vehicle telemetry and industrial control systems.
Industry Challenges
- Platform Engineering Talent Scarcity:Kubernetes-native API gateway configuration and service mesh topology design require skills possessed by fewer than 15% of existing enterprise architects.
- Multi-Cloud Credential Sprawl:Identity federation across AWS IAM, Azure AD, and Google Cloud Identity creates authentication chain vulnerabilities that breach detection systems struggle to trace.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud API Market |
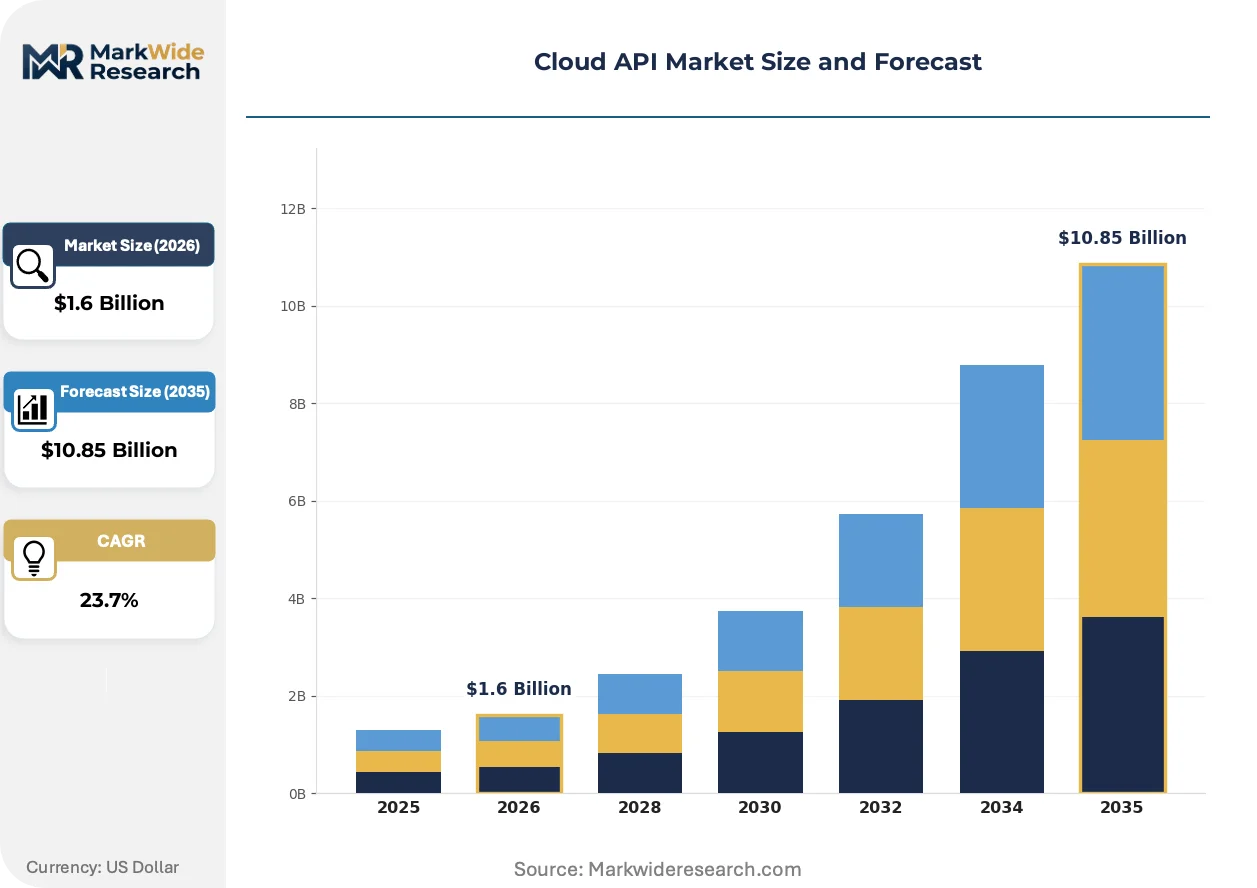
| Market Size in 2026 | $1.6 Billion |
| Market Size in 2035 | $10.85 Billion |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Community Cloud Solution Type: Authentication APIs, Data Integration APIs, Messaging APIs, Payment APIs, Storage APIs Application: Mobile App Development, Web Development, Enterprise Integration, E-commerce, Content Management End User: Software Developers, IT Consultancies, Independent Vendors, Managed Service Providers |
| Companies Covered | Amazon Web Services, Inc., Microsoft Corporation, Google LLC, IBM Corporation, Oracle Corporation, Salesforce.com, Inc., Red Hat, Inc., SAP SE, Broadcom Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud API Market Strategic Shifts & Innovations
API delivery architectures are compressing toward edge-native execution models that minimize round-trip latency while preserving centralized governance policies.
WebAssembly (Wasm) runtime modules are embedding directly into API gateway data planes to execute custom authentication logic and payload transformation at wire speed. Telecommunications operators and high-frequency trading platforms are deploying these modules at sub-millisecond initialization thresholds. The technology is miniaturizing the boundary between network infrastructure and application logic, collapsing traditional OSI layer distinctions.
EU AI Act risk classification tiers are mandating algorithmic audit trails for API-mediated machine learning inference, particularly in credit scoring and recruitment automation use cases. API providers must now expose model provenance metadata through standardized headers. Financial services deployers in France and Germany are restructuring their MLOps pipelines to capture these provenance signals before the enforcement deadlines.
Developer self-service portals are displacing traditional IT ticket-based API provisioning workflows in enterprise technology organizations. Platform engineering teams at retail and logistics conglomerates are embedding usage-based billing and automated rate-limiting into these portals. This behavioral shift is most pronounced in India and the United States, where cloud-native maturity enables product-led API consumption models.
Cloud API Market Segmentation
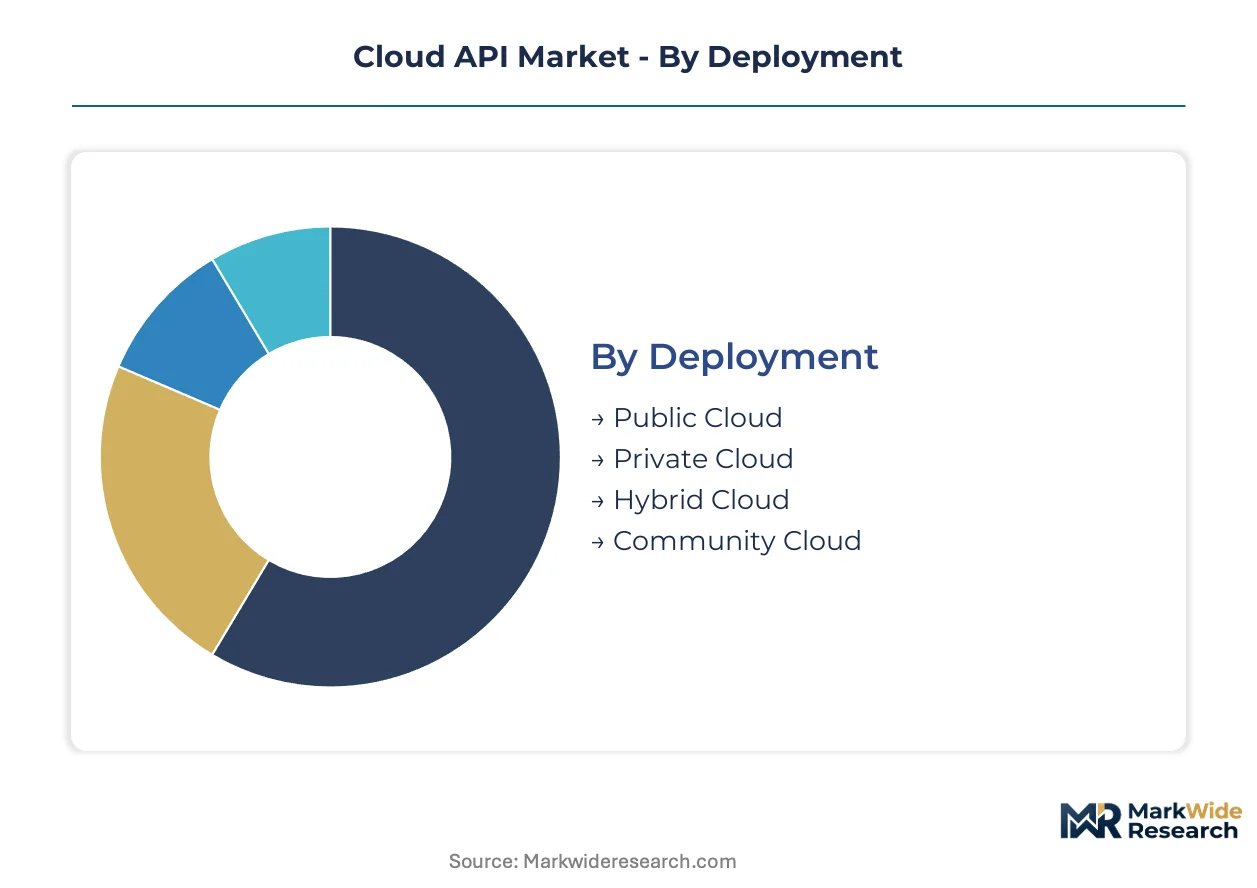
Cloud API market segmentation reveals divergent procurement patterns across deployment modes and solution architectures. Channel strategies vary sharply between hyperscale cloud marketplaces and specialized API gateway vendors. Understanding these segment boundaries enables precise platform positioning and geographic rollout sequencing.
Deployment:
Public cloud APIs flow predominantly through hyperscale provider marketplaces, while private and hybrid configurations route through systems integrators and managed service channels.
- Public Cloud:Multi-tenant API infrastructure delivered over shared compute pools with pay-per-call metering. Demand concentrates among software developers in the United States building consumer-facing mobile applications, constrained by egress bandwidth pricing volatility.
- Private Cloud:Dedicated API gateway appliances deployed within enterprise data centers or single-tenant virtual private clouds. Financial institutions in Germany favor this mode for core banking API exposure under Bafin operational resilience mandates.
- Hybrid Cloud:Unified control planes spanning on-premises gateways and public cloud endpoints. IT consultancies in India deploy these architectures for manufacturing clients navigating BIS cloud security guidelines.
- Community Cloud:Shared API infrastructure serving consortia with common compliance requirements. Healthcare networks leverage these deployments for HIPAA-aligned FHIR data exchange.
By volume, Public Cloud leads. By growth pace, Hybrid Cloud is expanding most quickly.
Solution Type:
Cost tier stratification separates authentication and payment APIs at premium pricing from storage and messaging APIs competing on commodity throughput metrics.
- Authentication APIs:OAuth 2.0 and OIDC token services enabling zero-trust identity verification. Zero-trust mandates from NIST cybersecurity frameworks drive federal contractor procurement in the United States.
- Data Integration APIs:ETL pipeline connectors and real-time streaming interfaces normalizing heterogeneous data sources. Enterprise integration platforms in India absorb these tools for UPI-linked financial data orchestration.
- Messaging APIs:Asynchronous notification and event streaming infrastructure. E-commerce platforms embed these for order status propagation.
- Payment APIs:PCI-DSS compliant transaction processing interfaces. PSD2 open banking regulations in Europe mandate standardized REST payment initiation.
- Storage APIs:Object and block storage abstraction layers with S3-compatible semantics. Latency-sensitive applications avoid these for edge-native alternatives.
Authentication APIs command the highest per-call pricing. Data Integration APIs are gaining share fastest.
Application:
Volume concentration follows mobile-first development patterns, while margin pools accumulate in regulated enterprise integration workloads.
- Mobile App Development:Backend-as-a-service APIs powering iOS and Android client applications. Consumer technology startups in India represent the dominant consumption cluster.
- Web Development:Server-side rendering and Jamstack architecture APIs. Frontend frameworks drive automated provisioning through developer self-service portals.
- Enterprise Integration:Legacy system modernization through API-led connectivity. Manufacturing conglomerates in Germany deploy these for ERP synchronization.
- E-commerce:Catalog, inventory, and fulfillment API orchestration. Omnichannel retailers require sub-100ms response times for cart abandonment reduction.
- Content Management:Headless CMS APIs decoupling editorial workflows from presentation layers. Media organizations favor GraphQL implementations for flexible content fetching.
Enterprise Integration carries the steepest project values. Mobile App Development shows the shallowest growth trajectory.
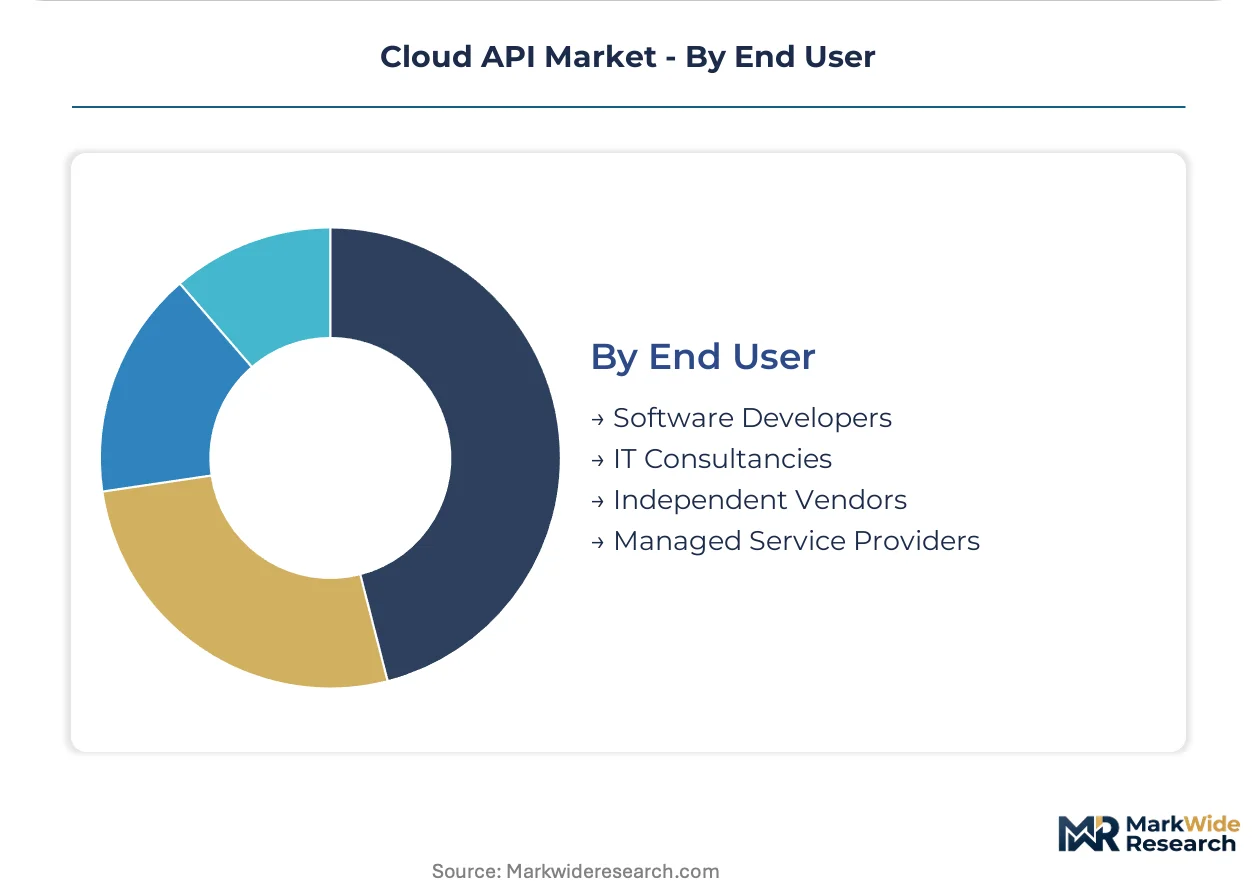
End User:
Customer maturity determines procurement sophistication, with managed service providers consolidating fragmented enterprise demand.
- Software Developers:Individual practitioners and product teams consuming APIs through documentation-driven self-service. Open-source SDK availability shapes platform selection.
- IT Consultancies:Systems integrators embedding API management into client transformation programs. These intermediaries intermediate between vendor roadmaps and enterprise requirements.
- Independent Vendors:Software companies exposing proprietary functionality through partner-facing APIs. Monetization models range from freemium tiers to enterprise licensing.
- Managed Service Providers:Outsourced operations teams assuming full lifecycle API governance. Healthcare and financial services verticals outsource to these specialists for compliance burden absorption.
IT Consultancies intermediate the largest transaction volumes. Managed Service Providers are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NIST cybersecurity frameworks in the United States anchor the regulatory foundation for Cloud API governance across major demand centers. Procurement patterns diverge sharply between federal contractor mandates in North America, open banking directives in Europe, and data localization requirements in Asia-Pacific.
United States
Federal zero-trust mandates from NIST drive OAuth 2.0 procurement cycles among defense contractors and healthcare systems. HIPAA-mandated FHIR APIs open reimbursement-linked data exchange workflows for EHR interoperability. Silicon Valley clusters and Seattle metro areas concentrate developer self-service portal deployments for cloud-native enterprises.
Germany
Bafin operational resilience requirements compel financial institutions to deploy dedicated API gateway appliances for core banking exposure. Gaia-X initiative creates captive demand for API infrastructure within national jurisdictional boundaries. Frankfurt and Munich manufacturing conglomerates deploy hybrid architectures for ERP synchronization under strict data sovereignty rules.
India
UPI expansion and BIS cloud security guidelines accelerate API gateway procurement for financial data orchestration. MeitY data localization directives mandate on-premises API infrastructure for regulated sectors. Bengaluru and Hyderabad technology clusters lead mobile-first API consumption among consumer technology startups.
United Kingdom
FCA open banking regulations enforce standardized REST interfaces for payment initiation and account aggregation. GDPR Article 44 compliance elevates hybrid cloud configurations for cross-border data flows. London fintech clusters drive authentication API demand for real-time payment verification systems.
Japan
METI digital transformation initiatives promote API-led connectivity for legacy manufacturing system modernization. JIS standards alignment shapes procurement criteria for industrial IoT API deployments. Tokyo and Osaka enterprise technology organizations adopt developer self-service portals for internal platform engineering teams.
Cloud API Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in Cloud API market structure. Hyperscale cloud providers consolidate infrastructure-level API primitives and gateway management capabilities under unified control planes. Specialist vendors concentrate on protocol-specific toolchains, edge-native execution runtimes, and regulated industry compliance modules. Competitive moves center on Kubernetes-native service mesh integration and sovereign cloud partnership structures for data residency requirements.
Within the integrated leader tier, Microsoft Corporation, Amazon Web Services, Inc., and Google LLC exemplify distinct strategic positioning archetypes. Microsoft leverages enterprise installed base relationships to anchor hybrid deployment services across Azure ecosystems. Amazon Web Services occupies infrastructure-level dominance through serverless compute and storage orchestration primitives. Google represents Kubernetes-native API management with deep open-source developer workflow integration. IBM Corporation and Oracle Corporation sit within the enterprise legacy modernization tier, bridging mainframe connectivity to cloud-native architectures.
| Leading Market Players |
|---|
| Amazon Web Services, Inc. |
| Microsoft Corporation |
| Google LLC |
| IBM Corporation |
| Oracle Corporation |
| Salesforce.com, Inc. |
| Red Hat, Inc. |
| SAP SE |
| Broadcom Inc. |
| Others |
Cost & Logistics Intelligence
Forty-five to ninety-day gateway provisioning cycles for hybrid cloud deployments concentrate vendor pricing power among hyperscale providers while forcing enterprise buyers into longer commitment horizons to secure rate stability. This lead-time band compresses margin pools for systems integrators caught between client demand for flexible consumption and infrastructure vendors pushing reserved capacity discounts.
Pricing Analysis
United States-Germany pricing spreads of 20-35% for equivalent API gateway throughput tiers reflect divergent compliance bundling and data residency infrastructure costs. Authentication APIs command premium subscription tiers tied to FedRAMP certification levels, while storage APIs compete on commodity per-gigabyte throughput metrics. Cost compression in messaging APIs intensifies as Twilio-anchored competitors expand freemium tiers. Managed service providers exhibit the sharpest price sensitivity, while federal contractors absorb premium zero-trust security pricing without volume negotiation leverage.
Supply Chain Analysis
Ninety-day silicon lead times for specialized API gateway appliances constrain hardware-dependent private cloud deployments while accelerating software-only consumption models. Supply concentrates in Taiwan for gateway semiconductor components, India for systems integration labor pools, and Ireland for EU data residency infrastructure. Raw material dependencies span advanced networking ASICs, encryption co-processors, and sovereign cloud facility construction inputs. Single-source vulnerability runs through TSMC-fabricated security chips. Distribution runs through hyperscale cloud marketplaces for public deployments and regional systems integrators for hybrid configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among managed service providers consolidating fragmented enterprise API governance demand, compressing vendor margin capture and forcing platform vendors toward channel partnership structures.
For Market Incumbents: Compound hybrid cloud sovereignty positioning through Gaia-X and MeitY-compliant infrastructure partnerships before regulatory enforcement windows tighten. Anchor zero-trust authentication capabilities against emerging Kubernetes-native gateway entrants. Prioritize vertical integration into edge-native WASM runtime modules to defend against latency-optimized challengers. For New Entrants and Emerging Players: Anchor in healthcare FHIR interoperability workflows where HIPAA-mandated data exchange creates captive demand outside hyperscale provider dominance. Target Germany's Bafin-regulated financial institutions with dedicated API gateway appliances bypassing multi-tenant compliance complexity. Pursue developer self-service portal distribution to intercept IT consultancy channel intermediation. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across Kubernetes-native API management tooling as open-source foundations commoditize core gateway functions. Long-term viability favors platform engineering talent arbitrage plays and regulated industry compliance module specialists. Signal to watch: hyperscale provider acquisition pace for edge-native execution runtime vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Kubernetes-native service mesh consolidation reduces multi-cloud credential sprawl for federal contractors under NIST frameworks. |
| Geographic Expansion | Gaia-X-aligned sovereign cloud partnerships capture German financial institution procurement cycles under Bafin mandates. |
| Acquisition of Specialist Firm | Edge-native WASM runtime vendors enable sub-10ms API response for autonomous vehicle telemetry pipelines. |
| Strategic Partnership | Healthcare network FHIR data exchange consortia unlock reimbursement-linked workflows under HIPAA interoperability rules. |
| Product Launch | Developer self-service portals displace IT ticket workflows among India and United States cloud-native enterprises. |
Research Approach
Desk research of hyperscaler capex disclosures, SEC 10-K infrastructure segments, and EU regulatory filing databases preceded structured interviews with platform engineering directors, API product managers, healthcare IT procurement leads, and federal contractor cybersecurity officers. Primary fieldwork combined with secondary validation against NIST framework documentation, BIS cloud security guidelines, and open banking regulatory texts. Bottom-up API call volume estimates and top-down enterprise IT spend allocations were triangulated to anchor market sizing.
Variance decomposition across deployment mode, solution architecture, and end-user maturity segments structured the analytical framework over the projection horizon. Modeled dimensions spanned public-private-hybrid-community cloud configurations, authentication-data integration-messaging-payment-storage API categories, and developer-consultancy-vendor-MSP procurement channels. CAGRs were derived from segment-level adoption curve inflections and regulatory mandate enforcement sequencing. Kubernetes-native penetration rates and zero-trust security procurement cycles served as industry-specific forecast inputs.
Material uncertainties — sovereign cloud mandate delays, hyperscale provider pricing volatility, and platform engineering talent scarcity — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory enforcement timing and enterprise cloud-native maturity progression. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Cloud VPN Market
Cloud Computing
Cloud Calling Market
Cloud Computing
Asia Pacific Cloud Computing Market
Cloud Computing
Italy Cloud Computing Market
Cloud Computing
Europe Mobile Cloud Market
Cloud Computing
Global Public Cloud Service Market
Cloud Computing
Industrial Cloud Market
Cloud Computing
Cloud Continuum Market
Cloud Computing
Cloud Infrastructure-As-A-Service Market
Cloud Computing
Government Cloud Market
Cloud Computing
Cloud Database Market
Cloud Computing
Cognitive Cloud Market
Cloud Computing
Saudi Arabia Cloud Computing Market
Cloud Computing
Cloud Banking Solutions Market
Cloud Computing
SME Cloud Market
Cloud Computing
Global Distributed Cloud Market