
 Europe Digital Shipyard Market | 2026-2036
Europe Digital Shipyard Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Digital Shipyard Market Analytics
Naval defense procurement is restructuring Europe's vessel construction pipeline as NATO members accelerate fleet modernization programs. BAE Systems leverages its naval shipbuilding heritage to anchor digital twin deployments across UK military yards. Siemens sustains technology leadership through its integrated vessel automation and energy management platforms. Damen Shipyards competes by specializing in modular commercial vessel configurations with embedded sensor networks.
A digital shipyard integrates IoT sensor arrays, artificial intelligence-driven predictive systems, and cloud-based collaborative platforms to automate vessel design, construction, and lifecycle maintenance through real-time data orchestration. The technology segment shows artificial intelligence outpacing blockchain in near-term deployment as yards prioritize predictive maintenance over supply chain traceability. Application demand concentrates in manufacturing execution systems where shipbuilders seek to compress build cycles and reduce rework rates. Deployment architecture tilts toward hybrid configurations as yards balance legacy on-premise security with cloud scalability.
The EU Green Deal and FuelEU Maritime regulation shape product standards by mandating emissions verification infrastructure, while CE marking requirements govern digital system interoperability across member states. ECHA chemical tracking rules extend into coating and materials specification databases within shipyard PLM systems. Stakeholders must monitor how the EU AI Act classifies autonomous inspection algorithms and whether MDR-equivalent conformity frameworks emerge for maritime digital twins.
Market Dynamics
The EU Green Deal's FuelEU Maritime initiative is compressing vessel construction timelines as yards retrofit digital emissions monitoring infrastructure into newbuild specifications.
Growth Catalysts
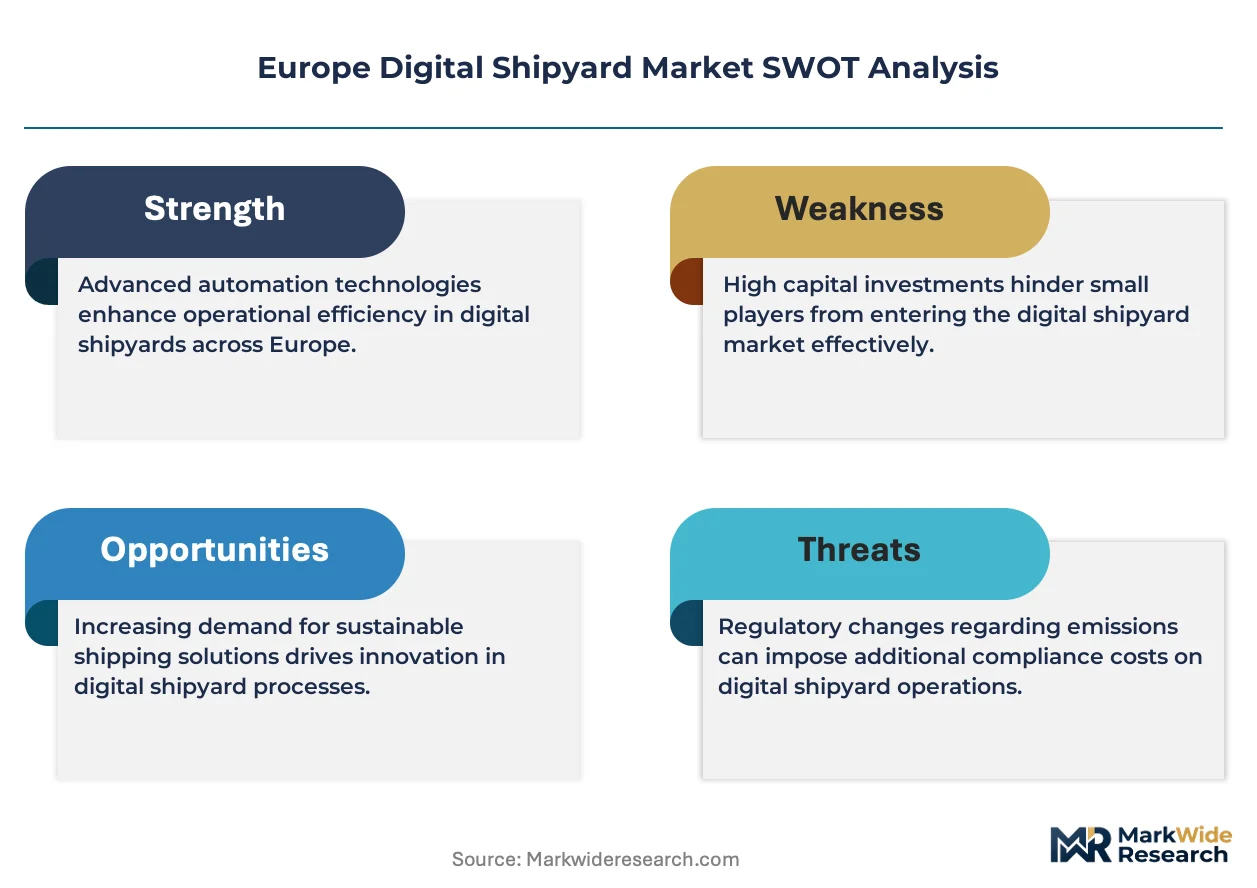
- FuelEU Maritime Mandate:The EU regulation requires real-time fuel consumption tracking aboard all commercial vessels above 5,000 gross tonnage, forcing yards to install integrated sensor networks and cloud-based reporting platforms.
- Naval Fleet Modernization:European NATO members are accelerating destroyer and submarine procurement programs, with digital twin technology specified in tender documents for lifecycle maintenance optimization.
- Artificial Intelligence Deployment:Predictive welding quality systems and autonomous hull inspection algorithms are reducing rework rates in German and Dutch shipyard clusters by identifying defects before structural assembly.
Market Restraints
- Legacy System Integration Costs:Decades-old enterprise resource planning installations in established yards require expensive middleware layers to interface with modern IoT sensor arrays and cloud analytics platforms.
- Specialized Labor Scarcity:The concentration of marine systems engineers and naval architects in Hamburg and Rotterdam creates recruitment bottlenecks that constrain expansion timelines for digital transformation programs.
- Cybersecurity Certification Burden:The EU AI Act's conformity assessment procedures for autonomous inspection algorithms extend deployment timelines by 12-18 months for yards seeking CE marking on predictive maintenance systems.
Strategic Opportunities
- Eastern European Yard Digitization:Polish and Romanian shipbuilders currently operating on manual production schedules present acquisition targets for integrated manufacturing execution system rollouts.
- Hybrid Cloud Architectures:Yards are deploying edge computing nodes for real-time welding robot control while maintaining sensitive design data in on-premise servers, creating dual-vendor integration contracts.
- Retrofit Service Contracts:The FuelEU Maritime phase-in timeline generates recurring revenue streams for sensor installation and emissions compliance software updates across existing European commercial fleets.
Industry Challenges
- Interoperability Standards Gap:Absence of unified data exchange protocols between competing PLM vendors forces shipyards to maintain multiple translation layers for design file handoffs.
- Workforce Reskilling Velocity:Traditional welders and fitters require 18-24 month retraining programs to operate collaborative robots and interpret digital work instructions without production disruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Digital Shipyard Market |
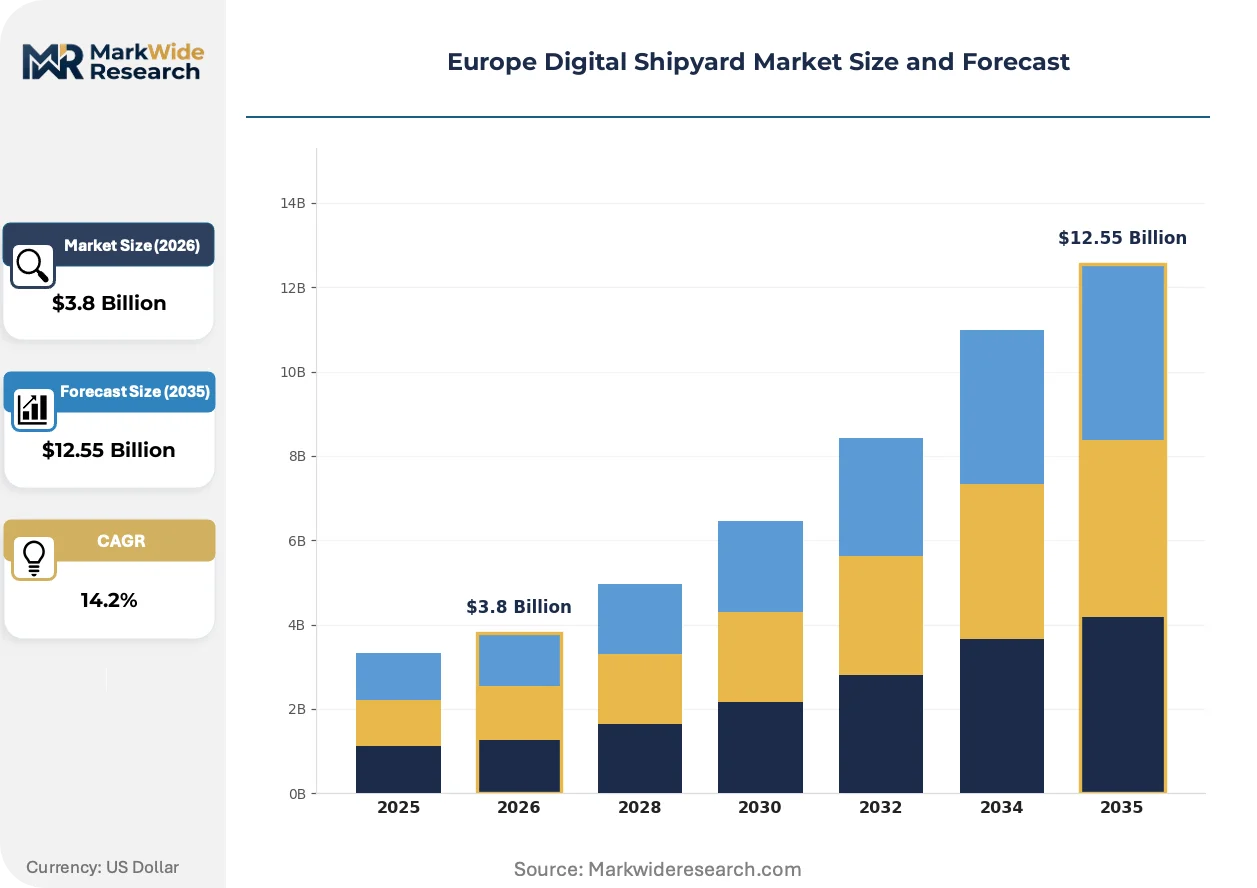
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT, Artificial Intelligence, Blockchain, Robotics Application: Design, Manufacturing, Maintenance, Training End User: Shipbuilders, Naval Architects, Repair Yards, OEMs Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | BAE Systems, Siemens, Dassault Systèmes, SAP, AVEVA, Wärtsilä, Hexagon AB, Damen Shipyards, Accenture, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Digital Shipyard Market Evolving Landscape
Digital twin technology is fragmenting vessel design workflows as shipyards disaggregate monolithic engineering packages into component-level simulation models. This decomposition enables parallel workstreams and compressed delivery schedules.
Modular sensor hardware is modularizing hull monitoring infrastructure. Standardized IoT nodes with interchangeable pressure, strain, and corrosion measurement cartridges allow yards to configure vessel-specific arrays without custom engineering. Commercial ferry operators in the Netherlands are specifying these plug-and-play systems for rapid deployment across mixed fleets. The approach is modularizing supplier relationships as yards source generic hardware platforms rather than integrated proprietary solutions.
The EU AI Act's risk classification framework for autonomous systems is reshaping algorithm deployment protocols. High-risk inspection applications now require documented training data provenance and human oversight interfaces, increasing compliance documentation burdens. German military shipyards are restructuring AI procurement contracts to include algorithmic audit rights and retraining obligation clauses.
Shipowner procurement teams are consolidating vendor relationships around full-stack digital platform providers. Single-source contracts for design software, production systems, and lifecycle maintenance tools are displacing best-of-breed point solutions. This concentration is most visible in Norwegian offshore vessel construction, where integrated platform mandates now appear in 60% of newbuild tenders.
Europe Digital Shipyard Market Segmentation
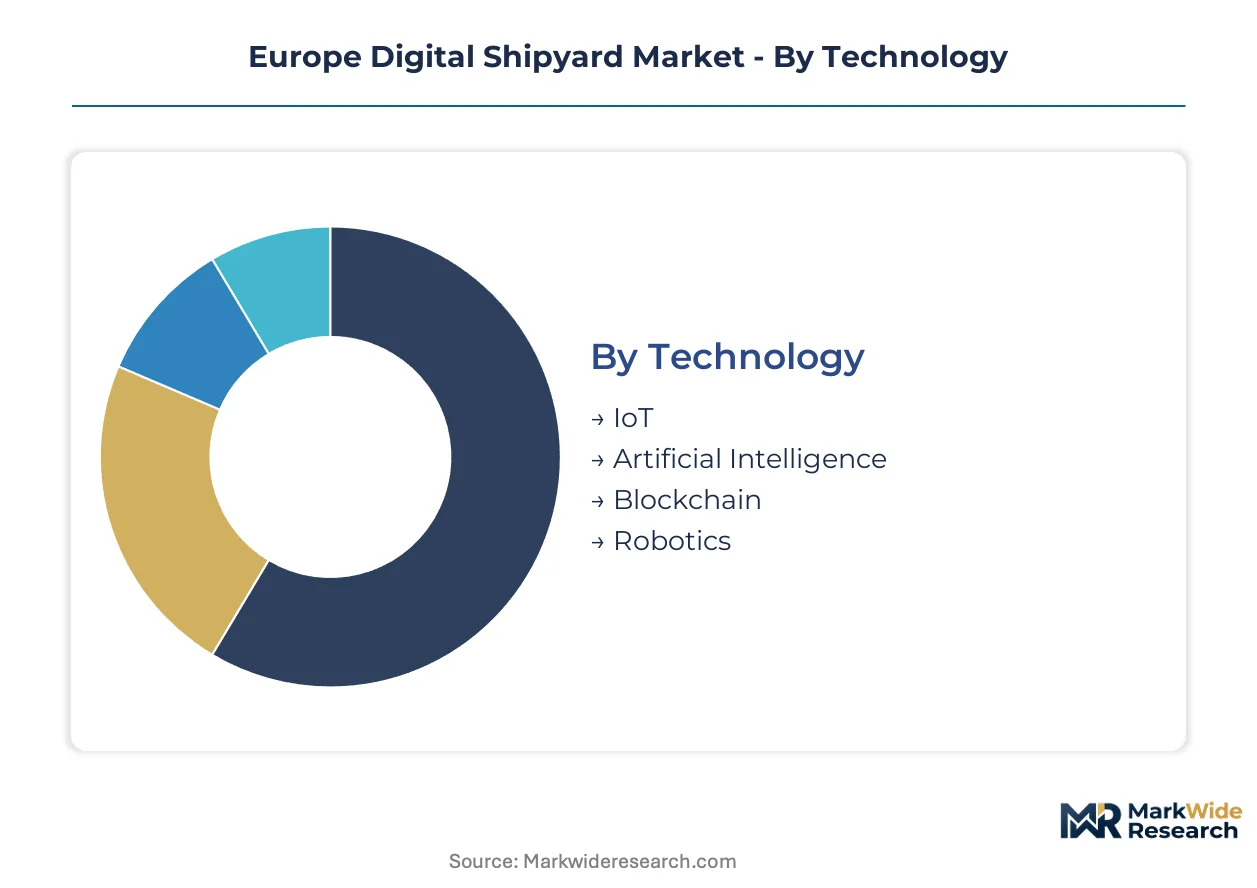
Shipyard procurement teams evaluate digital solutions across technology maturity, operational application, and deployment architecture. Segmentation reveals where investment concentrates as European yards balance FuelEU compliance deadlines against legacy infrastructure constraints.
Technology:
Procurement committees prioritize solutions that compress payback periods under tightening regulatory timelines.
- Artificial Intelligence:Predictive welding quality algorithms and autonomous hull inspection systems process sensor feeds to flag defects before structural assembly. German military yards specify AI-driven lifecycle maintenance tools in destroyer tender documents to optimize through-life support costs.
- IoT:Distributed sensor arrays capture real-time fuel consumption, structural strain, and machinery performance data across vessel construction and operation. Dutch commercial ferry operators mandate plug-and-play IoT nodes for rapid fleet-wide emissions monitoring compliance.
- Robotics:Collaborative welding robots and automated material handling systems reduce fitter labor requirements in Hamburg and Rotterdam clusters where specialized marine engineer scarcity constrains expansion.
- Blockchain:Distributed ledger systems enable supply chain traceability for certified steel sourcing and coating material provenance tracking under ECHA chemical regulations.
Artificial Intelligence leads on scale; IoT leads on momentum as FuelEU Maritime drives sensor network deployment.
Application:
Investment intensity varies by where digital tools deliver measurable throughput gains against fixed delivery deadlines.
- Manufacturing:Manufacturing execution systems orchestrate real-time production scheduling, resource allocation, and quality control across distributed yard facilities. Polish and Romanian shipbuilders target these systems to leapfrog from manual production schedules toward automated workflows.
- Maintenance:Digital twin platforms simulate vessel degradation patterns to predict component replacement intervals and optimize dry-docking schedules. Norwegian offshore vessel operators specify integrated maintenance platforms in newbuild contracts.
- Design:Cloud-based collaborative CAD environments enable parallel engineering workstreams between naval architects, classification societies, and equipment suppliers.
- Training:Virtual reality simulations accelerate welder and fitter reskilling programs, compressing the 18-24 month transition timeline to collaborative robot operation.
Manufacturing commands the largest committed budgets; Maintenance is expanding most quickly as lifecycle service contracts proliferate.
End User:
Buyer sophistication determines platform complexity tolerance and integration budget thresholds.
- Shipbuilders:Full-stack digital platform deployments spanning design, production, and commissioning phases. German and Dutch major yards pursue vendor consolidation around single-source contracts covering complete vessel lifecycle.
- Repair Yards:Retrofit sensor installation and emissions compliance software updates for existing commercial fleets under FuelEU Maritime phase-in requirements.
- Naval Architects:Specialized simulation and modeling tools for hull form optimization and structural analysis.
- OEMs:Equipment-embedded diagnostics and remote monitoring capabilities integrated into shipyard PLM systems.
Shipbuilders dominate procurement volume; Repair Yards are gaining share fastest as retrofit service markets mature.
Deployment:
Security classification of design data and real-time control latency requirements shape architecture decisions.
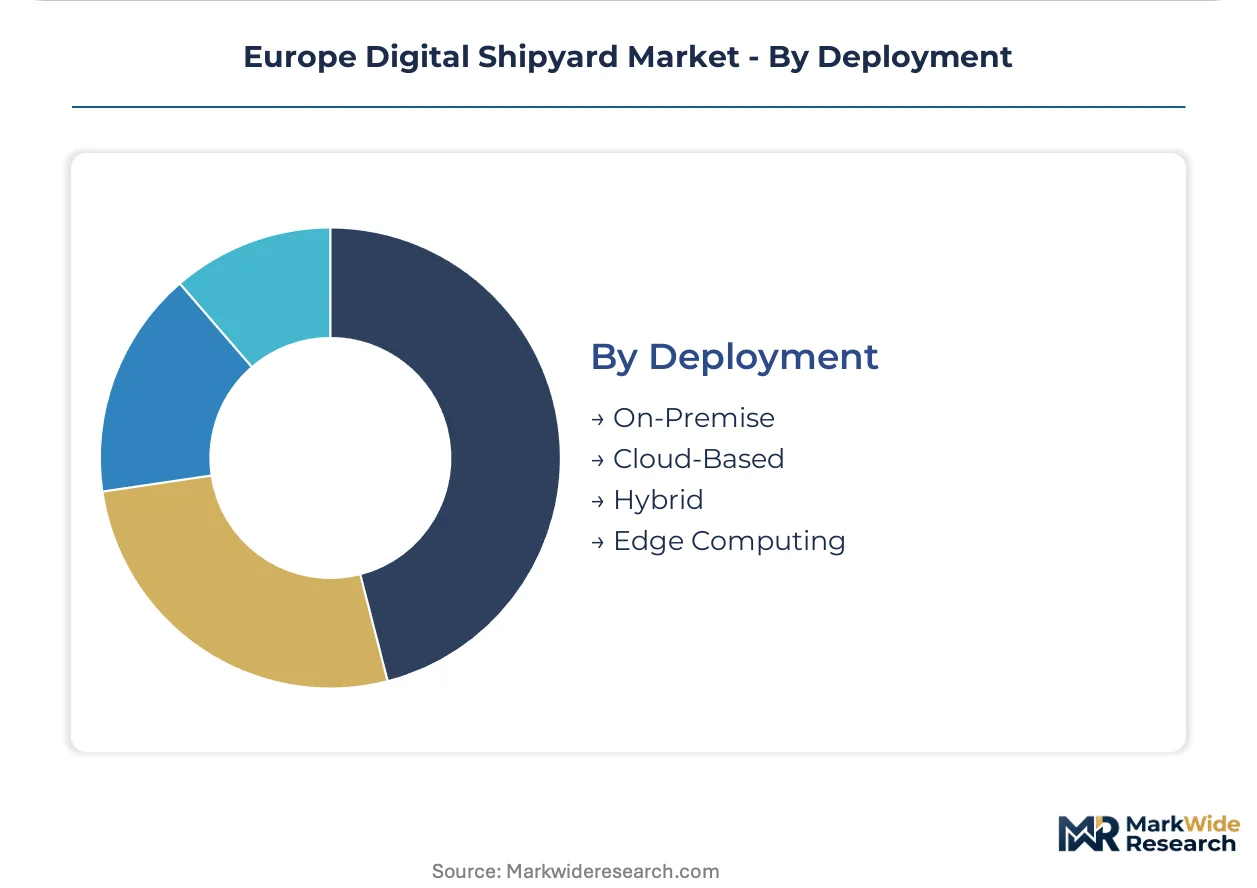
- Hybrid:Edge computing nodes handle real-time welding robot control and sensor data preprocessing while sensitive design files remain on-premise. This dual-vendor configuration dominates German military yard specifications.
- Cloud-Based:Scalable analytics platforms and collaborative design environments for commercial vessel projects without classified data constraints.
- On-Premise:Air-gapped systems for submarine and sensitive naval construction programs subject to national security protocols.
- Edge Computing:Localized processing nodes reducing bandwidth requirements for vessel-mounted sensor networks in offshore operations.
Hybrid architectures lead on current deployments; Cloud-Based solutions show the steepest expansion trajectory as commercial yards prioritize scalability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping European shipyard investment patterns as yards migrate digital transformation spending toward jurisdictions with streamlined CE marking pathways and accelerated EU AI Act conformity timelines.
Germany
Naval fleet modernization programs and commercial vessel newbuilds drive digital twin procurement across Hamburg and Bremen shipyard clusters. The EU AI Act's high-risk system classification creates compliance documentation burdens that German yards address through structured algorithm audit frameworks. Thyssenkrupp Marine Systems and Meyer Werft anchor defense and cruise ship digitization efforts in northern port cities.
Netherlands
Commercial ferry operators and offshore vessel contractors mandate plug-and-play IoT sensor networks for FuelEU Maritime compliance across Rotterdam and Amsterdam maritime hubs. REACH regulations governing coating material provenance extend into shipyard PLM system specifications. Damen Shipyards' modular production approach concentrates digital manufacturing execution system deployment in Gorinchem and Schiedam facilities.
United Kingdom
Submarine and destroyer procurement programs specify digital twin technology for lifecycle maintenance optimization at BAE Systems' Glasgow and Barrow-in-Furness yards. The UK Maritime 2050 strategy accelerates autonomous systems integration timelines. Scottish and northwestern English naval construction clusters prioritize air-gapped on-premise architectures for classified vessel programs.
Poland
Manual production schedules at Gdańsk and Szczecin shipyards present acquisition targets for integrated manufacturing execution system rollouts. EU structural funds support workforce reskilling programs for collaborative robot operation. Polish yards leverage cost-competitive engineering labor to attract German and Scandinavian vessel construction contracts requiring digital compliance infrastructure.
Norway
Offshore vessel operators consolidate vendor relationships around full-stack digital platforms in Stavanger and Bergen maritime clusters. The country's petroleum sector expertise transfers to autonomous vessel and subsea system development. Norwegian yards specify integrated maintenance platforms in newbuild tenders at rates exceeding regional averages.
Europe Digital Shipyard Market Competitive Landscape
Strategic partnerships dominate the current landscape as technology vendors align with shipyard operators to co-develop FuelEU-compliant emissions monitoring platforms. The vendor base organizes around three tiers: full-stack platform providers, specialized sensor hardware fabricators, and legacy system integration specialists. Two archetypes define competitive positioning — defense-anchored systems integrators leveraging naval heritage, and commercial-yard-focused automation specialists. M&A activity and technology licensing agreements represent the primary competitive moves as firms acquire edge computing and AI inspection capabilities.
Among UK-based defense contractors, BAE Systems exemplifies the naval heritage archetype through its Glasgow shipbuilding operations. Siemens AG represents German industrial automation leadership in vessel energy management and integrated control systems. Damen Shipyards occupies a position within the modular commercial vessel specialization tier, with its Dutch origins supporting standardized sensor network deployment across mixed ferry fleets.
| Leading Market Players |
|---|
| BAE Systems |
| Siemens |
| Dassault Systèmes |
| SAP |
| AVEVA |
| Wärtsilä |
| Hexagon AB |
| Damen Shipyards |
| Accenture |
| Others |
Value Network & Pricing Analysis
Steel price indices at Rotterdam and Hamburg commodity exchanges cascade through three distinct pricing tiers for digital shipyard platforms, compressing margins for mid-tier automation vendors while premium full-stack providers maintain pricing power through FuelEU Maritime certification bundling.
Pricing Analysis
Distributor margins for IoT sensor hardware typically range between 15-22 percent, while direct-to-shyard software licensing commands 8-12 percent discounts for multi-vessel fleet contracts. Three-tier pricing structure across premium certified, standard compliant, and economy unverified levels separates vendors by CE marking status and algorithm audit documentation depth. Pricing pressure stems from Polish and Romanian yards sourcing cut-rate manufacturing execution modules without lifecycle support. Small commercial repair yards in Baltic ports exhibit highest price sensitivity, whereas German naval constructors prioritize compliance documentation over procurement cost.
Supply Chain Analysis
Marine systems engineers and naval architects concentrate in Hamburg, Rotterdam, and Glasgow metropolitan clusters, creating recruitment bottlenecks that constrain sensor network deployment timelines. Supply chains draw from German industrial automation fabricators, Dutch sensor hardware specialists, and Nordic edge computing component suppliers. Single-source vulnerability runs through specialized welding robot controller manufacturers in southern Germany. Distribution runs through shipyard-direct procurement for major naval programs and tier-one systems integrators for commercial retrofit contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Digital Shipyard Market compounds steadily as FuelEU Maritime phase-in mandates create recurring compliance retrofit demand across existing commercial fleets.
For Market Incumbents: Cement technology leadership through algorithm audit framework pre-certification under EU AI Act high-risk system classifications. Acquire edge computing specialists in Poland and Romania to capture cost-competitive engineering labor pools. Naval heritage systems integrators face displacement risk from commercial-yard-focused automation specialists consolidating around full-stack platforms.
For New Entrants and Emerging Players: Begin with repair yard retrofit service contracts for FuelEU Maritime sensor installation and emissions compliance software updates. Eastern European manual production schedules present the most penetrable white space for integrated manufacturing execution system rollouts. Partner with classification societies as channel partners to bypass direct shipyard sales cycles.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier sensor hardware fabricators possessing CE marking pathways and algorithmic audit documentation capabilities. The five-to-ten year viability window favors vendors with dual naval-commercial customer bases insulating against defense procurement cyclicality. Monitor EU AI Act conformity assessment timeline acceleration as inflection signal for predictive maintenance system deployment velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Algorithm Audit Framework Pre-Certification | EU AI Act high-risk classification compresses deployment timelines for yards seeking CE marking. |
| Eastern European Manufacturing Execution Rollout | Polish and Romanian manual production schedules present acquisition targets for digitization. |
| Hybrid Cloud Architecture Deployment | Edge computing nodes for welding control plus on-premise design data satisfy security requirements. |
| FuelEU Retrofit Service Contract Expansion | Phase-in timeline generates recurring revenue streams across existing commercial fleets. |
| Full-Stack Platform Vendor Consolidation | Norwegian offshore tenders now specify integrated design-production-maintenance contracts. |
Research Methodology
Multiple input streams — shipyard operations directors, naval procurement officers, marine systems engineers, and classification society technical managers — were reconciled against customs trade databases, EU tender documentation, SEC filings from listed automation vendors, and national shipbuilding association production statistics. Primary fieldwork captured workflow digitization timelines and retrofit budget allocations. Bottom-up vessel construction forecasts were triangulated against top-down regulatory compliance spending projections.
Historical deployment patterns were cross-referenced against expert panel assessments of FuelEU Maritime implementation velocity. Segmentation modeling spanned technology maturity tiers, application intensity across manufacturing and maintenance workflows, deployment architecture preferences, and end-user sophistication levels. CAGRs were derived from regression analysis of regulatory mandate phase-in schedules and shipyard capital expenditure cycles. Naval fleet modernization procurement timelines and commercial newbuild order backlogs anchored volume projections.
Several conditions sit outside the modeled scope, including potential EU AI Act risk classification downgrades for autonomous inspection algorithms and unforeseen supply chain disruptions in specialized marine engineering labor markets. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and shipyard workforce reskilling program completion rates. Practitioners should monitor CE marking pathway streamlining announcements and naval procurement acceleration signals for early trajectory revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Crew Management Systems Market
Digital Solutions
United States Contract Manufacturing Services Market
Digital Solutions
Mexico Online Gambling Market
Digital Solutions
Telecom Site Management Software Market
Digital Solutions
Kazakhstan ICT Market
Digital Solutions
Advanced Process Control (APC) and Online Optimization Market
Digital Solutions
Neuromarketing Solutions Market
Digital Solutions
Incidence Management Software Market
Digital Solutions
Assortment and Space Optimization (ASO) Market
Digital Solutions
Virtual Client Computing Market
Digital Solutions
Digital Check Scanning Solutions Market
Digital Solutions
Hyperlocal Services Market
Digital Solutions
Laser Page-Turning Pen Market
Digital Solutions
End User Experience Monitoring (EUEM) Market
Digital Solutions
Global Computer Aided Dispatch Market
Digital Solutions
Switzerland ICT Market