
 Digital Clothing Market | 2026-2036
Digital Clothing Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Clothing Market Analysis
Multi-source design-to-render pipelines is decoupling asset creation from proprietary game engines across the digital clothing value chain. CLO Virtual Fashion leverages native 3D modeling tools to anchor technical workflows for apparel brands entering virtual production. Nike competes through sports-centric digital collections that extend its physical merchandise into persistent gaming environments. The Fabricant specializes in purely digital couture, occupying a premium creative tier distinct from hybrid physical-digital offerings.
Digital clothing comprises computer-generated garments rendered through polygon mesh construction, texture mapping, and physics-based simulation for drape and movement behavior, serving commercial purposes from virtual try-on to in-game avatar customization and NFT-backed ownership. Augmented Reality and 3D Modeling lead technology adoption as infrastructure layers, while Blockchain application segments attract margin concentration through scarcity mechanics and resale royalties. Gaming and Social Media Marketing represent the fastest-growing application channels as platform economics shift toward user-generated virtual goods.
ISO standards for digital asset interoperability, the EU AI Act provisions on synthetic media transparency, and China's MIIT guidelines for virtual property rights collectively shape product standards and cross-platform portability requirements for digital clothing creators. The US Federal Trade Commission monitors disclosure obligations for influencer marketing of virtual goods, affecting how fashion brands and social media promoters present digital apparel to consumers. Stakeholders must track evolving regulatory definitions of virtual asset ownership and platform liability as jurisdictions develop distinct frameworks for digital commerce.
Market Dynamics
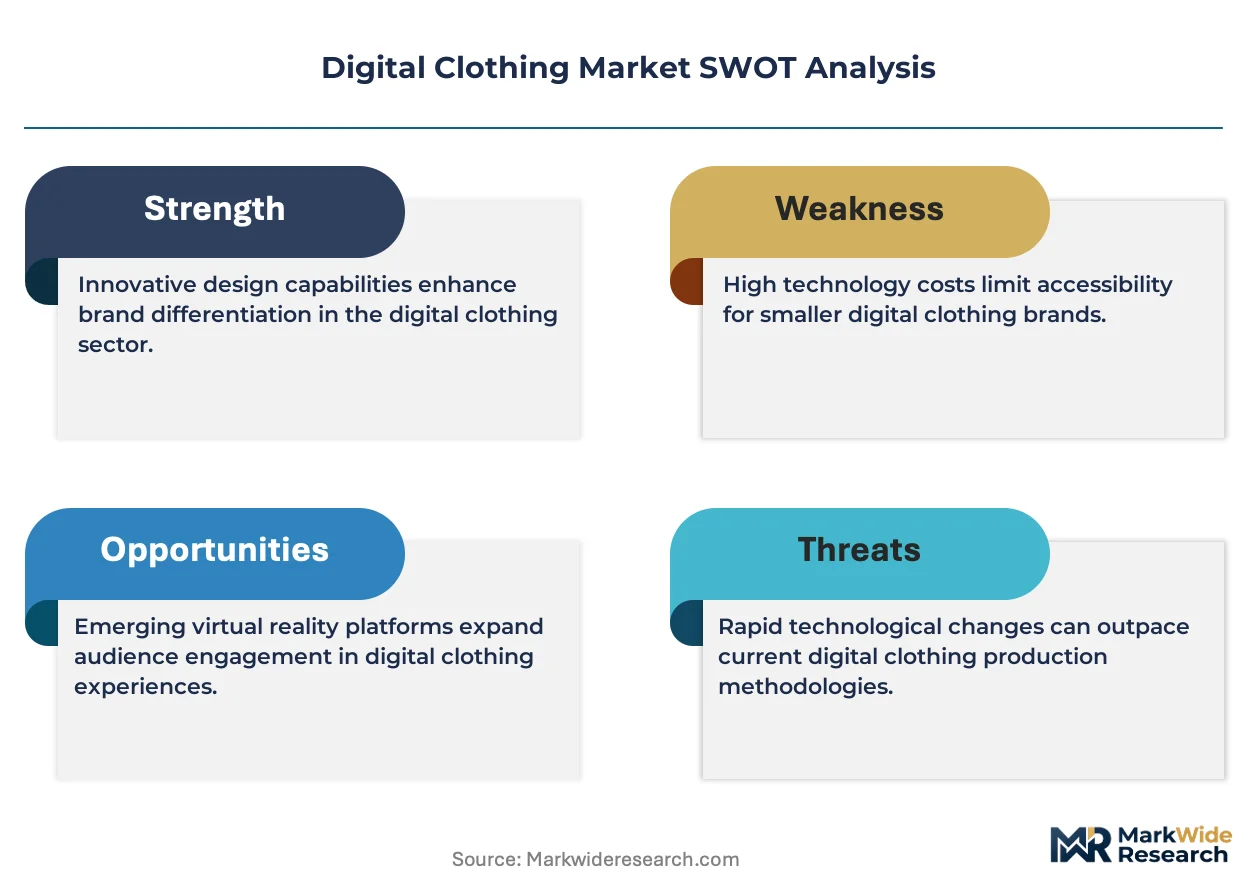
Physics-based simulation engines and blockchain-based ownership verification are restructuring value capture across digital clothing production pipelines, compressing design-to-deployment cycles while fragmenting platform control over asset distribution.
Growth Catalysts
- EU AI Act transparency mandates:Synthetic media disclosure requirements for virtual try-on applications are accelerating investment in auditable 3D rendering pipelines among European fashion retailers.
- Gaming platform economics:Persistent avatar customization systems in multiplayer environments are creating recurring revenue streams for digital garment creators through microtransaction marketplaces.
- Polygon mesh optimization:Advances in real-time cloth simulation algorithms are reducing computational load for mobile AR applications, expanding addressable device bases.
Market Restraints
- GPU compute cost volatility:Cloud rendering expenses for high-fidelity physics simulation fluctuate with semiconductor supply constraints, pressuring margin structures for mid-tier design studios.
- Platform gatekeeping concentration:Meta and Epic Games control dominant distribution channels for consumer-facing digital fashion, extracting substantial revenue shares from creators.
- Interoperability technical limitations:Proprietary file formats across Unreal Engine, Unity, and native WebGL implementations fragment asset portability and inflate adaptation costs.
Strategic Opportunities
- Underpenetrated Indian market:Mobile-first social commerce platforms and Bollywood gaming integrations offer expansion vectors for virtual apparel targeting price-sensitive demographics.
- Brazilian regulatory tailwinds:ANVISA's emerging framework for digital health and wellness applications creates precedent for virtual try-on classification as regulated medical-adjacent tools.
- AI-generative texture synthesis:Diffusion models trained on textile datasets are converging with parametric pattern tools to democratize surface design for non-specialist creators.
Industry Challenges
- 3D technical artist scarcity:Specialized expertise combining apparel pattern-making with real-time engine workflows commands premium compensation, constraining studio scaling.
- Cross-platform certification complexity:Apple's App Store and Google's Play Store impose divergent content moderation standards for avatar customization assets, delaying release timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Clothing Market |
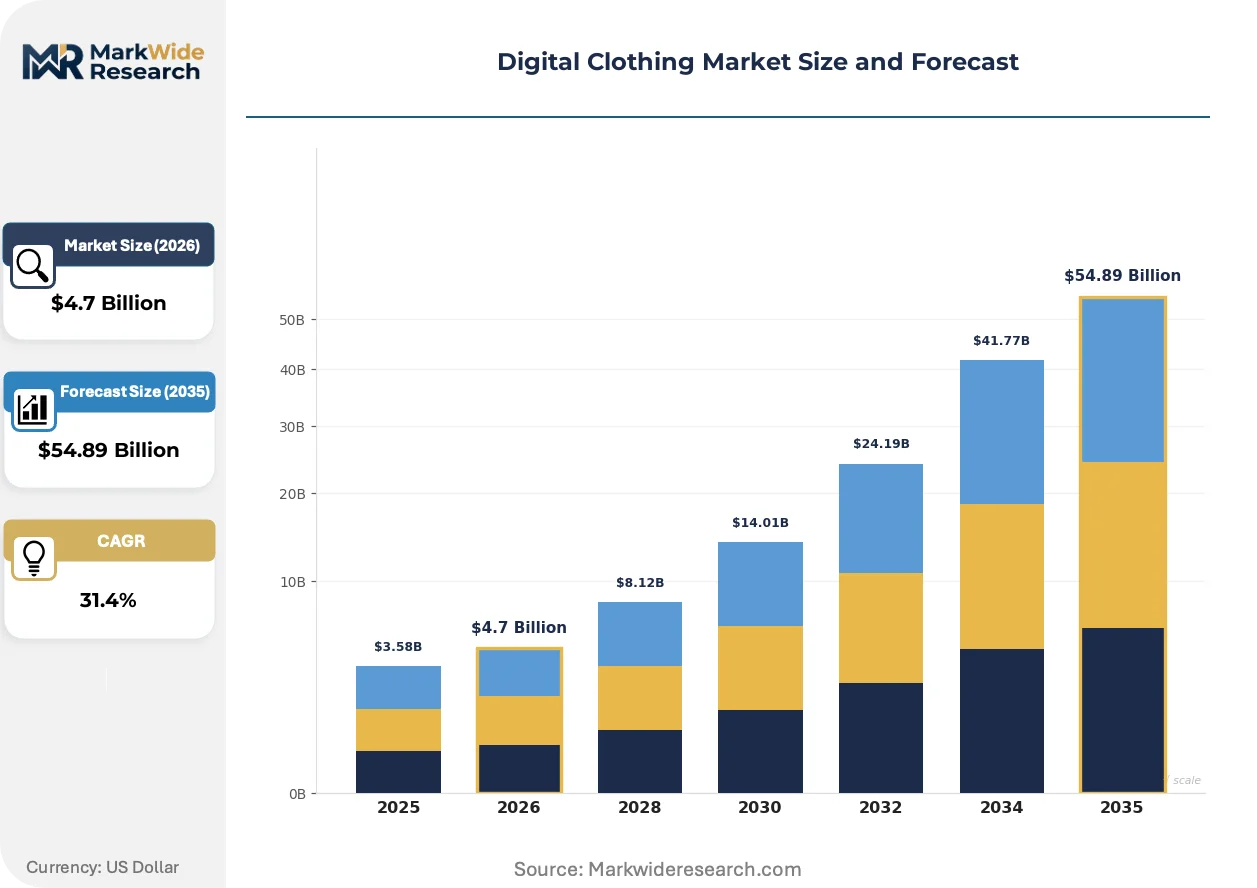
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $54.89 Billion |
| CAGR (2026 – 2036) | 31.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Accessories, Footwear, Outerwear, Activewear Technology: Augmented Reality, Virtual Reality, 3D Modeling, Blockchain End User: Fashion Brands, E-commerce Platforms, Game Developers, Social Media Influencers Application: Gaming, Virtual Runways, Online Shopping, Social Media Marketing |
| Companies Covered | The Fabricant, Gucci, Style3D, Nike, Balenciaga, CLO Virtual Fashion, Mango, Stitch Fix, Browzwear, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Clothing Market Emerging Trajectories
Generative AI integration and decentralized ownership infrastructure are actively redrawing competitive boundaries between traditional fashion houses and native digital creators.
Real-time ray-traced fabric rendering is unifying previously separate offline and interactive production pipelines. Luxury brands adopting Unreal Engine 5 for virtual showrooms are collapsing the gap between cinematic marketing assets and playable game items. This compression is unifying asset investment decisions across marketing and product teams.
China's MIIT guidelines for virtual property rights are establishing precedent for cross-platform asset portability enforcement. Domestic platforms must implement standardized metadata schemas for user-owned digital goods. Fashion brands operating in Chinese gaming ecosystems are restructuring licensing agreements to comply with transferable ownership mandates.
Direct-to-avatar distribution models are displacing wholesale relationships between digital clothing creators and platform operators. Independent designers are leveraging NFT marketplaces and decentralized application stores to retain margin and customer relationships. South Korean social platforms including Zepeto and Naver are responding by launching creator-first revenue-sharing programs to retain talent.
Digital Clothing Market Segmentation
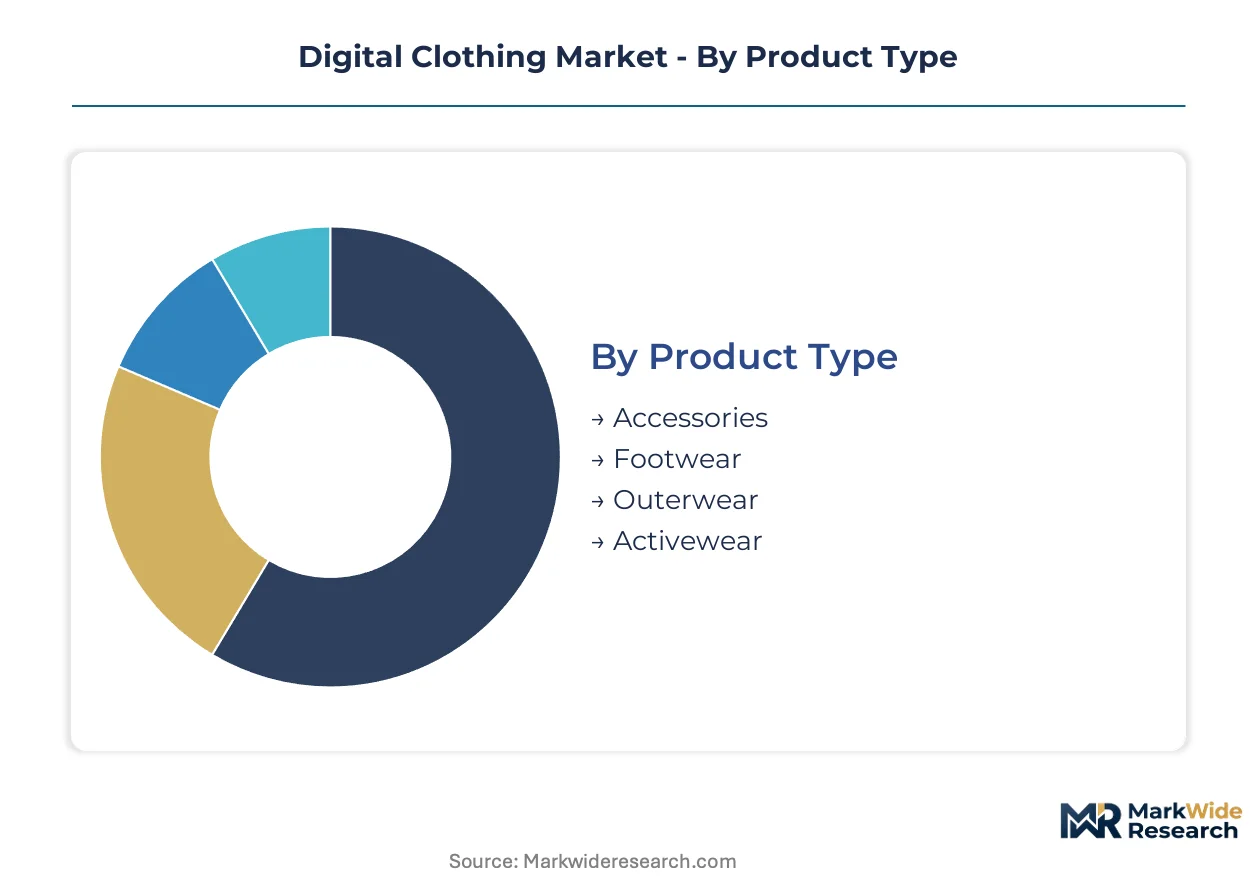
Segmentation in digital clothing reveals how technical specifications and distribution channels fragment value capture across production pipelines. Understanding these divisions exposes where margin concentrates and which customer types drive platform economics.
Product Type:
Customization intensity varies sharply across this category, from mass-produced accessories to bespoke outerwear requiring physics-based simulation.
- Activewear:Compression-fit garments demand high polygon mesh density for muscle drape simulation. Demand clusters in United States and South Korea where fitness gaming integrations and esports sponsorships require performance-oriented avatar customization.
- Outerwear:Complex layering systems with wind physics and material thickness variation command premium rendering budgets. Luxury fashion houses in France and Italy deploy these assets for virtual showroom experiences where fabric behavior authenticity determines brand perception.
- Footwear:Sole deformation and lace dynamics require specialized rigid-body physics engines.
- Accessories:Lower polygon budgets enable rapid mass production for social media filter integrations.
Most installed capacity flows through Accessories. Expansion is steepest in Activewear.
Technology:
Cost tier stratification separates infrastructure-heavy implementations from lightweight consumer-facing deployments.
- 3D Modeling:Native polygon mesh construction with parametric pattern tools anchors professional design workflows. CLO Virtual Fashion and Browzweave deployments in Germany and Japan concentrate demand among technical apparel designers requiring garment-to-avatar fit accuracy.
- Blockchain:Ownership verification and resale royalty enforcement attract margin concentration through scarcity mechanics. South Korean platforms Zepeto and Naver implement domestic MIIT-compliant metadata standards for transferable asset portability.
- Augmented Reality:Mobile-first try-on applications dominate e-commerce conversion optimization.
- Virtual Reality:Immersive showroom deployments require headset penetration thresholds limiting addressable markets.
Deployment volume concentrates in Augmented Reality. Value capture is climbing fastest in Blockchain.
End User:
Customer type determines procurement scale and technical specification complexity across the value chain.
- Fashion Brands:Established houses integrate digital clothing as brand extension requiring unified asset pipelines across marketing and product teams. LVMH and Kering deployments in France prioritize Unreal Engine 5 compatibility for cinematic-to-playable asset conversion.
- Game Developers:Persistent multiplayer environments create recurring revenue through microtransaction marketplaces. Epic Games and Roblox ecosystems in United States extract substantial platform fees from creator revenue.
- E-commerce Platforms:Conversion-rate optimization drives AR try-on adoption with lower fidelity requirements.
- Social Media Influencers:Direct-to-avatar distribution through NFT marketplaces enables margin retention outside platform gatekeeping.
Transaction volume flows predominantly through Game Developers. Revenue growth is expanding most quickly in Social Media Influencers.
Application:
Maturity gradients separate established commercial channels from emerging experimental formats.
- Gaming:Avatar customization systems in persistent multiplayer environments generate recurring microtransaction revenue. China's Tencent and NetEase gaming ecosystems implement MIIT-mandated transferable ownership standards reshaping licensing agreements.
- Social Media Marketing:Filter-based virtual try-on drives engagement metrics for influencer campaigns. United States FTC disclosure obligations for virtual goods marketing create compliance complexity affecting campaign design.
- Online Shopping:AR-enabled size recommendation reduces return rates for physical apparel retailers.
- Virtual Runways:Cinematic presentation formats require highest fidelity assets with limited scalability.
User engagement concentrates in Gaming. Adoption velocity is gaining share fastest in Social Media Marketing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are pulling digital clothing production toward jurisdictions with lighter compliance burdens for virtual asset classification. Studios migrate rendering operations from markets with strict synthetic-media disclosure mandates to regions with clearer virtual property rights frameworks.
United States
FTC disclosure obligations for influencer-marketed virtual goods are tightening campaign design requirements. Fashion brands operating in California and New York are restructuring social media partnerships to meet transparency standards. Los Angeles anchors the largest concentration of technical 3D artists serving entertainment-to-fashion crossover pipelines.
China
MIIT guidelines for transferable virtual property rights are reshaping licensing agreements across Tencent and NetEase gaming ecosystems. Domestic platforms must implement standardized metadata schemas for user-owned digital goods. Shanghai and Shenzhen clusters host the densest concentrations of CLO Virtual Fashion and Style3D deployment teams.
South Korea
Zepeto and Naver creator-first revenue-sharing programs are retaining talent against decentralized marketplace competition. The country's national telecommunications regulator enforces platform interoperability standards for avatar assets. Seoul's Gangnam district concentrates fashion-tech hybrid studios serving K-pop idol virtual merchandise.
France
EU AI Act synthetic-media transparency mandates are accelerating auditable 3D rendering pipeline investment. ANSM and CNIL guidance on biometric data in virtual try-on applications affects AR deployment strategies. Paris luxury houses anchor Unreal Engine 5 virtual showroom development for cinematic-to-playable asset conversion.
India
Mobile-first social commerce platforms and Bollywood gaming integrations are opening expansion vectors for price-sensitive virtual apparel. The country's national IT ministry is drafting preliminary frameworks for digital asset classification. Mumbai and Bengaluru clusters concentrate technical talent pools for offshore 3D modeling services.
Digital Clothing Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue pure-digital couture and decentralized distribution channels. The market structures around three maturity tiers: legacy fashion houses extending physical brands, native digital creators, and infrastructure-software vendors. Two strategic archetypes dominate—hybrid physical-digital integrators and blockchain-native pure-players. Competitive moves concentrate on M&A for technical talent acquisition and strategic partnerships for engine-agnostic asset pipelines.
Within the infrastructure tier, CLO Virtual Fashion and Style3D occupy positions anchoring professional design workflows. The Fabricant exemplifies the pure-digital creative tier distinct from hybrid offerings. Among fashion house entrants, Nike and Gucci represent divergent positioning—sports-centric gaming integration versus luxury metaverse presence.
| Leading Market Players |
|---|
| The Fabricant |
| Gucci |
| Style3D |
| Nike |
| Balenciaga |
| CLO Virtual Fashion |
| Mango |
| Stitch Fix |
| Browzwear |
| Others |
Supply Flow & Price Mechanics
EU AI Act synthetic-media transparency mandates gate qualified supply for premium-tier digital clothing, as only studios with auditable 3D rendering pipelines access European fashion retailer contracts. This regulatory filter concentrates pricing power among compliant producers while excluding cost-optimized competitors from high-margin segments.
Pricing Analysis
GPU compute cost pass-through dominates pricing structures for physics-based simulation services, with cloud rendering expenses fluctuating alongside semiconductor supply constraints. Three-tier pricing structure across premium, standard, and economy levels separates Unreal Engine 5 cinematic assets from mobile-optimized AR filters and basic social media accessories. Price differentiation hinges on polygon mesh density certification and real-time engine compatibility tier. Cost compression in mid-tier design studios is intensifying because platform gatekeepers extract substantial revenue shares. E-commerce platforms demonstrate highest price sensitivity due to thin margins on conversion-rate optimization tools, while luxury fashion houses absorb premium pricing for showroom authenticity.
Supply Chain Analysis
Technical artist scarcity in Germany, Japan, and the United States constrains production capacity for specialized apparel-pattern-to-avatar-fit workflows. Raw material dependencies center on CLO Virtual Fashion and Style3D software licenses, cloud GPU compute contracts, and blockchain node infrastructure. Single-source vulnerability runs through dominant platform distribution channels controlled by Meta and Epic Games. Distribution runs through direct-to-avatar NFT marketplaces and decentralized application stores alongside traditional platform-integrated pipelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where studios migrate rendering operations from EU synthetic-media disclosure jurisdictions toward regions with clearer virtual property rights frameworks like South Korea and China.
For Market Incumbents: Lock in technical talent pipelines through acquisition of CLO Virtual Fashion-certified studios in Shanghai and Shenzhen clusters. Secure Unreal Engine 5 compatibility certifications ahead of competitor migrations. Platform gatekeeper revenue-share extraction threatens margin structures; backward integration into proprietary rendering infrastructure reduces dependency on cloud GPU volatility.
For New Entrants and Emerging Players: Capture underpenetrated Indian mobile-first social commerce segments through Bollywood gaming integrations targeting price-sensitive demographics. Leverage AI-generative texture synthesis tools to bypass 3D technical artist scarcity constraints. Direct-to-avatar distribution through domestic NFT marketplaces bypasses platform gatekeeping.
For Investors and Strategic Acquirers: Roll-up economics work for technical-artist-scarce mid-tier studios because CLO Virtual Fashion certification creates defensible capability moats. Five-to-ten year viability hinges on cross-platform asset portability standardization. Watch China's MIIT enforcement actions on transferable ownership as the dominant inflection signal for licensing agreement restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Engine-Agnostic Asset Pipeline Development | Unreal Engine 5 and Unity interoperability reduces adaptation costs for multi-platform fashion brands. |
| Creator-First Revenue-Sharing Program Launch | Zepeto and Naver implementations retain talent against decentralized marketplace competition. |
| MIIT-Compliant Metadata Standard Implementation | Tencent and NetEase ecosystems require transferable ownership schemas for user-owned digital goods. |
| AI-Generative Texture Synthesis Integration | Diffusion models trained on textile datasets democratize surface design for non-specialist creators. |
| Direct-to-Avatar Distribution Channel Establishment | NFT marketplaces enable margin retention outside Meta and Epic Games platform gatekeeping. |
Methodological Framework
Direct dialogue with 3D technical artists, fashion house digital transformation leads, gaming platform monetization executives, blockchain infrastructure developers, and AR/UX designers grounded qualitative findings. Secondary validation drew from MIIT regulatory filings, EU AI Act implementation guidance, FTC disclosure enforcement actions, SEC filings by listed fashion conglomerates, and platform developer documentation. Bottom-up segment sizing triangulated against top-down market aggregation across product type, technology, end user, and application dimensions.
Bottom-up modeling anchored volume and value outputs across the projection horizon through polygon mesh production capacity estimates, platform transaction volume disclosures, and software licensing revenue patterns. Segmentation dimensions included product type complexity tier, technology infrastructure intensity, end user procurement scale, and application channel maturity. CAGRs derived from fitted growth curves incorporating gaming platform economics, social media filter adoption velocities, and regulatory implementation timelines. Physics-based simulation algorithm advances and blockchain ownership standardization served as primary technology trajectory inputs.
Platform policy reversals, GPU supply chain disruptions, and jurisdictional regulatory fragmentation are the dominant revision risks for forecast stability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Space Planning Software Market
Digital Solutions
Data Quality and Data Governance Solution Market
Digital Solutions
Global Parking Reservation System Market
Digital Solutions
Big Data Technology Market
Digital Solutions
Digital Project Delivery Solutions Market
Digital Solutions
Virtual Workspace Solutions Market
Digital Solutions
Global Online Classifieds Market
Digital Solutions
IT Monitoring Tools Market
Digital Solutions
Global Data Catalog Market
Digital Solutions
IT Operations Management Market
Digital Solutions
Global Computer Aided Dispatch Market
Digital Solutions
Governed Enterprise Architecture Scenario Sandbox Market
Digital Solutions
Real Time Bidding Market
Digital Solutions
Social Employee Recognition Systems Market
Digital Solutions
Asia-Pacific Digital Twin Market
Digital Solutions
Email Marketing Market