
 Global Digital Asset Management Software Market | 2026-2036
Global Digital Asset Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Digital Asset Management Software Market Foresight
Creative operations talent scarcity is unwinding traditional procurement cycles as enterprises prioritize platforms that reduce manual tagging and version-control overhead. Adobe leverages deep Creative Cloud integration to dominate design-centric workflows. Bynder anchors mid-market brand management with configurable portals. OpenText Corporation sustains enterprise-grade governance through robust permission architectures and long-term retention policies.
Digital Asset Management Software constitutes a centralized repository system with metadata indexing, version control, and rights-management protocols designed to store, retrieve, and distribute rich media files across organizational boundaries. Cloud-based deployment leads solution architecture due to elastic storage economics and distributed team enablement, while workflow automation captures expanding margin pools as enterprises seek to compress creative production cycles. Media & Entertainment end users drive volume, though rights management functionality sees accelerating attach rates as licensing complexity multiplies across streaming and syndication channels.
GDPR and the EU AI Act shape European data residency and automated content-tagging compliance requirements, while HIPAA constrains healthcare DAM implementations in the United States and Japan's METI guidelines influence domestic cloud procurement standards. DAM vendors must navigate divergent sovereignty rules as generative AI training data provenance becomes a procurement checkpoint. Stakeholders should monitor whether emerging copyright frameworks for synthetic media force architectural changes to ingestion pipelines and attribution tracking.
Market Dynamics
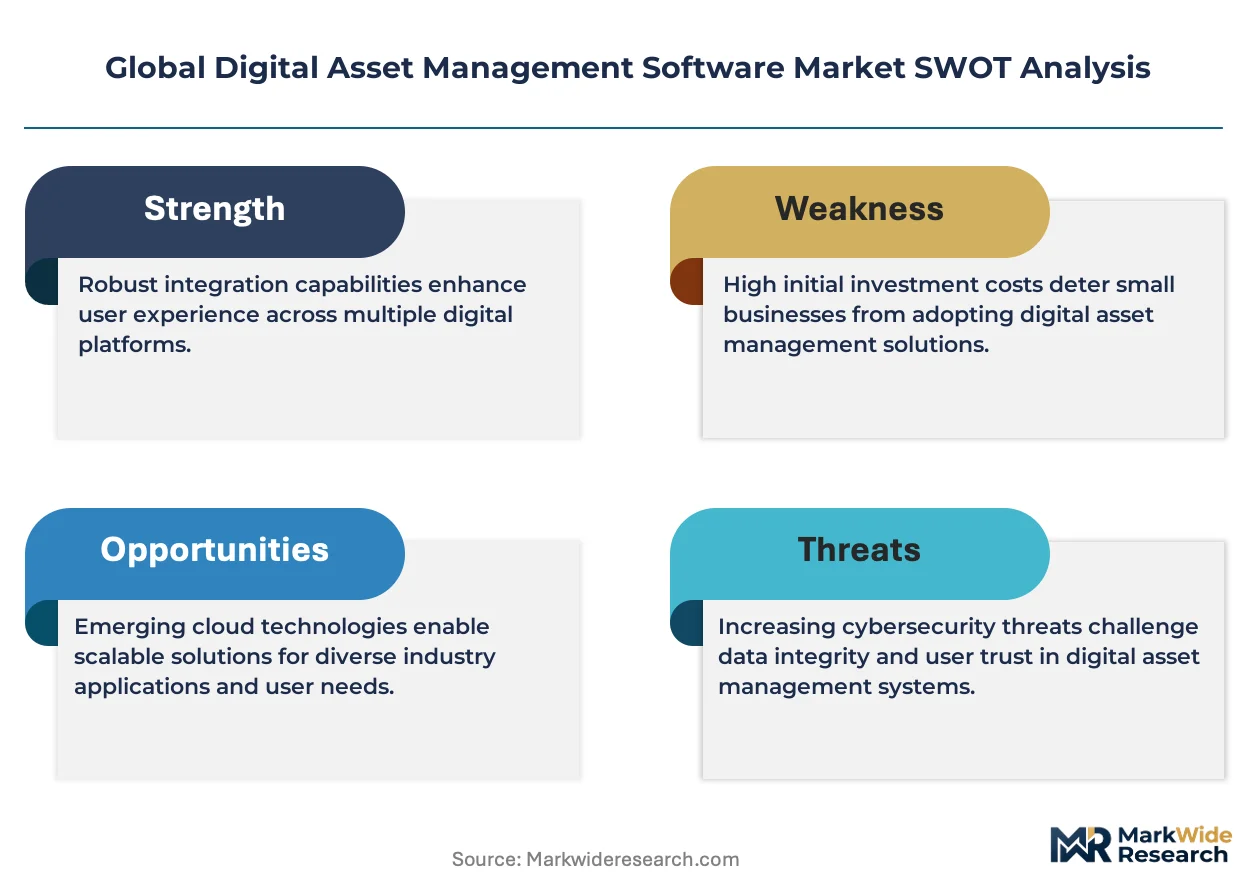
Generative AI training data provenance requirements are forcing DAM vendors to rebuild ingestion pipelines around synthetic media attribution tracking, compressing product roadmaps and elevating compliance engineering to core R&D priority.
Growth Catalysts
- EU AI Act automated content-tagging mandates:European enterprises must deploy AI-powered metadata systems for synthetic media detection, accelerating replacement of manual tagging workflows.
- Healthcare HIPAA-compliant cloud storage:United States hospital systems and pharmaceutical marketers require DAM architectures with audit trails for patient-facing creative assets.
- Elastic cloud economics:Distributed creative teams in Media & Entertainment sectors demand consumption-based storage scaling rather than capital-intensive on-premise deployments.
Market Restraints
- GPU compute cost volatility:AI-powered auto-tagging features depend on NVIDIA and AMD accelerator availability, creating margin pressure during supply crunches.
- Data residency fragmentation:Divergent sovereignty rules across Germany, Japan, and the United States force redundant infrastructure investments.
- Legacy on-premise sunk costs:Enterprises with existing OpenText or Adobe investments face high switching friction despite cloud advantages.
Strategic Opportunities
- India's PLI scheme for digital infrastructure:Domestic cloud procurement incentives create entry pathways for DAM vendors establishing Mumbai and Bangalore data centers.
- Retail omnichannel asset syndication:Unified product imagery workflows spanning e-commerce, in-store displays, and social commerce remain underpenetrated outside the United States and Germany.
- ISO 27001 and SOC 2 convergence:Dual certification as a procurement checkpoint opens mid-market segments previously gated by enterprise security requirements.
Industry Challenges
- Creative operations talent scarcity:Enterprises lack personnel capable of configuring workflow automation and metadata taxonomy design.
- Multi-cloud integration complexity:Hybrid deployments across AWS, Azure, and Google Cloud require specialized DevOps capabilities.
- Generative AI copyright ambiguity:Unclear attribution frameworks for synthetic media create legal exposure in training data sourcing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Digital Asset Management Software Market |
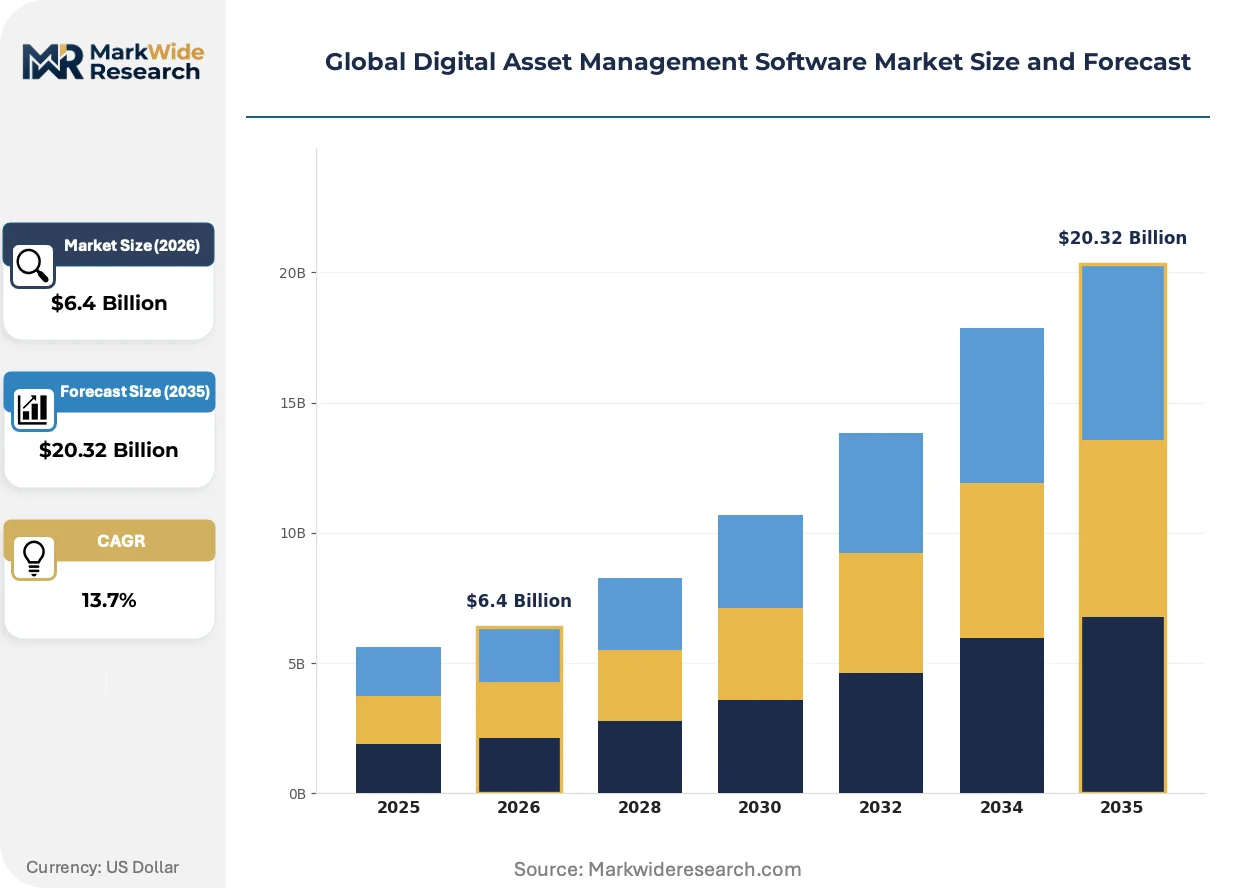
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $20.32 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, SaaS, Managed Services Solution Type: Media Management, Content Collaboration, Workflow Automation, Rights Management, Analytics Application: Marketing Campaigns, Brand Management, E-Learning, Digital Publishing, Event Management End User Industry: Media & Entertainment, Advertising Agencies, Educational Institutions, Government Agencies, Non-Profit Organizations |
| Companies Covered | Adobe, Bynder, Aprimo, Canto, Oracle Corporation, OpenText Corporation, IBM Corporation, Celum, Acquia DAM (Widen), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Digital Asset Management Software Market Shifts & Advancements
Foundation model-based auto-tagging is compressing implementation timelines from quarters to weeks, while regulatory pressure on AI training data is reshaping vendor competitive moats around provenance tooling rather than storage scale.
Multimodal AI embedding models are displacing rule-based metadata extraction in enterprise DAM deployments. Media & Entertainment buyers in Los Angeles and London are piloting systems that generate descriptive captions from video frames without human transcription. This capability is displacing offshore manual tagging services that previously captured fifteen to twenty percent of implementation budgets.
Japan's METI cloud procurement guidelines now mandate domestic data residency for public-sector DAM contracts. Japanese system integrators are rebuilding partner certification programs to qualify vendors for government and healthcare segments. Healthcare providers in Osaka and Tokyo are responding by segmenting asset libraries between domestic sovereign clouds and global creative collaboration platforms.
Outcome-based pricing tied to workflow automation metrics is replacing per-seat licensing in mid-market procurement. Brand management teams in Germany and the United Kingdom now negotiate contracts indexed to creative production cycle compression rather than user counts. This model is most visible in retail and CPG verticals where seasonal campaign velocity directly correlates to revenue performance.
Global Digital Asset Management Software Market Segmentation
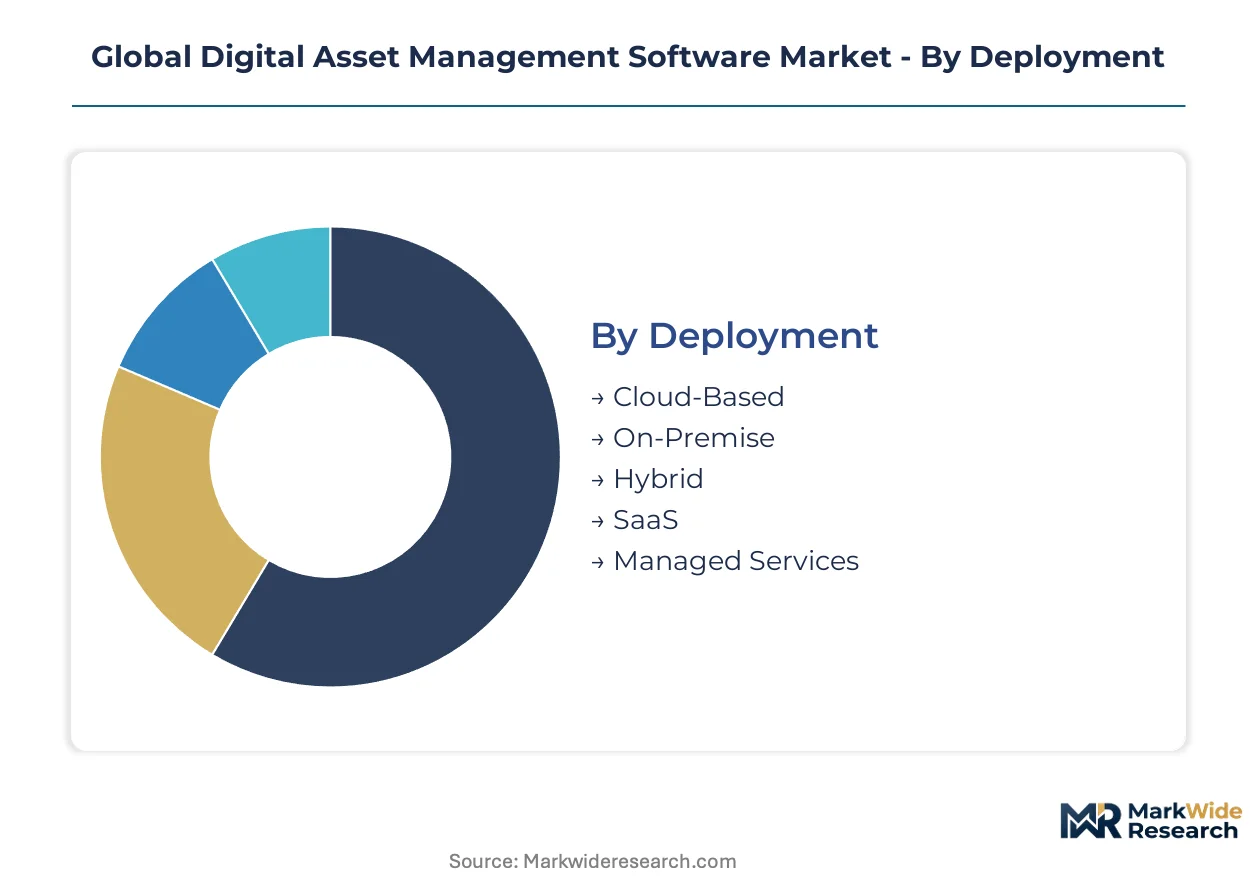
Segmentation in Digital Asset Management Software reveals how deployment architecture, functional modules, and industry verticals create divergent compliance requirements and margin profiles. Procurement patterns vary sharply between elastic cloud consumption in Media & Entertainment and rigid on-premise mandates in government healthcare systems.
Deployment:
GDPR, HIPAA, and Japan's METI guidelines each impose distinct residency and audit-trail requirements that reshape infrastructure choices across regulated versus unregulated buyers.
- Cloud-Based:Elastic storage economics dominate Media & Entertainment workflows in Los Angeles and London, though EU AI Act synthetic-media tagging mandates now require embedded provenance tooling that elevates base architecture costs. AWS, Azure, and Google Cloud compete for enterprise contracts where consumption-based scaling replaces capital-intensive procurement.
- On-Premise:Government agencies in Germany and Japan retain air-gapped deployments for classified or patient-facing creative assets, accepting higher total cost of ownership to satisfy national cybersecurity frameworks and HIPAA-level audit requirements. Hardware refresh cycles now extend to seven years as budget constraints harden.
- Hybrid:Split architectures segment asset libraries between domestic sovereign clouds and global collaboration platforms, particularly in Osaka and Tokyo healthcare networks responding to METI procurement guidelines.
- SaaS:Subscription models compress implementation timelines to weeks for mid-market advertising agencies in the United Kingdom and Germany seeking rapid workflow automation without dedicated DevOps staffing.
- Managed Services:Outsourced infrastructure operations appeal to educational institutions and non-profits lacking internal IT capacity, with vendors absorbing compliance documentation burdens for ISO 27001 and SOC 2 certification maintenance.
Established volume favors Cloud-Based; emerging adoption favors Hybrid.
Solution Type:
Functional modules compete for margin pools based on automation depth, with AI-powered extraction displacing manual services that previously captured implementation budgets.
- Media Management:Centralized repository systems with metadata indexing and version control form the technical foundation, demanded universally across end-user industries but facing commoditization pressure as storage economics flatten.
- Content Collaboration:Real-time annotation and approval workflows concentrate in advertising agencies and brand management teams across New York and London, where distributed creative production demands synchronous editing capabilities.
- Workflow Automation:Rule-based routing and approval chains are climbing the fastest in retail and CPG verticals, with outcome-based pricing tied to campaign velocity compression replacing per-seat licensing in German and UK procurement.
- Rights Management:Licensing complexity across streaming and syndication channels drives accelerating attach rates in Los Angeles and London Media & Entertainment clusters, where synthetic media attribution tracking is becoming a procurement checkpoint.
- Analytics:Usage telemetry and asset performance dashboards remain underpenetrated outside enterprise martech stacks, with mid-market buyers prioritizing operational functionality over measurement sophistication.
Workflow Automation gains share fastest; Analytics lags in mid-market penetration.
Application:
Use-case specificity determines integration depth with adjacent martech systems, with omnichannel consistency requirements elevating technical specifications in retail versus episodic deployment in education.
- Marketing Campaigns:Seasonal velocity demands in retail and CPG sectors compress production cycles through automated asset syndication across e-commerce, in-store displays, and social commerce channels, primarily in the United States and Germany.
- Brand Management:Configurable portals with permission architectures sustain governance for distributed franchise networks and multinational product portfolios, with configurable taxonomy design becoming a competitive differentiator.
- E-Learning:Educational institutions in Japan and Germany segment libraries between student-facing content and administrative assets, with SCORM compliance and accessibility standards shaping technical requirements.
- Digital Publishing:Rights-cleared image and video workflows serve news organizations and book publishers facing accelerated content refresh demands, though generative AI copyright ambiguity creates legal exposure in training data sourcing.
- Event Management:Time-bound asset creation for conferences and trade shows favors rapid-deployment SaaS models with minimal configuration overhead, often procured outside central IT governance.
Marketing Campaigns commands the largest absolute spend; E-Learning shows steepest expansion trajectory in institutional digitization.
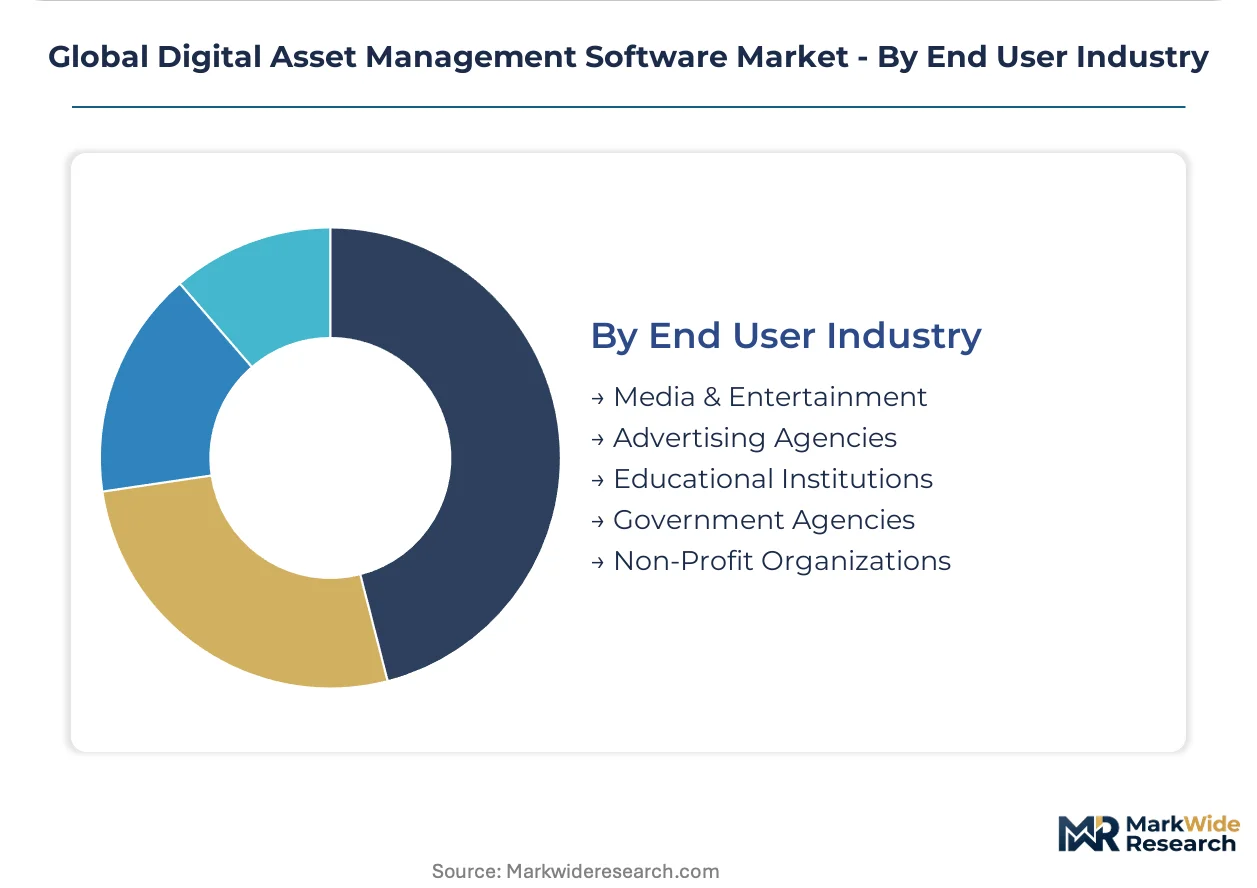
End User Industry:
Industry verticals impose divergent security, retention, and workflow requirements that fragment vendor competitive positioning between enterprise governance specialists and mid-market agility providers.
- Media & Entertainment:Volume leadership concentrates in Los Angeles and London production clusters, where multimodal AI embedding models now generate descriptive captions from video frames without human transcription, displacing offshore manual tagging services.
- Advertising Agencies:Project-based procurement cycles favor rapid implementation and flexible user scaling, with creative operations talent scarcity driving demand for pre-configured workflow templates rather than custom taxonomy design.
- Educational Institutions:Budget constraints and decentralized purchasing favor lightweight SaaS deployments, with accessibility compliance and student data privacy regulations shaping vendor selection criteria.
- Government Agencies:Domestic data residency mandates in Japan and Germany, combined with long-term retention policies, sustain demand for on-premise and sovereign cloud architectures despite elastic cloud economics.
- Non-Profit Organizations:Grant-funded procurement prioritizes cost transparency and donor-visible impact metrics, with managed services models reducing internal IT burden for mission-focused organizations.
Media & Entertainment anchors current revenue; Government Agencies provide most durable contract tenures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
DAM consumption patterns diverge sharply by geography: United States buyers prioritize Creative Cloud integration velocity, while German and Japanese procurement emphasizes sovereign data architectures and domestic residency mandates.
United States
Enterprise martech stack maturity drives demand for AI-powered auto-tagging and workflow automation among Los Angeles and New York media clusters. HIPAA audit-trail requirements shape hospital system and pharmaceutical marketer procurement specifications. Healthcare providers in Boston and pharmaceutical marketers in New Jersey segment asset libraries between patient-facing creative and internal administrative content.
Germany
GDPR data residency rules and EU AI Act synthetic-media detection mandates compress implementation timelines for automated metadata systems. Brand management teams in Munich and Hamburg negotiate outcome-based contracts indexed to campaign velocity rather than per-seat licensing. Industrial marketing clusters in Baden-Württemberg demand configurable taxonomy design for distributed franchise networks.
Japan
METI cloud procurement guidelines mandate domestic data residency for public-sector contracts, forcing segmentation between sovereign clouds and global collaboration platforms. Healthcare networks in Osaka and Tokyo partition asset libraries to satisfy national cybersecurity frameworks. System integrators in Tokyo rebuild partner certification programs to qualify vendors for government and healthcare segments.
United Kingdom
Mid-market advertising agencies in London prioritize rapid-deployment SaaS models with minimal DevOps overhead. Creative operations talent scarcity drives demand for pre-configured workflow templates rather than custom taxonomy design. Retail brand management teams negotiate contracts tied to omnichannel asset syndication across e-commerce and social commerce channels.
India
PLI scheme incentives for digital infrastructure create entry pathways for vendors establishing Mumbai and Bangalore data centers. Domestic cloud procurement preferences accelerate as enterprise martech adoption matures among Bangalore technology companies and Mumbai media houses. Educational institutions in Delhi-NCR favor lightweight SaaS deployments with accessibility compliance built into vendor selection criteria.
Global Digital Asset Management Software Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding premium positioning through deep creative workflow integration and enterprise governance capabilities. The middle tier competes on configurable portal agility and rapid implementation timelines. Two strategic archetypes dominate: design-centric platforms anchored in creative cloud ecosystems, and governance-focused vendors emphasizing permission architectures and long-term retention policies. Competitive moves concentrate on M&A for AI auto-tagging capabilities and geographic expansion through domestic data center establishment.
Within the integrated leader tier, Adobe and OpenText Corporation occupy positions at opposite ends of the workflow-governance spectrum, with the former exemplifying design-centric platform dominance and the latter representing enterprise-grade permission and retention specialization. Bynder anchors the mid-market brand management archetype with configurable portal approaches. Aprimo and Canto sit within the specialist tier, with Acquia DAM reflecting the consolidation trajectory of acquired platform capabilities.
| Leading Market Players |
|---|
| Adobe |
| Bynder |
| Aprimo |
| Canto |
| Oracle Corporation |
| OpenText Corporation |
| IBM Corporation |
| Celum |
| Acquia DAM (Widen) |
| Others |
Supply & Pricing Matrix
Elastic cloud storage economics compress unit costs as hyperscaler capacity scales, concentrating supply leverage among AWS, Azure, and Google Cloud while anchoring price floors for on-premise alternatives. This scale dynamic funnels mid-market buyers toward consumption-based SaaS tiers and forces legacy vendors to absorb margin pressure from GPU-dependent AI auto-tagging features.
Pricing Analysis
Contract structures stratify across annual subscriptions for enterprise governance tiers, monthly SaaS consumption for mid-market agility, and project-based licensing for episodic campaign workflows. Three-tier pricing separates premium AI-enabled suites with synthetic media provenance tooling from standard collaboration portals and economy storage-only tiers. Pricing pressure stems from NVIDIA accelerator supply crunches elevating auto-tagging feature costs. Healthcare and government buyers in Germany and Japan exhibit lowest price sensitivity due to compliance mandates, while mid-market advertising agencies in the United Kingdom drive hardest bargain hunting.
Supply Chain Analysis
Inventory lead times for GPU accelerators stretch to quarters during supply crunches, forcing DAM vendors to pre-commit cloud compute contracts. Infrastructure supply concentrates in the United States, Ireland, and Singapore where hyperscaler regions cluster. Software development draws from distributed engineering talent pools in India, Poland, and Portugal. Single-source vulnerability sits with NVIDIA for AI training inference chips. Distribution runs through direct enterprise sales teams for governance-heavy deployments and self-serve web channels for mid-market SaaS adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where switching costs lock enterprises into taxonomy investments and integration architectures, with regulatory entrenchment deepening as EU AI Act and HIPAA compliance requirements compound migration friction.
For Market Incumbents: Shield installed base through backward integration into AI auto-tagging model training, capturing proprietary metadata taxonomies as switching-cost amplifiers. Fortify position by establishing sovereign cloud data centers in Japan and Germany ahead of METI and GDPR enforcement waves. Emerging GPU cost volatility and open-source foundation model commoditization threaten premium pricing power.
For New Entrants and Emerging Players: Lead with vertical-specific workflow templates for retail omnichannel asset syndication, where seasonal campaign velocity demands outstrip incumbent configuration timelines. India's PLI-subsidized cloud infrastructure offers lowest competitive density for domestic data center establishment. Partner with Mumbai system integrators to bypass direct enterprise sales cost structures.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors governance-specialist vendors with HIPAA and EU AI Act certification moats over design-centric platforms facing Creative Cloud integration pressure. Acquisition targets with proven sovereign cloud deployments in Osaka and Berlin command durability premiums. Watch generative AI copyright framework clarity as inflection signal for provenance-tooling valuation resets.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Auto-Tagging Capability Acquisition | Foundation model integration displaces manual tagging services that captured implementation budgets. |
| Sovereign Cloud Data Center Expansion | METI and GDPR residency mandates force geographic infrastructure segmentation for contract eligibility. |
| Outcome-Based Pricing Model Rollout | Campaign velocity indexing aligns vendor incentives with retail seasonal production cycle compression. |
| Synthetic Media Provenance Tooling Buildout | EU AI Act automated content-tagging mandates elevate compliance engineering to core R&D priority. |
| Healthcare-Specific Compliance Certification | HIPAA audit-trail requirements gate hospital system and pharmaceutical marketer procurement decisions. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of vendor financial disclosures, hyperscaler infrastructure investment reports, and regulatory filing databases. Primary interviews engaged chief technology officers at enterprise martech stack owners, creative operations directors at retail brand teams, and compliance officers at healthcare systems. Secondary sources encompassed SEC 10-K software segment disclosures, EU AI Act implementation guidance documents, and METI cloud procurement guideline updates. Bottom-up deployment model sizing triangulated against top-down enterprise software spend allocation estimates.
Segmentation dimensions modeled span deployment architecture, functional solution modules, end-user industry verticals, and geographic regulatory clusters across the projection horizon. CAGRs derived from elasticity-adjusted adoption curves weighted by cloud infrastructure maturity indices and AI feature penetration assumptions. Forecast inputs incorporated GPU supply constraint scenarios and sovereign cloud procurement policy trajectories.
The analysis sits within stated boundaries; outcomes outside sustained hyperscaler price competition or accelerated copyright framework enforcement would require recalibration. Forecasts reflect documented assumptions regarding regulatory implementation timelines and technology adoption elasticity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Data Classification Tool Market
Digital Solutions
Interactive Response Technology Market
Digital Solutions
Global Transport Management Software Market
Digital Solutions
Digital User Experience Solutions Market
Digital Solutions
Global Freight Software Market
Digital Solutions
Container Management Software Market
Digital Solutions
Australia Digital Marketing Software Market
Digital Solutions
Canada ICT Market
Digital Solutions
Global Web Hosting Service Market
Digital Solutions
Global Procurement-As-A-Service (PAAS) Market
Digital Solutions
Digital Business Support System Market
Digital Solutions
Digital Dispenser Systems Market
Digital Solutions
Desktop Virtualization Market
Digital Solutions
Global Handwriting Digital Pen Market
Digital Solutions
Crowdsourcing Market
Digital Solutions
Crop Management Software Market