
 Speech and Voice Analytics Market | 2026-2036
Speech and Voice Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Speech and Voice Analytics Market Analytics
Enterprise software distribution is rewriting how speech analytics reaches end users. NICE leverages direct channel partnerships with Fortune 500 banks to sustain premium positioning. Verint Systems anchors its footprint through telecom carrier relationships. Google competes via cloud API access that extends developer adoption across mid-market call centers.
Speech and voice analytics encompasses AI-driven processing of acoustic signals, phonetic patterns, and linguistic content to extract operational intelligence from verbal interactions, typically operating at latency thresholds below 300 milliseconds for real-time agent guidance. The technology serves commercial purposes spanning automated quality assurance, regulatory compliance verification, and predictive churn intervention. Cloud-based deployment captures the fastest expansion as enterprises abandon capital-intensive on-premises infrastructure for consumption-priced models. Voice biometrics solutions command margin premiums due to specialized algorithmic requirements and stringent accuracy benchmarks. Customer service applications dominate current revenue flows while fraud detection segments accelerate on banking sector urgency.
FCC guidelines on robocall mitigation and the EU AI Act's risk classification for biometric identification systems shape product development roadmaps and market access conditions. GDPR consent frameworks and HIPAA voice data safeguards impose architectural constraints on cross-border data flows and retention protocols. Stakeholders must monitor evolving algorithmic accountability requirements across multiple jurisdictions to anticipate compliance cost trajectories and competitive differentiation opportunities.
Market Dynamics
Cloud migration is compressing deployment cycles for speech analytics platforms while GDPR and the EU AI Act impose architectural constraints on biometric voice processing. Banking contact centers now demand sub-300 millisecond latency for real-time fraud intervention.
Growth Catalysts
- EU AI Act risk classification:Mandatory algorithmic accountability for biometric identification systems is forcing platform upgrades across European banking infrastructure.
- Voice biometrics in fraud prevention:Banking contact centers deploy acoustic pattern recognition to replace knowledge-based authentication, cutting average handle time.
- Real-time agent guidance:Phonetic analysis operating below 300 millisecond latency enables live coaching during customer interactions.
Market Restraints
- Cross-border data friction:GDPR consent frameworks block voice data transfers between EU and non-EU processing centers without explicit opt-in architecture.
- Specialized compute costs:GPU clusters for acoustic model training concentrate in hyperscaler regions, creating input cost volatility for mid-market vendors.
- Legacy telephony integration:Time-division multiplexing infrastructure in established contact centers requires expensive gateway hardware for IP-based analytics.
Strategic Opportunities
- Healthcare transcription convergence:HIPAA-compliant voice processing for clinical documentation remains underpenetrated relative to banking adoption.
- API-first distribution:Cloud-native vendors bypass traditional systems integrators through direct developer portal access.
- FCC robocall mitigation mandate:STIR/SHAKEN compliance creates certified analytics demand for call authentication verification.
Industry Challenges
- Phonetic model specialization:Shortage of computational linguists with dialect-specific training constrains accuracy improvement in non-English language support.
- Retention protocol complexity:Conflicting GDPR deletion timelines and banking audit requirements force expensive dual-database architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Speech and Voice Analytics Market |
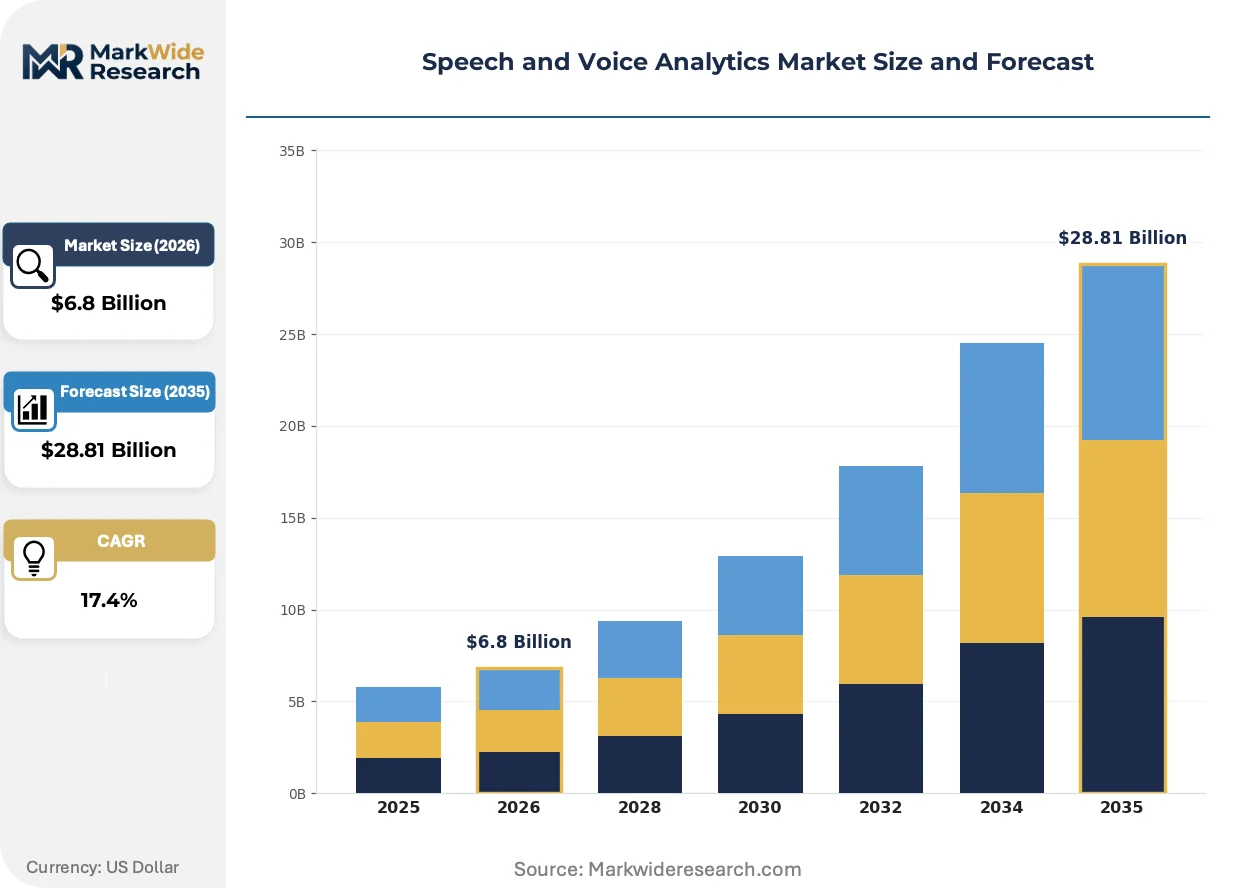
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $28.81 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Edge End User: Retail, Telecom, Healthcare, Banking Solution: Speech Recognition, Voice Biometrics, Sentiment Analysis, Call Monitoring Application: Customer Service, Market Research, Fraud Detection, Compliance Monitoring |
| Companies Covered | NICE, Verint Systems, Avaya, Genesys, CallMiner, OpenText, Google, Amazon Web Services, Uniphore, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Speech and Voice Analytics Market Evolving Landscape
Acoustic signal processing is fusing with large language models to enable context-aware transcription. Regulatory pressure on biometric data is fragmenting vendor architectures. Procurement patterns favor consumption-priced APIs over perpetual licenses.
Transformer-based speech recognition is hybridizing with traditional hidden Markov models to balance accuracy against edge-deployment constraints. Mid-market call centers in the United States adopt these hybrid stacks fastest. The convergence is compressing price premiums for pure-cloud solutions while extending functionality to on-premises environments.
The EU AI Act's high-risk system designation for biometric identification is mandating human-in-the-loop review architectures. Platform vendors must reengineer real-time pipelines to accommodate intervention checkpoints. Banking deployments across Germany, France, and Italy face the steepest compliance cost trajectories.
Enterprise buyers now unbundle quality assurance from workforce optimization suites. Standalone speech analytics APIs from cloud providers displace integrated platform renewals. This pattern concentrates in North American financial services where IT procurement teams favor modular best-of-breed stacks over single-vendor consolidation.
Speech and Voice Analytics Market Segmentation
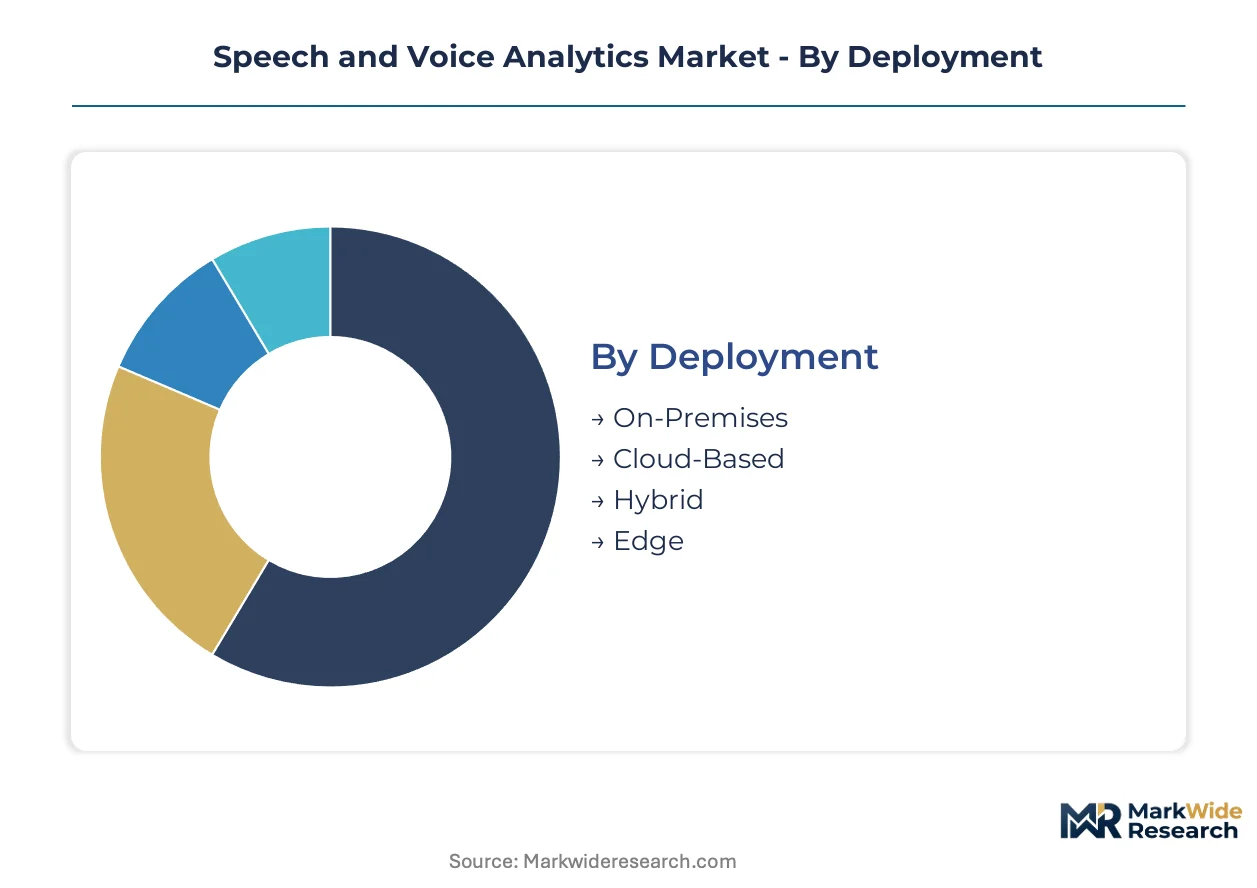
Speech and voice analytics vendors configure platform architectures around four critical dimensions: how software deploys, who consumes the output, what technical capability delivers value, and which operational problem gets solved. These segmentation layers determine pricing models, compliance obligations, and integration complexity for enterprise buyers.
Deployment:
Mature on-premises installations coexist with emerging edge-computing architectures as latency requirements tighten across banking and healthcare use cases.
- On-Premises:Dedicated hardware clusters within enterprise data centers process sensitive voice data behind firewall perimeters. Banking contact centers in Germany and France favor this model to satisfy EU AI Act biometric processing constraints and GDPR data localization mandates.
- Cloud-Based:Consumption-priced API access eliminates capital expenditure and accelerates deployment cycles. United States mid-market call centers adopt this fastest as IT procurement teams favor operational expenditure models and rapid scaling without infrastructure procurement delays.
- Hybrid:Split architectures route sensitive authentication data to on-premises nodes while pushing transcription workloads to cloud elasticity. Healthcare systems use this to isolate HIPAA-protected patient identifiers from general analytics processing.
- Edge:On-device inference at call center endpoints achieves sub-300 millisecond latency for real-time agent guidance. Telecom carriers pilot this for network-optimized fraud intervention without backhaul delays.
Cloud-based deployment handles the majority of new customer acquisitions; edge computing is the fastest mover on share as latency specifications harden.
End User:
Cost tier stratification separates high-margin regulated sectors from volume-driven consumer industries.
- Banking:Voice biometrics for fraud prevention and EU AI Act compliance drive premium pricing. Sub-300 millisecond latency requirements and algorithmic accountability mandates concentrate demand among tier-one institutions in the United States, Germany, and United Kingdom.
- Healthcare:HIPAA-compliant clinical documentation and ambient listening for electronic health records represent underpenetrated expansion territory. United States hospital systems and outpatient networks are the primary demand concentration.
- Telecom:FCC STIR/SHAKEN robocall mitigation compliance creates certified analytics demand. Carrier relationships anchor vendor footprint through multi-year infrastructure contracts.
- Retail:E-commerce voice assistants and contact center quality assurance operate at lower price points with standardized API consumption models.
Banking contributes the highest revenue per seat; healthcare is expanding most quickly as clinical documentation automation penetrates provider workflows.
Solution:
Technology maturity varies sharply across functional layers, with biometric authentication commanding specialized algorithmic premiums.
- Voice Biometrics:Acoustic pattern recognition for speaker identification and verification replaces knowledge-based authentication. Banking contact centers deploy this to cut average handle time while satisfying stringent accuracy benchmarks for fraud prevention.
- Speech Recognition:Phonetic-to-text transcription with transformer-based architectures achieves near-human accuracy. Cloud API distribution extends adoption across mid-market call centers in the United States seeking automated quality assurance.
- Sentiment Analysis:Prosodic feature extraction detects emotional valence in customer interactions. Retail and telecom applications dominate current deployments for churn prediction and escalation routing.
- Call Monitoring:Post-interaction analytics for compliance verification and coaching workflow integration. Regulatory pressure from GDPR and HIPAA drives retention protocol complexity in this segment.
Speech recognition handles the highest transaction volumes; voice biometrics is gaining share fastest as fraud losses accelerate authentication modernization.
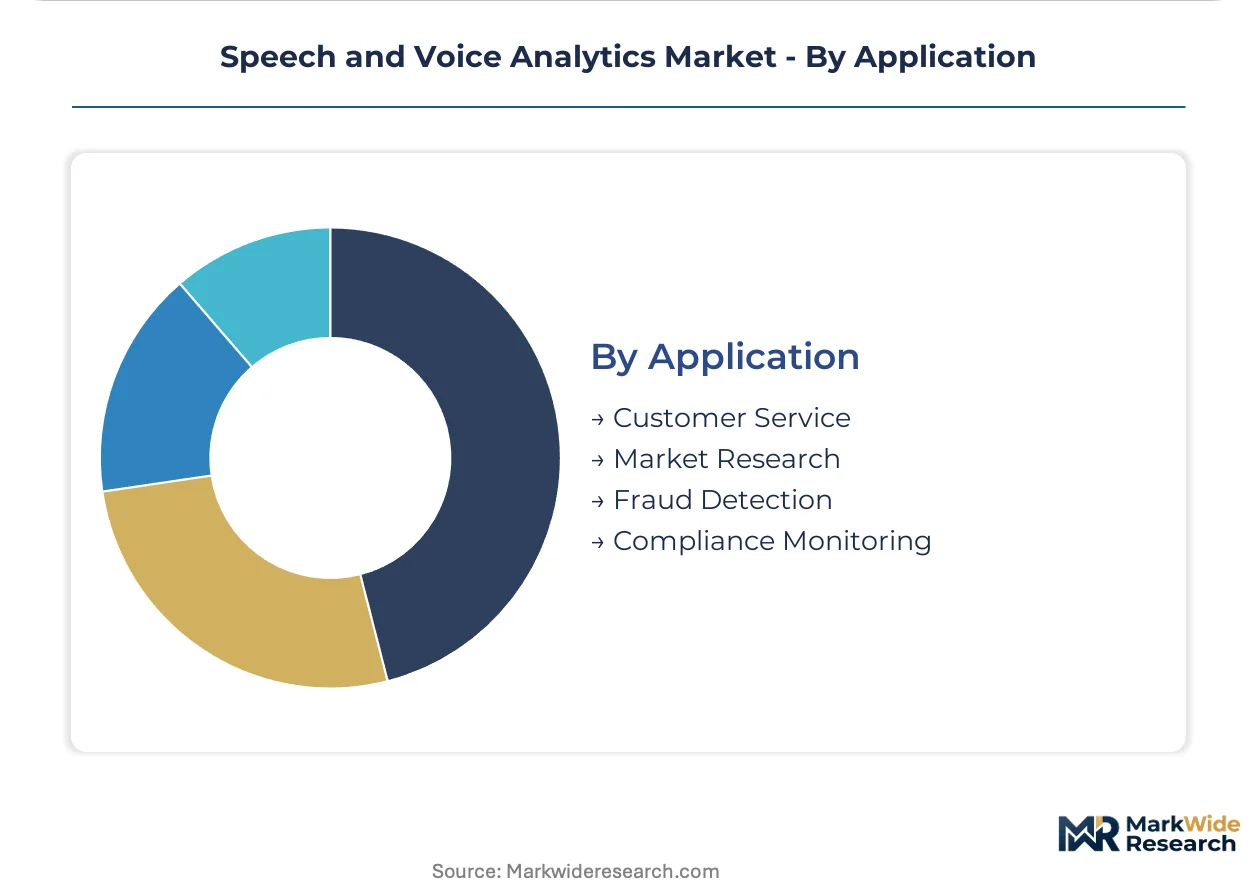
Application:
Customer-facing use cases dominate current revenue while risk-management applications capture expanding procurement attention.
- Customer Service:Real-time agent guidance and automated quality scoring for contact center operations. United States enterprise software procurement concentrates here with modular API preferences over integrated suites.
- Fraud Detection:Voice biometrics and anomaly detection for authentication and transaction verification. Banking sector urgency in the United States and European Union drives steepest compliance cost trajectories.
- Compliance Monitoring:Retention, retrieval, and audit-trail generation for regulatory examination. GDPR deletion timelines and banking audit requirements force expensive dual-database architectures in this application.
- Market Research:Conversational analytics for consumer insight extraction from recorded interviews. Lower penetration relative to operational applications reflects slower ROI demonstration.
Customer service absorbs the majority of platform throughput; fraud detection is climbing the fastest as biometric mandates tighten across financial services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC guidelines on robocall mitigation and the EU AI Act's biometric risk classification are redirecting procurement budgets toward compliant architectures. Banking contact centers in Germany and France now mandate sub-300 millisecond latency specifications. United States enterprise software teams favor modular API consumption over integrated platform renewals.
United States
Enterprise software procurement concentrates in Fortune 500 banking and telecom verticals. FCC STIR/SHAKEN mandates create certified analytics demand for call authentication verification. Greater Boston and New York Metro anchor vendor development activity for real-time agent guidance systems.
Germany
Tier-one banking institutions drive premium pricing for voice biometrics and algorithmic accountability. GDPR data localization requirements and EU AI Act high-risk system designations favor on-premises deployment architectures. Frankfurt and Munich financial clusters pilot human-in-the-loop review checkpoints for biometric processing pipelines.
United Kingdom
Banking contact centers demand fraud prevention solutions with stringent accuracy benchmarks. Post-Brexit data adequacy negotiations complicate cross-border voice transfers to EU processing centers. London's fintech corridor concentrates demand for cloud-native quality assurance APIs.
France
CNIL enforcement actions tighten consent architecture requirements for voice data retention. EU AI Act compliance costs concentrate in Paris and Lyon banking infrastructure upgrades. Healthcare systems in Île-de-France explore HIPAA-equivalent safeguards for clinical documentation automation.
India
RBI guidelines on digital payment security accelerate voice biometric adoption in banking contact centers. TRAI regulations on unsolicited commercial communication create demand for call authentication analytics. Bengaluru and Hyderabad technology corridors host development centers for dialect-specific acoustic model training.
Speech and Voice Analytics Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers differentiated by channel access and deployment architecture. Hyperscalers compete through cloud API distribution while legacy platform vendors defend installed bases through carrier and banking relationships. The competitive arena splits between M&A-driven portfolio expansion and direct developer portal strategies that bypass traditional systems integrators.
Within the legacy platform tier, NICE and Verint Systems exemplify entrenched positions sustained through Fortune 500 banking partnerships and telecom carrier anchoring. Google occupies a position representing the cloud-native API vector, competing via consumption-priced developer access that extends adoption across mid-market call centers. These three anchors illustrate how channel strategy differentiation—direct enterprise sales versus cloud marketplace distribution—determines addressable market geometry.
| Leading Market Players |
|---|
| NICE |
| Verint Systems |
| Avaya |
| Genesys |
| CallMiner |
| OpenText |
| Amazon Web Services |
| Uniphore |
| Others |
Value Network & Pricing Analysis
GPU cluster concentration in United States and Chinese hyperscaler regions concentrates acoustic model training costs among tier-one vendors, pushing margin pools toward voice biometrics specialists with captive algorithmic development. Cloud API distribution compresses price premiums for standardized speech recognition while edge-computing latency specifications sustain premium tiers for real-time banking deployments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates voice biometrics with sub-300 millisecond latency guarantees from cloud-transcription APIs and basic call-monitoring suites. Price differentiation rests on EU AI Act certification grade and customization depth for biometric accountability architectures. Cost compression in standard-tier speech recognition is intensifying because hyperscaler API commoditization erodes vendor margins. Mid-market United States call centers exhibit highest price sensitivity; tier-one European banking institutions show least.
Supply Chain Analysis
Extended payment terms from hyperscaler cloud providers anchor supplier-financing structures for mid-market vendors lacking capital reserves for GPU cluster procurement. Hardware dependencies draw from Taiwan semiconductor fabrication, United States chip design, and Chinese rare-earth magnet processing for acoustic sensor components. Single-source vulnerability concentrates in NVIDIA GPU supply for transformer model training. Distribution runs through direct enterprise sales for banking verticals and developer portal self-service for mid-market adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Speech and voice analytics functions as a service-attach opportunity where consumption-priced API renewals and compliance-monitoring subscriptions expand faster than perpetual license hardware. Recurring revenue from real-time agent guidance and fraud-detection algorithm updates outpaces upfront platform deployment.
For Market Incumbents: Entrench through EU AI Act certification investment and human-in-the-loop pipeline engineering that emerging cloud-native entrants cannot replicate without banking relationship depth. Fortify carrier and Fortune 500 anchoring against Google and Amazon API displacement by embedding workforce optimization integration. Vertical integration into dialect-specific acoustic model training secures non-English language accuracy moats.
For New Entrants and Emerging Players: Pursue healthcare clinical documentation automation where HIPAA-compliant ambient listening remains underpenetrated relative to banking saturation. Target United States outpatient networks and regional hospital systems lacking legacy telephony integration burdens. API-first developer portal distribution bypasses systems integrator gatekeeping that protects incumbent positions.
For Investors and Strategic Acquirers: Capital is best deployed toward voice biometrics specialists with EU AI Act high-risk system certifications and banking deployment references. Long-term viability hinges on regulatory compliance moats deepening faster than hyperscaler API commoditization. Watch for FCC STIR/SHAKEN mandate expansion into enterprise voice authentication as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Certification | Human-in-the-loop biometric pipelines unlock tier-one European banking procurement. |
| Healthcare Ambient Listening Launch | HIPAA-compliant clinical documentation captures provider workflow automation demand. |
| Edge Computing Partnership | Telecom carrier alliances enable sub-300 millisecond fraud intervention without backhaul. |
| API Marketplace Integration | Hyperscaler developer portals extend mid-market call center reach beyond direct sales. |
| Dialect Model Acquisition | Computational linguist teams with non-English acoustic training address phonetic specialization gaps. |
Research Methodology
Operator-level perspectives from contact center operations directors, biometric security architects, compliance officers at tier-one banks, and cloud procurement leads anchored the qualitative base. These primary inputs combined with secondary validation from FCC robocall mitigation filings, EU AI Act implementation guidance, HIPAA enforcement actions, and hyperscaler capex disclosures. Bottom-up deployment model sizing triangulated against top-down enterprise software spending patterns.
Scenario-bracketing framed analytical approach across the modeling period, with segmentation dimensions spanning deployment architecture, end-user vertical, solution capability tier, and application use case. CAGRs derived from fitted growth curves against historical banking and telecom adoption trajectories. Forecast inputs incorporated GPU cluster cost trajectories and regulatory compliance timeline acceleration.
Sensitivities concentrate around EU AI Act enforcement variance, hyperscaler API pricing aggression, and healthcare reimbursement policy for clinical documentation automation. Forecasts reflect documented assumptions on latency specification hardening and biometric accuracy benchmark evolution. Macroeconomic contraction in enterprise software procurement, regulatory deviation from current GDPR and EU AI Act frameworks, or breakthrough edge-device inference cost reduction would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Application Metrics and Monitoring Tools Market
Analytics
Predictive Analytics Market
Analytics
Global Telco Data Monetization Market
Analytics
Embedded Business Intelligence Market
Analytics
North America Crowd Analytics Market
Analytics
Contact Center Intelligence Market
Analytics
Practice Analytics Market
Analytics
Global in-Memory Analytics Market
Analytics
App Analytics Market
Analytics
Europe Network and Location Analytics Market
Analytics
Cyprus ICT Market
Analytics
Global Development Analytics Tools Market
Analytics
Global AI Video Analytics Market
Analytics
Automated Analytics Market
Analytics
Sentiment Analytics Market
Analytics
Saudi Arabia Geospatial Analytics Market