
 Motion Control Centers Market | 2026-2036
Motion Control Centers Market Size, Share, and Industry Trends Forecast 2026-2036
Motion Control Centers Market Foresight
Direct technical sales channels is reconfiguring how motion control centers reach end users in heavy manufacturing and robotics sectors. Siemens leverages vertical integration into servo drive production to control component availability across European automation clusters. ABB anchors its market presence through deep specialization in high-precision CNC machinery applications. Rockwell Automation differentiates via programmable logic platforms that dominate North American automotive assembly lines.
Motion control centers integrate servo drives, controllers, and actuators into unified electromechanical systems that coordinate multi-axis positioning with sub-micron accuracy through closed-loop feedback architectures. These assemblies synchronize motor torque, velocity, and positional data to execute complex trajectories in material handling and packaging environments. Servo drives capture the dominant margin pool due to power electronics complexity and thermal management requirements, while EtherCAT-enabled digital control architectures represent the fastest-expanding technology segment as machine builders abandon analog fieldbus topologies. Controllers maintain mature revenue stability in legacy retrofit markets where analog control installations persist.
IEC 61508 and the EU Machinery Directive impose functional safety integrity levels on multi-axis motion systems sold into European robotics and aerospace end uses. The EPA's energy efficiency guidelines and OSHA electrical safety standards shape product design requirements for US manufacturing deployments. Stakeholders must monitor how China's GB standards for industrial automation equipment evolve relative to IEC frameworks, as divergence would fragment certification pathways for multinational suppliers.
Market Dynamics
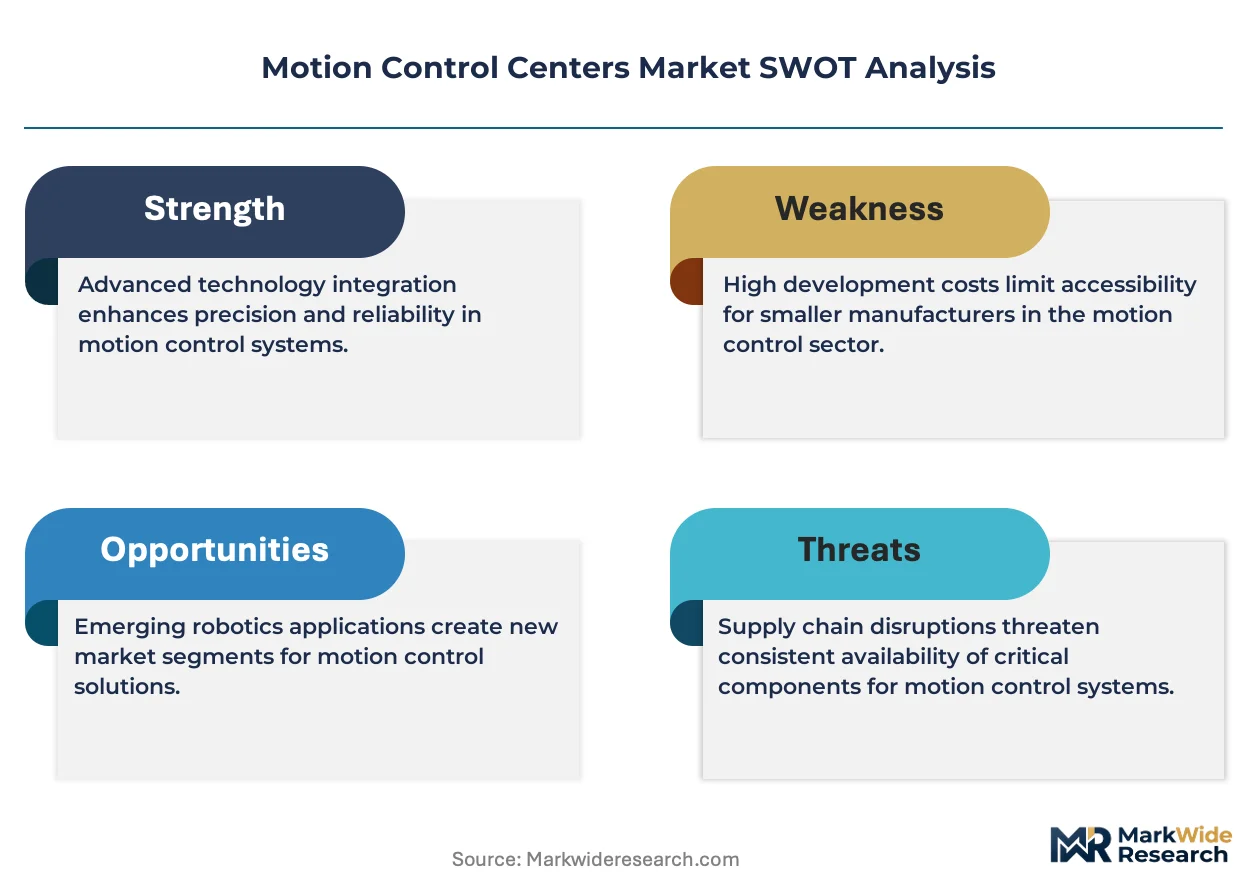
Motion control centers face structural pressure from the convergence of IEC 61508 functional safety mandates and the abandonment of analog fieldbus architectures. Machine builders in Germany, Japan, and the United States now demand EtherCAT-enabled digital platforms that integrate servo drives, controllers, and actuators into unified closed-loop systems.
Growth Catalysts
- EU Machinery Directive compliance:European robotics and aerospace end uses require SIL-rated multi-axis motion systems, forcing upgrades across installed bases.
- Servo-controller integration:Automotive assembly lines in Germany, Japan, and the United States expand adoption of unified electromechanical architectures.
- Yangtze River Delta concentration:Chinese machine builders source complete motion subsystems, creating dense demand clusters for domestic and multinational suppliers.
Market Restraints
- Power electronics cost volatility:Servo drives capture dominant margins due to thermal management complexity, exposing suppliers to semiconductor input price swings.
- Certification pathway fragmentation:China's evolving GB standards for industrial automation equipment risk diverging from IEC frameworks.
- Analog controller obsolescence drag:Legacy retrofit markets with persistent analog control installations delay full digital migration.
Strategic Opportunities
- Sub-micron precision applications:High-precision CNC machinery segments remain underpenetrated by integrated motion subsystems.
- Material handling convergence:Packaging environments require synchronized multi-axis positioning that hybridizes servo torque control with predictive trajectory algorithms.
- EPA energy efficiency guidelines:US manufacturing deployments face tightening electrical safety standards that favor next-generation thermal management designs.
Industry Challenges
- Functional safety engineering scarcity:SIL certification expertise concentrates among European automation specialists, constraining expansion timelines.
- Multi-axis integration complexity:Closed-loop feedback architectures require specialized commissioning that extends deployment cycles in brownfield facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motion Control Centers Market |
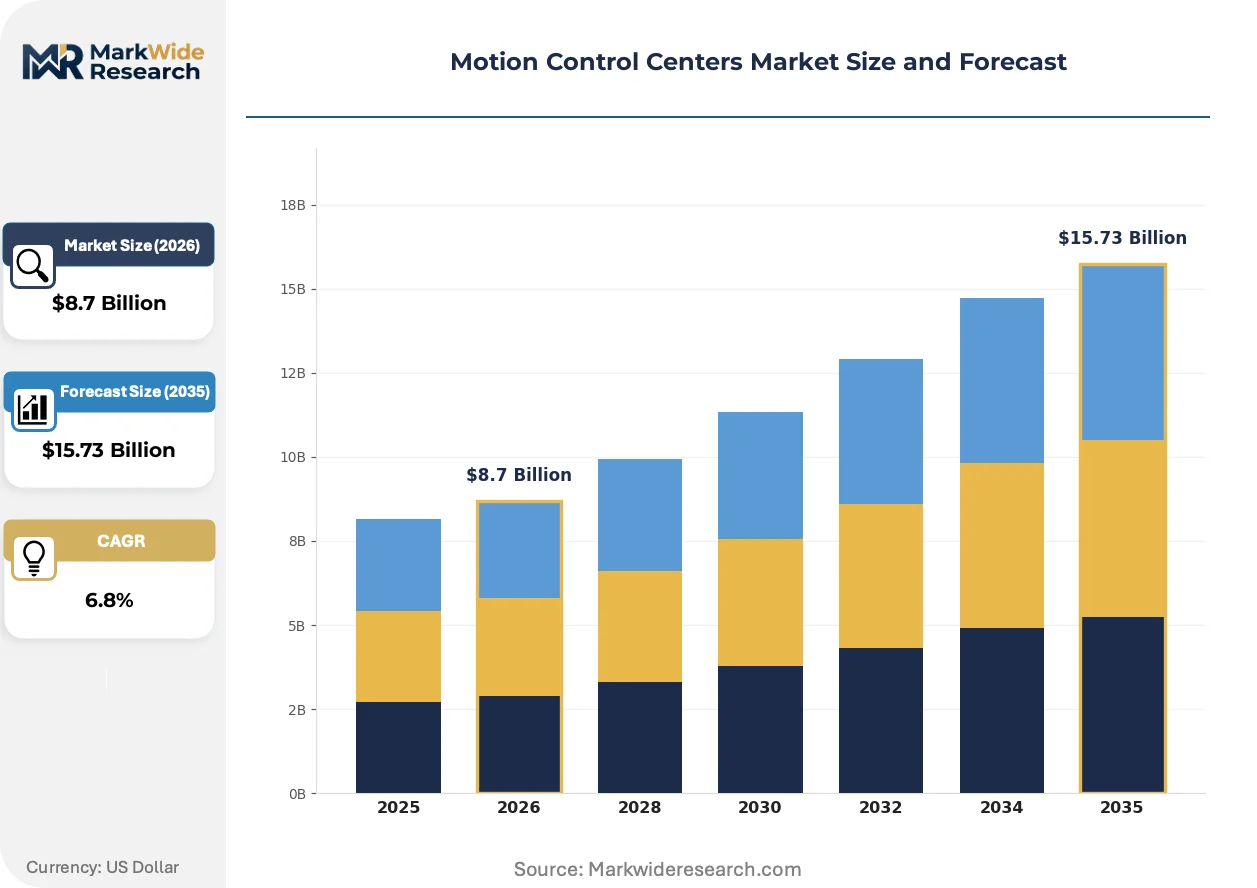
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Servo Drives, Stepper Motors, Controllers, Actuators End User: Manufacturing, Robotics, Aerospace, Automotive Technology: Digital Control, Analog Control, Programmable Logic, EtherCAT Application: Material Handling, Assembly Automation, CNC Machinery, Packaging |
| Companies Covered | Siemens, ABB, Schneider Electric, Mitsubishi Electric, Rockwell Automation, FANUC Corporation, Yaskawa Electric Corporation, Omron Corporation, Eaton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motion Control Centers Market Shifts & Advancements
Digital control architectures are compressing the technology lifecycle for motion control centers as machine builders abandon analog fieldbus topologies. Three developments dominate competitive positioning.
EtherCAT-enabled servo drive platforms is hybridizing real-time motion control with industrial IoT connectivity layers. Automotive assembly lines in Germany and the United States adopt these architectures fastest. The technology is compressing hardware differentiation and shifting margin capture toward software-defined motion profiles.
REACH and RoHS substance restrictions are tightening material compliance for power electronics in European-deployed systems. Component suppliers must requalify thermal interface materials and PCB substrates. High-precision CNC machinery applications face the steepest recertification burdens.
Direct technical sales channels are displacing traditional distributor networks in heavy manufacturing and robotics sectors. System integrators in the Yangtze River Delta now source complete motion subsystems through supplier-managed technical relationships. Germany and Japan show parallel channel compression as buyers prioritize application engineering over inventory proximity.
Motion Control Centers Market Segmentation
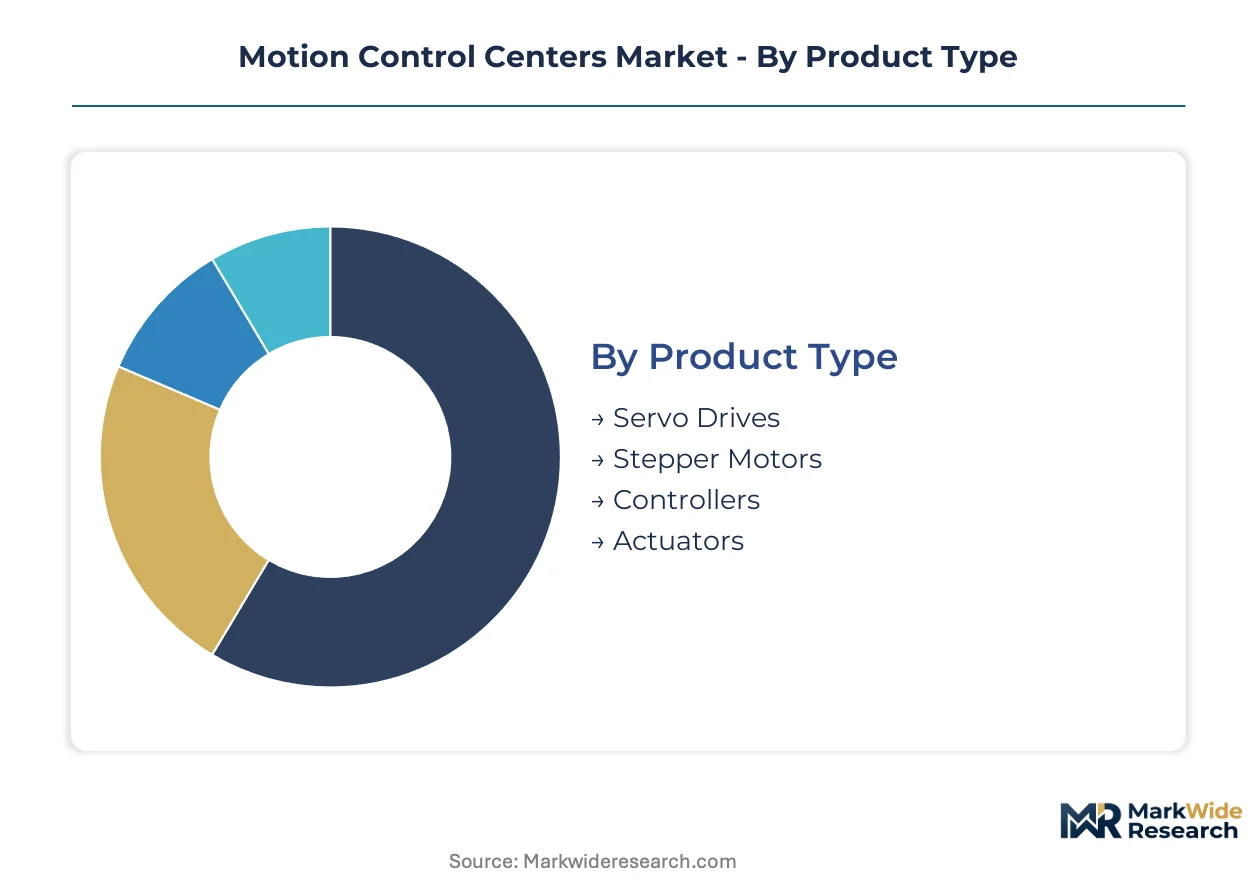
Motion control centers require differentiated service architectures across product tiers. Servo drive platforms demand intensive field engineering support, while controller retrofits operate through standardized maintenance contracts. Segmentation reveals where technical sales investments concentrate versus where volume economics dominate.
Product Type:
After-sales service intensity varies sharply across product categories. Servo drives require thermal management recalibration and power electronics diagnostics that extend field engineer deployment cycles. Stepper motors and basic controllers ship with remote troubleshooting protocols that compress service margins.
- Servo Drives:Power electronics assemblies with integrated thermal management systems coordinate motor torque through closed-loop feedback architectures. Demand concentrates in Germany and Japan where automotive assembly lines require SIL-rated multi-axis platforms. IEC 61508 certification mandates force recurring firmware validation cycles that deepen supplier-customer technical relationships.
- Controllers:Digital and analog control platforms execute trajectory algorithms across material handling and packaging environments. China's Yangtze River Delta machine builders source these through direct technical channels that bypass traditional distributor networks. The shift toward EtherCAT-enabled architectures accelerates controller replacement cycles in brownfield European facilities.
- Stepper Motors:Open-loop positioning systems serve cost-sensitive material handling applications with reduced precision requirements.
- Actuators:Electromechanical motion converters integrate with servo drives in high-precision CNC machinery segments.
Servo drives hold the largest share; momentum sits with controllers as analog-to-digital migration accelerates.
End User:
Cost tier differentiation separates capital-intensive aerospace deployments from high-volume manufacturing installations. Aerospace and automotive sectors absorb premium pricing for SIL-certified platforms, while general manufacturing prioritizes total cost of ownership metrics.
- Automotive:Assembly line automation demands sub-micron positioning accuracy for welding and painting robots across German, Japanese, and US facilities. Integrated servo-controller architectures reduce commissioning time in greenfield plants. EPA energy efficiency guidelines and OSHA electrical safety standards shape procurement specifications for North American deployments.
- Robotics:Multi-axis coordination platforms require real-time trajectory optimization for collaborative and industrial robot arms. European robotics OEMs face EU Machinery Directive compliance burdens that concentrate demand among certified system integrators. REACH and RoHS substance restrictions add material recertification costs for power electronics suppliers.
- Manufacturing:General industrial automation spans packaging, material handling, and discrete assembly with varying precision requirements.
- Aerospace:Flight control surface testing and satellite positioning systems demand extreme precision with extended validation protocols.
Manufacturing holds the largest share; aerospace climbs the fastest as satellite production scales.
Technology:
Volume concentration tracks the abandonment of legacy fieldbus architectures. EtherCAT and digital control platforms capture expanding share as machine builders retire analog installations, though programmable logic retains retrofit market presence.
- EtherCAT:Real-time industrial Ethernet protocols synchronize servo drives, controllers, and sensors through distributed clock mechanisms. Automotive assembly lines in Germany and the United States adopt these architectures fastest for synchronized multi-axis positioning. The technology compresses hardware differentiation and shifts margin capture toward software-defined motion profiles.
- Digital Control:Microprocessor-based architectures replace analog signal processing with algorithmic trajectory optimization. China's GB standards evolution for industrial automation equipment creates certification uncertainty for multinational suppliers deploying digital platforms. Machine builders in the Yangtze River Delta demand complete motion subsystems with pre-validated digital control stacks.
- Analog Control:Legacy voltage-based positioning systems persist in brownfield facilities with extended replacement cycles.
- Programmable Logic:PLC-based motion modules serve retrofit markets where analog controller obsolescence delays full digital migration.
Programmable logic holds the largest share; EtherCAT gains share fastest as fieldbus abandonment accelerates.
Application:
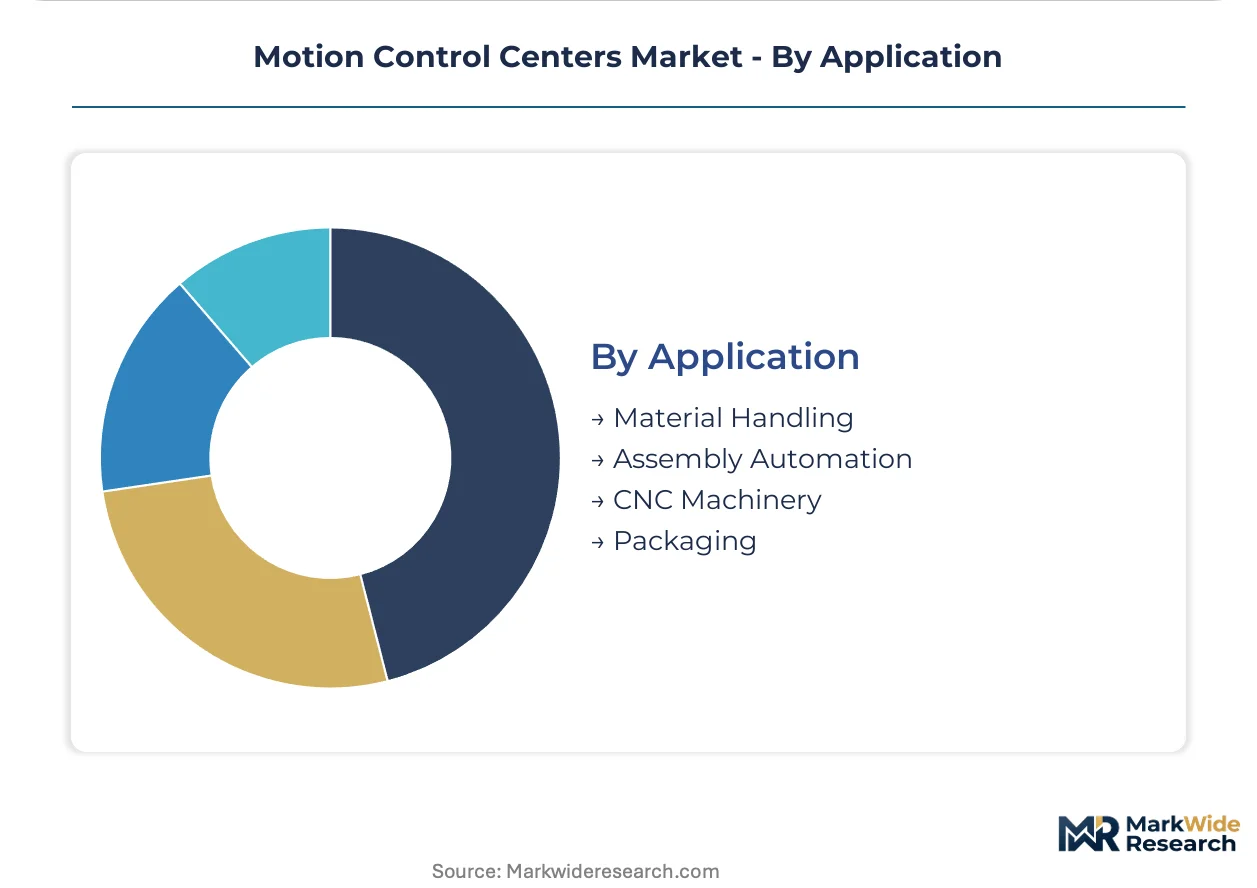
Customer type segmentation separates OEM system integrators from end-user facilities with captive engineering teams. CNC machinery and assembly automation demand deep application engineering, while packaging and material handling standardize around configurable platform solutions.
- CNC Machinery:High-precision cutting and grinding operations require coordinated multi-axis positioning with nanometer-level repeatability. ABB anchors market presence through deep specialization in this segment across European aerospace and automotive toolrooms. REACH substance restrictions force thermal interface material requalification that extends certification timelines.
- Assembly Automation:Robotic welding, fastening, and inspection systems coordinate servo torque with predictive trajectory algorithms. Siemens leverages in-house servo drive production to control component availability for German automotive tier-one suppliers. Direct technical sales channels displace distributor networks as buyers prioritize application engineering.
- Material Handling:Conveyor and gantry systems coordinate velocity and positioning across warehouse and factory floor environments.
- Packaging:Form-fill-seal and cartoning machinery synchronize multi-axis motion for high-throughput consumer goods production.
Material handling holds the largest share; CNC machinery shows steepest expansion trajectory as precision requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Japanese automation clusters where IEC 61508 certification scarcity commands premium positioning. Chinese machine builders in the Yangtze River Delta extract volume discounts through consolidated subsystem procurement.
Germany
Automotive assembly lines in Bavaria and Baden-Württemberg drive demand for SIL-rated multi-axis platforms. The EU Machinery Directive and REACH substance restrictions tighten compliance burdens for power electronics suppliers. Stuttgart's precision engineering cluster anchors European servo drive development.
Japan
Robotics OEMs in the Nagoya and Osaka industrial corridors require nanometer-level positioning systems for collaborative robot arms. METI industrial automation guidelines shape domestic certification frameworks. The Kanto region around Tokyo concentrates FANUC and Yaskawa manufacturing facilities.
United States
EPA energy efficiency guidelines and OSHA electrical safety standards reshape procurement specifications for North American automotive tier-one suppliers. The Midwest manufacturing belt spanning Michigan and Ohio absorbs integrated servo-controller architectures for welding automation.
China
MIIT GB standards evolution for industrial automation equipment creates certification uncertainty for multinational suppliers. The Yangtze River Delta manufacturing corridor from Shanghai to Suzhou sources complete motion subsystems through direct technical channels.
South Korea
Display panel and semiconductor equipment manufacturers in the Seoul Capital Area demand sub-micron precision for lithography positioning systems. MFDS and national industrial safety frameworks govern multi-axis control platform deployments. Busan-Ulsan heavy industry clusters adopt EtherCAT-enabled digital architectures.
Motion Control Centers Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in servo drive and controller manufacturing. The vendor base separates into three tiers: diversified electrical conglomerates with captive motion divisions, pure-play automation specialists, and regional system integrators. European and Japanese players dominate functional safety certification. Competitive moves concentrate on backward integration into power electronics and strategic partnerships for predictive maintenance software.
Among diversified electrical conglomerates, Siemens and ABB occupy positions as archetypal platform integrators leveraging in-house servo drive production. Rockwell Automation exemplifies the North American automation specialist tier with programmable logic dominance. These three represent distinct geographic anchoring strategies—German vertical integration, Swiss-Swedish precision specialization, and US software-defined control architectures.
| Leading Market Players |
|---|
| Siemens |
| ABB |
| Schneider Electric |
| Mitsubishi Electric |
| Rockwell Automation |
| FANUC Corporation |
| Yaskawa Electric Corporation |
| Omron Corporation |
| Eaton |
| Others |
Supply & Pricing Matrix
Undercapacity in European servo drive foundries is compressing lead times and hardening supplier pricing power, while Yangtze River Delta buyers exploit volume consolidation to extract configured-to-order discounts from multinational vendors.
Pricing Analysis
Configured-to-order pricing for SIL-certified multi-axis platforms commands substantial premiums over standard EtherCAT controller configurations. Pricing stratifies across safety integrity levels, with IEC 61508 certification tiers separating automotive robotics deployments from general material handling installations. Cost compression in analog controller retrofits is intensifying as brownfield buyers defer digital migration. Chinese machine builders exhibit highest price sensitivity, while German automotive tier-one suppliers absorb premium positioning for validated safety architectures.
Supply Chain Analysis
Upstream power electronics feedstock draws from Taiwan semiconductor foundries, German precision component manufacturers, and Japanese thermal management material suppliers. IGBT modules, rare-earth magnets, and high-grade aluminum heat sinks anchor bill-of-materials volatility. Single-source vulnerability concentrates in silicon carbide substrate supply for next-generation servo drives. Distribution runs through direct technical sales channels that displace traditional distributor networks in heavy manufacturing and robotics sectors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated machine builder clusters in China's Yangtze River Delta, where subsystem procurement volume aggregates across domestic and multinational supplier bases.
For Market Incumbents: Insulate margin positions through captive servo drive production and SIL certification depth. Siemens and ABB already control component availability through in-house manufacturing. Emerging Chinese automation vendors threaten pricing in standard controller segments. Priority lever: deepen technical sales relationships with Yangtze River Delta system integrators to defend against local supplier encroachment. For New Entrants and Emerging Players: Establish a beachhead in programmable logic retrofit markets where analog controller obsolescence delays full EtherCAT migration. Brownfield European facilities with legacy installations present the most penetrable entry point. Go-to-market angle: software-defined motion profiles that compress hardware differentiation and shift margin capture toward recurring firmware validation services. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among servo drive specialists with embedded thermal management service contracts. Long-term viability hinges on functional safety engineering depth and backward integration into power electronics. Acquisition target archetype: European automation specialists with SIL certification concentration. Signal to watch: divergence between China's GB standards and IEC frameworks as fragmentation catalyst.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Power Electronics | Servo drive manufacturers securing IGBT module supply from Taiwan foundries reduce semiconductor input volatility. |
| Functional Safety Certification Investment | SIL-rated platform development opens European automotive and aerospace procurement channels under EU Machinery Directive. |
| Predictive Maintenance Software Partnership | Machine builders in Germany adopt algorithmic trajectory optimization to extend motion subsystem lifecycle value. |
| Direct Technical Sales Channel Expansion | Yangtze River Delta system integrators source complete motion subsystems through supplier-managed engineering relationships. |
| EtherCAT Architecture Migration | Automotive assembly lines in the United States abandon analog fieldbus for real-time industrial Ethernet protocols. |
Research Methodology
The analysis maps servo drive platforms, digital and analog controllers, stepper motors, and electromechanical actuators, each validated through plant engineers, OEM procurement teams, aftermarket service heads, and system integration specialists. Primary interviews with automation vendors and machine builders combined with secondary validation from SEC filings, customs trade data, IEC certification registries, and automotive production databases. Bottom-up unit economics triangulated against top-down sector sizing across product tiers and regional demand clusters.
Assumptions held fixed include regulatory framework stability around IEC 61508 and EU Machinery Directive compliance burdens, while semiconductor input pricing and Chinese GB standards evolution were treated as variable stress conditions. Segmentation dimensions modeled span product type, end-use industry, technology architecture, and application environment. CAGRs derived from installed base replacement cycles and greenfield adoption curves, with servo drive thermal management complexity and EtherCAT penetration rates as motion-specific forecast inputs across the projection horizon.
Stress conditions across semiconductor supply availability, functional safety certification timelines, and China-EU regulatory divergence were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions with acknowledgment that power electronics cost volatility or abrupt standards fragmentation could materially revise trajectory projections. Cross-checking against automotive capital expenditure disclosures and industrial automation order backlogs is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Europe SCADA Market
Industrial Automation
Drilling Automation Market
Industrial Automation
Smart Elevator Market
Industrial Automation
Asia Pacific Sortation Systems Market
Industrial Automation
Sortation Systems Market
Industrial Automation
Smart Sorting Line Market
Industrial Automation
Smart Warehouse Technologies Market
Industrial Automation
Cold Storage AGV Market
Industrial Automation
Europe Warehouse Automation Systems Market
Industrial Automation
Europe Industrial Embedded Systems Market
Industrial Automation
Smart Factory Market
Industrial Automation
Internet of Things Enabled Industrial Wearables Market
Industrial Automation
Global Programmable Logical Controllers Automation Market
Industrial Automation
Global Feeder Automation Market
Industrial Automation
Global Blasting Automation Services Market
Industrial Automation
Linear Motion System Market