
 Supply Chain Analytics Market | 2026-2036
Supply Chain Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Supply Chain Analytics Market Analysis
Modular deployment packaging is broadening buyer choice in supply chain analytics as vendors unbundle monolithic suites into composable microservices. SAP SE leverages its ERP-installed base to anchor cloud analytics subscriptions across manufacturing verticals. IBM Corporation competes through AI-infused demand forecasting modules that integrate with existing warehouse management systems. Oracle Corporation sustains differentiation via database-native optimization engines that reduce data latency for inventory planners.
Supply chain analytics encompasses statistical modeling, machine learning algorithms, and network optimization techniques applied to procurement, logistics, and demand data streams, typically processing terabyte-scale enterprise datasets through ETL pipelines and real-time streaming architectures to reduce operational expenditure and service-level variance. Predictive analytics leads current revenue contribution as manufacturers prioritize demand sensing over historical reporting, while prescriptive analytics represents the fastest-expanding margin pool as optimization engines mature for route and inventory decisions. Cloud-based deployment now dominates new installations, though hybrid configurations retain traction among healthcare end users with segmented data sovereignty requirements.
The EU AI Act imposes algorithmic transparency requirements on automated supply chain decisions, compelling vendors to embed explainability layers into predictive models, while HIPAA constrains how healthcare logistics platforms handle protected inventory data tied to patient services. FDA traceability mandates for pharmaceutical distribution further shape analytics specifications for lot-tracking and cold-chain verification. Stakeholders must weigh compliance architecture costs against the operational flexibility of multi-tenant cloud deployments when selecting platform partners.
Market Dynamics
Cloud migration mandates from the EU AI Act are forcing pharmaceutical and automotive manufacturers to re-architect their analytics stacks, accelerating the shift from on-premise warehouse management systems to compliant multi-tenant platforms with embedded explainability layers.
Growth Catalysts
- EU AI Act algorithmic transparency:Automated supply chain decisions now require explainable predictive models, compelling manufacturers to upgrade legacy forecasting engines and expand vendor relationships with compliant platform providers.
- Pharmaceutical demand forecasting:Manufacturers are deploying advanced modules to reduce inventory carrying costs while maintaining FDA traceability for lot-tracking and cold-chain verification across distribution networks.
- Germany's industrial corridor concentration:Automotive OEMs anchor procurement of prescriptive logistics platforms, creating dense reference customer bases that accelerate adoption across tier-1 and tier-2 supplier networks.
Market Restraints
- Data sovereignty segmentation:Healthcare end users with HIPAA constraints face elevated architecture costs when configuring hybrid cloud deployments that isolate protected inventory data tied to patient services.
- Terabyte-scale ETL pipeline complexity:Real-time streaming architectures require specialized engineering talent that concentrates in Germany, the United States, and India, limiting deployment velocity for mid-market manufacturers elsewhere.
- Microservices integration friction:Unbundled analytics suites demand custom API development to connect with existing warehouse management systems, extending implementation timelines and inflating professional services spend.
Strategic Opportunities
- Prescriptive analytics margin expansion:Optimization engines for route and inventory decisions represent the fastest-expanding revenue pool as vendors mature AI-native capabilities beyond descriptive and predictive modules.
- India's pharmaceutical manufacturing:CDSCO traceability mandates and PLI scheme incentives create a compliant, cost-optimized base for analytics vendors to establish regional delivery centers serving Asia-Pacific markets.
- Digital twin convergence:Integration of statistical modeling with physics-based simulation is electrifying demand sensing accuracy, enabling manufacturers to compress forecast-to-fulfillment cycles in volatile component markets.
Industry Challenges
- Embedded explainability engineering:Vendors must rebuild core predictive algorithms to satisfy EU AI Act documentation requirements, diverting R&D resources from feature development and compressing release cadences.
- Legacy ERP integration complexity:SAP-installed base dominance forces competing analytics platforms to maintain expensive connector libraries, fragmenting development priorities across database-native and middleware-dependent architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Supply Chain Analytics Market |
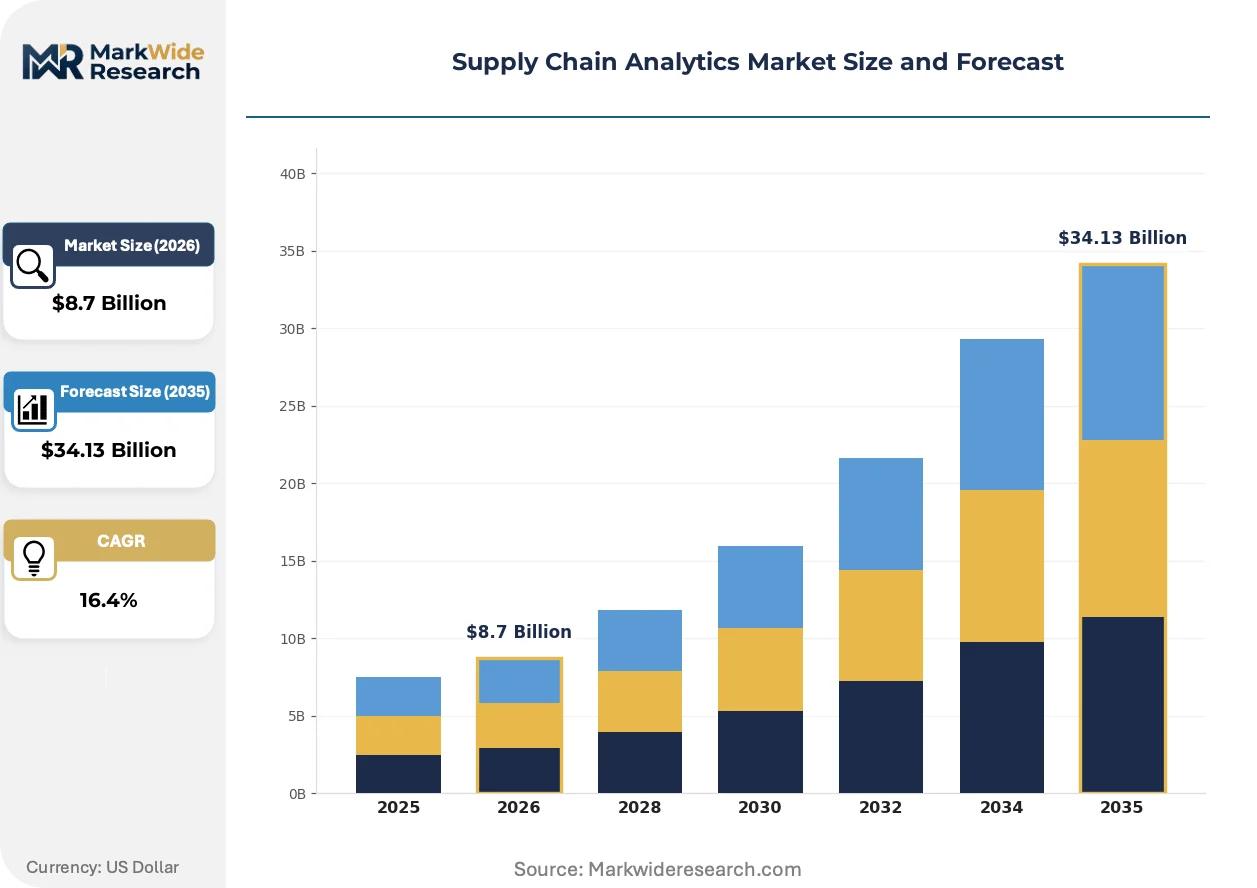
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Descriptive Analytics, Predictive Analytics, Prescriptive Analytics, Diagnostic Analytics Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services End User: Retail, Manufacturing, Transportation, Healthcare Application: Inventory Management, Demand Forecasting, Supplier Performance, Logistics Optimization |
| Companies Covered | SAP SE, Oracle Corporation, IBM Corporation, Accenture PLC, SAS Institute Inc., Capgemini SE, JDA Software Group, Inc., MicroStrategy, Inc., Genpact Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Supply Chain Analytics Market Emerging Trajectories
Real-time streaming architectures and AI-infused optimization engines are compressing decision latency from days to hours, while regulatory mandates reshape competitive positioning around compliance-native platform design rather than pure performance benchmarking.
Digital twin technology is electrifying supply chain planning by fusing statistical demand models with physics-based network simulation. Pharmaceutical manufacturers in Germany and the United States are piloting these converged systems to stress-test cold-chain resilience before physical deployment. The technology is compressing scenario planning cycles and reducing inventory buffers previously held as contingency against disruption.
REACH and the EU AI Act are jointly elevating algorithmic audit requirements for automated procurement decisions. Chemical and automotive manufacturers must now document model training data lineage and bias testing protocols, creating new vendor selection criteria that favor platforms with native compliance tooling. German industrial software providers are capturing early advantage by embedding regulatory documentation workflows directly into user interfaces.
Outcome-based contracting for analytics subscriptions is displacing traditional seat-license models in enterprise procurement. Automotive OEMs in Stuttgart and Munich now negotiate contracts tied to measurable inventory reduction or service-level improvement, transferring performance risk to platform vendors. This shift concentrates vendor relationships around providers willing to underwrite operational guarantees rather than pure technology licensing.
Supply Chain Analytics Market Segmentation
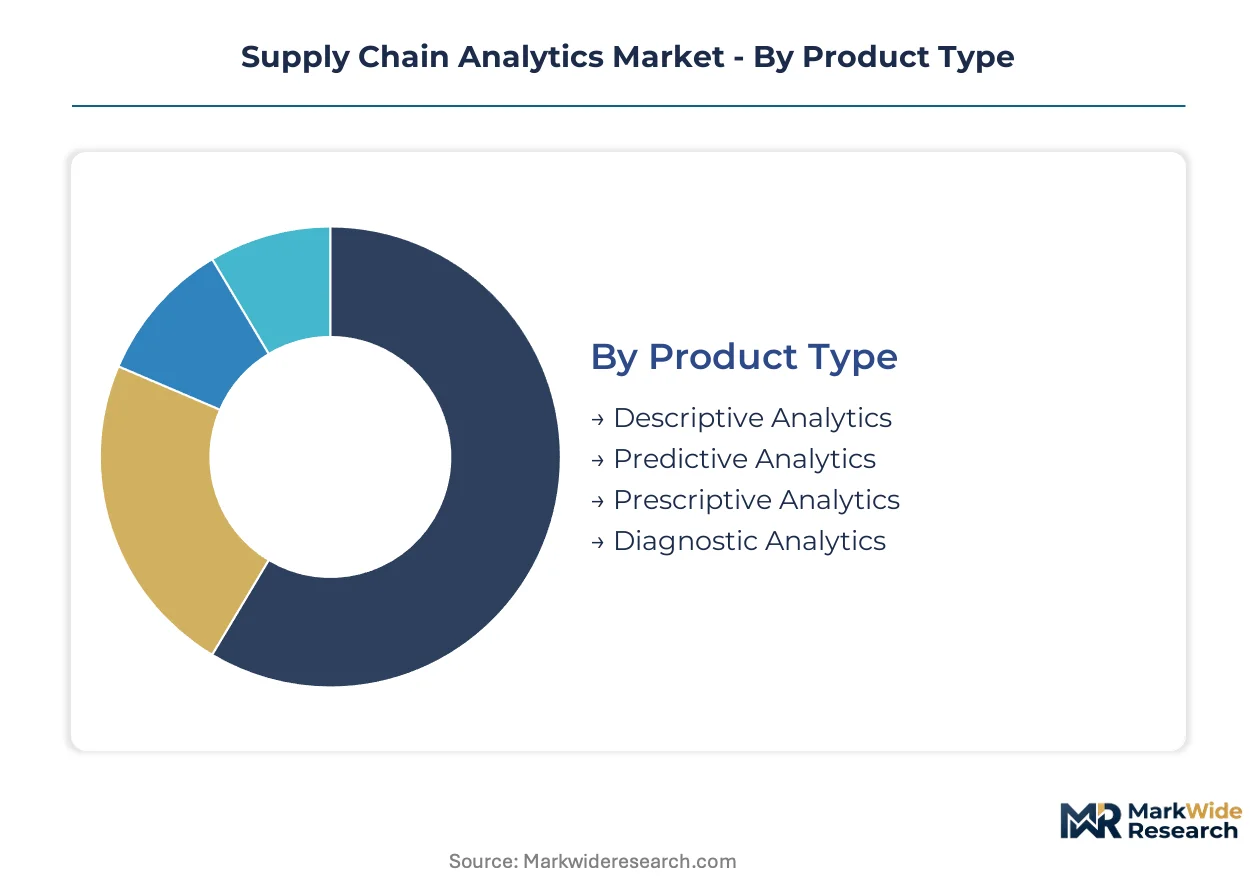
Supply chain analytics buyers navigate four intersecting dimensions when selecting platforms. Procurement committees weigh functional capability against deployment architecture, while end-use constraints and application specificity determine integration complexity and compliance burden.
Product Type:
Budget allocation patterns reveal how maturity curves shape technology selection across manufacturing verticals.
- Predictive Analytics:Machine learning algorithms process historical demand signals and external variables to generate forward-looking forecasts. German automotive OEMs in Stuttgart and Munich anchor procurement volumes as these manufacturers prioritize demand sensing over retrospective reporting for volatile component markets.
- Prescriptive Analytics:Optimization engines apply mathematical programming to recommend specific inventory and routing decisions. Revenue concentration is accelerating fastest here as vendors mature AI-native capabilities that reduce operational expenditure through automated decision support.
- Descriptive Analytics:Visualization dashboards and historical reporting modules remain prevalent in mid-market implementations where IT departments lack specialized data science resources.
- Diagnostic Analytics:Root-cause analysis tools isolate supply chain failures through variance decomposition and anomaly detection algorithms.
Volume sits with Predictive Analytics; growth tilts toward Prescriptive Analytics.
Deployment:
Architecture decisions hinge on data sovereignty requirements and regulatory jurisdiction rather than pure cost optimization.
- Cloud-Based:Multi-tenant platforms with elastic compute resources now dominate new installations across European manufacturing. EU AI Act algorithmic transparency mandates are accelerating migration from legacy on-premise warehouse management systems to compliant architectures with embedded explainability layers.
- Hybrid:Segmented configurations isolate sensitive datasets within private infrastructure while routing anonymized analytics workloads to public cloud resources. Healthcare end users with HIPAA constraints face elevated implementation costs when configuring these deployments for protected inventory data tied to patient services.
- On-Premises:Single-tenant installations persist in defense and classified industrial applications where air-gapped networks are mandatory.
- Managed Services:Outsourced platform operations appeal to mid-market manufacturers lacking specialized engineering talent for terabyte-scale ETL pipeline maintenance.
Adoption concentrates in Cloud-Based configurations; compliance complexity sustains Hybrid demand.
End User:
Industry-specific regulatory frameworks reshape platform specifications and vendor selection criteria.
- Manufacturing:Discrete and process manufacturers deploy end-to-end visibility platforms spanning procurement through distribution. German industrial corridor concentration creates dense reference customer bases that accelerate adoption across tier-1 and tier-2 automotive supplier networks.
- Healthcare:Hospital systems and pharmaceutical distributors require lot-tracking capabilities and cold-chain verification modules. FDA traceability mandates for pharmaceutical distribution shape analytics specifications, constraining how platforms handle serialized inventory data.
- Retail:Omnichannel merchants prioritize demand forecasting accuracy across e-commerce and physical store networks.
- Transportation:Third-party logistics providers optimize fleet routing and carrier selection through network optimization engines.
Procurement scale favors Manufacturing; regulatory tailwinds strengthen Healthcare.
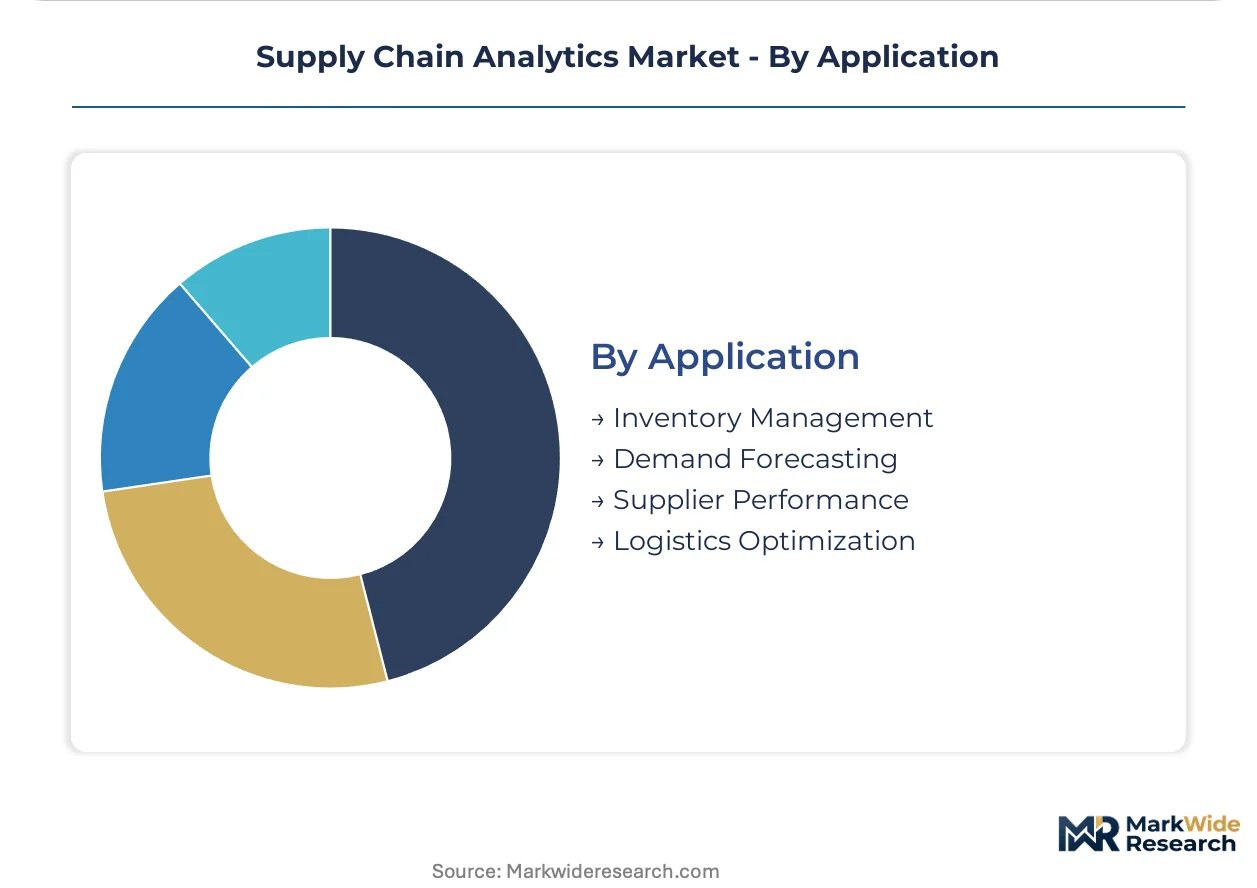
Application:
Functional priority sequencing determines implementation roadmap phasing and change management intensity.
- Demand Forecasting:Statistical modeling and machine learning modules reduce inventory carrying costs while maintaining service levels. Pharmaceutical manufacturers are expanding adoption most aggressively as they balance working capital efficiency against stockout risks for critical therapies.
- Inventory Management:Multi-echelon optimization and safety stock positioning tools compress working capital requirements. Real-time streaming architectures enable planners to respond within hours rather than days to demand shocks.
- Logistics Optimization:Route planning and mode selection algorithms reduce freight expenditure through network modeling.
- Supplier Performance:Scorecarding and risk monitoring platforms track delivery reliability, quality metrics, and financial health indicators.
Investment prioritization clusters on Demand Forecasting; operational impact concentrates in Inventory Management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Germany's industrial corridor while consumption spreads across pharmaceutical hubs in the United States and India. Cloud migration mandates from the EU AI Act are reshaping vendor relationships in Europe, whereas FDA traceability requirements drive specification changes in North American healthcare logistics.
Germany
Automotive OEMs in Stuttgart and Munich anchor procurement of prescriptive logistics platforms, creating dense reference customer bases across tier-1 supplier networks. The EU AI Act imposes algorithmic transparency requirements on automated supply chain decisions, compelling manufacturers to embed explainability layers into predictive models. Baden-Württemberg's manufacturing belt hosts concentrated pilot programs for digital twin convergence in volatile component markets.
United States
Pharmaceutical manufacturers expand adoption of demand forecasting modules to reduce inventory carrying costs while maintaining FDA traceability for lot-tracking and cold-chain verification. HIPAA constrains how healthcare logistics platforms handle protected inventory data tied to patient services, elevating architecture costs for hybrid cloud configurations. The Boston-Cambridge biotech corridor drives specification requirements for serialized inventory analytics.
India
CDSCO traceability mandates and PLI scheme incentives create a compliant, cost-optimized base for analytics vendors to establish regional delivery centers serving Asia-Pacific markets. The country's pharmaceutical manufacturing sector is expanding deployment of advanced forecasting modules to balance working capital efficiency against stockout risks. Maharashtra and Gujarat host concentrated implementation of terabyte-scale ETL pipelines for generic drug distribution networks.
United Kingdom
Post-Brexit regulatory divergence is forcing pharmaceutical distributors to maintain dual compliance architectures for EU and UK markets, inflating platform configuration costs. The Medicines and Healthcare products Regulatory Agency is aligning with FDA traceability standards for pharmaceutical distribution. London's financial services sector is piloting outcome-based contracting models for analytics subscriptions tied to measurable inventory reduction.
China
NMPA traceability mandates for pharmaceutical distribution are accelerating adoption of lot-tracking analytics platforms across domestic supply chains. Dual carbon goals are pressuring manufacturers to optimize route planning and freight mode selection through network optimization engines. The Yangtze River Delta hosts concentrated deployment of real-time streaming architectures for electronics component procurement.
Supply Chain Analytics Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across deployment architecture and functional module categories. Enterprise software incumbents leverage ERP-installed bases to anchor cloud analytics subscriptions, while consulting-led integrators bundle implementation services with platform licensing. Three strategic archetypes dominate: database-native optimization engine providers, AI-infused demand forecasting specialists, and outcome-based contracting pioneers. Competitive intensity concentrates on M&A activity targeting microservices capabilities and strategic partnerships bridging legacy warehouse management integration gaps.
Within the enterprise software tier, SAP SE exemplifies the ERP-anchored diversification archetype, while Oracle Corporation occupies a position emphasizing database-native performance. IBM Corporation represents the AI-infused forecasting specialist model, competing through modular integration with existing infrastructure. These three entities anchor vendor selection committees for large-scale manufacturing implementations across Germany, the United States, and India.
| Leading Market Players |
|---|
| SAP SE |
| Oracle Corporation |
| IBM Corporation |
| Accenture PLC |
| SAS Institute Inc. |
| Capgemini SE |
| JDA Software Group, Inc. |
| MicroStrategy, Inc. |
| Genpact Limited |
| Others |
Supply Flow & Price Mechanics
Automotive OEM procurement committees in Germany's industrial corridor anchor demand for prescriptive logistics platforms, concentrating buyer power and compressing vendor margins through outcome-based contracting tied to measurable inventory reduction. This buyer concentration elevates pricing leverage for tier-1 manufacturers while forcing mid-market vendors toward SaaS-tiered subscription models to compete.
Pricing Analysis
Margin tightening in cloud-native analytics tiers reflects EU AI Act compliance engineering costs that vendors must absorb or pass through. Three-tier pricing structure across premium, standard, and economy levels segments by explainability depth and audit documentation bundled. Certification tier differentiation separates FDA-validated pharmaceutical modules from general manufacturing forecasting tools. Mid-market manufacturers exhibit highest price sensitivity, deferring upgrades until compliance deadlines force procurement. Enterprise automotive buyers leverage reference customer density to negotiate performance-guarantee clauses that transfer operational risk.
Supply Chain Analysis
Refurbishment flows for legacy on-premise warehouse management systems create secondary markets as European manufacturers migrate to compliant cloud architectures. Engineering talent concentrates in Germany, the United States, and India, anchoring professional services delivery and ETL pipeline development. Platform development draws from open-source machine learning frameworks and hyperscaler compute infrastructure. Single-source vulnerability concentrates in explainability-layer engineering expertise required for EU AI Act documentation. Distribution runs through direct enterprise sales teams augmented by systems integrators specializing in SAP connector libraries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The supply chain analytics market operates as a vertical-integration race where control over database-native optimization engines determines pricing power and customer retention. Incumbents and challengers alike pursue downstream integration into managed services to capture recurring revenue.
For Market Incumbents: Anticipate margin compression from outcome-based contracting by embedding performance guarantees into standard terms before competitors establish precedent. Fortify SAP connector libraries against API fragmentation as microservices unbundling accelerates integration complexity. Prioritize backward integration into real-time streaming infrastructure to reduce dependency on hyperscaler compute pricing.
For New Entrants and Emerging Players: Systems integrators with healthcare compliance expertise represent the most penetrable channel for bypassing incumbent ERP-anchored relationships. Target hybrid cloud configurations for HIPAA-constrained hospital systems where elevated architecture costs deter pure-play cloud vendors. Lead with FDA traceability modules that incumbent suites bolt on as aftermarket additions.
For Investors and Strategic Acquirers: Distressed-cycle entries favor AI-native forecasting specialists with established automotive reference customers in Germany's industrial corridor. Long-term viability hinges on prescriptive analytics margin expansion as optimization engines mature beyond descriptive and predictive modules. Watch CDSCO traceability mandate enforcement in India as inflection signal for Asia-Pacific delivery center valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | ERP-native analytics subscriptions reduce churn by embedding into SAP-installed manufacturing bases. |
| Acquisition of Specialist Firm | Explainability-layer engineering targets satisfy EU AI Act documentation requirements without diverting R&D. |
| Geographic Expansion | India delivery centers leverage PLI scheme incentives to serve CDSCO-compliant pharmaceutical manufacturers. |
| Strategic Partnership | Systems integrator alliances bridge legacy warehouse management integration gaps for mid-market manufacturers. |
| Product Launch | Digital twin convergence modules compress forecast-to-fulfillment cycles for volatile automotive component markets. |
Methodological Framework
Independent corroboration across supply chain software vendors, automotive procurement executives, and pharmaceutical logistics directors underwrites the qualitative findings. Primary fieldwork encompassed CTOs at German industrial OEMs, IT procurement officers evaluating EU AI Act compliance, platform engineers building explainability layers, and integration specialists maintaining SAP connector libraries. Secondary validation drew from FDA 483 inspection observations, EMA guidance documents on algorithmic transparency, customs records of analytics software imports, and SEC 10-K disclosures from enterprise software providers. Bottom-up deployment counts triangulate against top-down IT spending surveys across manufacturing verticals.
Rate-of-change decomposition separates volume expansion from pricing mix shifts across the projection horizon. Segmentation dimensions modeled include functional module type, deployment architecture, end-use vertical, and regional regulatory cluster. CAGRs derive from logistic curve fitting of technology adoption patterns calibrated against historical ERP migration timelines. Forecast inputs incorporate EU AI Act implementation phase deadlines and FDA traceability mandate enforcement schedules without assigning specific calendar dates.
Caveats apply where EU AI Act interpretive guidance revisions or CDSCO traceability deadline extensions could materially shift the outlook. Forecasts reflect assumptions about cloud migration velocity and professional services talent availability that warrant monitoring. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Data Visualization Market
Analytics
Mobile Analytics Market
Analytics
Europe Data Monetization Market
Analytics
Global Data Analysis Software Market
Analytics
Event Stream Processing Market
Analytics
United States Geospatial Analytics Market
Analytics
Europe Speech Analytics Market
Analytics
UK Video Analytics Market
Analytics
Germany Geospatial Analytics Market
Analytics
Identity Analytics Market
Analytics
Embedded Analytics Software Market
Analytics
Enterprise Drone Analytics Software Market
Analytics
RAN Analytics and Monitoring Market
Analytics
Global Customer Analytics Market
Analytics
Global Customer Experience Analytics Market
Analytics
Europe Operational Intelligence Market