
 Data Analysis Tools Market | 2026-2036
Data Analysis Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Data Analysis Tools Market Outlook
The gap between raw data infrastructure and consumable business intelligence is narrowing as organizations demand embedded analytics inside operational workflows. Microsoft Power BI leverages its Office ecosystem to dominate desktop-to-cloud transitions. Databricks sustains momentum through unified lakehouse architecture that collapses storage and compute silos. Alteryx specializes in self-service data preparation for line-of-business analysts without coding expertise.
Data analysis tools encompass software platforms that ingest, transform, model, and visualize structured and semi-structured data through statistical methods, query engines, and interactive dashboards operating on datasets from gigabytes to petabytes in scale. These tools serve the industrial purpose of converting operational records into decision-ready intelligence across finance, supply chain, and customer-facing functions. Visualization tools capture premium attention as executives prioritize narrative-driven reporting over tabular exports. Cloud-based deployments absorb the fastest growth as IT departments retire on-premises server farms and redirect capital toward elastic consumption models.
The EU AI Act imposes risk-tiered compliance obligations on analytics platforms generating automated credit and health assessments, while the FDA scrutinizes clinical decision support algorithms for diagnostic safety. HIPAA continues to constrain how US healthcare entities share patient data across cloud analytics environments. Stakeholders must weigh regulatory fragmentation against the operational efficiency of unified global platforms.
Market Dynamics
Cloud-native lakehouse architectures are collapsing the traditional separation between data warehouses and data lakes, forcing vendors to unify storage and compute layers or lose enterprise contracts to integrated platforms.
Growth Catalysts
- EU AI Act compliance mandates:European healthcare and financial institutions must document algorithmic decision trails, creating procurement pull for auditable analytics platforms with built-in governance modules.
- Healthcare predictive modeling:US hospital systems deploy patient outcome forecasting tools to reduce readmission penalties and optimize resource allocation across emergency departments.
- India's data localization requirements:The RBI and MeitY push for in-country data processing, driving domestic cloud analytics infrastructure investment from multinational software providers.
Market Restraints
- Specialized talent scarcity:Organizations face 8-14 month hiring cycles for data engineers fluent in both SQL optimization and Python-based machine learning pipelines.
- Cross-border data friction:GDPR adequacy decisions and Schrems II rulings complicate analytics workloads spanning European and US cloud regions.
- GPU compute cost volatility:Training-intensive AI workloads expose enterprises to spot-price swings in cloud accelerator instances.
Strategic Opportunities
- Germany's Mittelstand analytics gap:Mid-sized manufacturers lack dedicated data science teams, creating demand for no-code predictive maintenance tools.
- Edge-to-cloud federated analytics:Converging 5G low-latency networks with containerized query engines enables real-time shop-floor dashboards without central data movement.
- India's PLI scheme for IT hardware:Domestic server and storage manufacturing incentives reduce landed costs for on-premises analytics appliances.
Industry Challenges
- Legacy ERP integration complexity:SAP and Oracle systems running on decade-old schemas require expensive custom connectors for modern BI extraction.
- Model explainability certification delays:FDA 510(k) pathways for clinical decision support algorithms extend development timelines by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Analysis Tools Market |
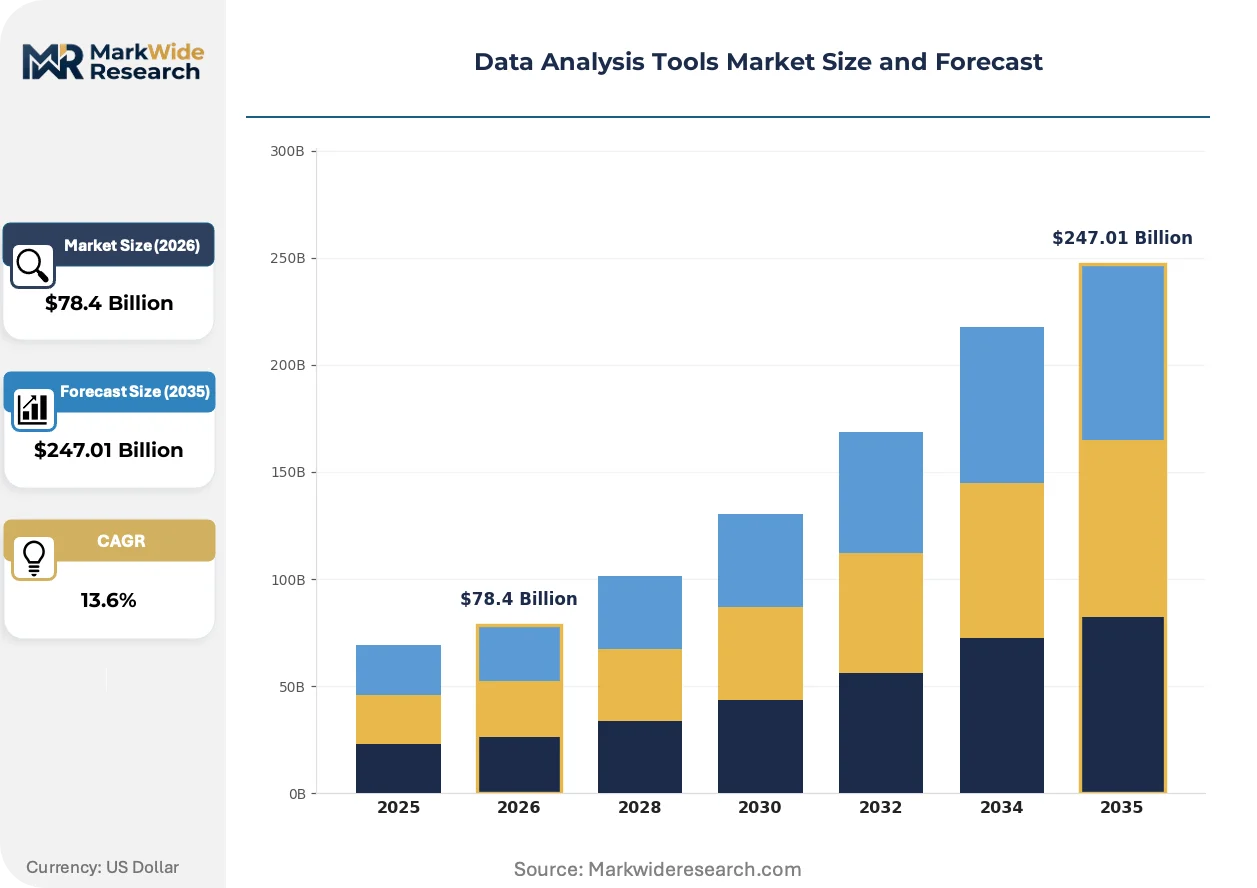
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $247.01 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Tool Type: Statistical Software, Visualization Tools, Spreadsheet Software, ETL Tools Deployment Model: On-Premises, Cloud-Based, Hybrid, Open Source End User: Enterprises, Small Businesses, Academic Institutions, Government Agencies Industry Vertical: Finance, Healthcare, Retail, Telecommunications |
| Companies Covered | Tableau, Microsoft Power BI, Qlik, SAS, Alteryx, Databricks, Sisense, TIBCO Spotfire, KNIME, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Analysis Tools Market Strategic Shifts
Natural language interfaces and automated feature engineering are compressing the distance between business questions and analytical answers, eliminating traditional bottlenecks in report generation.
Generative AI copilots embedded in query builders are digitizing the translation layer between executive intent and SQL logic. Fortune 500 analytics teams deploy these tools to reduce dashboard turnaround from weeks to hours. The technology is digitizing requirements-gathering processes that previously consumed 40% of BI project timelines.
The EU AI Act's risk classification framework imposes documentation burdens on high-stakes predictive models in credit and health domains. Vendors must now maintain technical files, conformity assessments, and human oversight protocols for automated decision systems. German automotive suppliers and French insurance groups are front-loading compliance costs ahead of 2026 enforcement deadlines.
Self-service procurement of analytics seats is displacing centralized IT provisioning as departmental budgets absorb SaaS subscription costs directly. Line-of-business leaders in US retail and healthcare bypass traditional vendor management offices to pilot tools on corporate credit cards. This pattern concentrates most visibly in mid-market enterprises with flat IT hierarchies and distributed profit-center accountability.
Data Analysis Tools Market Segmentation
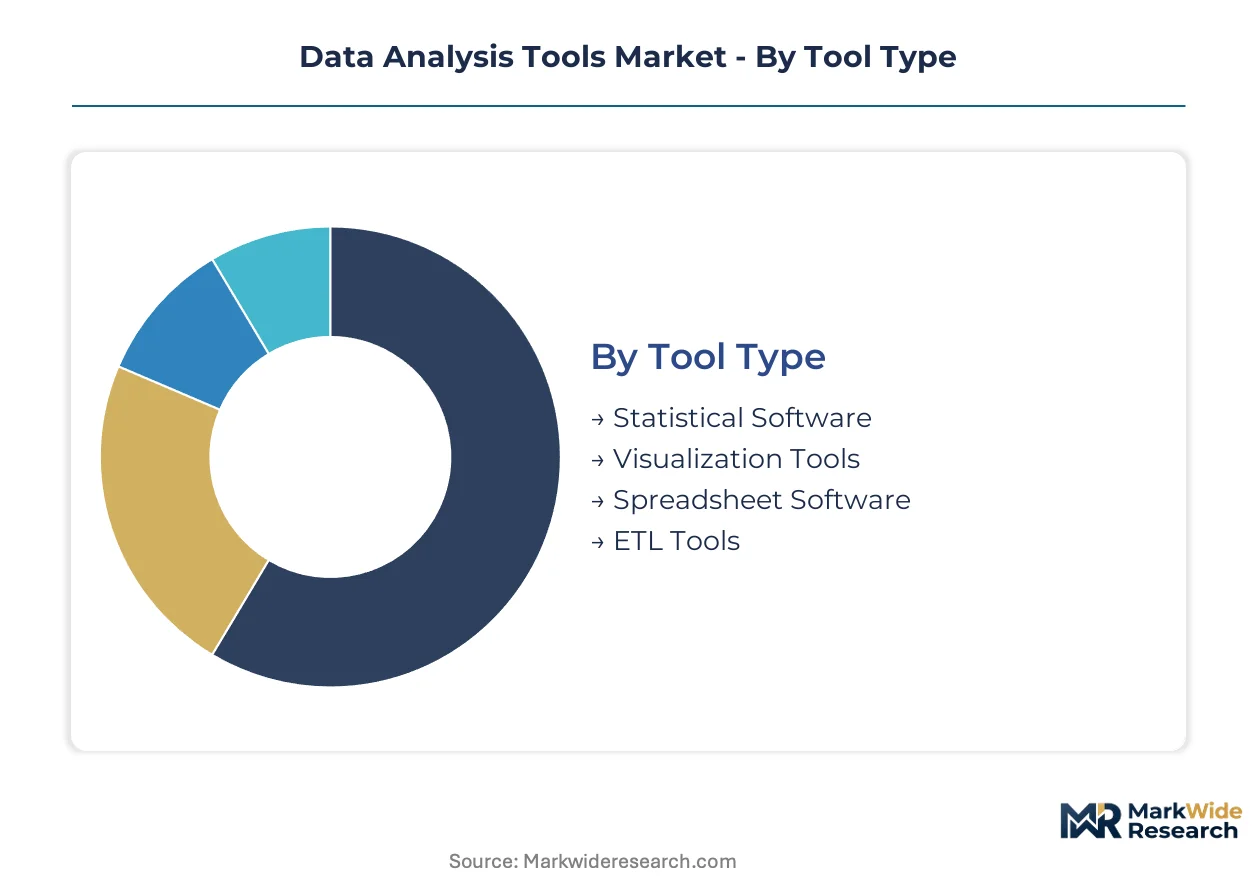
Data analysis tools fragment across technical architectures, procurement models, and organizational maturity levels. Understanding these divisions exposes where vendor R&D concentrates and where pricing power accumulates.
Tool Type:
Use cases span exploratory research through production-grade pipeline engineering, with each tool category serving distinct analytical workflows and user skill profiles.
- Statistical Software:Platforms execute hypothesis testing, regression modeling, and multivariate analysis on structured datasets. Demand concentrates in US pharmaceutical firms and German automotive R&D centers where FDA and KBA documentation requirements mandate reproducible analytical workflows.
- Visualization Tools:Interactive dashboards transform tabular outputs into narrative-driven executive presentations. US retail headquarters and Indian IT services firms deploy these most aggressively as storytelling replaces static reporting in client deliverables.
- Spreadsheet Software:Grid-based calculation environments persist as the universal entry point for business analysts. Small and mid-sized enterprises across Germany's Mittelstand rely on these for financial modeling without dedicated data science staffing.
- ETL Tools:Pipeline orchestration software extracts, transforms, and loads data across heterogeneous source systems. Cloud migration projects in India's banking sector drive procurement as RBI data localization rules require onshore data movement infrastructure.
Established volume favors spreadsheet software; emerging adoption favors visualization tools.
Deployment Model:
Cost structures and compliance obligations diverge sharply between capital-intensive on-premises ownership and operational expenditure cloud models.
- Cloud-Based:Elastic compute and storage consumption eliminates hardware procurement cycles. US healthcare systems accelerate migration as HIPAA business associate agreements mature with hyperscale providers.
- Hybrid:Workload splitting retains sensitive data on-premises while bursting analytics to cloud. German manufacturers favor this architecture under EU AI Act documentation requirements that mandate on-premise audit trails for high-risk automated decisions.
- On-Premises:Dedicated infrastructure serves organizations with strict data sovereignty or latency constraints. Indian public sector banks maintain these deployments per MeitY guidelines for critical financial infrastructure.
- Open Source:Community-developed frameworks reduce licensing costs for technically sophisticated users. Academic institutions across the United States and Europe deploy these for research reproducibility without vendor lock-in.
Procurement momentum concentrates in cloud-based deployments; regulatory complexity sustains hybrid architectures.
End User:
Organizational scale determines feature requirements, with procurement authority shifting between centralized IT and distributed business units.
- Enterprises:Global 2000 corporations demand governance, security certification, and enterprise support tiers. Multi-year contracts with US and German technology vendors dominate procurement.
- Small Businesses:Credit-card procurement of SaaS seats bypasses traditional vendor management. US and Indian mid-market firms pilot tools through departmental budgets before enterprise rollout.
- Academic Institutions:Research universities prioritize statistical rigor and reproducibility over commercial support. Grant-funded purchases in the United States and Europe favor open-source extensibility.
- Government Agencies:Public sector procurement emphasizes security certification and domestic data residency. Indian and US federal deployments face distinct compliance frameworks under MeitY and FedRAMP respectively.
Revenue concentration sits with enterprises; seat expansion rates favor small businesses.
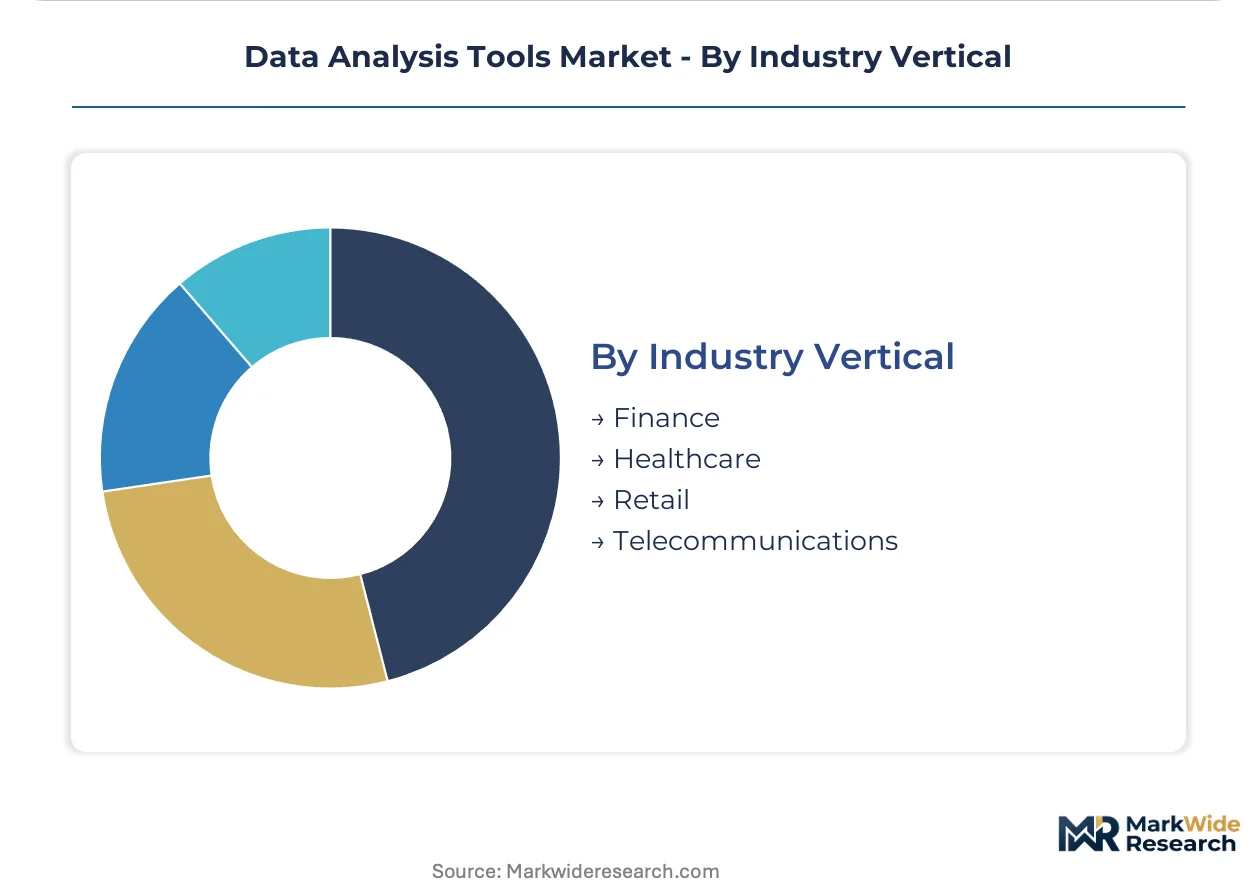
Industry Vertical:
Domain-specific regulatory and operational requirements shape feature roadmaps across vendor portfolios.
- Healthcare:Clinical decision support and patient outcome modeling drive demand. US hospital systems deploy these tools under FDA scrutiny for diagnostic algorithm safety and HIPAA constraints on cloud data sharing.
- Finance:Risk modeling, fraud detection, and algorithmic trading generate computational intensity. EU AI Act compliance for credit decisions forces documentation investments across German and French banking groups.
- Retail:Customer segmentation and supply chain optimization dominate use cases. US and Indian omnichannel retailers prioritize real-time inventory analytics across distributed store networks.
- Telecommunications:Network optimization and churn prediction consume streaming datasets. Indian operators leverage these tools under TRAI quality-of-service monitoring mandates.
Healthcare commands premium pricing; telecommunications shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Healthcare systems and financial institutions drive analytics procurement across concentrated demand centers, with regulatory frameworks in each jurisdiction reshaping deployment architectures and vendor selection criteria.
United States
Hospital networks and pharmaceutical manufacturers deploy patient outcome modeling tools to reduce readmission penalties and accelerate clinical trial analysis. FDA scrutiny of diagnostic algorithms under 510(k) pathways extends validation timelines for clinical decision support systems. The Boston-Cambridge biotech corridor concentrates predictive analytics R&D for drug discovery pipelines.
Germany
Automotive suppliers and Mittelstand manufacturers seek no-code predictive maintenance platforms to compensate for limited in-house data science staffing. KBA documentation requirements and EU AI Act risk-tiered obligations mandate auditable algorithmic decision trails for automated quality assessments. The Stuttgart industrial cluster integrates real-time shop-floor analytics with legacy ERP systems.
India
RBI data localization rules and MeitY guidelines push multinational software providers to establish domestic cloud infrastructure for banking and public sector analytics. The PLI scheme for IT hardware reduces landed costs for on-premises analytics appliances in critical financial infrastructure. Mumbai and Bangalore host concentrated deployment of ETL tools for cross-border payment monitoring.
United Kingdom
Financial services firms in London deploy risk modeling platforms under FCA and Prudential Regulation Authority oversight for algorithmic trading and credit assessment documentation. Open banking mandates accelerate API-based analytics integration across retail banking networks. The Canary Wharf fintech cluster drives procurement of real-time fraud detection systems.
France
Insurance groups and healthcare providers front-load EU AI Act compliance investments ahead of enforcement deadlines for high-stakes automated decision systems. CNIL guidance on automated processing constrains cross-border data flows for multinational analytics workloads. The Paris-Saclay research cluster anchors academic-industry partnerships for reproducible statistical software development.
Data Analysis Tools Market Competitive Environment
Channel-controlling players compete with product-specialist players across a consolidated landscape where ecosystem integration determines procurement outcomes. Microsoft leverages Office ecosystem dominance to capture desktop-to-cloud transitions, while Databricks sustains momentum through unified lakehouse architectures that collapse storage and compute silos. Strategic archetypes include platform consolidators, vertical specialists, and open-source commercializers. Competitive moves concentrate on strategic partnerships with cloud hyperscalers and portfolio diversification into adjacent AI governance modules.
Within the platform consolidator tier, Microsoft and Databricks occupy positions that exemplify divergent approaches to ecosystem capture. Tableau represents the visualization-specialist archetype that defined the self-service analytics category. Alteryx sits within the data preparation segment, serving line-of-business analysts without coding expertise. These three anchors demonstrate how vendor selection increasingly follows workflow integration requirements rather than standalone feature evaluation.
| Leading Market Players |
|---|
| Tableau |
| Microsoft Power BI |
| Qlik |
| SAS |
| Alteryx |
| Databricks |
| Sisense |
| TIBCO Spotfire |
| KNIME |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in US hyperscale cloud regions is compressing utilization rates below 65%, forcing infrastructure providers to bundle compute credits with analytics platform licenses and shifting pricing power toward enterprise procurement teams negotiating multi-year SaaS commitments.
Pricing Analysis
Cost-plus contracts with consumer price indexation dominate enterprise procurement of cloud analytics infrastructure, though seat-based SaaS subscriptions capture mid-market volume. Three-tier pricing structure across premium governance, standard self-service, and economy embedded-analytics levels differentiates by compliance certification depth and support response SLAs. Cost compression in the economy tier is intensifying because open-source alternatives erode per-seat pricing floors. Small businesses exhibit highest price sensitivity, while regulated healthcare and finance verticals absorb premium tiers without material negotiation leverage.
Supply Chain Analysis
Upstream feedstock for analytics platforms centers on GPU accelerator supply from Taiwan, memory modules from South Korea, and specialized ASIC design from the United States. Cloud infrastructure providers draw from concentrated semiconductor fabrication in Taiwan and South Korea, with final assembly of on-premises appliances distributed across Mexico and Malaysia. Single-source vulnerability in advanced node GPU supply creates procurement risk for training-intensive AI workloads. Distribution runs through direct hyperscaler marketplaces, systems integrator channel partners, and OEM embedded licensing agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where switching costs lock enterprises into embedded workflow integrations, with regulatory entrenchment via EU AI Act compliance documentation further cementing incumbent positions.
For Market Incumbents: Pre-empt displacement by open-source lakehouse alternatives through backward integration into specialized query acceleration hardware and exclusive certification partnerships with FDA and EMA for clinical decision support pathways. Channel control over systems integrator training programs represents the critical lever for entrenching enterprise relationships against emerging platform challengers. For New Entrants and Emerging Players: Germany's Mittelstand manufacturing segment with under-500-employee scale and minimal in-house data science staffing represents the most penetrable entry point for no-code predictive maintenance tools. India's domestic cloud infrastructure requirements under RBI data localization rules create white-space for localized ETL and governance modules. Go-to-market through vertical-specific reseller partnerships with industrial automation distributors bypasses direct enterprise sales cycle disadvantages. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity play because compliance documentation burdens for high-risk automated decision systems under EU AI Act and FDA 510(k) pathways create durable competitive barriers that favor established platform vendors with dedicated regulatory affairs infrastructure. Acquisition targets should display vertical-specific workflow integration depth rather than horizontal feature breadth. The signal to watch is enforcement action timing under EU AI Act risk-tiered obligations as a demand inflection catalyst.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedded analytics within Microsoft Office and Salesforce workflows captures procurement decisions before standalone evaluation. |
| Regulatory Certification Investment | EU AI Act conformity assessment pre-clearance and FDA 510(k) pathway completion lock out unqualified competitors in healthcare and finance. |
| Geographic Expansion | Domestic cloud infrastructure deployment in India under RBI localization rules secures public sector banking procurement eligibility. |
| Strategic Partnership | Hyperscaler marketplace listings and co-sell agreements with AWS, Azure, and GCP accelerate enterprise procurement velocity. |
| Acquisition of Specialist Firm | Vertical-specific no-code tool vendors in predictive maintenance and clinical decision support fill portfolio gaps without organic development timelines. |
Study Parameters
Desk research of SEC 10-K filings, hyperscaler capex disclosures, and EU regulatory guidance documents preceded structured interviews with chief data officers, IT procurement officers, platform engineers, and channel partners across the United States, Germany, and India. Primary intelligence on deployment architecture preferences and vendor selection criteria was validated against secondary data from hospital procurement databases, banking technology spend surveys, and manufacturing automation investment trackers. Bottom-up seat-count estimates and top-down addressable market sizing were triangulated to constrain forecast variance.
Assumptions regarding cloud migration velocity, regulatory enforcement timelines, and GPU supply availability were held fixed across baseline scenarios while sensitivity testing varied enterprise IT budget growth and open-source adoption rates. Segmentation modeling incorporated deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern dimensions. CAGRs were derived from logistic diffusion curves fitted to historical technology adoption patterns, with inputs from clinical trial data volume growth and manufacturing sensor deployment density trajectories.
Practitioners should monitor EU AI Act enforcement action timing, FDA 510(k) backlog clearance rates, and hyperscaler GPU allocation policies for early signals requiring forecast revision. Cross-checking against Gartner and IDC enterprise software spend benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Asia-Pacific Mobile Analytics Market
Analytics
Sales Intelligence Market
Analytics
Customer Identity Graph Drift Monitoring Market
Analytics
Global in-Store Analytics Market
Analytics
Business Intelligence and Analytics Software Market
Analytics
Iraq ICT Market
Analytics
Analytics Sandbox Market
Analytics
Social Business Intelligence Market
Analytics
Global Network Analytics Market
Analytics
Digital Analytics Solutions Market
Analytics
UK Video Analytics Market
Analytics
Content Analytics and Discovery Software Market
Analytics
Service Analytics Market
Analytics
Supply Chain Big Data Analytics Market
Analytics
Mobile Analytics Market
Analytics
IT Operation Analytics (ITOA) Market