
 Customer Analytics in E-Commerce Market | 2026-2036
Customer Analytics in E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Customer Analytics in E-Commerce Market Analysis
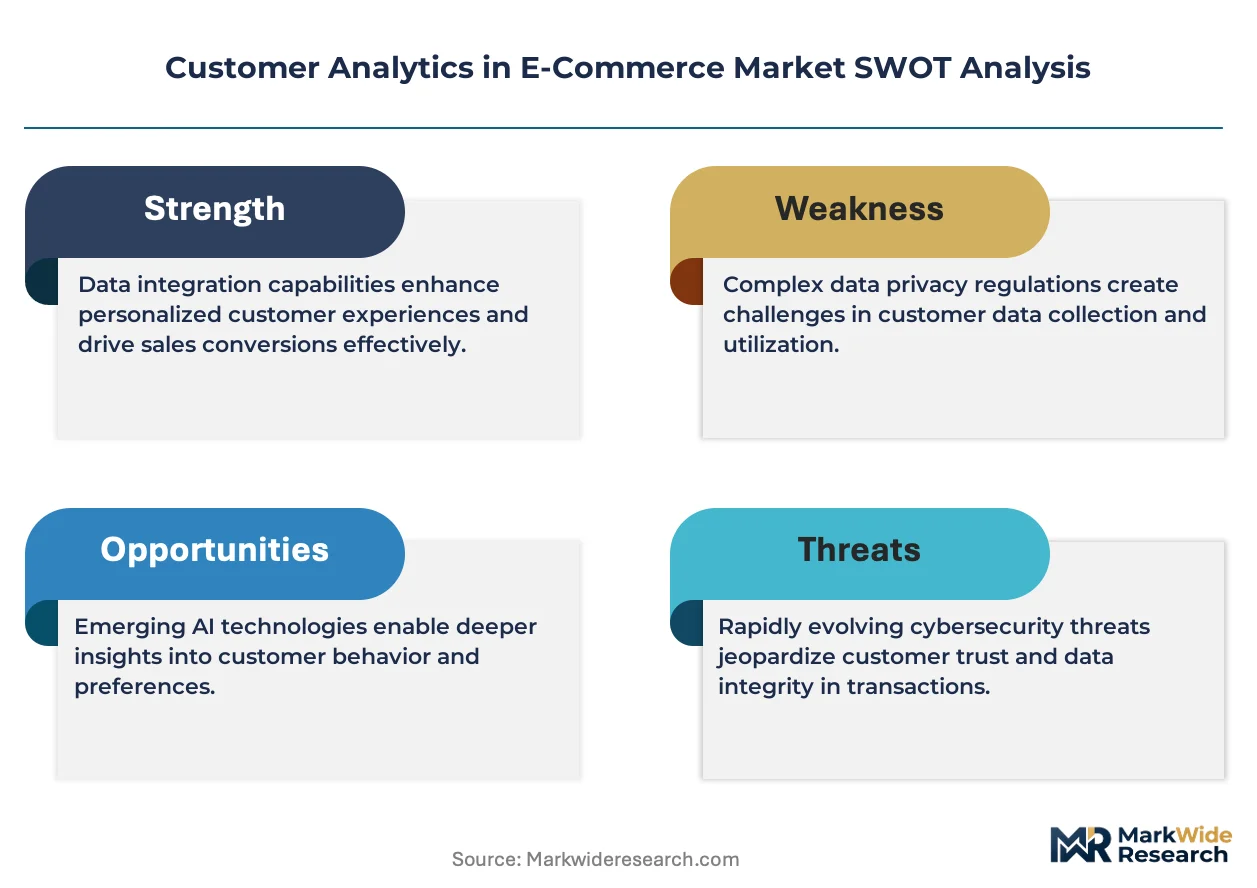
GDPR Article 22 is decoupling automated profiling from unchecked deployment across European e-commerce platforms. Salesforce leverages its Einstein engine to anchor predictive segmentation for enterprise retailers. Google dominates search-intent analytics, while SAS specializes in statistical depth for fraud-pattern detection among payment processors.
Customer analytics in e-commerce encompasses the computational extraction, modeling, and activation of behavioral signals from digital transaction logs, clickstream data, and identity graphs to forecast purchasing propensity and optimize lifetime value. The discipline relies on real-time event streaming architectures with sub-100-millisecond latency thresholds to serve dynamic pricing and inventory allocation decisions. Cloud-based deployment leads the technology dimension by eliminating capital-intensive infrastructure provisioning for mid-market retailers. Machine learning applications within personalization and recommendation systems command the fastest expansion, as neural collaborative filtering replaces rule-based merchandising logic. On-premises installations persist among luxury brands with stringent data residency requirements, though their margin pool stagnates relative to SaaS alternatives.
The Federal Trade Commission scrutinizes dark-pattern analytics that manipulate consumer choice architecture, while the EU AI Act mandates human oversight for high-risk automated decision systems in credit and pricing. India's Digital Personal Data Protection Act compels explicit consent frameworks for cross-site behavioral tracking, reshaping how marketplaces architect their data pipelines. Stakeholders must weigh sovereign data localization against the latency economics of centralized cloud inference.
Market Dynamics
Real-time event streaming architectures with sub-100-millisecond latency thresholds are compressing decision cycles across digital commerce, forcing retailers to rebuild data pipelines around inference speed rather than batch processing efficiency.
Growth Catalysts
- EU AI Act transparency mandates:Algorithmic explainability requirements are accelerating investment in interpretable machine learning frameworks for recommendation engines.
- Vernacular-language analytics tools:India's direct-to-consumer brand ecosystem is driving demand for multilingual natural language processing in customer segmentation.
- Behavioral clustering deployment:Online fashion retailers are reducing cart abandonment through real-time micro-segmentation of purchase intent signals.
Market Restraints
- Data residency compliance costs:India's Digital Personal Data Protection Act imposes explicit consent frameworks that fragment cross-site tracking architectures.
- Cloud inference latency economics:Sovereign data localization requirements in multiple jurisdictions conflict with centralized model serving efficiency.
- Human oversight mandates:The EU AI Act compels manual review protocols for high-risk automated pricing and credit decisions, slowing deployment velocity.
Strategic Opportunities
- Vernacular analytics penetration:Tier-2 and Tier-3 Indian cities remain underserved by English-first customer intelligence platforms.
- Federated learning architectures:Privacy-preserving model training across distributed datasets addresses GDPR Article 22 profiling restrictions.
- Neural collaborative filtering convergence:Deep learning recommendation systems are replacing rule-based merchandising logic in mid-market retail.
Industry Challenges
- Real-time pipeline engineering talent:Sub-100-millisecond latency requirements demand scarce expertise in event streaming and edge inference optimization.
- Legacy system integration friction:On-premises data warehouses at established retailers resist cloud-native analytics migration without extensive API reconstruction.
- Dark-pattern detection exposure:The Federal Trade Commission is scrutinizing choice architecture manipulation, requiring audit trails for behavioral nudge implementations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Customer Analytics in E-Commerce Market |
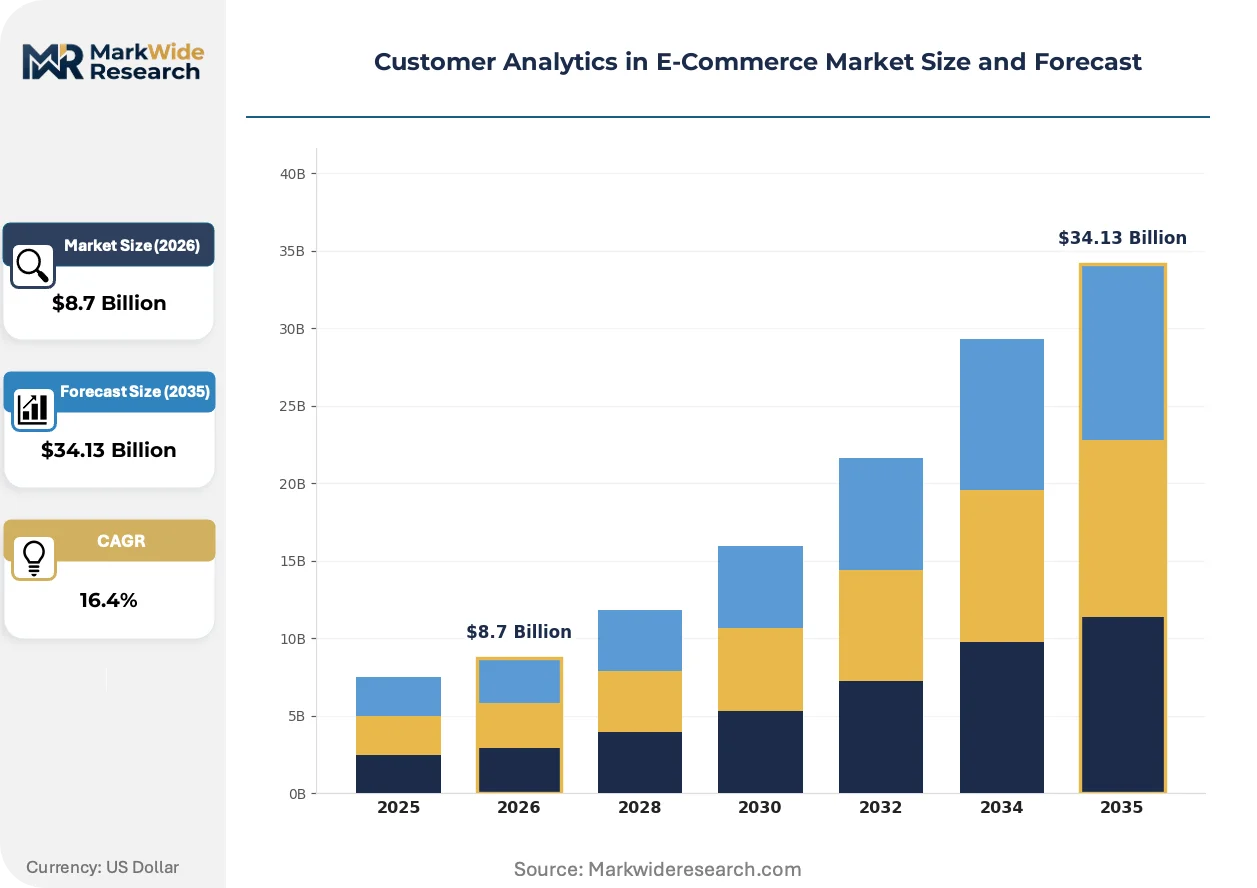
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Personalization, Customer Segmentation, Predictive Analytics, Recommendation Systems Technology: Machine Learning, Big Data, AI, Cloud Computing End User: Retailers, Marketplaces, Brands, Consumer Goods Deployment: On-Premises, Cloud-Based, Hybrid, SaaS |
| Companies Covered | Adobe, Salesforce, Oracle, SAP, IBM, Google, Microsoft, SAS, Tableau, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Customer Analytics in E-Commerce Market Emerging Trajectories
Neural architectures are compressing the latency-performance tradeoff in customer intelligence, while regulatory fragmentation across data sovereignty and algorithmic accountability is forcing modular compliance engineering.
Transformer-based sequence models are overtaking traditional collaborative filtering for next-action prediction in e-commerce recommendation systems. Enterprise retailers are deploying these architectures for real-time personalization at scale. The technology is overtaking matrix factorization approaches by capturing long-range behavioral dependencies in clickstream data.
GDPR Article 22 is decoupling automated profiling from unchecked deployment across European e-commerce platforms. The regulation forces explicit human-in-the-loop protocols for consequential pricing decisions. High-risk algorithmic systems in credit and dynamic pricing now require documented override capabilities.
Direct-to-consumer brands are unbundling third-party marketplace analytics in favor of first-party data sovereignty. Subscription commerce and owned-channel retail are displacing platform-dependent customer intelligence. This shift concentrates most visibly in India's vernacular-language brand ecosystem, where marketplace fee structures erode margin capture.
Customer Analytics in E-Commerce Market Segmentation
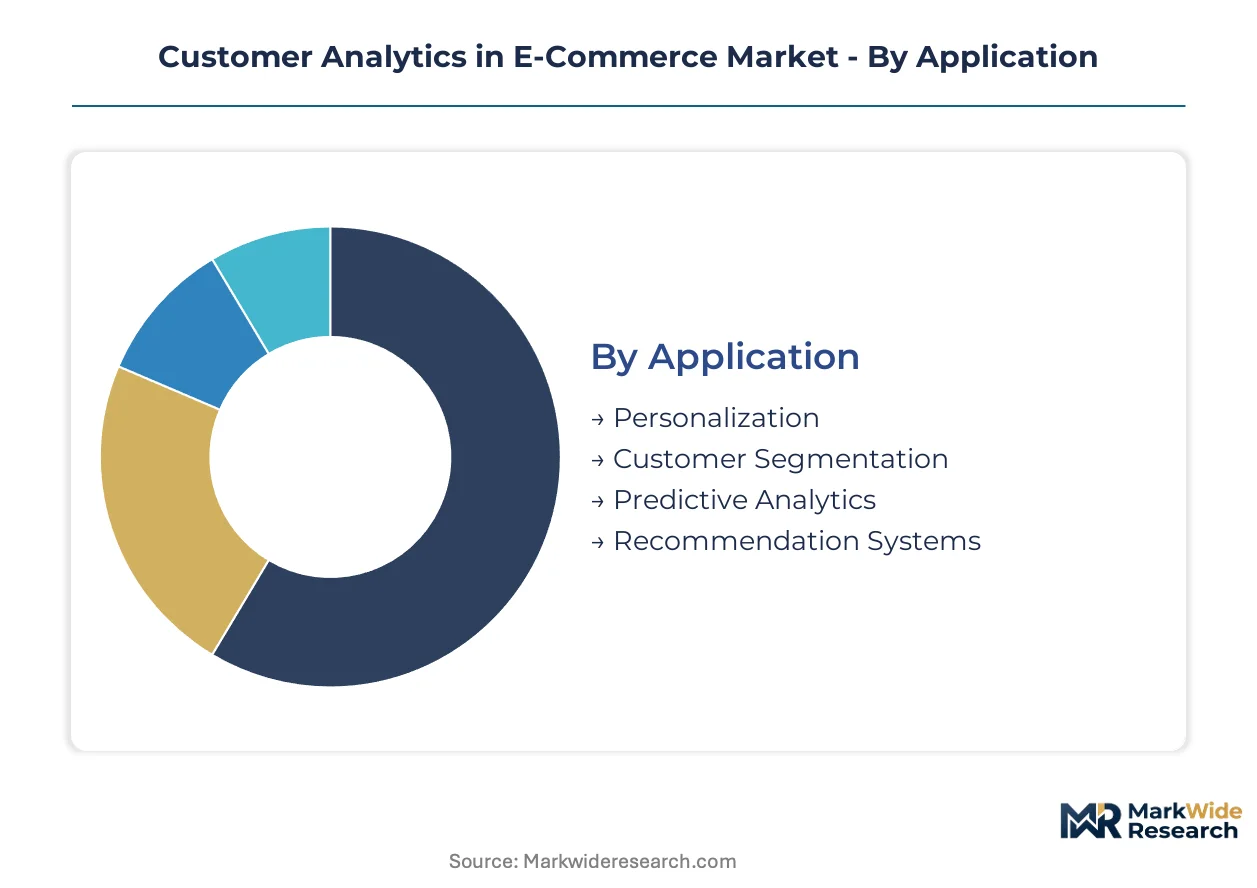
Customer analytics in e-commerce fragments across four structural dimensions: application purpose, underlying technology, buyer organization type, and infrastructure delivery model. Each axis carries distinct certification burdens and latency requirements that reshape vendor positioning.
Application:
GDPR Article 22 and the EU AI Act impose divergent compliance loads across use cases, with automated profiling and consequential pricing decisions triggering mandatory human oversight protocols.
- Personalization:Real-time content adaptation engines process clickstream signals through sub-100-millisecond inference pipelines. European fashion retailers deploy these systems under strict algorithmic transparency mandates that document override capabilities for dynamic pricing adjustments.
- Recommendation Systems:Neural collaborative filtering architectures replace legacy matrix factorization by capturing long-range behavioral dependencies in session data. India's direct-to-consumer brands drive vernacular-language model demand as they unbundle marketplace dependency for first-party data sovereignty.
- Customer Segmentation:Behavioral clustering isolates micro-cohorts from identity graphs and transaction logs.
- Predictive Analytics:Propensity scoring models forecast lifetime value and churn probability from historical purchase patterns.
Leading the category by volume: Personalization. Growing fastest: Recommendation Systems.
Technology:
Cost tier stratification separates capital-intensive infrastructure from pay-as-you-scale alternatives, with mid-market retailers avoiding upfront GPU cluster investments.
- Cloud Computing:Distributed inference architectures eliminate data center provisioning for seasonal demand spikes. Indian marketplaces leverage multi-region deployments to satisfy Digital Personal Data Protection Act localization requirements without sacrificing latency economics.
- Machine Learning:Supervised and unsupervised algorithms extract predictive signals from structured and unstructured behavioral data. European platforms invest heavily in interpretable model frameworks to satisfy EU AI Act explainability mandates for high-risk automated decisions.
- AI:Generative and discriminative models power natural language interfaces and visual search capabilities.
- Big Data:Distributed storage and processing frameworks handle petabyte-scale event streams from global transaction networks.
Cloud Computing captures the largest installed base. Machine Learning claims the steepest expansion trajectory.
End User:
Customer maturity and data sophistication create sharp capability gaps between platform-dependent sellers and owned-channel operators.
- Marketplaces:Aggregator platforms deploy unified analytics layers across millions of third-party sellers. Amazon and Flipkart infrastructure teams face FTC scrutiny on dark-pattern detection while optimizing conversion funnels through behavioral nudge architectures.
- Brands:Direct-to-consumer operators build proprietary intelligence stacks to escape marketplace fee erosion. Subscription commerce specialists in India's Tier-2 cities prioritize vernacular-language dashboard interfaces for non-English marketing teams.
- Retailers:Multi-channel merchants integrate online and offline behavioral signals into unified customer views.
- Consumer Goods:Manufacturers apply demand sensing analytics to optimize production scheduling and inventory positioning.
Marketplaces dominate current spending. Brands are gaining share fastest through first-party data investments.
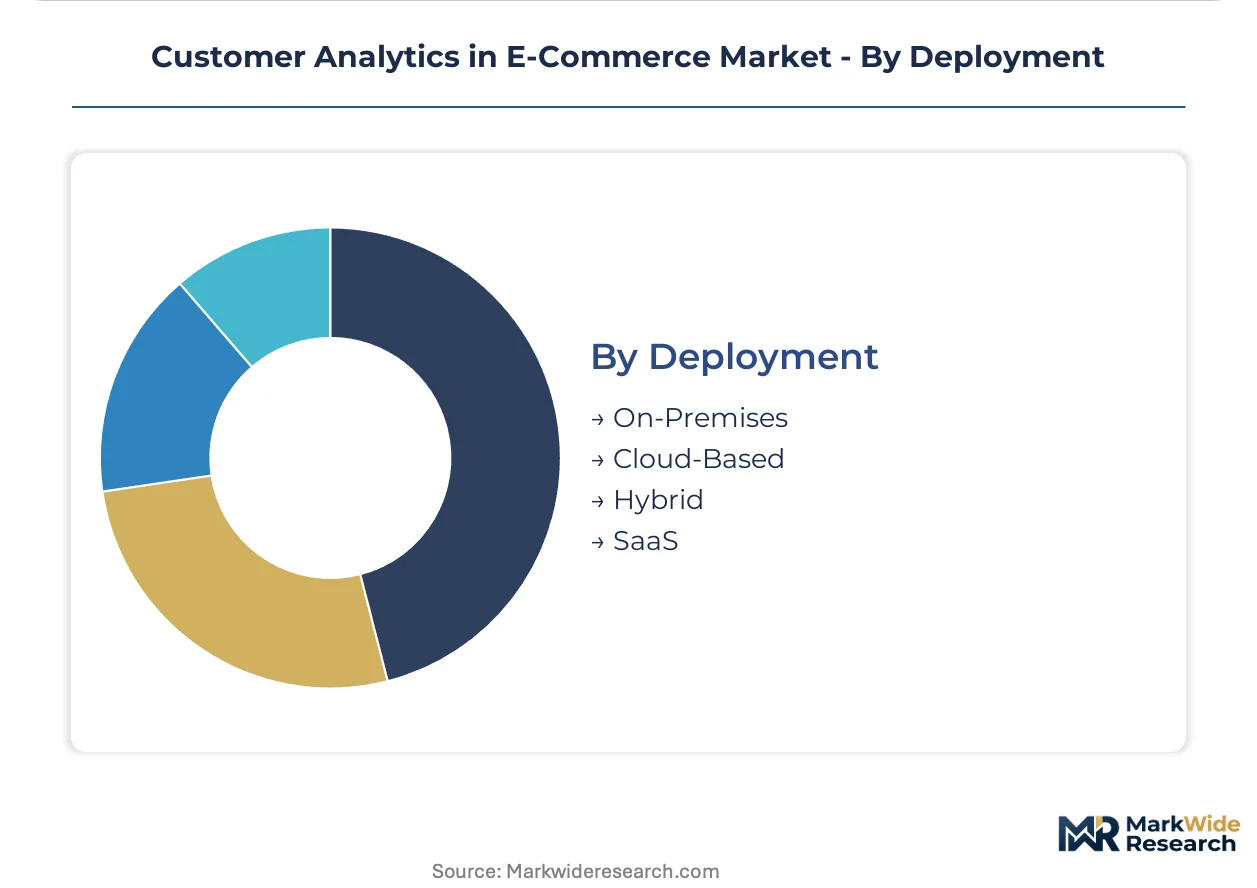
Deployment:
Infrastructure location decisions trade latency optimization against sovereign data residency requirements across fragmented regulatory jurisdictions.
- Cloud-Based:Fully managed SaaS and PaaS offerings eliminate hardware lifecycle management for mid-market retailers. GDPR-bound European operators select EU-only regions to preempt cross-border transfer restrictions while maintaining sub-100-millisecond response thresholds.
- SaaS:Pre-configured analytics applications accelerate time-to-value for organizations lacking internal data engineering capacity. Indian direct-to-consumer startups prefer consumption-priced models that align costs with fluctuating transaction volumes.
- On-Premises:Self-managed infrastructure persists among luxury brands with stringent data residency requirements and legacy system dependencies.
- Hybrid:Split architectures process sensitive data locally while leveraging cloud elasticity for compute-intensive model training.
Cloud-Based deployment leads by revenue volume. SaaS delivery is climbing the fastest among emerging market entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Bangalore and Hyderabad concentrate cloud infrastructure investment for Indian e-commerce analytics, while GDPR enforcement zones across Northern Europe reshape data pipeline economics for cross-border retailers.
United States
FTC scrutiny of dark-pattern analytics and behavioral nudge architectures drives compliance investment among marketplace operators. The Federal Trade Commission's enforcement actions against manipulative choice architecture force audit trail documentation for conversion optimization systems. Seattle and San Francisco Bay Area clusters host the dominant cloud-native analytics engineering talent pools.
Germany
EU AI Act transparency mandates accelerate interpretable machine learning framework adoption for automated pricing decisions. The Bundesdatenschutzaufsichtsbehörde enforces GDPR Article 22 human-in-the-loop protocols for consequential algorithmic systems. Berlin and Munich house specialized compliance engineering consultancies serving DAX-listed retailers.
India
Vernacular-language natural language processing demand surges among Tier-2 and Tier-3 direct-to-consumer brands unbundling marketplace dependency. The Digital Personal Data Protection Act imposes explicit consent frameworks fragmenting cross-site behavioral tracking architectures. Bangalore and Hyderabad special economic zones concentrate cloud infrastructure investment for real-time inference pipelines.
United Kingdom
Post-Brexit data adequacy negotiations force dual-compliance architecture investment for retailers serving EU and UK markets simultaneously. The Information Commissioner's Office enforces automated decision-making transparency requirements under UK GDPR derivative regulations. London's fintech corridor anchors fraud-pattern detection analytics specialization among payment processors.
France
CNIL enforcement of algorithmic accountability pushes French luxury brands toward on-premises deployment for stringent data residency requirements. The EU AI Act's high-risk system classification triggers manual review protocol implementation for dynamic pricing engines. Parisian fashion houses invest in first-party data sovereignty infrastructure to escape platform fee erosion.
Customer Analytics in E-Commerce Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across deployment models and latency tiers. Cloud-native SaaS vendors capture mid-market expansion through consumption-priced models, while legacy enterprise software houses defend installed base relationships through hybrid integration capabilities. Strategic archetypes separate into real-time inference specialists, compliance-heavy European operators, and vernacular-language regional champions. Competitive moves concentrate on federated learning partnerships and sovereign cloud region expansion.
Among diversified technology conglomerates, Adobe, Salesforce, and SAP occupy positions spanning creative cloud integration, CRM-native analytics, and ERP-embedded intelligence respectively. Adobe exemplifies the content-personalization convergence archetype through its creative-to-commerce workflow integration. Salesforce anchors predictive segmentation capabilities through its Einstein engine deployment across enterprise retail. SAP represents the operational-data-context archetype, embedding customer intelligence within supply chain and financial planning systems.
| Leading Market Players |
|---|
| Adobe |
| Salesforce |
| Oracle |
| SAP |
| IBM |
| Microsoft |
| SAS |
| Tableau |
| Others |
Supply Flow & Price Mechanics
Latency-performance tier divergence separates sub-100-millisecond real-time inference engines from batch-processed analytics commodities, with premium deployments commanding SaaS multiples that reflect scarce edge-computing infrastructure and specialized event-streaming engineering talent. This bifurcation manifests in supply chain configurations where cloud-native vendors concentrate GPU cluster investments in Bangalore and Hyderabad special economic zones, while on-premises luxury deployments tether to Frankfurt and Paris data centers under CNIL and Bundesdatenschutzaufsichtsbehörde residency mandates.
Pricing Analysis
Short lead-time premiums attach to sub-100-millisecond inference pipelines serving dynamic pricing and inventory allocation decisions, while spot inventory discounts emerge for batch-processed segmentation tools with 24-hour latency tolerances. SaaS consumption models dominate mid-market retail, with pricing stratifying across premium real-time tiers, standard daily-batch tiers, and economy self-service analytics levels. Price differentiation hinges on latency thresholds and GDPR Article 22 compliance certification levels. Cost compression in standard tiers intensifies as Indian direct-to-consumer brands consolidate vendor relationships. Enterprise retailers exhibit lowest price sensitivity; Tier-2 Indian startups show highest.
Supply Chain Analysis
Freight cost exposure concentrates in cross-border data transfer economics between EU-only cloud regions and centralized training clusters, forcing Indian marketplaces into multi-region inference architectures. Supply concentrates in the United States for cloud-native engineering talent, India for vernacular-language NLP development, and Germany for interpretable machine learning frameworks. Raw material dependencies span GPU accelerators from NVIDIA supply chains, open-source transformer architectures from Hugging Face ecosystems, and consent-management platforms for Digital Personal Data Protection Act compliance. Single-source vulnerability sits with NVIDIA's datacenter GPU allocation. Distribution runs through hyperscaler marketplaces and direct enterprise sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into first-party data pipelines is accelerating competitive separation, with direct-to-consumer brands and marketplace operators racing to own identity graphs rather than rent third-party signals. This upstream control over behavioral data assets is reshaping margin capture and vendor dependency structures.
For Market Incumbents: Hedge against federated learning disruption by acquiring vernacular-language NLP specialists in India's Tier-2 cities before regional champions consolidate. Deepen backward integration into consent-management infrastructure to preempt Digital Personal Data Protection Act fragmentation costs. Defend against SaaS-native entrants by embedding Einstein-style predictive engines into existing CRM workflows rather than bolting on standalone analytics modules. For New Entrants and Emerging Players: Enter via India's underserved vernacular-language dashboard segment, where English-first platforms from Adobe and Salesforce leave Tier-3 direct-to-consumer brands without accessible intelligence tools. Target the compliance-heavy European mid-market through interpretable machine learning frameworks that preempt EU AI Act audit requirements. Anchor go-to-market through consumption-priced SaaS models that align with fluctuating transaction volumes rather than upfront licensing. For Investors and Strategic Acquirers: Re-rating potential sits with federated learning specialists given GDPR Article 22 enforcement acceleration and manual-oversight mandate expansion. Long-term viability favors privacy-preserving architectures that train across distributed datasets without centralizing sensitive behavioral records. Watch for FTC dark-pattern enforcement actions as inflection indicators for audit-trail technology demand.| Strategic Initiative | Industry Significance |
|---|---|
| Federated Learning Partnership | Addresses GDPR Article 22 profiling restrictions while preserving model accuracy across distributed Indian and European datasets. |
| Vernacular NLP Acquisition | Captures Tier-2 and Tier-3 Indian direct-to-consumer brands abandoning English-first marketplace analytics platforms. |
| Sovereign Cloud Region Expansion | Satisfies Digital Personal Data Protection Act localization mandates without sacrificing sub-100-millisecond latency economics. |
| Interpretable ML Framework Investment | Preempts EU AI Act transparency enforcement for high-risk automated pricing and credit decision systems. |
| Consent-Management Platform Integration | Fragments cross-site tracking architectures into compliant first-party data pipelines under India's explicit consent framework. |
Methodological Framework
Document review covered SEC filings from Adobe, Salesforce, and SAP, hyperscaler capex disclosures from Google and Microsoft, EU AI Act implementation guidance, and Digital Personal Data Protection Act draft rules, complemented by interviews with chief data officers at Indian direct-to-consumer brands, compliance engineering leads at German retailers, and cloud infrastructure architects at Bangalore special economic zone operators. Secondary validation drew from FTC enforcement action records, CNIL algorithmic accountability guidance, and trade data on GPU import flows. Bottom-up segment sizing triangulated against top-down market aggregation.
Cross-referencing historical deployment velocity against expert panel inputs shaped the analytical framework across the projection horizon. Segmentation dimensions modeled encompass deployment model, organization size tier, application purpose, latency requirement threshold, and regional regulatory cluster. CAGRs derived from growth rate reconciliation between vendor revenue disclosures and end-user spending surveys. Industry-specific forecast inputs incorporated EU AI Act implementation timelines and vernacular-language model adoption curves in Indian Tier-2 cities.
Revisions become necessary when EU AI Act enforcement intensity exceeds baseline assumptions, when NVIDIA GPU supply constraints tighten cloud inference capacity, or when India's Digital Personal Data Protection Act final rules diverge from draft provisions. Forecasts reflect documented assumptions about regulatory implementation pacing and technology substitution rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Latin America Location Based Data Analytics Market
Analytics
Europe Predictive Analytics Market
Analytics
UK Video Analytics Market
Analytics
Spend Analytics Software Market
Analytics
Japan Geospatial Analytics Market
Analytics
AI Performance Marketing Market
Analytics
Learning Analytics Solution Market
Analytics
Global Network Analytics Market
Analytics
Global Business Intelligence (BI) Software Market
Analytics
UAE Geospatial Analytics Market
Analytics
Sweden ICT Market
Analytics
Human Resource Analytics Market
Analytics
Lead Intelligence Software Market
Analytics
Global Sales Performance Management Market
Analytics
United Kingdom Business Intelligence Market
Analytics
Data Wrangling Market