
 Data Analytics Outsourcing Market | 2026-2036
Data Analytics Outsourcing Market Size, Share, and Industry Trends Forecast 2026-2036
Data Analytics Outsourcing Market Intelligence
The EU AI Act is realigning how European enterprises contract analytics services, forcing providers to demonstrate algorithmic transparency and audit trails. Accenture leverages its compliance infrastructure to anchor large outsourcing contracts across Frankfurt and Paris. IBM sustains technology leadership through proprietary AI governance tooling that addresses emerging regulatory requirements. Deloitte competes on sector depth, embedding specialized risk models for financial services clients navigating supervisory expectations.
Data analytics outsourcing encompasses the delegation of statistical analysis, machine learning operations, and business intelligence workflows to third-party specialists, typically delivered through cloud-native platforms with service-level agreements governing latency, accuracy thresholds, and data residency. Its primary commercial purpose is converting raw enterprise data into actionable intelligence without the fixed cost of in-house data science teams. Predictive analytics commands premium pricing due to specialized talent scarcity and longer implementation cycles, while cloud-based deployment captures the fastest expansion as enterprises retire on-premises data warehouses. Retail and financial services end users represent the deepest margin pools, driven by high-frequency transaction data and regulatory reporting obligations.
FDA oversight of clinical decision-support algorithms shapes healthcare outsourcing contracts, requiring validated documentation chains that only specialized vendors can maintain. India's BIS data localization guidelines and the EU's GDPR cross-border transfer mechanisms create divergent compliance architectures that providers must navigate simultaneously. Stakeholders should monitor how emerging AI liability frameworks in the European Union and United States redistribute risk between enterprise buyers and analytics vendors.
Market Dynamics
Cloud migration mandates under the EU AI Act are forcing analytics providers to rebuild compliance architectures for algorithmic transparency and audit trails. This regulatory pressure is compressing vendor consolidation timelines as enterprises seek partners with pre-certified governance tooling.
Growth Catalysts
- FDA Clinical Decision-Support Oversight:Healthcare providers outsource algorithm validation to specialized vendors capable of maintaining documentation chains for clinical AI tools.
- India BIS Data Localization:Domestic delivery centers in Bangalore and Hyderabad capture expanding contract volumes as global enterprises seek compliant offshore processing.
- Real-Time Predictive Analytics:Financial services firms deploy outsourced machine learning operations for high-frequency transaction monitoring and regulatory reporting automation.
Market Restraints
- Specialized Talent Scarcity:Data science labor shortages in India and Eastern Europe inflate implementation timelines for predictive analytics engagements.
- Cross-Border Transfer Friction:GDPR mechanisms and divergent EU-US data frameworks create legal uncertainty that delays contract finalization.
- On-Premises Legacy Inertia:Enterprises with sunk costs in internal data warehouses resist full cloud migration despite operational inefficiencies.
Strategic Opportunities
- EU AI Act Compliance Services:Algorithmic audit and transparency tooling represents unmet demand as European enterprises face 2025 enforcement deadlines.
- Edge Analytics Convergence:Integration of 5G infrastructure with distributed machine learning enables low-latency outsourcing for manufacturing and logistics clients.
- Saudi Arabia and UAE Digital Transformation:National AI strategies in Gulf economies create first-mover advantages for providers establishing localized delivery capabilities.
Industry Challenges
- Multi-Jurisdiction Certification Burden:Vendors must simultaneously maintain FDA, EMA, and CDSCO documentation standards for healthcare analytics contracts.
- Algorithmic IP Disputes:Ambiguous ownership of trained models and feature engineering creates contractual friction between enterprises and outsourcing partners.
- Legacy System Integration Complexity:Mainframe data warehouses and proprietary ETL pipelines require expensive middleware development before cloud analytics deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Analytics Outsourcing Market |
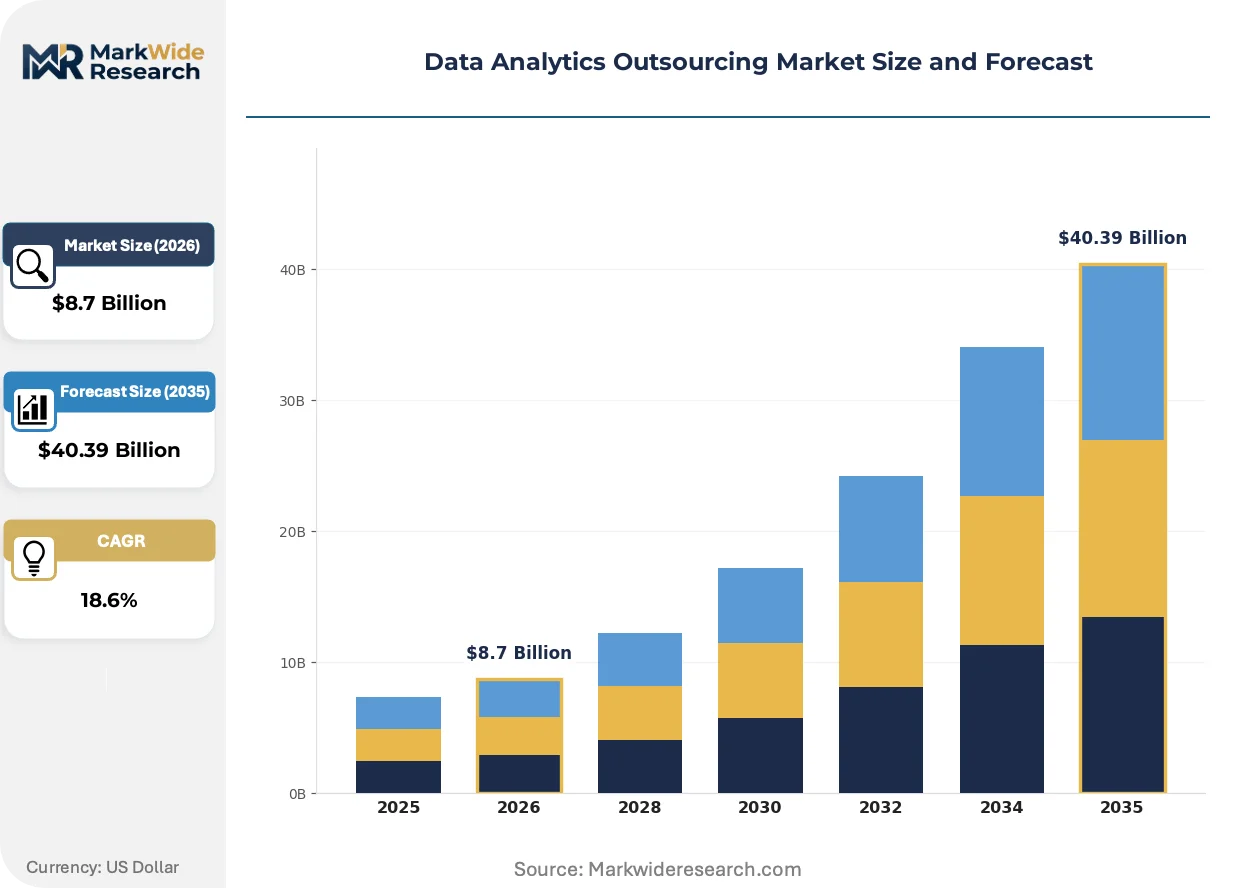
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $40.39 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Data Mining, Data Processing, Data Visualization, Predictive Analytics End User: Retail, Financial Services, Healthcare, Telecommunications Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services Industry Vertical: Manufacturing, Education, Transportation, Energy |
| Companies Covered | Wipro, Fractal Analytics, Accenture, Xavor Corporation, Innowise, IBM, SG Analytics, Adastra, Deloitte, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Analytics Outsourcing Market Strategic Shifts & Innovations
Generative AI capabilities are embedding into analytics workflows, reshaping how enterprises contract for insight generation. Three developments are restructuring competitive positioning and value capture.
Automated machine learning (AutoML) platforms are electrifying the economics of statistical model deployment. Retail and consumer goods enterprises adopt these tools at compressed implementation cycles, collapsing the traditional six-month data science engagement into weeks. This compression is forcing tier-one providers to reposition toward higher-value interpretive and governance services.
The EU AI Act's risk-based classification system is mandating algorithmic impact assessments for high-stakes applications. Financial services and healthcare buyers now require documented conformity procedures before contract execution. German and French enterprises are advancing fastest in embedding these requirements into procurement specifications.
Consumption-based pricing models are displacing fixed-fee analytics contracts. Enterprise buyers prefer variable cost structures tied to query volume or insight frequency rather than committed capacity. This shift is most visible among mid-market financial services firms in London and Singapore seeking operational flexibility.
Data Analytics Outsourcing Market Segmentation
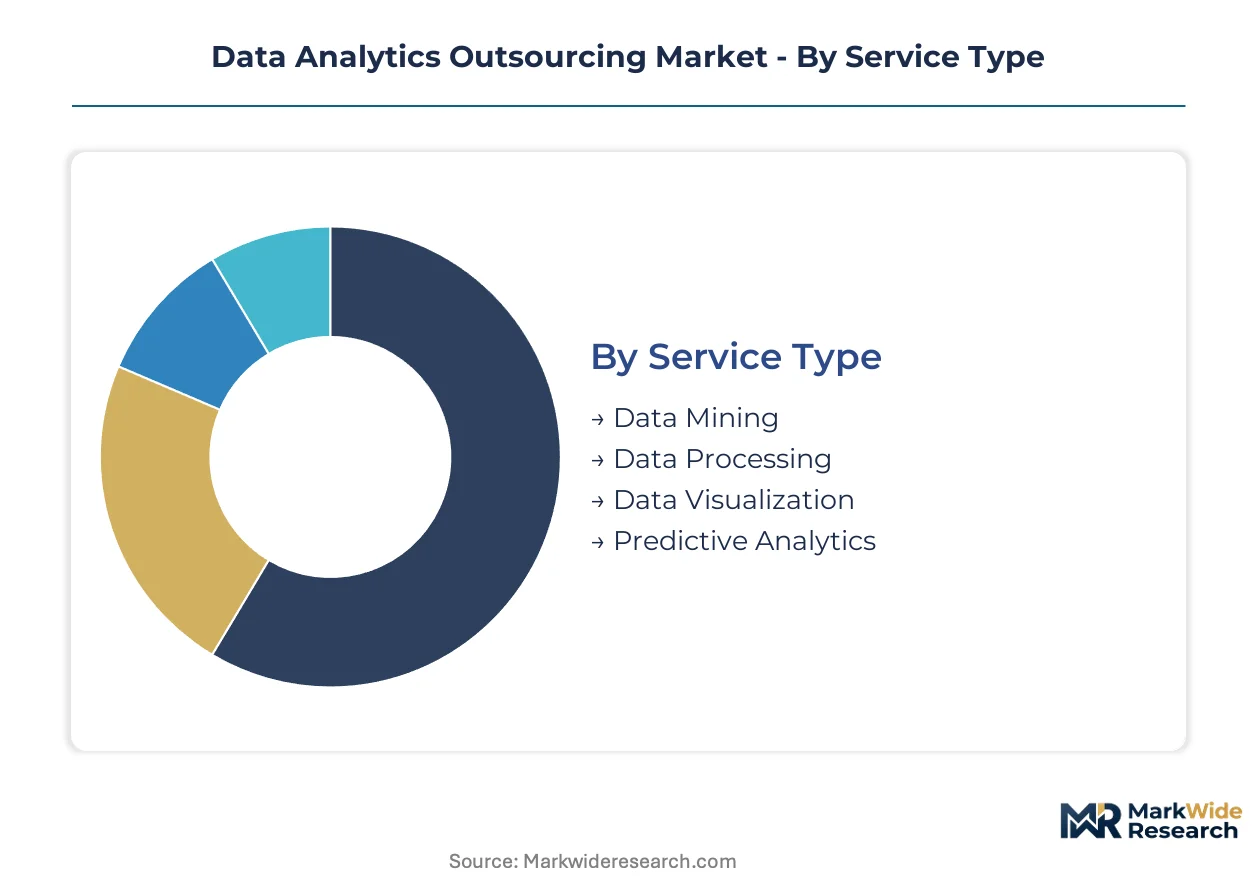
Segmentation in data analytics outsourcing reveals how service complexity, regulatory exposure, and infrastructure maturity reshape contract structures. Buyers select service tiers and deployment modes based on data sensitivity, latency requirements, and cross-border compliance obligations.
Service Type:
Standalone analytical services operate independently from client systems, while embedded offerings integrate directly into enterprise workflows and decision engines.
- Predictive Analytics:Machine learning models forecasting demand, risk, or operational outcomes through statistical inference and pattern recognition. Financial services firms in London and Singapore deploy these tools for high-frequency transaction monitoring and regulatory reporting automation, paying premium rates for specialized talent.
- Data Visualization:Interactive dashboards and graphical reporting interfaces translating complex datasets into executive-facing insights. Retail enterprises concentrate demand here, driven by real-time inventory tracking and customer behavior analytics across omnichannel operations.
- Data Mining:Pattern extraction from large unstructured datasets using clustering and association algorithms.
- Data Processing:ETL pipelines, cleansing workflows, and transformation routines preparing raw data for downstream analysis.
Volume placements concentrate in Data Processing; the faster expansion belongs to Predictive Analytics.
End User:
Customer archetypes segment by data velocity, regulatory scrutiny, and insight-to-action latency requirements.
- Financial Services:Banks, insurers, and asset managers outsourcing algorithmic trading analytics, fraud detection, and stress testing. GDPR and SEC reporting mandates drive contract specifications for audit trails and data lineage documentation.
- Healthcare:Providers and payers delegating clinical decision-support validation, population health analytics, and claims optimization. FDA oversight requirements shape vendor selection toward specialists maintaining validated documentation chains.
- Retail:Merchandisers and e-commerce platforms seeking demand forecasting and customer segmentation.
- Telecommunications:Network operators analyzing subscriber churn, traffic patterns, and infrastructure utilization.
Contract value pools deepest in Financial Services; Healthcare climbs the fastest as clinical AI adoption accelerates.
Deployment:
Infrastructure choices reflect trade-offs between control, compliance certification, and operational flexibility.
- Cloud-Based:Scalable compute and storage delivered through hyperscaler platforms with consumption-based pricing. EU AI Act transparency mandates are compressing migration timelines as enterprises seek pre-certified governance tooling.
- Hybrid:Split architectures retaining sensitive data on-premises while bursting analytical workloads to cloud infrastructure. German and French manufacturers favor this model for intellectual property protection alongside elastic capacity.
- On-Premises:Dedicated hardware installations within client data centers.
- Managed Services:Fully outsourced infrastructure and operations with SLA-governed uptime and performance.
Legacy commitments sustain On-Premises volume; Cloud-Based deployment gains share fastest as data warehouse retirement accelerates.
Industry Vertical:
Sector-specific applications diverge by data granularity, physical asset intensity, and regulatory density.
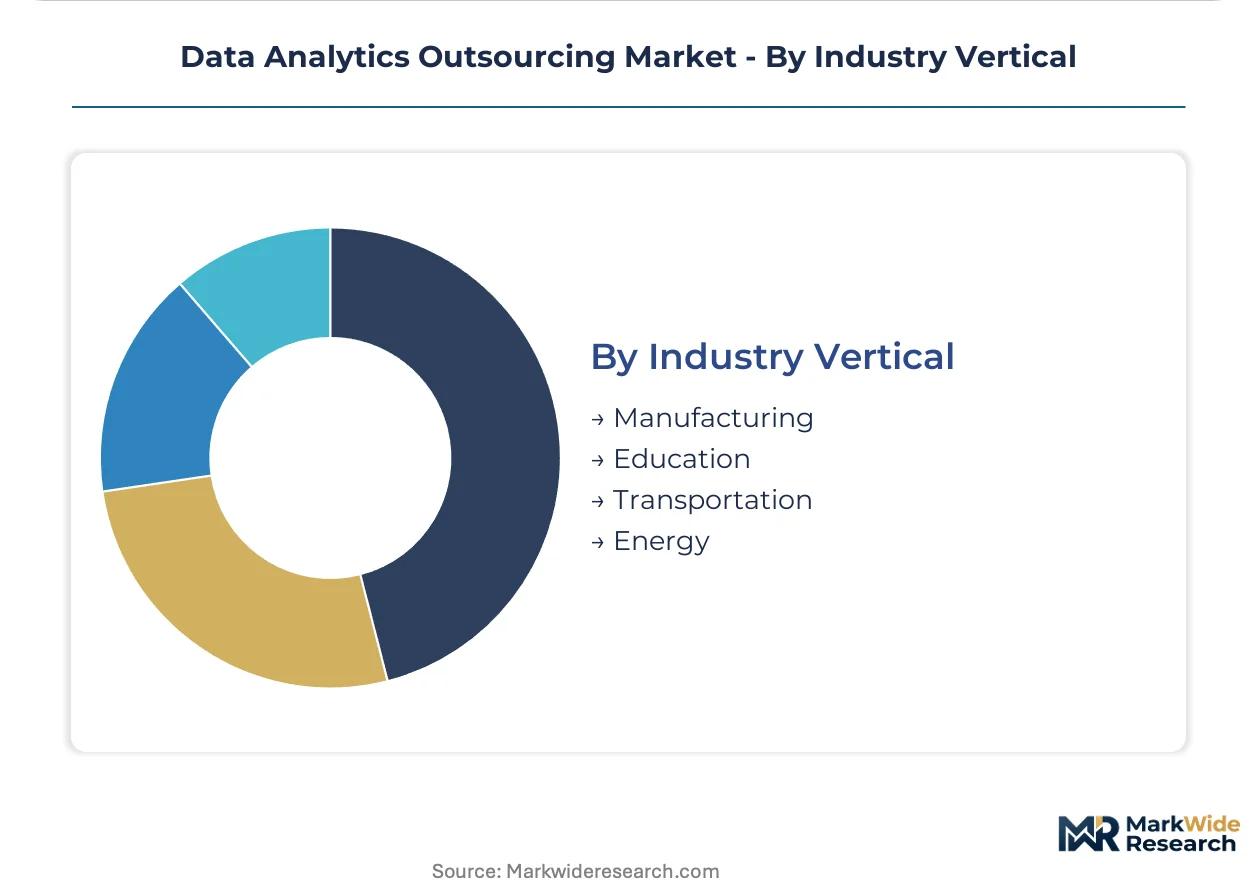
- Manufacturing:Predictive maintenance, quality control analytics, and supply chain optimization across discrete and process industries. German automotive suppliers and Japanese electronics manufacturers drive adoption of edge-integrated analytics for real-time production monitoring.
- Energy:Grid optimization, renewable forecasting, and emissions analytics for utilities and oil & gas operators. Saudi Arabia and UAE national AI strategies are creating localized demand for infrastructure monitoring and carbon accounting services.
- Transportation:Fleet analytics, route optimization, and logistics coordination.
- Education:Learning analytics, enrollment forecasting, and institutional performance measurement.
Manufacturing anchors current vertical spending; Energy shows the steepest expansion trajectory as decarbonization analytics mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bangalore and Hyderabad anchor global delivery capacity for outsourced analytics services, hosting the largest concentration of specialized talent and compliance-certified operations centers serving cross-border enterprise demand.
United States
Financial services firms in New York and Chicago drive premium demand for algorithmic trading analytics and fraud detection systems. FDA oversight of clinical decision-support algorithms shapes healthcare outsourcing contracts toward vendors with validated documentation chains. The Boston-Cambridge corridor concentrates specialized healthcare analytics providers serving pharmaceutical and biotech clients.
India
BIS data localization guidelines redirect global contract volumes toward domestic delivery centers in Bangalore and Hyderabad. IT services exporters in these cities capture expanding mandates from European and North American enterprises seeking compliant offshore processing. The Hyderabad Financial District and Bangalore Electronic City host the densest clusters of GDPR-certified analytics operations.
Germany
Automotive manufacturers in Stuttgart and Munich outsource predictive maintenance analytics and supply chain optimization to specialized vendors. EU AI Act transparency mandates compress migration timelines as German enterprises seek pre-certified governance tooling. The Frankfurt Rhine-Main metropolitan area concentrates financial services analytics demand tied to ECB supervisory reporting requirements.
United Kingdom
Mid-market financial services firms in London prefer consumption-based pricing models tied to query volume and insight frequency. FCA regulatory reporting obligations drive contract specifications for audit trails and data lineage documentation. The Canary Wharf and City of London districts host the deepest pools of sell-side and buy-side analytics outsourcing.
United Arab Emirates
National AI strategies in Abu Dhabi and Dubai create first-mover advantages for providers establishing localized delivery capabilities. MOHAP oversight of healthcare data processing shapes vendor selection toward specialists with Gulf-specific compliance architectures. Dubai Internet City and Abu Dhabi Global Market anchor the emerging analytics services corridor serving Saudi Arabia and broader GCC demand.
Data Analytics Outsourcing Market Key Industry Players
Premium-margin players sit above commodity-margin players across regulatory certification depth and sector-specific governance tooling. The vendor base stratifies into three tiers: global consultancies with pre-built compliance infrastructure, specialized analytics pure-plays with vertical depth, and scale-driven IT services exporters with cost-optimized delivery. Dominant competitive moves include strategic partnerships with hyperscaler cloud platforms and portfolio diversification into AI governance and algorithmic audit services.
Within the global consultancy tier, Accenture and Deloitte occupy positions defined by regulatory anchoring and sector specialization. Accenture leverages its Frankfurt and Paris compliance infrastructure to anchor large outsourcing contracts under EU AI Act mandates. Deloitte competes through embedded risk models for financial services clients navigating supervisory expectations. Among specialized analytics pure-plays, Fractal Analytics exemplifies the vertical-depth archetype, while IBM represents technology-led positioning through proprietary AI governance tooling.
| Leading Market Players |
|---|
| Wipro |
| Fractal Analytics |
| Accenture |
| Xavor Corporation |
| Innowise |
| IBM |
| SG Analytics |
| Adastra |
| Deloitte |
| Others |
Cost & Logistics Intelligence
Captive integration of compliance-certified delivery centers anchors supply positioning and pricing power for tier-one providers competing under divergent regulatory mandates. Vertical control over Bangalore and Hyderabad operations creates cost advantages that commodity players cannot replicate, while EU AI Act certification investments justify premium positioning in Frankfurt and Paris procurement cycles.
Pricing Analysis
Outcome-based pricing tied to algorithmic audit completion and regulatory submission success anchors contract structures in healthcare and financial services verticals. Three-tier pricing structure across premium certified, standard compliant, and economy offshore tiers separates Accenture's governance tooling from Fractal's vertical depth and Wipro's scale delivery. Pricing pressure stems from AutoML platform commoditization compressing implementation timelines for predictive analytics engagements. Mid-market financial services firms in London exhibit highest price sensitivity, while FDA-validated healthcare contracts demonstrate lowest elasticity due to documentation chain requirements.
Supply Chain Analysis
India's BIS data localization guidelines redirect sourcing toward domestic delivery centers, reshaping how global enterprises provision compliant offshore processing. Talent pipelines concentrate in Bangalore, Hyderabad, and Pune, drawing from Indian Institutes of Technology and specialized data science institutes. Supply chain risk centers on single-source vulnerability for EU AI Act-certified governance tooling, where only Accenture and IBM maintain pre-validated infrastructure. Distribution runs through direct enterprise sales for premium tiers and channel partnerships for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around regulatory certification depth as EU AI Act enforcement deadlines eliminate vendors lacking pre-built audit infrastructure. Compliance capability gaps force weaker players toward acquisition or exit.
For Market Incumbents: Anchor market position through proprietary AI governance tooling investments addressing FDA, EMA, and CDSCO simultaneous certification requirements. Acquire specialized healthcare analytics pure-plays to deepen clinical decision-support validation capabilities before EU AI Act transparency mandates harden procurement specifications. Defend against AutoML platform commoditization by repositioning toward interpretive and algorithmic audit services. For New Entrants and Emerging Players: Capture white-space in Saudi Arabia and UAE national AI strategy implementations, where localized delivery capabilities remain underdeveloped relative to Gulf digital transformation timelines. Target algorithmic impact assessment services for German and French mid-market enterprises facing compressed EU AI Act compliance deadlines. Pursue hyperscaler cloud partnership routes to bypass captive infrastructure investments. For Investors and Strategic Acquirers: Exit pathways concentrate in vertical-specialist acquisition by global consultancies seeking sector depth. Long-term viability favors providers with simultaneous multi-jurisdiction certification maintenance and proprietary governance tooling IP. Watch FDA guidance expansion on clinical AI liability as inflection signal for healthcare analytics vendor valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Certification | Pre-certified governance tooling unlocks Frankfurt and Paris procurement cycles ahead of enforcement deadlines. |
| Healthcare Vertical Acquisition | FDA-validated documentation chains command premium positioning in pharmaceutical and provider outsourcing. |
| Hyperscaler Cloud Partnership | AWS and Azure integration accelerates consumption-based pricing adoption among mid-market financial services. |
| Gulf Localization Buildout | Dubai and Abu Dhabi delivery centers capture Saudi Arabia and UAE national AI strategy implementation demand. |
| AutoML Platform Development | Automated machine learning compression threatens tier-one repositioning toward higher-value interpretive services. |
Research Approach
Independent corroboration across chief data officers at financial services firms, healthcare analytics procurement leads, regulatory affairs specialists at EU AI Act consultancies, and cloud platform partnership directors underwrites the qualitative findings. Primary fieldwork combined structured interviews with secondary validation through SEC 10-K disclosures, EU regulatory filing databases, and hyperscaler capex reports. Bottom-up service line sizing and top-down market envelope triangulation anchored volume estimates.
Comparable-period anchoring to historical outsourcing contract cycles and regulatory implementation timelines structured the projection framework. Segmentation dimensions modeled span service type complexity, deployment architecture, end-user regulatory exposure, and geographic delivery center certification status. CAGRs derived from elasticity-adjusted demand curves incorporating talent pipeline constraints and cross-border transfer friction coefficients.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU AI Act enforcement variance, FDA clinical AI liability expansion, and India BIS localization rule tightening. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
North America Operational Intelligence Market
Analytics
Global Customer Analytics Market
Analytics
Content Analytics Discovery and Cognitive Software Market
Analytics
Global Hadoop Big Data Analytics Market
Analytics
Global Mobile BI Market
Analytics
Analytics of Things (Aot) Market
Analytics
Global Analytics Software Market
Analytics
Service Analytics Market
Analytics
Spain Geospatial Imagery Analytics Market
Analytics
Global Business Intelligence (BI) Software Market
Analytics
Cyprus ICT Market
Analytics
Global Big Data Analytics in Telecom Market
Analytics
Cloud-Based Business Analytics Software Market
Analytics
Legal Analytics Market
Analytics
Data Visualization Market
Analytics
Cognitive Analytics Solutions Market