
 Text Analytics Market | 2026-2036
Text Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Text Analytics Market Intelligence
Capability gaps in GPU cluster ownership and proprietary training data is rotating competitive dynamics across the Text Analytics Market. IBM Corporation leverages its Watson infrastructure to sustain enterprise contracts in regulated industries. Microsoft Corporation anchors cloud-native text analytics through Azure AI services. Google LLC differentiates via transformer architecture leadership and multilingual model scale.
Text analytics encompasses computational methods for extracting structure, meaning, and patterns from unstructured textual data through natural language processing, statistical modeling, and machine learning algorithms operating on tokenized linguistic units. Its primary commercial purpose centers on transforming document corpora, conversational transcripts, and digital content into actionable intelligence for automated decision systems. Cloud-Based deployment captures the dominant revenue share as enterprises migrate legacy on-premises document processing pipelines to elastic compute environments. Natural Language Processing solutions command premium pricing due to transformer-based model complexity and specialized hardware requirements. Sentiment Analysis applications within financial services represent the fastest-expanding use case as algorithmic trading desks integrate real-time news and social media signal processing.
The EU AI Act imposes risk-tiered compliance obligations on automated text analysis systems processing personal or sensitive content, directly shaping product development roadmaps for vendors serving European enterprises. The FDA regulates natural language processing tools deployed in clinical decision support, requiring validation of text-derived diagnostic recommendations. ISO standards for artificial intelligence management systems provide baseline governance frameworks that procurement teams increasingly mandate in vendor assessments. Stakeholders must monitor regulatory divergence between jurisdictions as compliance fragmentation threatens to partition cloud service architectures and model training methodologies across territorial boundaries.
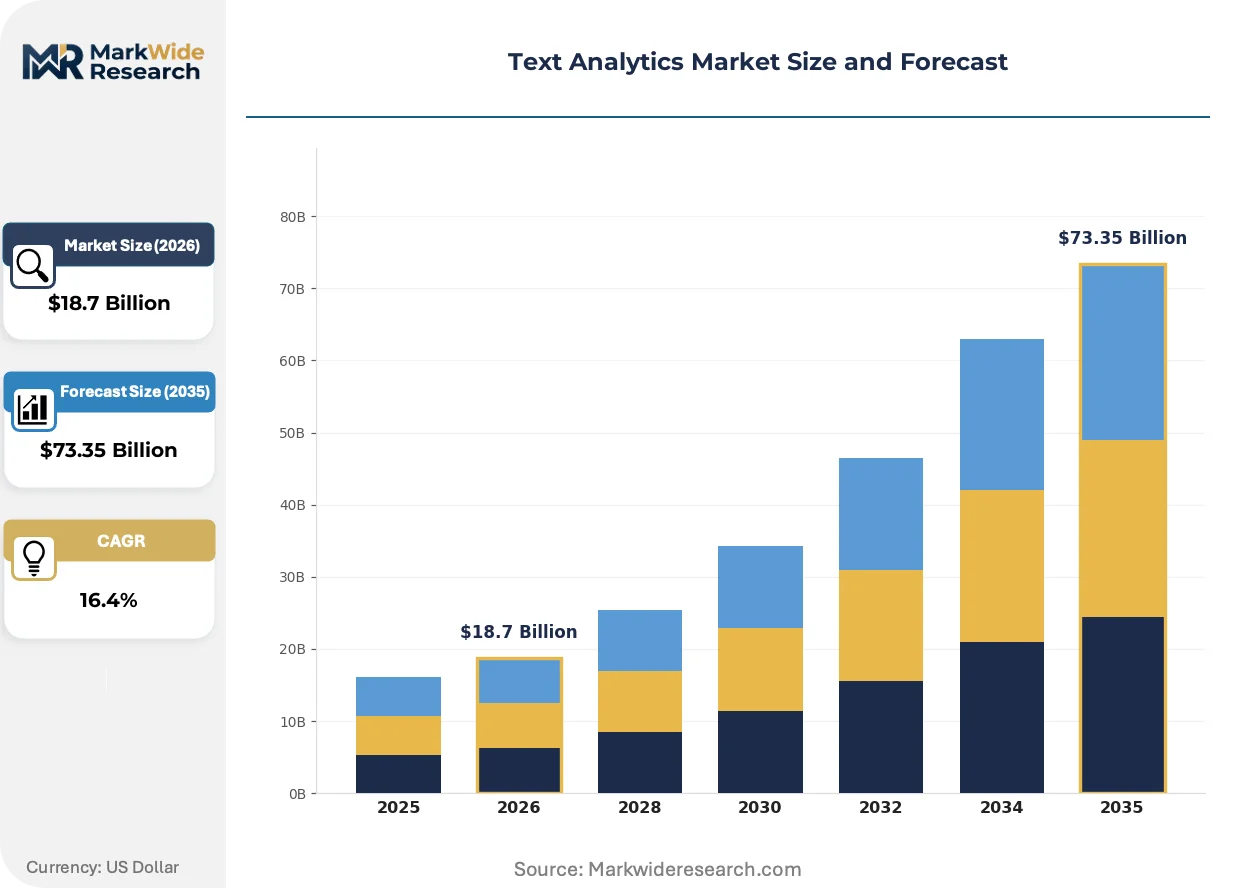
Market Dynamics
Transformer architectures and GPU cluster scarcity are compressing vendor margins while concentrating competitive advantage among hyperscale cloud operators with captive infrastructure.
Growth Catalysts
- EU AI Act risk-tiered obligations:Mandates for human oversight in high-risk text processing systems are creating certified solution demand across European financial services and healthcare procurement.
- Algorithmic trading desk integration:Real-time sentiment analysis pipelines processing news feeds and social media streams are becoming standard infrastructure for quantitative hedge funds and electronic market makers.
- Cloud infrastructure elasticity:Enterprise migration from on-premises document processing to elastic compute environments is unlocking scalable deployment of transformer-based NLP workloads.
Market Restraints
- NVIDIA GPU supply concentration:Training and inference dependency on a single semiconductor supplier creates procurement bottlenecks and price volatility for model development operations.
- Proprietary training data scarcity:High-quality labeled text corpora in specialized domains remain concentrated within incumbent technology firms and licensed media archives.
- Cross-border data localization:Divergent national requirements for text data residency are fragmenting cloud architectures and inflating compliance overhead for multinational deployments.
Strategic Opportunities
- India's BIS AI standardization:Emerging mandatory certification for automated text analysis systems creates first-mover advantage for vendors establishing local compliance infrastructure.
- Clinical decision support validation:FDA regulatory pathways for NLP-derived diagnostic recommendations open specialized healthcare applications with premium pricing and extended contract durations.
- Edge deployment convergence:Compression techniques enabling transformer inference on device-local hardware are unlocking manufacturing floor and field service applications previously blocked by latency constraints.
Industry Challenges
- Multilingual model engineering talent:Scarce expertise in low-resource language architectures and cross-lingual transfer learning limits product localization velocity for emerging market expansion.
- ISO 42001 AI management system certification:Extended audit timelines and documentation requirements are delaying enterprise sales cycles and inflating pre-revenue implementation costs.
- Legacy document pipeline integration:Mainframe-era content management systems in regulated industries resist API-based connectivity, forcing expensive middleware development for each major deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Text Analytics Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Sentiment Analysis, Topic Detection, Text Classification, Entity Recognition Deployment: Cloud-Based, On-Premises, Hybrid, SaaS End User: Healthcare Providers, Financial Services, Retailers, Market Researchers Solution: Natural Language Processing, Machine Learning, Data Mining, Predictive Analytics |
| Companies Covered | IBM Corporation, Microsoft Corporation, Google LLC, Amazon Web Services, Inc., SAP SE, SAS Institute Inc., Oracle Corporation, OpenText Corporation, Clarabridge, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Text Analytics Market Strategic Shifts & Innovations
Foundation model commoditization is compressing API pricing while specialized fine-tuning and retrieval-augmented generation architectures are creating new differentiation vectors for vertical applications.
Retrieval-augmented generation is decomposing the monolithic knowledge cutoff problem of large language models. Financial services compliance teams are adopting RAG pipelines at accelerated pace to ground regulatory interpretations in current source documents. This architecture is decomposing the competitive moat of massive pre-trained models by enabling smaller specialized systems to match enterprise accuracy requirements.
REACH substance screening obligations are mandating automated extraction of chemical hazard statements from safety data sheets and technical documentation. Industrial chemical manufacturers must deploy text analytics to validate compliance across multilingual supplier communications. The regulation most affects EU-based formulators and is driving procurement of multilingual named entity recognition systems with audit trail capabilities.
Consumption patterns among enterprise buyers are compressing from perpetual license models toward usage-metered API access with committed spend tiers. Systems integrators and value-added resellers are losing margin to direct cloud vendor relationships as procurement teams centralize vendor management. This shift is most visible in United States technology and financial services verticals where cloud-native procurement functions have mature FinOps capabilities.
Text Analytics Market Segmentation
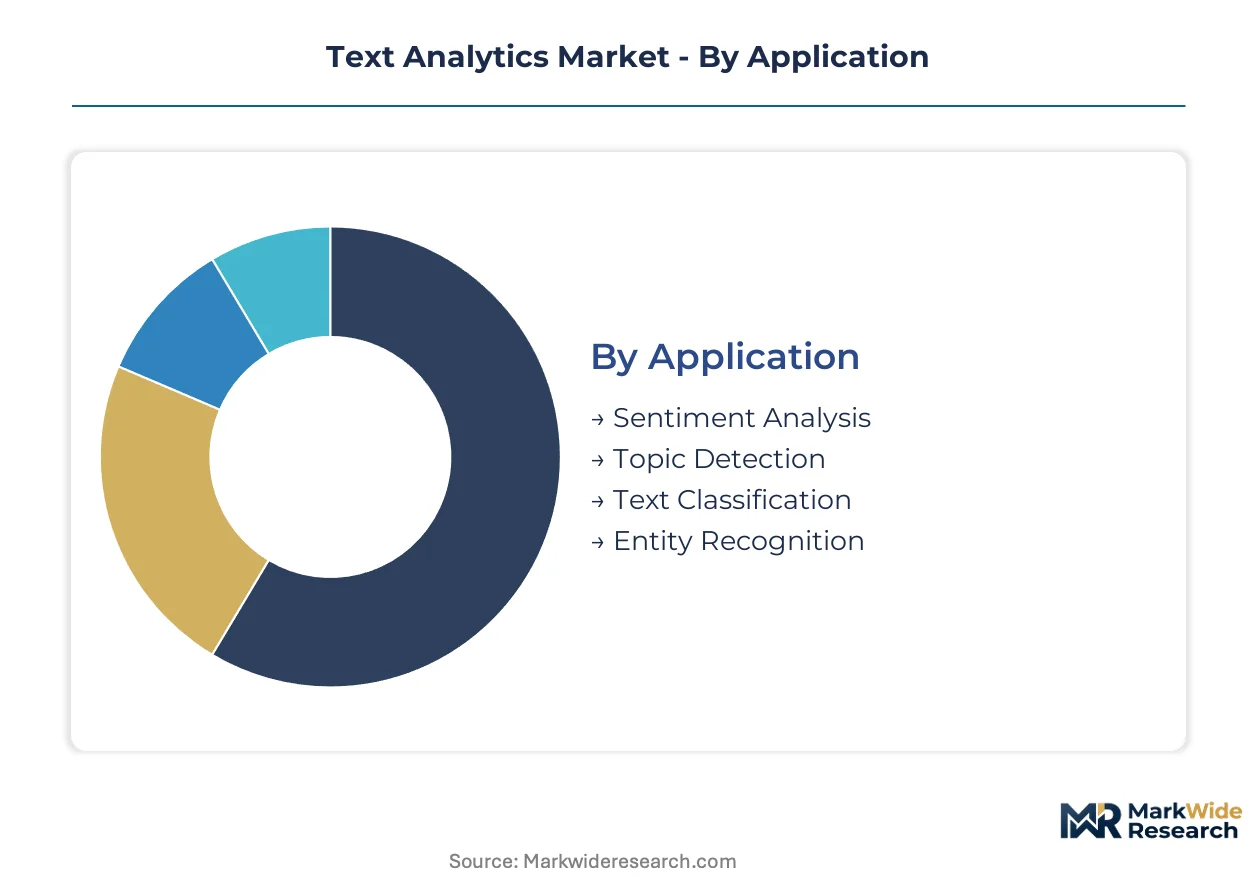
Text analytics procurement patterns diverge sharply across deployment architectures and solution types. Enterprise buyers weigh latency constraints against compliance overhead when selecting application-specific configurations.
Application:
Substitution pressure from unified AI platforms threatens standalone point solutions most acutely in commoditized detection tasks.
- Sentiment Analysis:Real-time polarity scoring and emotion detection algorithms process streaming text from social media, news feeds, and customer interactions. Quantitative hedge funds in the United States deploy these pipelines for algorithmic trading signals, driving premium pricing for sub-second latency infrastructure.
- Topic Detection:Unsupervised clustering and latent semantic indexing identify emergent themes across document corpora without predefined taxonomies. Market research agencies concentrate procurement here, pressured by client demands for rapid trend identification from unstructured survey verbatims.
- Text Classification:Supervised learning approaches categorize documents into predefined schema for routing and prioritization.
- Entity Recognition:Named entity extraction systems identify and disambiguate proper nouns, dates, and numerical expressions.
Sentiment Analysis retains volume leadership; Entity Recognition holds the steepest expansion curve.
Deployment:
Cost tier stratification separates elastic consumption models from capital-intensive fixed infrastructure commitments.
- Cloud-Based:Elastic compute environments host transformer-based workloads with metered API access and autoscaling clusters. Financial services firms in the United States dominate procurement, migrating legacy document processing to Azure and AWS infrastructure.
- SaaS:Pre-configured text analytics applications deliver immediate functionality through browser interfaces without model training requirements. Retailers favor this tier for rapid deployment of customer feedback analysis.
- On-Premises:Air-gapped hardware installations process sensitive text within organizational boundaries.
- Hybrid:Architectures split inference workloads between edge devices and central cloud resources.
Cloud-Based deployments capture the largest revenue share; SaaS offerings are climbing the fastest.
End User:
Application maturity varies dramatically across vertical compliance requirements and unstructured data volumes.
- Financial Services:Algorithmic trading desks and risk management functions deploy real-time sentiment pipelines for market intelligence. EU AI Act risk-tiered obligations are reshaping procurement specifications for automated text processing in Frankfurt and London.
- Healthcare Providers:Clinical documentation and decision support systems extract diagnostic insights from electronic health records. FDA validation requirements for NLP-derived recommendations create extended sales cycles but premium contract values.
- Retailers:Customer experience teams analyze feedback across channels for product development signals.
- Market Researchers:Survey analytics and social listening platforms process qualitative data at scale.
Financial Services commands the highest solution spend; Healthcare Providers are gaining share fastest.
Solution:
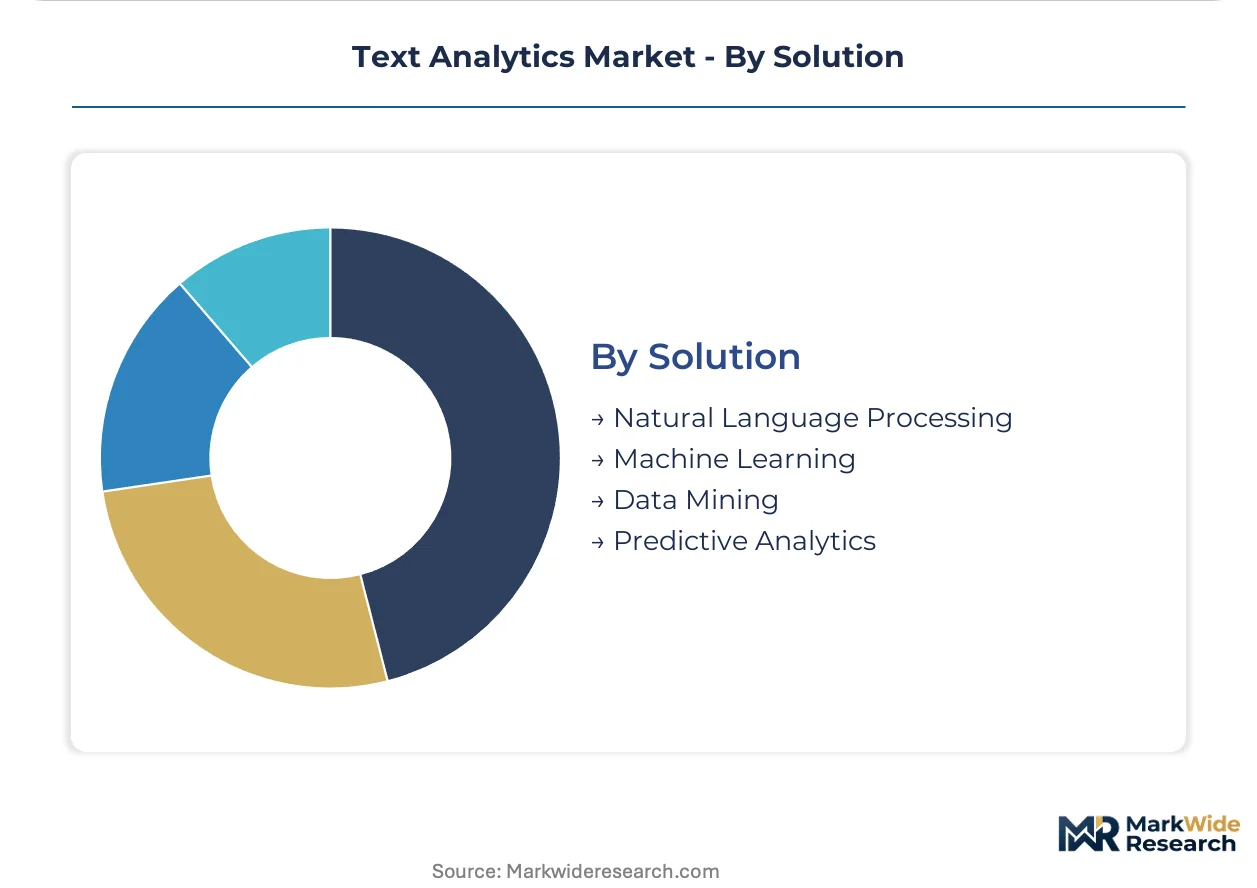
Supply concentration in GPU infrastructure and proprietary training data favors vertically integrated technology stacks.
- Natural Language Processing:Transformer architectures and large language models execute tokenization, parsing, and semantic analysis tasks. Specialized hardware requirements and scarce engineering talent sustain premium pricing for enterprise deployments.
- Machine Learning:Statistical classification and regression models underpin custom text analytics applications with domain-specific training data.
- Data Mining:Pattern discovery across unstructured document collections reveals latent relationships.
- Predictive Analytics:Forecasting models project future states from textual trend indicators.
Natural Language Processing dominates revenue concentration; Predictive Analytics shows the steepest trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States cloud infrastructure markets while European compliance overhead compresses vendor margins. German and French procurement teams absorb certification costs that American buyers avoid. Asian markets split between India's cost-driven BPO demand and Japan's precision-engineered enterprise requirements.
United States
Financial services firms in New York and Chicago deploy real-time sentiment pipelines for algorithmic trading signals. The SEC scrutinizes NLP-derived investment recommendations under existing securities fraud frameworks. Silicon Valley cloud operators anchor elastic compute pricing that shapes global procurement benchmarks.
Germany
Industrial chemical manufacturers in Ludwigshafen and Leverkusen automate REACH compliance documentation extraction. The EU AI Act mandates human oversight for high-risk text processing in Frankfurt banking operations. Bavarian automotive suppliers integrate multilingual entity recognition for supplier quality audits.
United Kingdom
London hedge funds consume premium latency infrastructure for news sentiment arbitrage. The Financial Conduct Authority examines automated text analysis under market abuse surveillance guidelines. Edinburgh fintech clusters specialize in regulatory technology applications for document classification.
India
Bangalore IT services firms and Mumbai financial institutions drive demand for cost-optimized NLP APIs. BIS AI standardization creates mandatory certification pathways for automated text analysis vendors. Hyderabad's pharmaceutical outsourcing hubs deploy clinical document processing for FDA submission support.
Japan
Tokyo trading houses and Osaka manufacturers require precision-tuned Japanese language models for contract analysis. METI guidelines shape AI procurement standards for enterprise text processing systems. Nagoya automotive engineering clusters adopt edge-deployed transformer inference for quality control documentation.
Text Analytics Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the Text Analytics Market. Hyperscale cloud operators command transformer infrastructure and proprietary training data while specialized vendors compete on domain-specific fine-tuning. The structure stratifies into three tiers: full-stack platform providers, vertical application specialists, and API-first infrastructure vendors. Competitive moves center on retrieval-augmented generation partnerships and edge deployment compression licensing.
Within the full-stack platform tier, IBM Corporation, Microsoft Corporation, and Google LLC anchor enterprise procurement decisions across regulated industries. These entities exemplify divergent strategic positioning: IBM leverages established Watson infrastructure for compliance-heavy contracts, Microsoft anchors cloud-native delivery through Azure AI services, and Google differentiates via transformer architecture scale and multilingual model breadth. Their collective presence shapes pricing benchmarks and feature roadmaps that smaller vendors must match or circumvent through specialization.
| Leading Market Players |
|---|
| IBM Corporation |
| Microsoft Corporation |
| Google LLC |
| Amazon Web Services, Inc. |
| SAP SE |
| SAS Institute Inc. |
| Oracle Corporation |
| OpenText Corporation |
| Clarabridge, Inc. |
| Others |
Cost & Logistics Intelligence
GPU cluster utilization rates above eighty percent anchor cost floors for transformer-based NLP services, concentrating pricing power among hyperscale operators with captive infrastructure while compressing margins for vendors leasing compute from third-party cloud providers.
Pricing Analysis
The customization-premium spread separates standard API-tier access from configured-to-order deployments with fine-tuned models and dedicated inference endpoints. Subscription-SaaS tiered pricing dominates enterprise procurement, with differentiation driven by ISO 42001 certification grade and vertical integration depth into proprietary training data. Cost compression in mid-market SaaS tiers is intensifying because foundation model commoditization erodes feature premiums. Retailers exhibit highest price sensitivity, while quantitative hedge funds in the United States absorb premium latency infrastructure costs without negotiation.
Supply Chain Analysis
Container availability constraints on the Shanghai-Los Angeles trade lane inflate lead times for NVIDIA H100 GPU shipments, forcing vendors to pre-position hardware in regional cloud availability zones. Supply concentrates in Taiwan for advanced semiconductor fabrication, the United States for cloud infrastructure orchestration, and India for cost-optimized annotation labor. Raw material dependencies include high-bandwidth memory modules from South Korea, specialized cooling systems from Germany, and rare earth elements for permanent magnet motors in liquid-cooled racks. Single-source vulnerability around NVIDIA GPU supply creates procurement bottlenecks. Distribution runs through direct hyperscaler relationships and value-added reseller channels serving regulated industries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Text analytics demand cycles with enterprise cloud migration waves and regulatory compliance deadlines, positioning the current expansion as a recovery phase following foundation model commoditization shocks.
For Market Incumbents: Shield enterprise contract renewal rates by embedding retrieval-augmented generation capabilities into existing Watson and Azure AI deployments before specialized vendors achieve feature parity. Accelerate ISO 42001 certification investment to create compliance friction against emerging entrants lacking audit infrastructure. Vertical integration into proprietary financial and healthcare training data reinforces moats against API-first competitors.
For New Entrants and Emerging Players: Differentiate on edge-deployed transformer compression for manufacturing floor applications where latency constraints block hyperscaler solutions. Target India's BIS AI certification window as the most penetrable geography, where mandatory compliance infrastructure creates first-mover advantage before incumbents localize operations. Pursue channel partnerships with systems integrators serving Japan's precision-engineered enterprise requirements.
For Investors and Strategic Acquirers: Domain-specific fine-tuning shops with FDA-validated clinical NLP pipelines represent the most attractive acquisition archetype, combining regulatory barriers with recurring revenue from extended healthcare contracts. Long-term viability hinges on model architecture portability across cloud providers rather than single-platform dependency. Watch FDA approval velocity for NLP-derived diagnostic recommendations as the inflection signal for healthcare segment premiumization.
| Strategic Initiative | Industry Significance |
|---|---|
| Retrieval-Augmented Generation Integration | Financial services compliance teams at Frankfurt banks adopt RAG to ground regulatory interpretations in current source documents. |
| Edge Deployment Compression Licensing | Nagoya automotive engineering clusters deploy on-device transformer inference for quality control documentation analysis. |
| ISO 42001 Certification Investment | European procurement teams increasingly mandate AI management system audits in vendor assessments under EU AI Act pressure. |
| Proprietary Training Data Acquisition | Licensed media archives and specialized domain corpora create differentiation moats against foundation model commoditization. |
| Multilingual Model Localization | Hyderabad pharmaceutical outsourcing hubs require clinical document processing capabilities for FDA submission support in English and regional languages. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with natural language processing engineering leads, cloud procurement officers at financial services firms, regulatory compliance directors in healthcare systems, and channel partners serving enterprise deployments. Secondary validation drew from SEC filings of hyperscale cloud operators, EU AI Act implementation guidance documents, FDA 510(k) clearance databases for NLP clinical tools, and ISO 42001 certification registries. Bottom-up segment sizing triangulated against top-down infrastructure spend estimates from hyperscaler capex disclosures.
Across the analysis window, the forecasting framework modeled deployment architecture, solution type, end-user vertical, and regional regulatory cluster as primary segmentation dimensions. CAGRs were derived from elasticity-adjusted adoption curves calibrated to historical cloud migration patterns and compliance deadline clustering. Industry-specific inputs included GPU cluster availability constraints, BIS AI standardization timelines in India, and REACH substance screening automation mandates affecting EU chemical manufacturers.
The analysis sits within stated boundaries; outcomes outside sustained cloud infrastructure investment levels, stable semiconductor supply chains, or coherent regulatory enforcement across jurisdictions would require recalibration. Forecasts reflect assumptions around transformer architecture persistence and enterprise procurement centralization trends. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
India Geospatial Analytics Market
Analytics
India Contact Center Analytics Market
Analytics
Video Analytics Market
Analytics
North America HR Analytics Market
Analytics
Data Analysis Tools Market
Analytics
Japan Geospatial Analytics Market
Analytics
Network Analysis Module (NAM) Market
Analytics
Europe Crowd Analytics Market
Analytics
Geospatial Analytics Market
Analytics
Global Social Intelligence Market
Analytics
RAN Analytics and Monitoring Market
Analytics
Global Clickstream Analytics Market
Analytics
Business Intelligence (BI) Market
Analytics
Greece ICT Market
Analytics
North America Location Analytics Market
Analytics
Data Analytics Market