
 Mobile Application Stores Market | 2026-2036
Mobile Application Stores Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Application Stores Market Foresight
Subscription-based feature tiers within app ecosystems is decoupling monetization from one-time downloads. Apple Inc. leverages its closed-platform architecture to sustain premium service margins. Google LLC anchors the open Android ecosystem through Play Store distribution and developer tooling dominance.
Mobile application stores function as digital distribution platforms that aggregate, validate, and deliver software binaries to end-user devices through cryptographic signing and sandboxed execution environments. They serve as the primary commercial gateway connecting developers to consumers in the mobile software economy. The freemium payment model captures the largest user base while subscription services generate the most predictable revenue streams. Android platform type leads in absolute download volume globally, though iOS commands disproportionate monetization per user.
The EU Digital Markets Act imposes interoperability and sideloading obligations on designated gatekeepers, reshaping platform control across Europe. The FTC and Department of Justice in the United States pursue parallel antitrust actions targeting app store fee structures and payment system exclusivity. India's MeitY enforces data localization and pre-installed app transparency rules that affect store operations. Stakeholders must monitor whether regulatory fragmentation forces operational divergence between open and closed platform strategies.
Market Dynamics
The EU Digital Markets Act and its Asia-Pacific analogues are dismantling platform exclusivity architectures, forcing gatekeepers to open payment rails and distribution channels that were previously sealed.
Growth Catalysts
- India's Developer Ecosystem Maturation:Smartphone penetration in tier-2 and tier-3 cities under TRAI's digital inclusion mandates is creating first-time app consumers at scale. Local developer communities are proliferating regional language applications.
- EU Digital Markets Act Interoperability Mandates:Designated gatekeepers must permit sideloading and alternative payment systems, reducing friction for developer onboarding across European markets.
- Enterprise Mobile Workforce Solutions:North American corporations are deploying proprietary app distribution channels for field service, inventory management, and secure communications.
Market Restraints
- Platform Fee Compression Resistance:Apple's closed-platform architecture sustains 30% commission structures that developers cannot circumvent without regulatory intervention.
- Data Localization Infrastructure Costs:India's MeitY mandates require server deployment within national borders, elevating operational expenditure for foreign platform operators.
- Fragmented Regulatory Compliance:The FTC and Department of Justice pursue parallel antitrust tracks that diverge from EU enforcement timelines, forcing multi-jurisdictional legal expenditure.
Strategic Opportunities
- Super-App Convergence in Southeast Asia:Messaging, payments, and mini-program ecosystems are integrating within single platforms, creating stickier user retention models than standalone distribution.
- Subscription Tier Architectures:Freemium-to-premium conversion pathways are decoupling monetization from download velocity, generating predictable recurring revenue streams.
- B2B Enterprise App Channels:Mobile Device Management vendors are white-labeling private app stores for healthcare, logistics, and financial services with enhanced cryptographic validation.
Industry Challenges
- Antitrust Litigation Timeline Uncertainty:Protracted court proceedings in US federal districts delay strategic planning for fee structure modifications.
- Legacy Payment System Integration:Alternative in-app purchase rails must interoperate with established banking infrastructure, creating technical debt for platform migrations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Application Stores Market |
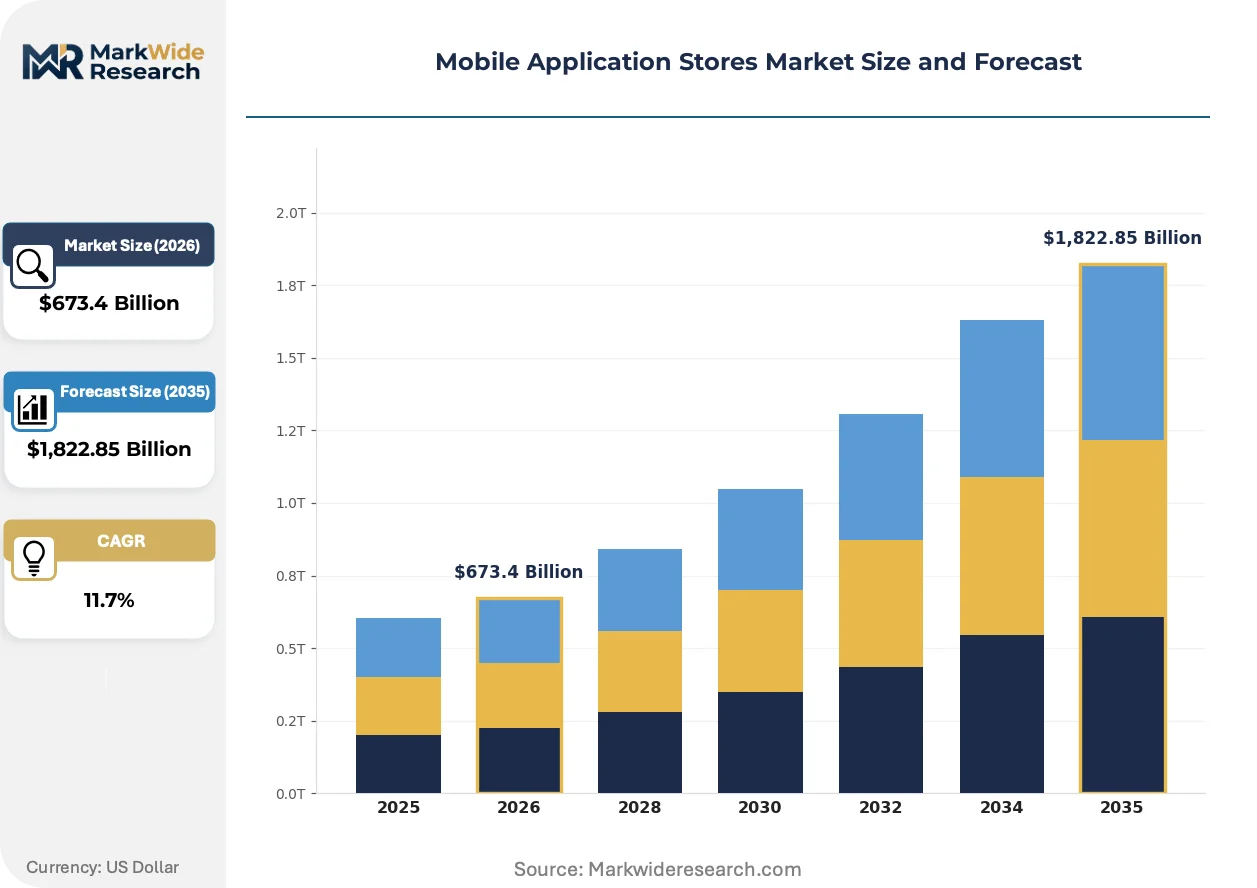
| Market Size in 2026 | $673.4 Billion |
| Market Size in 2035 | $1,822.85 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: App Distribution, App Monetization, In-App Advertising, User Acquisition Platform Type: iOS, Android, Windows, Others Payment Model: Free, Freemium, Subscription, One-Time Purchase End User: Developers, Brands, Consumers, Enterprises |
| Companies Covered | Apple Inc., Google LLC, Huawei Technologies, Tencent Holdings, Xiaomi Corporation, Oppo, Vivo, Amazon.com, Samsung Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Application Stores Market Shifts & Advancements
Platform operators are reconstructing revenue models around recurring service fees rather than transaction commissions, while regulatory frameworks force architectural openness that threatens historical control points.
Progressive Web Applications are expanding into native-app functionality through service workers and offline caching capabilities. Enterprise IT departments in manufacturing and logistics are adopting PWAs to bypass store approval delays. This technology is expanding into territory previously monopolized by platform-native binaries, compressing gatekeeper leverage over distribution.
REACH chemical compliance and the EU AI Act are imposing algorithmic transparency obligations on recommendation engines within app stores. Operators must document ranking methodologies and provide audit trails for automated curation decisions. European developers gain procedural recourse against opaque demotion practices, shifting power toward creator coalitions.
Consumption patterns among Gen Z and Alpha cohorts favor bite-sized, modular app experiences over comprehensive suites. Short-form video platforms in Brazil and Indonesia are spawning mini-app ecosystems where users complete transactions without leaving the host environment. This behavior fragments discovery away from centralized store interfaces toward social and entertainment platforms.
Mobile Application Stores Market Segmentation
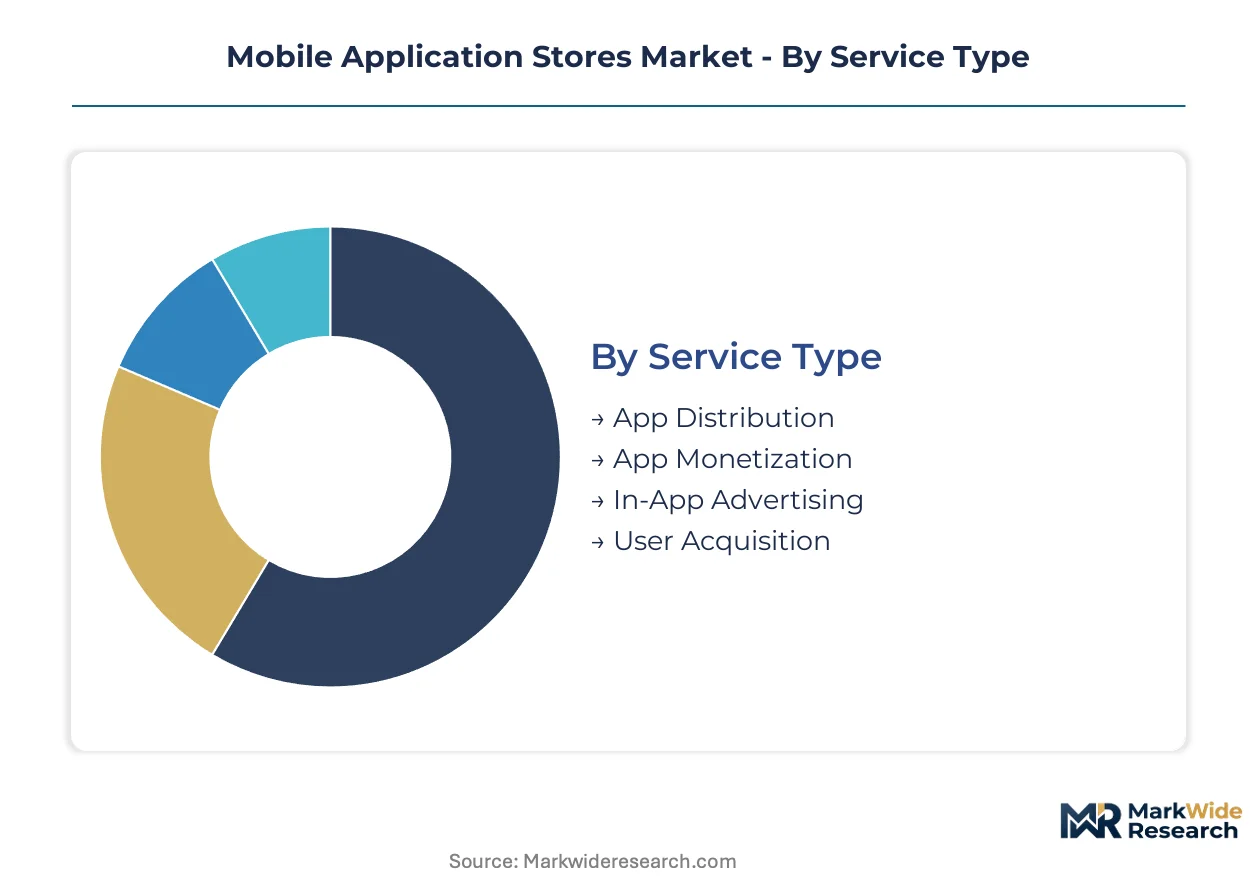
Segmentation in mobile application stores reveals how platform operators extract value across divergent customer workflows. Each dimension—service delivery, operating system, payment mechanics, and user identity—carries distinct regulatory exposure and margin architecture.
Service Type:
App store certification burdens cluster heavily around distribution and monetization services, with advertising and acquisition facing lighter algorithmic transparency obligations under EU AI Act and comparable Asia-Pacific frameworks.
- App Distribution:Core infrastructure for binary validation, cryptographic signing, and sandboxed delivery. Developer demand concentrates in India as TRAI's digital inclusion mandates expand smartphone penetration into tier-2 and tier-3 cities. EU Digital Markets Act interoperability mandates are forcing architectural openness that threatens historical gatekeeper control over this segment.
- App Monetization:Payment processing, subscription management, and revenue analytics. Enterprise adoption in North America drives demand for proprietary distribution channels with enhanced cryptographic validation. Platform fee compression resistance from Apple sustains 30% commission structures that developers cannot circumvent without regulatory intervention.
- In-App Advertising:Programmatic ad serving and attribution within native applications. REACH chemical compliance and algorithmic transparency obligations impose documentation requirements on recommendation engines.
- User Acquisition:Paid install campaigns, app store optimization, and retargeting tools. Gen Z and Alpha cohorts favor bite-sized modular experiences that fragment discovery away from centralized store interfaces.
App Distribution sits at the top of the volume ranking, with App Monetization climbing the fastest as subscription tier architectures decouple revenue from download velocity.
Platform Type:
Cost tier differentiation separates closed-platform premium margins from open-ecosystem volume plays, with regulatory fragmentation forcing operational divergence between strategies.
- iOS:Closed architecture with proprietary App Store distribution and strict binary validation. FTC and Department of Justice antitrust actions target fee structures and payment system exclusivity in US federal districts. Disproportionate monetization per user sustains premium service margins despite lower absolute download volume.
- Android:Open-source foundation with Play Store distribution dominance and developer tooling leadership. Google's anchoring of this ecosystem through distribution and tooling faces EU sideloading mandates that reduce friction for alternative channels.
- Windows:Desktop-mobile convergence platform with UWP and Win32 application support. Enterprise IT departments in manufacturing adopt progressive web applications to bypass store approval delays.
- Others:Emerging proprietary platforms including HarmonyOS, Tizen, and region-specific operating systems. India's MeitY data localization requirements elevate operational expenditure for foreign operators serving these alternatives.
Android commands the steepest expansion trajectory in absolute download volume, with iOS gaining share fastest in enterprise segments requiring enhanced security validation.
Payment Model:
Customer type and maturity determine which payment mechanics dominate, with enterprise procurement favoring predictable subscription commitments over transactional freemium conversions.
- Free:Ad-supported distribution with zero upfront cost. Brazil and Indonesia short-form video platforms spawn mini-app ecosystems where transactions complete without leaving host environments.
- Freemium:Tiered feature access with conversion pathways to premium functionality. Captures the largest user base while subscription services generate more predictable revenue streams.
- Subscription:Recurring revenue through monthly or annual service fees. North American corporations deploy these models for field service and secure communications applications.
- One-Time Purchase:Perpetual licensing for premium applications. Legacy payment system integration creates technical debt as alternative in-app purchase rails must interoperate with established banking infrastructure.
Freemium sits at the top of the volume ranking, with Subscription climbing the fastest as platform operators reconstruct revenue models around recurring service fees.
End User:
Supply concentration in developer tooling and enterprise mobility management shapes how each user category accesses platform services.
- Developers:Binary publishers seeking distribution reach and monetization infrastructure. Local developer communities in India proliferate regional language applications under digital inclusion mandates.
- Brands:Consumer-facing companies deploying proprietary applications for engagement and commerce. Super-app convergence in Southeast Asia integrates messaging, payments, and mini-program ecosystems within single platforms.
- Consumers:End-users discovering, installing, and transacting within mobile applications. Consumption patterns favor modular experiences over comprehensive suites.
- Enterprises:Organizations deploying private app stores for workforce mobility. Mobile Device Management vendors white-label distribution channels for healthcare, logistics, and financial services with enhanced cryptographic validation.
Consumers sit at the top of the volume ranking, with Enterprises climbing the fastest as B2B channels expand beyond traditional store boundaries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's developer ecosystem expansion contrasts with regulatory friction in the European Union, where interoperability mandates are dismantling historical platform control. Platform operators navigate divergent compliance architectures across these jurisdictions. The United States maintains antitrust pressure through federal enforcement actions.
United States
Enterprise mobile workforce solutions drive demand from North American corporations deploying proprietary distribution channels. The FTC and Department of Justice pursue parallel antitrust tracks targeting app store fee structures and payment system exclusivity. Seattle and San Francisco host concentrated platform engineering operations where alternative payment rail integration is accelerating.
Germany
Industrial manufacturing and automotive sectors generate enterprise app consumption for field service and inventory management applications. The EU Digital Markets Act imposes sideloading and interoperability obligations on designated gatekeepers operating across German markets. Munich and Berlin anchor developer communities adapting to algorithmic transparency requirements under the EU AI Act.
India
Smartphone penetration in tier-2 and tier-3 cities under TRAI's digital inclusion mandates creates first-time app consumers at scale. MeitY enforces data localization and pre-installed app transparency rules that elevate operational expenditure for foreign platform operators. Bengaluru and Hyderabad concentrate regional language application development from proliferating local developer communities.
China
Super-app convergence integrates messaging, payments, and mini-program ecosystems within single platforms, fragmenting discovery away from centralized store interfaces. MIIT and SAMR regulate app distribution with emphasis on data security and algorithmic recommendation transparency. Shenzhen and Beijing host dominant domestic platform operators expanding HarmonyOS distribution infrastructure.
Brazil
Short-form video platforms spawn mini-app ecosystems where Gen Z and Alpha cohorts complete transactions without leaving host environments. ANVISA and central bank regulations govern financial services embedded within super-app architectures. São Paulo anchors Latin America's largest developer community adapting to modular consumption preferences.
Mobile Application Stores Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with closed-platform operators commanding premium margins while open-ecosystem players compete on distribution volume. The vendor base concentrates around three strategic archetypes: gatekeeper platforms with proprietary hardware-software integration, super-app operators with embedded mini-program ecosystems, and enterprise-focused private store providers. Dominant competitive moves include strategic partnerships with mobile device management vendors and portfolio diversification into subscription-based service tiers.
Among hardware-integrated platform operators, Apple Inc., Google LLC, and Huawei Technologies occupy positions across the closed-to-open architecture spectrum. Apple Inc. exemplifies the premium-tier gatekeeper archetype through its proprietary App Store distribution and strict binary validation protocols. Google LLC anchors the open-ecosystem volume play through Play Store distribution dominance and developer tooling leadership. Huawei Technologies represents the emerging alternative platform vector, expanding HarmonyOS distribution infrastructure amid geopolitical fragmentation of mobile operating systems.
| Leading Market Players |
|---|
| Apple Inc. |
| Google LLC |
| Huawei Technologies |
| Tencent Holdings |
| Xiaomi Corporation |
| Oppo |
| Vivo |
| Amazon.com |
| Samsung Electronics |
| Others |
Supply & Pricing Matrix
Platform engineering talent concentration in Bengaluru and Hyderabad generates labor-cost differentials that widen pricing-tier spreads between premium closed-platform services and economy-tier open-ecosystem alternatives. Indian developer communities proliferating regional language applications compress entry-level pricing while EU-mandated interoperability investments elevate compliance-layer premiums.
Pricing Analysis
Capacity additions in Southeast Asia are reshaping price floors for super-app mini-program ecosystems, forcing standalone distribution platforms toward subscription-tier architectures to preserve margins. Three-tier pricing structure across premium, standard, and economy levels segments by cryptographic validation depth and developer tooling sophistication. Price differentiation rests on certification grade for enterprise security compliance and volume scale for consumer-facing freemium conversions. Pricing pressure stems from Progressive Web Application adoption in manufacturing and logistics sectors that bypass native store approval delays. Enterprise procurement teams demonstrate lowest price sensitivity due to mandatory compliance requirements, while independent developers in tier-2 Indian cities exhibit highest elasticity.
Supply Chain Analysis
Binary validation and cryptographic signing certification gates concentrate supply chain control among platform operators with proprietary hardware-software integration. Geographic supply concentrates in the United States for enterprise Mobile Device Management infrastructure, China for super-app distribution ecosystems, and India for regional language application development. Raw material dependencies encompass cloud compute capacity for app store hosting, semiconductor fabrication for device compatibility testing, and payment rail infrastructure for monetization services. Supply chain risk centers on single-source vulnerability for Apple's proprietary App Store validation protocols. Distribution runs through OEM pre-installation agreements, direct-to-device over-the-air updates, and enterprise white-label private store deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in mobile application stores hinges on subscription-tier conversion pathways that decouple revenue from download velocity, with cloud infrastructure cost optimization enabling service-tier premiums.
For Market Incumbents: Lock in enterprise Mobile Device Management partnerships to secure proprietary distribution channels for healthcare and financial services before regulatory fragmentation forces architectural openness. Deepen backward integration into payment rail infrastructure to defend against EU-mandated alternative in-app purchase systems. Prioritize certification investment for algorithmic transparency documentation under EU AI Act obligations to preempt developer coalition challenges. For New Entrants and Emerging Players: Launch via super-app mini-program ecosystems in Brazil and Indonesia where Gen Z consumption patterns favor modular experiences over comprehensive native applications. Target tier-2 and tier-3 Indian cities under TRAI digital inclusion mandates where first-time smartphone adoption outpaces established platform penetration. Pursue white-label private store deployment for North American logistics and field service enterprises as the most penetrable B2B segment. For Investors and Strategic Acquirers: Mobile Device Management vendors with cryptographic validation capabilities are the most active acquirer category in this space, consolidating enterprise-focused distribution channels. Long-term viability favors platform operators with demonstrated interoperability compliance across EU, US, and Asia-Pacific regulatory frameworks. Monitor antitrust litigation timeline convergence between FTC and Department of Justice proceedings as the critical inflection signal for fee structure modification windows.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Super-app convergence in Southeast Asia embeds payment and messaging ecosystems within single interfaces. |
| Strategic Partnership | Mobile Device Management vendors white-label private stores for healthcare compliance requirements. |
| Acquisition of Specialist Firm | Cryptographic validation capabilities consolidate within enterprise-focused distribution channel providers. |
| Geographic Expansion | Indian tier-2 and tier-3 cities under TRAI mandates create first-time app consumer scale. |
| Product Launch | Progressive Web Applications bypass native store approval delays in manufacturing and logistics sectors. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with platform engineering directors, enterprise IT procurement officers, app store monetization leads, and mobile developer community organizers with secondary validation against SEC filings, App Annie usage disclosures, hyperscaler capex reports, and EU regulatory submission databases. Bottom-up developer ecosystem sizing and top-down platform revenue triangulation anchored volume estimates.
Segment-weighting applied service type, platform architecture, payment model, and end-user category dimensions across the projection horizon. CAGRs derived from installed base growth curves, monetization rate trajectories, and regulatory compliance cost absorption patterns. Forecast inputs encompassed smartphone penetration trajectories under national digital inclusion mandates and enterprise mobility management adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU Digital Markets Act enforcement or geopolitical fragmentation of mobile operating systems. Projections reflect documented assumptions on developer fee tolerance thresholds and alternative distribution channel viability. A model refresh is warranted upon material change in antitrust litigation timeline convergence or super-app mini-program ecosystem expansion velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Automation Software Market
Software & Services
PCB Layout Software Market
Software & Services
Global Organizational Change Management Software Market
Software & Services
BFSI Software Market
Software & Services
Global Linux Operating System Market
Software & Services
Global Corporate Wellness Software Market
Software & Services
Car-Hailing Software Market
Software & Services
Codeless Testing Market
Software & Services
Point of Sale (Pos) Software Market
Software & Services
Email Optimization Software Market
Software & Services
CAM Software Market
Software & Services
Global Performance Appraisal Software Market
Software & Services
Content Curation Software Market
Software & Services
3D Animation Production Software Market
Software & Services
Harbor and Marina Management Software Market
Software & Services
Global Server Management Software Market