
 Sales Intelligence Market | 2026-2036
Sales Intelligence Market Size, Share, and Industry Trends Forecast 2026-2036
Sales Intelligence Market Intelligence
A persistent shortage of data-literate sales operations talent is unwinding traditional go-to-market execution across mid-market and enterprise teams. Salesforce leverages its platform ecosystem to anchor multi-product contracts spanning CRM and intelligence layers. ZoomInfo sustains dominance in North American contact data through proprietary sourcing infrastructure and continuous validation pipelines. HubSpot competes by bundling lightweight intelligence into its inbound marketing suite, lowering adoption barriers for smaller revenue organizations.
Sales intelligence encompasses the collection, enrichment, and analysis of prospect and customer data to prioritize outreach, forecast pipeline velocity, and optimize account engagement workflows; core technical parameters include real-time data freshness SLAs, match rates exceeding industry baselines for identity resolution, and API latency thresholds under milliseconds for CRM synchronization. Cloud-based deployment leads solution architecture due to elastic scalability and reduced infrastructure overhead, while lead generation and competitive intelligence solutions capture expanding margin pools as buyers demand predictive intent signals beyond static firmographics. Account-based marketing use cases are maturing fastest as orchestration platforms integrate advertising, sales engagement, and analytics into unified execution layers.
FDA oversight of software-as-medical-device claims intersects with sales intelligence only at the margins, though FTC Section 5 enforcement against deceptive data practices directly constrains how providers represent data provenance and accuracy to commercial buyers; GDPR and the EU AI Act collectively reshape European deployment architectures by mandating explainability for automated scoring and restricting cross-border data transfers without adequacy mechanisms. Stakeholders must monitor emerging state-level privacy legislation in the United States, as fragmented compliance obligations threaten to fragment product roadmaps and inflate operational overhead for vendors serving multi-jurisdictional accounts.
Market Dynamics
Real-time intent signal processing is compressing sales cycles and forcing vendors to rebuild data pipelines around millisecond latency requirements rather than batch-update architectures.
Growth Catalysts
- EU AI Act compliance frameworks:Financial services providers in Europe are accelerating procurement of explainable scoring tools to meet automated decision-making transparency mandates before enforcement deadlines.
- Account-based marketing orchestration:Enterprise SaaS buyers in the United States are consolidating vendor relationships around platforms that unify advertising, engagement, and analytics layers.
- Contact data freshness SLAs:Real-time validation infrastructure is expanding addressable market coverage for mid-market teams previously locked out of premium intelligence tiers.
Market Restraints
- Cross-border data transfer restrictions:GDPR adequacy mechanism uncertainties are fragmenting European deployment architectures and inflating vendor operational overhead.
- Proprietary sourcing infrastructure concentration:North American contact data markets exhibit supply-side consolidation around vertically integrated validation pipeline operators.
- API latency threshold technical limitations:Sub-millisecond CRM synchronization requirements demand specialized edge computing investments that exclude smaller regional competitors.
Strategic Opportunities
- State-level privacy legislation fragmentation:Emerging patchwork compliance obligations in the United States create openings for modular architecture vendors serving multi-jurisdictional enterprise accounts.
- Predictive intent signal convergence:Integration of first-party behavioral data with third-party firmographic enrichment is unlocking new pricing power in competitive intelligence solutions.
- India PLI scheme digital infrastructure:Government incentives for cloud and data center expansion are lowering entry barriers for sales intelligence localization in South Asian markets.
Industry Challenges
- Data-literate sales operations talent scarcity:Mid-market and enterprise teams face execution gaps as traditional go-to-market playbooks require statistical competency most organizations lack.
- Legacy CRM integration complexity:Hybrid environments combining modern intelligence layers with decades-old customer databases generate synchronization failures and data quality degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sales Intelligence Market |
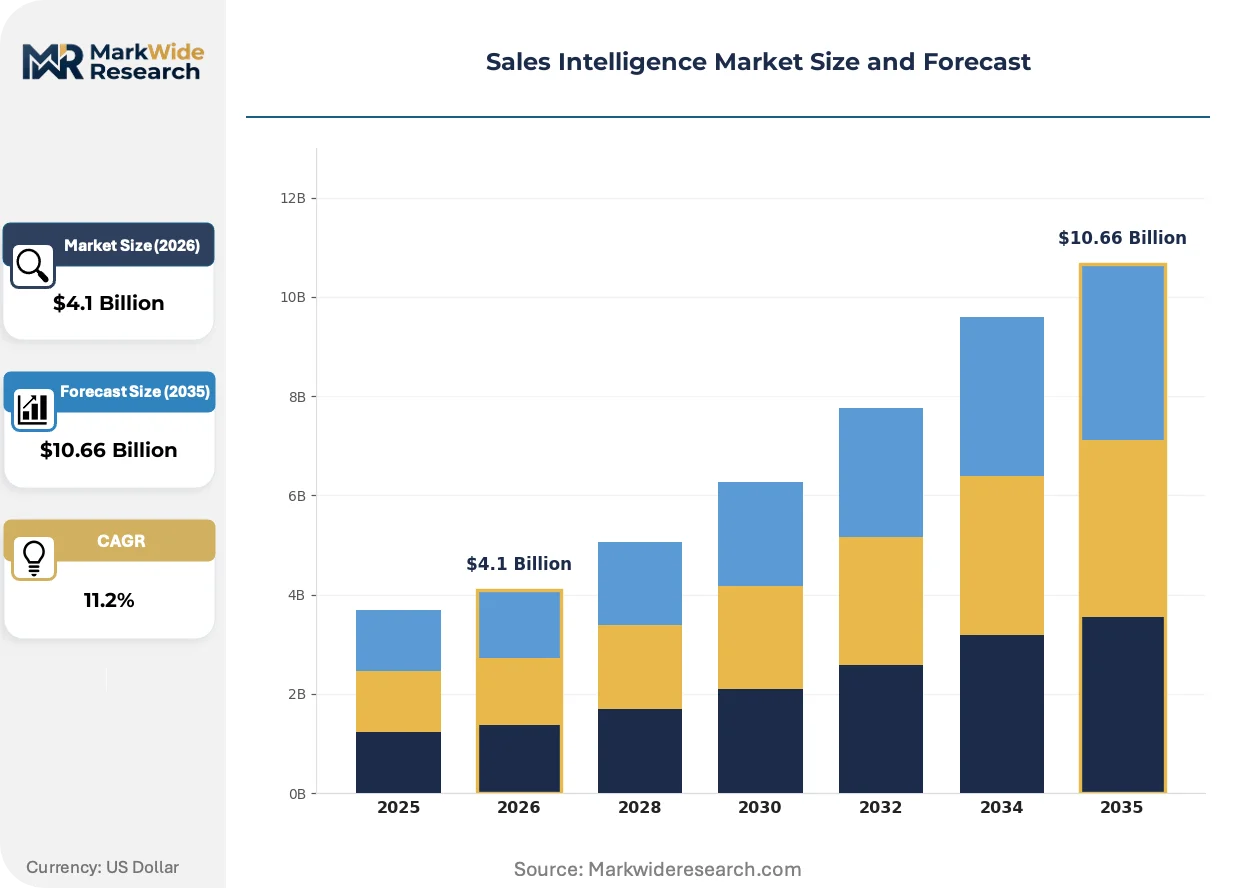
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $10.66 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, SaaS, Hosted Solution: Lead Generation, Contact Data Management, Customer Insights, Sales Forecasting, Competitive Intelligence Use Case: Market Penetration, Account-Based Marketing, Customer Retention, Cross-Selling & Upselling, Sales Performance Management End User: Technology Vendors, Financial Services Providers, Manufacturing Firms, Telecommunications Operators, Consumer Goods Companies |
| Companies Covered | ZoomInfo, Salesforce, HubSpot, LinkedIn, Dun & Bradstreet, Oracle, Clearbit, Demandbase, HG Insights, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sales Intelligence Market Strategic Shifts & Innovations
Artificial intelligence is rewriting competitive rules across data enrichment, scoring algorithms, and workflow automation, compressing the gap between signal capture and commercial action.
Real-time identity resolution engines are supplanting batch-processed firmographic databases in enterprise technology stacks. Mid-market SaaS buyers are adopting these systems within eighteen-month replacement cycles. The shift is compressing vendor switching costs and rewarding continuous validation infrastructure over static data licensing models.
The EU AI Act's explainability requirements for automated customer scoring are forcing architectural redesigns across European deployments. Providers must now embed interpretability layers into algorithmic decision paths previously treated as proprietary black boxes. Financial services and insurance verticals face the steepest compliance timelines and are pre-emptively restructuring vendor contracts to allocate liability.
Buyer procurement committees are consolidating around outcome-based intelligence contracts that tie fees to pipeline contribution metrics rather than seat-based subscriptions. Traditional data vendors with fixed pricing models are losing RFP participation to performance-aligned competitors. This pattern is most pronounced in United States enterprise SaaS segments where CFO scrutiny of martech spend has intensified.
Sales Intelligence Market Segmentation
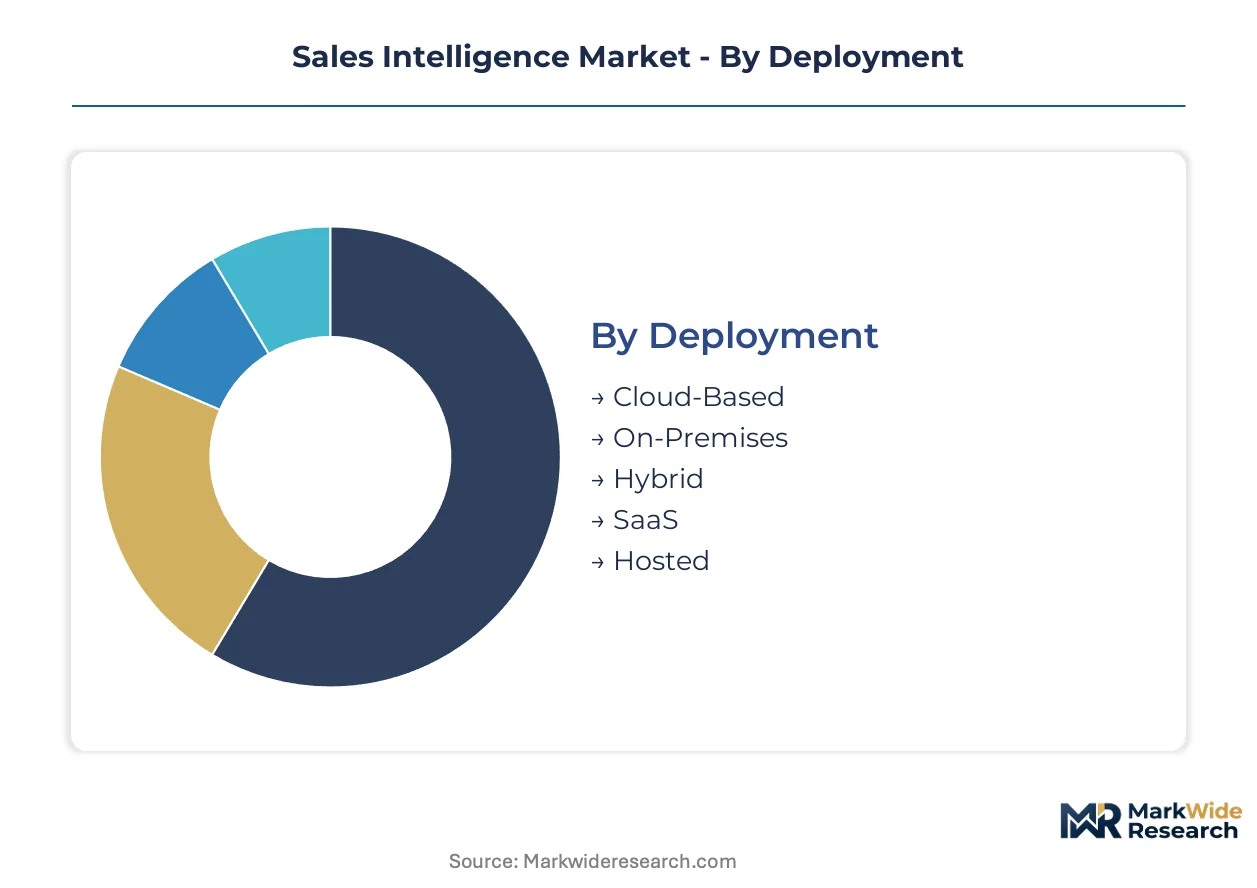
Segmentation in sales intelligence reveals how buyers prioritize data freshness, integration depth, and workflow automation. Vendors configure pricing and product architecture around deployment flexibility and solution sophistication. Understanding these splits exposes where procurement committees allocate budget and where competitive displacement occurs fastest.
Deployment:
Margin pools concentrate in cloud-native architectures that command premium pricing for elastic scalability and reduced infrastructure overhead.
- Cloud-Based:Elastic compute resources enable real-time data pipeline scaling without capital expenditure. Financial services providers in the United States prioritize these deployments for millisecond-latency CRM synchronization and continuous validation SLAs.
- SaaS:Subscription economics lower adoption barriers for mid-market revenue teams while embedding intelligence directly into workflow applications. Technology vendors consolidate procurement around these offerings to compress implementation timelines and reduce IT dependency.
- Hybrid:Combines cloud scalability with on-premises data residency for regulated verticals. Manufacturing firms deploy these configurations to satisfy internal security policies while accessing external enrichment sources.
- On-Premises:Self-managed infrastructure serving organizations with strict data sovereignty requirements. Telecommunications operators in Europe favor these deployments to satisfy GDPR cross-border transfer restrictions.
- Hosted:Dedicated single-tenant environments managed by vendor operations teams. Consumer goods companies select this model to balance customization needs with operational outsourcing.
The dominant share belongs to Cloud-Based, while SaaS is closing the gap fastest.
Solution:
Application maturity varies sharply across the solution stack, with predictive capabilities commanding pricing premiums over static data repositories.
- Contact Data Management:Real-time validation pipelines continuously refresh prospect information through proprietary sourcing infrastructure. Financial services providers expand procurement of these solutions to sharpen targeting precision and reduce outreach waste.
- Competitive Intelligence:Integration of first-party behavioral signals with third-party firmographic enrichment unlocks predictive pricing power. Enterprise SaaS buyers in the United States consolidate vendor relationships around platforms delivering unified advertising, engagement, and analytics layers.
- Lead Generation:Automated prospect identification and prioritization based on intent signal processing. Technology vendors deploy these tools to compress sales cycles and improve conversion rates.
- Customer Insights:Behavioral analytics and segmentation for existing account expansion. Manufacturing firms leverage these capabilities to identify cross-selling opportunities within installed bases.
- Sales Forecasting:Algorithmic pipeline velocity prediction and revenue projection. Telecommunications operators integrate these systems with ERP platforms for capital planning alignment.
Contact Data Management holds the largest installed base, though Competitive Intelligence exhibits the steepest expansion trajectory as buyers demand predictive capabilities beyond static firmographics.
Use Case:
Customer lifecycle positioning determines solution configuration complexity and integration depth requirements.
- Account-Based Marketing:Orchestration platforms unify advertising, sales engagement, and analytics into unified execution layers. Enterprise SaaS buyers prioritize these deployments for coordinated multi-channel outreach to named accounts.
- Customer Retention:Churn prediction and health scoring for existing account protection. Financial services providers invest heavily here given high customer lifetime values and switching costs.
- Market Penetration:Greenfield prospect identification in untapped segments or geographies. Consumer goods companies deploy these capabilities for regional expansion initiatives.
- Cross-Selling & Upselling:Product affinity modeling and timing optimization for existing accounts. Technology vendors leverage these tools to expand platform adoption within customer organizations.
- Sales Performance Management:Quota allocation, activity tracking, and compensation optimization. Telecommunications operators implement these systems to align field sales incentives with strategic priorities.
Account-Based Marketing captures the dominant procurement focus, while Customer Retention is gaining share fastest as subscription economics elevate churn prevention priority.
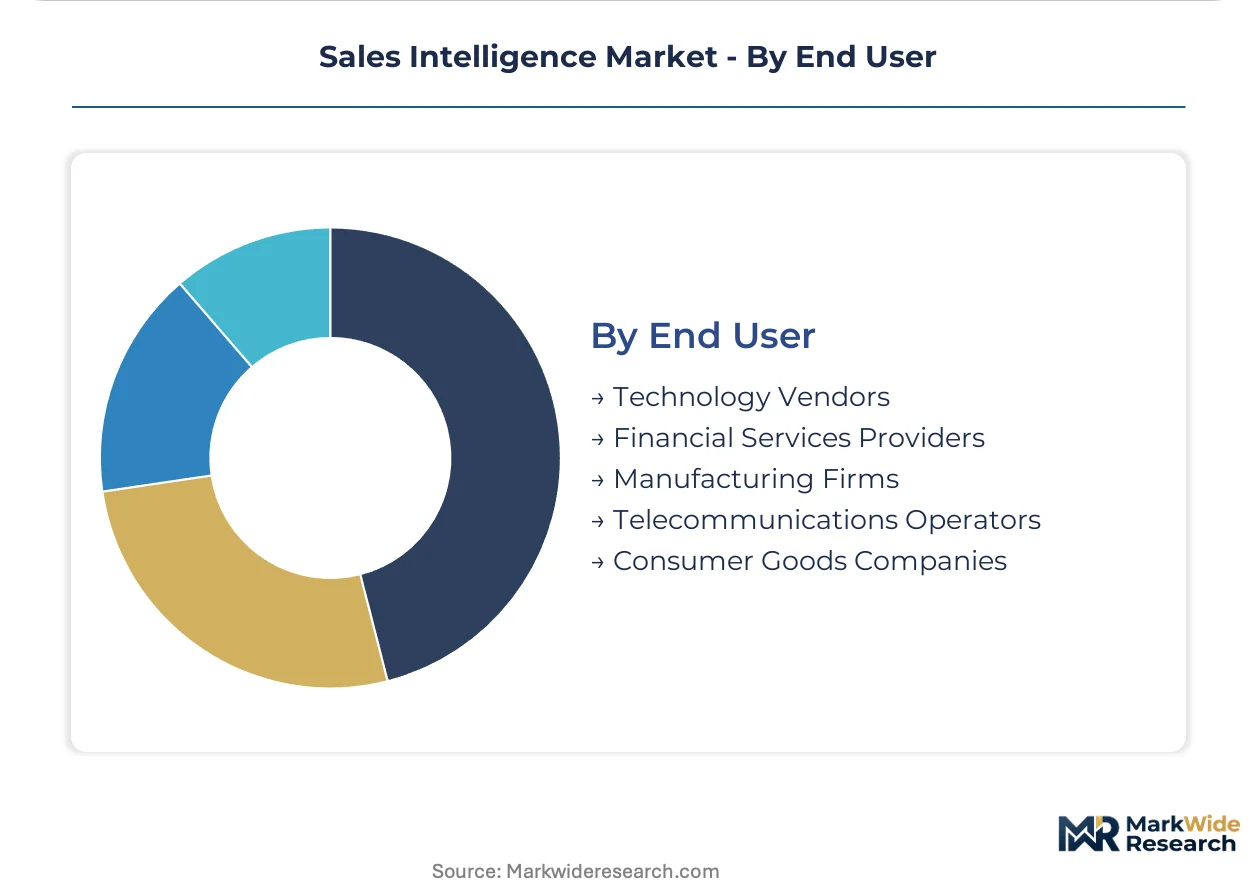
End User:
Vertical specialization requirements fragment vendor roadmaps as regulatory and workflow constraints diverge across industries.
- Financial Services Providers:Demand explainable scoring tools to satisfy EU AI Act transparency mandates for automated decision-making. Procurement committees pre-emptively restructure vendor contracts to allocate algorithmic liability.
- Technology Vendors:Prioritize real-time intent signals and API-native architectures for rapid integration with existing SaaS stacks. These buyers exhibit the shortest replacement cycles and highest willingness to switch for capability advances.
- Manufacturing Firms:Require hybrid deployment options balancing cloud accessibility with operational technology security boundaries. Long sales cycles and committee-based procurement favor established vendor relationships.
- Telecommunications Operators:Seek massive-scale data processing for consumer and enterprise segment targeting. Regulatory scrutiny of data practices elevates provenance documentation requirements.
- Consumer Goods Companies:Focus on retail channel intelligence and shopper behavior analytics. These organizations prioritize solutions with pre-built connectors to marketing cloud platforms.
Technology Vendors represent the largest addressable segment, though Financial Services Providers are expanding procurement fastest as compliance deadlines approach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FTC Section 5 enforcement against deceptive data practices anchors the United States as the primary demand center for sales intelligence, while GDPR and the EU AI Act reshape European deployment architectures through explainability mandates and cross-border transfer restrictions.
United States
Enterprise SaaS buyers in California and New York prioritize real-time intent signals and account-based marketing orchestration platforms. FTC scrutiny of data provenance representations constrains how vendors market accuracy claims to commercial buyers. The San Francisco Bay Area and Boston corridor concentrate procurement committees consolidating vendor relationships around unified advertising and analytics layers.
Germany
Financial services providers in Frankfurt and Munich accelerate procurement of explainable scoring tools to meet EU AI Act transparency deadlines for automated customer decisions. BSI certification requirements for data processing systems elevate vendor qualification barriers. The Rhine-Main and Bavarian industrial clusters host procurement teams restructuring contracts to allocate algorithmic liability before enforcement dates.
United Kingdom
Technology vendors in London and the Southeast exhibit the shortest replacement cycles for real-time identity resolution engines. FCA guidance on algorithmic accountability intersects with commercial data ethics frameworks. The London fintech corridor drives demand for outcome-based intelligence contracts tied to pipeline contribution metrics rather than seat-based subscriptions.
India
Mid-market revenue teams in Bengaluru and Hyderabad adopt SaaS-delivered sales intelligence to compress implementation timelines and reduce IT dependency. PLI scheme incentives for cloud and data center expansion lower localization barriers for global vendors. The NCR-Delhi corridor and Maharashtra industrial belt concentrate demand for contact data management solutions targeting regional expansion initiatives.
Japan
Manufacturing firms in Tokyo and Osaka deploy hybrid configurations balancing cloud accessibility with operational technology security boundaries. METI guidelines on data governance shape vendor selection criteria for cross-border data handling. The Kanto and Kansai metropolitan areas host procurement committees favoring established vendor relationships amid long sales cycles and committee-based buying processes.
Sales Intelligence Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with platform-native providers commanding multi-product contracts against point-solution vendors competing on workflow depth. The structure rewards continuous validation infrastructure over static data licensing models, compressing switching costs as buyers adopt real-time systems within eighteen-month replacement cycles. Three archetypes dominate: vertically integrated data originators, workflow-embedded intelligence layers, and outcome-based performance vendors. Competitive displacement accelerates through M&A consolidation of validation pipelines and strategic partnerships bundling advertising with engagement orchestration.
Within the integrated platform tier, Salesforce and Oracle represent archetypal ecosystem anchors leveraging CRM infrastructure to embed intelligence layers directly into customer workflow applications. ZoomInfo occupies a position exemplifying vertically integrated data origination, with proprietary sourcing infrastructure sustaining dominance in North American contact markets. HubSpot sits within the inbound-native archetype, bundling lightweight intelligence into marketing suites to lower adoption barriers for smaller revenue organizations. These three patterns illustrate how vendor configuration around deployment flexibility, data freshness SLAs, and integration depth determines competitive positioning across buyer segments.
| Leading Market Players |
|---|
| ZoomInfo |
| Salesforce |
| HubSpot |
| Dun & Bradstreet |
| Oracle |
| Clearbit |
| Demandbase |
| HG Insights |
| Others |
Cost & Logistics Intelligence
GDPR adequacy mechanism requirements gate both European vendor qualification and price differentiation simultaneously, forcing providers to embed compliance infrastructure costs into tiered service offerings while restricting lower-cost data sourcing alternatives. This regulatory architecture compresses margins for mid-market entrants while rewarding vertically integrated operators with captive validation pipelines.
Pricing Analysis
United States enterprise contracts command 40-60% premiums over equivalent European deployments due to real-time latency requirements and outcome-based performance guarantees. Pricing stratifies across premium, standard, and economy tiers differentiated by data freshness SLAs, API call volumes, and integration depth. Cost compression in the standard tier is intensifying because cloud infrastructure commoditization erodes switching costs. Mid-market SaaS buyers exhibit highest price sensitivity, while financial services providers accept premium positioning for explainable scoring compliance.
Supply Chain Analysis
Just-in-time data validation pipelines dominate procurement patterns as buyers reject batch-processed repositories with degradation curves exceeding 90 days. Proprietary sourcing infrastructure concentrates in the United States, United Kingdom, and Germany, drawing from web scraping operations, contributed business card networks, and partnership data feeds. Single-source vulnerability persists around North American contact graph databases. Distribution runs through API-first platforms and embedded CRM marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sales intelligence market sits in early-cycle recovery as enterprise SaaS procurement committees resume martech consolidation programs deferred during budget freezes. CFO scrutiny of pipeline contribution metrics accelerates displacement of seat-based subscription vendors.
For Market Incumbents: Compound platform stickiness by embedding intelligence layers deeper into workflow automation, capturing multi-product contracts before point-solution competitors achieve feature parity. Prioritize backward integration into proprietary validation pipelines to defend data freshness SLAs against emerging real-time identity resolution engines. Channel control through CRM marketplace dominance remains the critical defensive lever. For New Entrants and Emerging Players: Anchor in modular compliance architectures serving multi-jurisdictional enterprises navigating fragmented United States state-level privacy legislation. White-space concentration exists in India and Southeast Asia where PLI scheme infrastructure incentives lower localization barriers. Pursue outcome-based pricing models tied to pipeline generation metrics to bypass incumbent seat-based contract structures. For Investors and Strategic Acquirers: EU AI Act enforcement deadlines reshape the acquisition landscape toward explainable scoring specialists with financial services vertical penetration. Five-to-ten year viability favors vendors with continuous validation infrastructure over static data licensors. The signal to watch is procurement committee consolidation velocity around unified advertising-engagement-analytics platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Validation Pipeline Acquisition | Captures data freshness SLAs that determine RFP participation in financial services procurement. |
| Explainable Scoring Layer Development | Satisfies EU AI Act transparency mandates for automated customer decisions in European deployments. |
| Outcome-Based Contract Structuring | Aligns vendor compensation with pipeline contribution metrics preferred by CFO scrutiny. |
| Edge Computing Infrastructure Investment | Delivers sub-millisecond API latency required for real-time CRM synchronization. |
| Modular Compliance Architecture Launch | Addresses fragmented United States state-level privacy legislation through configurable deployment options. |
Research Approach
Cross-validation between primary interviews with sales operations leaders and secondary validation through SEC filings and hyperscaler capex disclosures anchors the qualitative findings. Conversations with CRM platform engineers, enterprise SaaS procurement officers, data privacy compliance leads, and sales engagement specialists inform capability assessments. Bottom-up sizing of vendor revenue segments triangulates against top-down enterprise software spend allocation models.
Sensitivity analysis around adoption curve assumptions tests forecast robustness across the projection horizon. Segmentation dimensions modeled include deployment architecture, organization size tier, vertical regulatory intensity, integration complexity, and regional compliance framework. CAGRs derive from slope-intercept fitting of historical penetration data against technology diffusion curves. Forecast inputs incorporate sales cycle compression rates and procurement committee consolidation patterns.
Material uncertainties — regulatory enforcement timing, cross-border data transfer mechanism rulings, and talent scarcity severity — sit outside the modeled envelope. Forecasts reflect documented assumptions about buyer behavior continuity and vendor competitive positioning stability. Revision becomes warranted when EU AI Act liability allocation precedents cross thresholds that restructure vendor contract economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Marketing Analytics Market
Analytics
In-Memory Analytics Tools Market
Analytics
Customer Journey Analytics Market
Analytics
US Predictive Analytics Market
Analytics
Global Saas-Based Business Analytics Market
Analytics
North America Crowd Analytics Market
Analytics
Enterprise Drone Analytics Software Market
Analytics
Business Analytics Market
Analytics
Big Data Analytics in Manufacturing Market
Analytics
Crowd Analytics Market
Analytics
Cloud Analytics Market
Analytics
Content Analytics and Search Software Market
Analytics
Global Digital Intelligence Platform Market
Analytics
Data Preparation Market
Analytics
Global Social Intelligence Market
Analytics
Speech and Voice Analytics Market