
 North America Fluid Milk Market | 2026-2036
North America Fluid Milk Market Size, Share, and Industry Trends Forecast 2026-2036
North America Fluid Milk Market Intelligence
Plant-based alternatives are realigning conventional fluid milk economics as oat and almond beverages capture refrigerated case space. Dean Foods leverages its extensive direct-store-delivery network to sustain volume in conventional white milk. Saputo Inc. anchors its North American position through backward integration into dairy cooperative supply chains. Dairy Farmers of America competes aggressively on cooperative-member pricing to control raw milk sourcing across the Midwest and Northeast.
Fluid milk denotes pasteurized, unfermented cow's milk standardized to specific butterfat levels, typically processed through HTST (high-temperature short-time) treatment at 72°C for 15 seconds to eliminate pathogens while preserving sensory quality. Its primary commercial purpose spans direct consumption, institutional feeding programs, and ingredient supply for food manufacturing. Whole milk retains dominant volume share in household purchases through supermarkets, while flavored milk generates disproportionate margin contribution via school nutrition contracts and convenience store single-serve sales. Carton packaging leads institutional channels due to cost efficiency and stackability, though bottle formats command premium positioning in specialty retail.
The FDA enforces Grade A Pasteurized Milk Ordinance standards that dictate pathogen limits, temperature controls, and labeling requirements across interstate commerce. USDA National School Lunch Program specifications shape institutional demand by mandating fat-content tiers and vitamin fortification levels for program eligibility. State-level dairy pricing regulations, particularly Federal Milk Marketing Order classifications, directly determine processor margins and farmgate returns. Stakeholders must monitor evolving plant-based labeling disputes and potential revisions to Federal Milk Marketing Order structures that could redistribute value between fluid and manufactured milk classes.
Market Dynamics
Federal Milk Marketing Order classifications are redistributing value between fluid milk handlers and dairy cooperatives across the Upper Midwest and Northeast, compressing processor margins while elevating farmgate returns in Wisconsin and Minnesota processing clusters.
Growth Catalysts
- USDA National School Lunch Program specifications:Mandated fat-content tiers and vitamin fortification levels for program eligibility institutionalize volume commitments from K-12 nutrition directors.
- HTST pasteurization technology:High-temperature short-time treatment at 72°C for 15 seconds preserves sensory quality while eliminating pathogens, extending shelf-life for food service distribution.
- Upper Midwest dairy belt concentration:Wisconsin and Minnesota processing clusters generate economies of scale in raw milk collection and branded private-label supply throughout the region.
Market Restraints
- Feed cost volatility:Corn and soybean meal price swings transmit directly to dairy cooperative raw milk pricing formulas, destabilizing processor margin forecasts.
- Plant-based substitution:Oat and almond beverages capture refrigerated case space in conventional supermarkets, constraining white milk volume growth.
- FDA Grade A Pasteurized Milk Ordinance compliance:Pathogen limits and temperature control mandates require continuous quality system upgrades that favor capital-intensive operators.
Strategic Opportunities
- Extended shelf-life (ESL) processing:Microfiltration and advanced thermal technologies enable distribution expansion into underpenetrated rural markets across the Great Plains.
- Convenience store single-serve channel:Flavored milk generates disproportionate margin contribution through grab-and-go positioning in C-store refrigerated sets.
- Inflation Reduction Act biofuel incentives:Dairy manure digesters qualify for renewable natural gas credits, offsetting farm-level sustainability compliance costs.
Industry Challenges
- Direct-store-delivery network maintenance:Labor scarcity in driver and merchandiser functions strains last-mile freshness guarantees for conventional white milk.
- Legacy plant retrofitting:Aging HTST infrastructure requires capital-intensive upgrades to meet FDA's updated nutrition labeling and safety standard timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Fluid Milk Market |
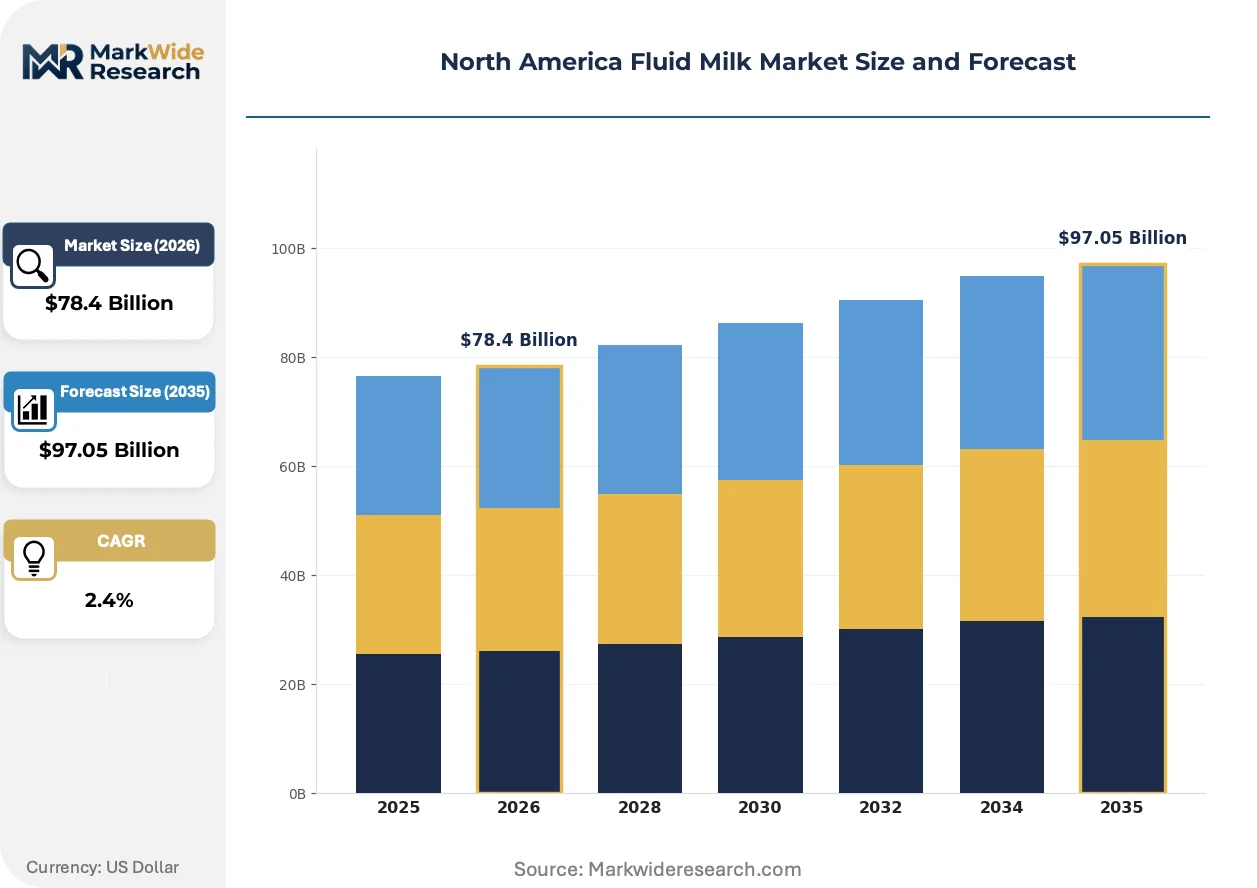
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $97.05 Billion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Milk, Skim Milk, Low-Fat Milk, Flavored Milk Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Specialty Stores Packaging Type: Bottle, Carton, Tetra Pack, Pouch End User: Households, Food Service, Healthcare Institutions, Schools |
| Companies Covered | Lactalis American Group, Dean Foods, Dairy Farmers of America, Darigold, Inc., Schreiber Foods, Saputo Inc., Agropur Cooperative, Borden Dairy Company, Nestlé USA, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Fluid Milk Market Strategic Shifts & Innovations
Processing technology convergence and regulatory recalibration are compressing traditional competitive advantages in fluid milk, while channel fragmentation rewards operators who can synchronize freshness logistics with diverging consumption occasions.
Aseptic carton filling systems are unifying extended shelf-life production with ambient distribution capability. Mid-size processors in the Texas Panhandle and Arizona desert markets are adopting this equipment to bypass cold-chain limitations. The technology is unifying previously separate fresh and shelf-stable supply chains into single production footprints.
The FDA's updated nutrition labeling requirements are forcing reformulation of flavored milk portfolios to reduce added sugars while maintaining palatability. Processors must reconfigure vitamin fortification protocols to comply with revised Daily Value percentages. School nutrition contracts in California and New York districts are most affected, with food service directors demanding compliant reformulations ahead of contract renewal cycles.
Household purchasing is fragmenting across multiple retail formats as club stores and e-commerce grocery capture fluid milk volume from conventional supermarkets. Convenience stores are consolidating single-serve flavored milk occasions previously served by food service. This behavioral rotation is most visible in suburban corridors of Texas and Florida, where time-compressed consumers prioritize proximity over one-stop shopping.
North America Fluid Milk Market Segmentation
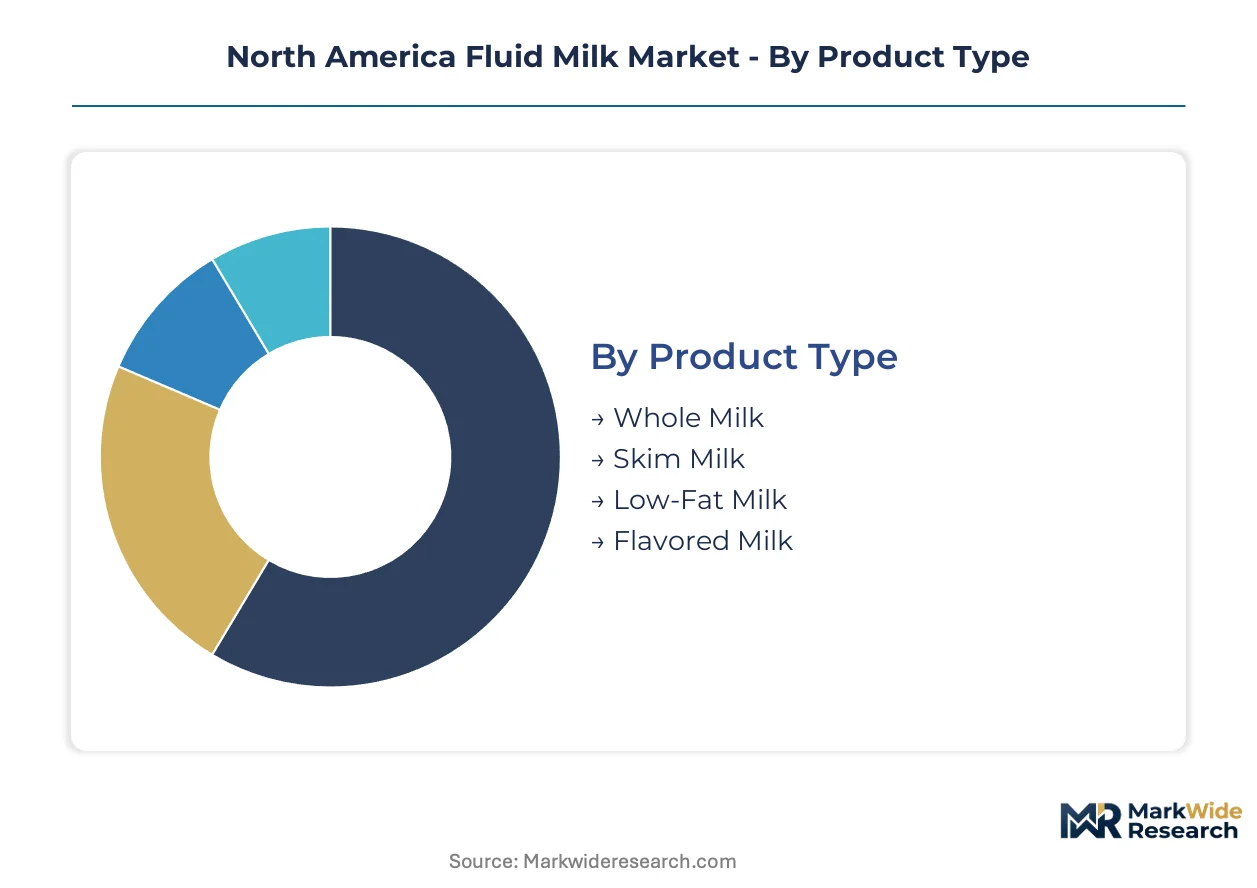
Fluid milk segmentation reveals how capital deployment, regulatory exposure, and channel economics fragment value capture across the North American dairy value chain. Processors must align production configurations with diverging margin profiles and freshness requirements inherent to each segment cluster.
Product Type:
Capital intensity peaks in segments requiring specialized fat standardization equipment and extended shelf-life processing infrastructure.
- Whole Milk:Retains butterfat content at 3.25% or higher without mechanical separation, demanding less processing capital than reduced-fat alternatives. Household procurement through Upper Midwest supermarket chains sustains volume leadership despite school nutrition program pressure to reduce saturated fat exposure.
- Skim Milk:Requires centrifugal separation systems and butterfat recovery operations that elevate fixed asset intensity. Demand concentrates in healthcare institutions across Minnesota and Wisconsin where therapeutic diet protocols mandate fat restriction.
- Low-Fat Milk:Standardized to 1% or 2% butterfat through partial separation, capturing operational efficiency from shared equipment with skim production lines.
- Flavored Milk:Incorporates added sugars and flavoring systems that trigger FDA nutrition labeling reformulation costs; school contract renewal cycles in California and New York drive reformulation urgency.
Whole milk absorbs the bulk of installed capacity; flavored milk is expanding most quickly through convenience store single-serve positioning.
Distribution Channel:
Channel selection dictates cold-chain infrastructure requirements and last-mile labor intensity across rural and urban market archetypes.
- Supermarkets:Volume concentration in Upper Midwest retail banners demands direct-store-delivery networks with daily replenishment cycles. Dean Foods maintains route density advantages through legacy infrastructure investments across Wisconsin and Minnesota.
- Convenience Stores:Single-serve flavored milk generates disproportionate margin contribution via grab-and-go refrigerated sets. Texas and Florida suburban corridors show fastest channel expansion as time-compressed consumers prioritize proximity.
- Online Retailers:Requires insulated packaging and expedited logistics that compress shelf-life windows; club store partnerships dominate fluid milk e-commerce penetration.
- Specialty Stores:Premium positioning for organic and grass-fed variants commands bottle-format packaging and differentiated sourcing credentials.
Supermarkets retain the largest share of fluid milk throughput; convenience stores are climbing the fastest as consumption occasions fragment.
Packaging Type:
Packaging technology selection determines shelf-life extension potential and distribution radius economics for regional processors.
- Carton:Gable-top paperboard dominates institutional channels through cost efficiency and stackability; school nutrition programs mandate carton formats for portion control compliance.
- Bottle:HDPE and PET formats command premium retail positioning; resealability drives household preference in suburban markets.
- Tetra Pack:Aseptic filling systems enable ambient distribution bypassing cold-chain limitations; Texas Panhandle and Arizona desert markets adopt this technology for rural penetration.
- Pouch:Flexible film formats reduce material costs and shipping weight; limited adoption constrained by puncture risk and consumer handling preferences.
Carton packaging holds the greatest installed base; Tetra Pack formats are gaining share fastest through ESL processing convergence.
End User:
End-user segmentation exposes diverging regulatory compliance burdens and contract pricing structures across institutional and retail demand pools.
- Households:Supermarket procurement of whole and reduced-fat variants drives volume; private-label capture rates exceed branded loyalty in price-sensitive Midwest markets.
- Food Service:HTST pasteurization at 72°C for 15 seconds meets food safety requirements for prepared meal and beverage program integration; operators expand procurement for prepared meal programs.
- Healthcare Institutions:Skim and low-fat fortification protocols align with therapeutic nutrition standards; vitamin D and A fortification mandates elevate formulation specificity.
- Schools:USDA National School Lunch Program specifications mandate fat-content tiers and vitamin fortification levels; California and New York district contract renewals demand sugar reduction reformulation.
Households consume the majority of fluid milk volume; food service is expanding most quickly through prepared meal program growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fluid milk demand concentrates in the Upper Midwest dairy belt, where processing infrastructure and cooperative supply chains create supply-side density unmatched elsewhere in the region.
United States
School nutrition programs and food service operators drive institutional volume through USDA National School Lunch Program specifications. The FDA enforces Grade A Pasteurized Milk Ordinance standards across interstate commerce. Wisconsin and Minnesota processing clusters supply branded and private-label fluid milk throughout the Great Lakes and Plains states.
Canada
Supply management systems stabilize farmgate pricing through provincial marketing boards. Health Canada administers dairy product safety standards aligned with international Codex guidelines. Quebec and Ontario dairy cooperatives concentrate processing capacity near Montreal and Toronto metro corridors.
Mexico
Urbanization in Mexico City and Guadalajara expands fluid milk consumption through modern retail format penetration. COFEPRIS regulates dairy product safety and labeling requirements for domestic production and imports. Northern border states host processing facilities serving cross-border supply chains into Texas and California markets.
California
Specialty fluid milk variants including organic and grass-fed command premium positioning through health-conscious consumer segments. State-level dairy pricing regulations and environmental compliance mandates shape processor operating costs. Central Valley dairy operations supply fluid milk to Los Angeles and San Francisco metropolitan distribution networks.
Texas
Convenience store single-serve flavored milk occasions expand through suburban corridor development in Dallas-Fort Worth and Houston. State health services administer milk safety inspections parallel to federal frameworks. Panhandle processing adopters deploy aseptic filling systems to bypass cold-chain limitations in rural markets.
North America Fluid Milk Market Key Industry Players
Backward integration into dairy cooperative supply chains dominates the current landscape, compressing processor margins while securing raw milk access. The market exhibits tiered concentration with national distributors, regional cooperatives, and private-label specialists competing across distinct channel positions. Three archetypes prevail: cooperative-affiliated processors with captive milk supply, direct-store-delivery operators with route density advantages, and private-label converters with flexible sourcing arrangements. M&A activity and capacity modernization constitute the primary competitive vectors as legacy infrastructure requires capital-intensive upgrades to meet FDA safety timelines.
Among cooperative-integrated processors, Dairy Farmers of America and Agropur Cooperative exemplify the backward-integration archetype, anchoring supply security through member ownership structures. Dean Foods occupies a position within the direct-store-delivery tier, leveraging legacy route infrastructure for last-mile freshness guarantees in Upper Midwest markets. These entities represent divergent strategic postures on supply chain control versus distribution asset intensity.
| Leading Market Players |
|---|
| Lactalis American Group |
| Dean Foods |
| Dairy Farmers of America |
| Darigold, Inc. |
| Schreiber Foods |
| Saputo Inc. |
| Agropur Cooperative |
| Borden Dairy Company |
| Nestlé USA |
| Others |
Cost & Logistics Intelligence
Class III milk futures on the Chicago Mercantile Exchange cascade through Federal Milk Marketing Order pricing formulas to set processor procurement baselines, with farmgate premiums in Wisconsin and Minnesota compressing handler margins while private-label converters capture residual value in supermarket channels.
Pricing Analysis
Volume concentrates in conventional white milk while margins accrue to flavored single-serve and extended shelf-life tiers. Price differentiation hinges on butterfat standardization grades and USDA organic certification premiums. Pricing pressure intensifies in the Upper Midwest as cooperative-member pricing formulas elevate raw milk costs. Private-label supermarket buyers exhibit highest price sensitivity; specialty organic purchasers demonstrate lowest.
Supply Chain Analysis
Fuel and refrigerated freight costs dominate last-mile economics for direct-store-delivery networks spanning Wisconsin, Minnesota, and Iowa processing clusters. Raw milk sourcing draws from the Upper Midwest dairy belt, with corn and soybean meal feed inputs tethered to commodity futures volatility. Single-source vulnerability concentrates in cooperative-affiliated processors with captive supply arrangements. Distribution runs through direct-store-delivery for conventional milk and cold-chain logistics for extended shelf-life variants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into dairy cooperative supply chains constitutes the defining competitive race, with processors securing raw milk access through member ownership structures while distributors invest in route density for freshness guarantees.
For Market Incumbents: Anticipate plant-based substitution pressure by fortifying direct-store-delivery network density in Wisconsin and Minnesota. Secure cooperative membership positions to lock in farmgate supply amid Federal Milk Marketing Order reclassification risks. Invest in HTST infrastructure upgrades to meet FDA Grade A Pasteurized Milk Ordinance timelines. For New Entrants and Emerging Players: The Inflation Reduction Act's biofuel incentives across the United States open a window for dairy manure digester partnerships that offset sustainability compliance costs. Target convenience store single-serve flavored milk in Texas and Florida suburban corridors. Pursue aseptic filling technology adoption to bypass cold-chain limitations in rural Great Plains markets. For Investors and Strategic Acquirers: Distressed-cycle entries favor private-label converters with flexible sourcing arrangements in the Upper Midwest. Long-term viability centers on processors with installed extended shelf-life capacity and school nutrition contract exposure. Monitor Federal Milk Marketing Order revision proposals as the critical inflection signal for margin redistribution between fluid and manufactured milk classes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cooperative Supply | Secures raw milk access through Dairy Farmers of America and Agropur member structures. |
| Extended Shelf-Life Processing Deployment | Enables distribution expansion into rural Texas Panhandle and Arizona markets. |
| Direct-Store-Delivery Network Modernization | Addresses driver scarcity while maintaining FDA temperature control compliance. |
| Flavored Milk Reformulation Investment | Meets California and New York school district sugar reduction contract requirements. |
| Aseptic Filling Technology Adoption | Unifies fresh and shelf-stable supply chains for ambient distribution capability. |
Research Approach
Document review covered Federal Milk Marketing Order administrative records, FDA Grade A Pasteurized Milk Ordinance filings, and USDA National School Lunch Program specifications, complemented by interviews with dairy cooperative procurement directors, HTST plant engineers, school nutrition program administrators, and convenience store category buyers. Secondary sources included customs data on dairy equipment imports, SEC filings from publicly traded processors, and state-level dairy pricing regulation databases. Bottom-up volume estimates from processing capacity utilization were triangulated against top-down consumption surveys.
Historical volume trajectories were cross-referenced against panel input from cooperative pricing committees to derive growth projections across the analysis window. Segmentation modeling incorporated product type, distribution channel, packaging format, and end-user regulatory exposure dimensions. CAGRs were computed from fitted trend lines adjusted for plant-based substitution elasticities and Federal Milk Marketing Order classification shifts. Forecast inputs included feed cost futures, school nutrition program enrollment patterns, and refrigerated logistics capacity expansion plans.
The model assumes a particular technology adoption path for extended shelf-life processing; alternative pathways for microfiltration and advanced thermal treatment would alter the outlook for rural distribution penetration. Forecasts reflect assumptions regarding cooperative pricing formula stability and FDA enforcement intensity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Savory Dairy Products Market
Dairy Products
US Yogurt and Probiotic Drink Market
Dairy Products
Fermented Dairy Ingredients Market
Dairy Products
Asia-Pacific Dairy Protein Market
Dairy Products
Global Yogurt Market
Dairy Products
North America Dairy Market
Dairy Products
Low Temperature Yogurt Market
Dairy Products
Lactose Market
Dairy Products
Europe Cow Milk Minerals Market
Dairy Products
Parmesan Cheese Market
Dairy Products
Skim Milk Powder Market
Dairy Products
Europe Cheese Market
Dairy Products
Europe Drinkable Yogurt Market
Dairy Products
Middle East and Africa UHT Milk Market
Dairy Products
Dry Buttermilk Market
Dairy Products
Latin America Cheese Market