
 Reconstituted Milk Market | 2026-2036
Reconstituted Milk Market Size, Share, and Industry Trends Forecast 2026-2036
Reconstituted Milk Market Analytics
Single-source reliance on fresh milk procurement is rebalancing toward multi-source models that integrate reconstituted dairy solids. Fonterra Co-operative Group anchors its competitive stance through backward integration into milk powder processing in Oceania. Nestlé S.A. leverages global blending facilities to sustain formulation consistency across beverage and confectionery lines. Lactalis specializes in cream and dairy blend outputs that occupy premium positioning in European food service channels.
Reconstituted milk denotes dairy products manufactured by rehydrating milk powders or concentrates with water to achieve standardized fat and solids content, typically requiring homogenization and heat treatment to match functional properties of fresh fluid milk. Its primary commercial purpose centers on delivering shelf-stable, cost-predictable dairy inputs for beverage manufacturing and baked goods production where seasonal fresh milk volatility disrupts margins. Powdered milk retains the largest volume share within product type segmentation, though liquid reconstituted formats are gaining traction in quick-service restaurant fountain applications. Dairy blends command higher margin pools by combining milk solids with vegetable fats to meet price-sensitive institutional demand in bakery and confectionery applications.
FDA standards for identity and labeling of reconstituted dairy products shape formulation transparency requirements in the United States, while EFSA and EU Green Deal sustainability disclosures are tightening carbon accounting for spray-drying energy use in European production. BIS quality specifications in India and CDSCO-adjacent food safety protocols further segment market access by certifying rehydration ratios and microbial thresholds. Stakeholders must monitor how evolving refrigerant regulations and renewable energy mandates alter the operating economics of powder-to-liquid reconstitution facilities.
Market Dynamics
Spray-drying energy intensity and refrigerant-phaseout mandates under the EU F-Gas Regulation are forcing capital reallocation toward renewable-powered reconstitution facilities, altering where processors site powder-to-liquid operations.
Growth Catalysts
- Southeast Asian urban dairy deficit:Domestic fresh milk shortfalls in Indonesia, Vietnam, and the Philippines accelerate institutional procurement of reconstituted inputs for beverage manufacturing.
- EU Green Deal carbon accounting:Sustainability disclosure requirements for Scope 2 emissions incentivize processors to source spray-dried powders from renewable-powered facilities.
- Membrane filtration advances:Ultrafiltration and reverse osmosis concentration methods reduce rehydration ratios while preserving functional proteins for bakery applications.
Market Restraints
- Fresh milk price volatility:Seasonal fluctuations in Oceania and European raw milk markets transmit directly into powder input costs, compressing blender margins.
- Single-geometry spray-dryer concentration:Toll-processing capacity clusters in New Zealand and the Netherlands, creating geographic supply risk for Asian formulators.
- Plant-based beverage substitution:Oat and almond protein isolates displace reconstituted dairy in quick-service fountain applications.
Strategic Opportunities
- Sub-Saharan African cold chain gaps:Shelf-stable reconstituted formats bypass refrigeration infrastructure deficits in Nigeria and Kenya for institutional feeding programs.
- India PLI scheme for food processing:Production-linked incentives for dairy infrastructure attract greenfield spray-drying investments in Gujarat and Maharashtra.
- Direct-to-manufacturer e-procurement platforms:Digital sourcing marketplaces connect Southeast Asian bakeries directly with Oceania powder exporters, compressing distributor layers.
Industry Challenges
- Spray-dryer thermal efficiency expertise:Shortage of process engineers capable of optimizing heat-recovery systems in multi-stage drying towers delays facility commissioning.
- F-Gas refrigerant retrofit timelines:EU facilities face compressed deadlines to replace hydrofluorocarbon-based cooling systems in powder storage, requiring parallel capital deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reconstituted Milk Market |
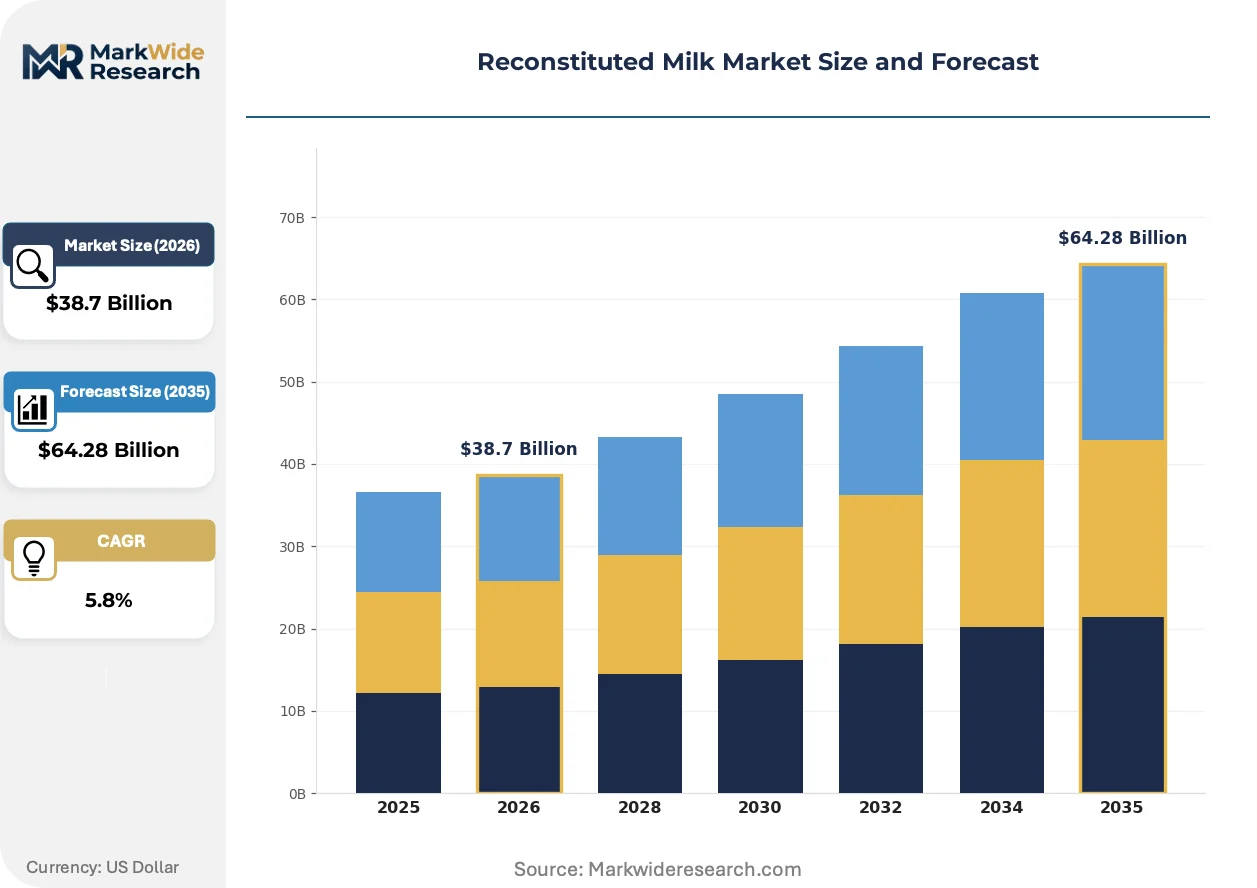
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powdered Milk, Liquid Milk, Cream, Dairy Blends End User: Retail Consumers, Food Processing, Restaurants, Bakeries Distribution Channel: Supermarkets, Online Retailers, Convenience Stores, Wholesalers Application: Beverages, Confectionery, Dairy Products, Bakery Items |
| Companies Covered | Nestlé S.A., Fonterra Co-operative Group, Lactalis, Arla Foods, Danone S.A., Dairy Farmers of America, Saputo, Yili Group, Mengniu Dairy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reconstituted Milk Market Evolving Landscape
Energy recovery systems and alternative protein blending are rewriting the technical and formulation boundaries of reconstituted dairy, while procurement digitization compresses traditional trading hierarchies.
Membrane concentration technology is rewriting how processors standardize solids content before drying. Large-scale beverage manufacturers in Thailand and Malaysia adopt ultrafiltration pre-concentration to reduce spray-dryer energy loads by fifteen to twenty percent. This compression of thermal input requirements is rewriting facility siting decisions, enabling relocation to markets with lower renewable energy tariffs.
The EU F-Gas Regulation mandates phasedown of hydrofluorocarbon refrigerants in industrial cooling systems through 2030. Spray-drying facilities in Germany and France retrofit ammonia-based or transcritical CO2 refrigeration for powder storage and climate control. Dairy blend processors face accelerated depreciation schedules as they reconcile legacy equipment with compliance deadlines.
Quick-service restaurant chains in Indonesia and the Philippines consolidate procurement through centralized ingredient platforms rather than regional dairy distributors. This channel compression eliminates layered markups but demands lot-traceability documentation that smaller reconstitution suppliers struggle to provide. The shift is most visible in fountain beverage and soft-serve ice cream supply contracts.
Reconstituted Milk Market Segmentation
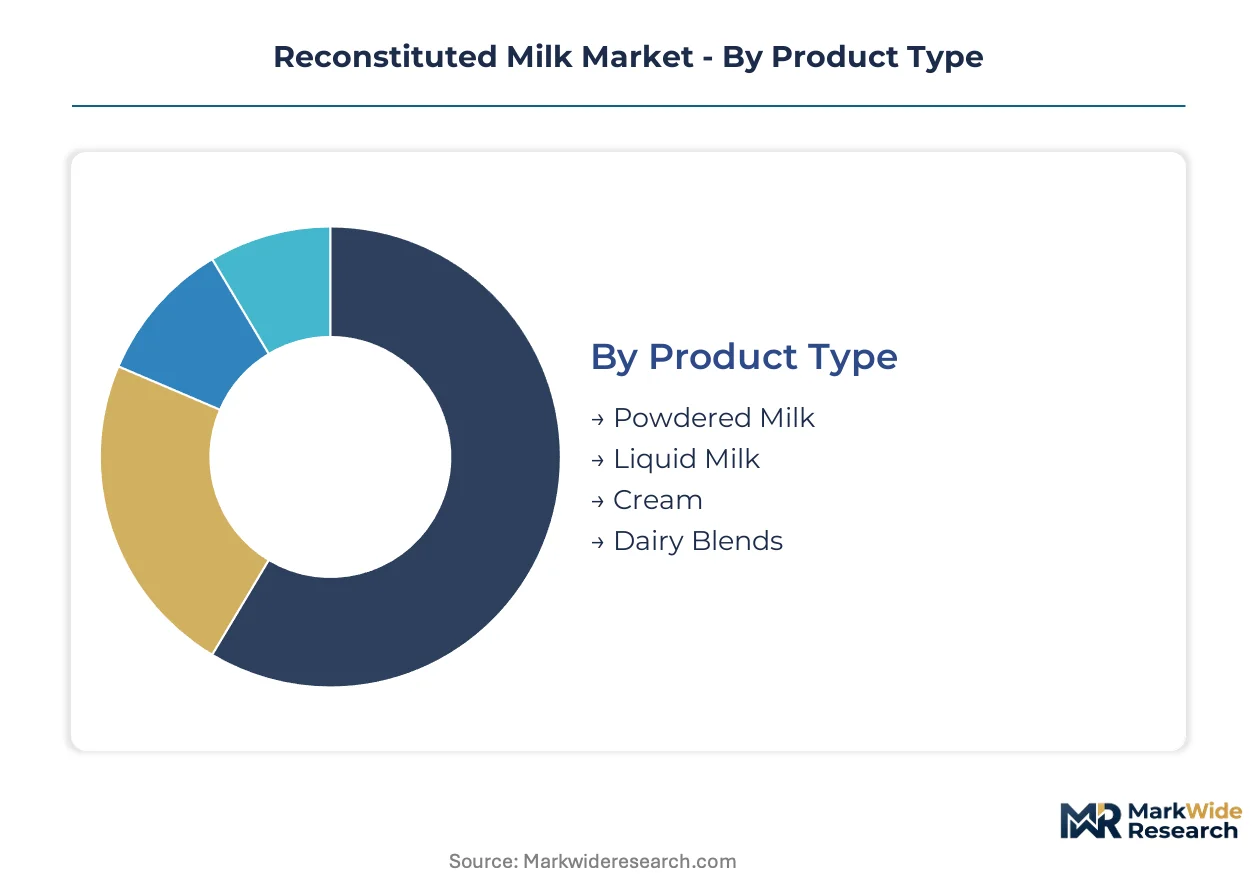
Reconstituted milk segmentation reflects divergent buyer priorities across cost predictability, shelf stability, and functional performance. Powdered formats dominate procurement for institutional buyers managing inventory volatility, while liquid reconstituted formats serve quick-service channels demanding operational simplicity.
Product Type:
Buyers in this category differentiate primarily by shelf-life requirements versus formulation flexibility.
- Powdered Milk:Dehydrated milk solids rehydrated to standardized protein and fat specifications. Procurement concentrates in Indonesian and Vietnamese beverage manufacturers seeking insulation from Oceania fresh milk price swings.
- Liquid Milk:Pre-reconstituted fluid formats delivered in bulk tanker or aseptic packaging. Quick-service restaurant chains in the Philippines adopt this segment to eliminate on-site rehydration labor and equipment.
- Cream:High-fat reconstituted dairy inputs standardized for whipping stability and mouthfeel. European food service channels drive demand for premium positioning in dessert applications.
- Dairy Blends:Milk solids combined with vegetable fats to achieve cost targets below pure dairy formulations. Institutional bakery procurement in Nigeria and Kenya favors these inputs for price-sensitive bread and pastry production.
Volume sits with Powdered Milk; growth tilts toward Dairy Blends.
End User:
Procurement scale and technical specification intensity separate buyers across this dimension.
- Food Processing:Large-scale manufacturers of infant formula, UHT beverages, and confectionery requiring batch-to-batch consistency in protein content and microbial specifications. Thai and Malaysian processors lead adoption of membrane-preconcentrated powders to reduce energy costs.
- Restaurants:Quick-service and casual dining chains sourcing fountain beverages, soft-serve, and sauce bases. Centralized procurement platforms in Indonesia now bypass traditional dairy distributors.
- Retail Consumers:Household purchasers of instant milk powders for home reconstitution, concentrated in price-sensitive urban markets with unreliable cold chain infrastructure.
- Bakeries:Artisan and industrial producers leveraging reconstituted dairy for cost-stable butter and cream alternatives in cake and pastry applications.
Food Processing commands the largest procurement volumes; Restaurants are climbing the fastest as fountain beverage consolidation accelerates.
Distribution Channel:
Channel selection tracks buyer sophistication and lot-traceability requirements.
- Wholesalers:Traditional dairy traders handling bulk powder shipments from New Zealand and Netherlands spray-drying clusters to Southeast Asian formulators.
- Online Retailers:Digital platforms connecting manufacturers directly with ingredient buyers, compressing markups but demanding documentation capabilities smaller suppliers lack.
- Supermarkets:Retail shelf presence for consumer-facing powdered milk brands in urban centers across India and Indonesia.
- Convenience Stores:Small-format retail for emergency household replenishment of instant milk products.
Wholesalers retain volume leadership; Online Retailers gain share fastest as procurement digitization penetrates mid-tier processors.
Application:
Functional protein requirements and heat stability needs determine formulation choices.
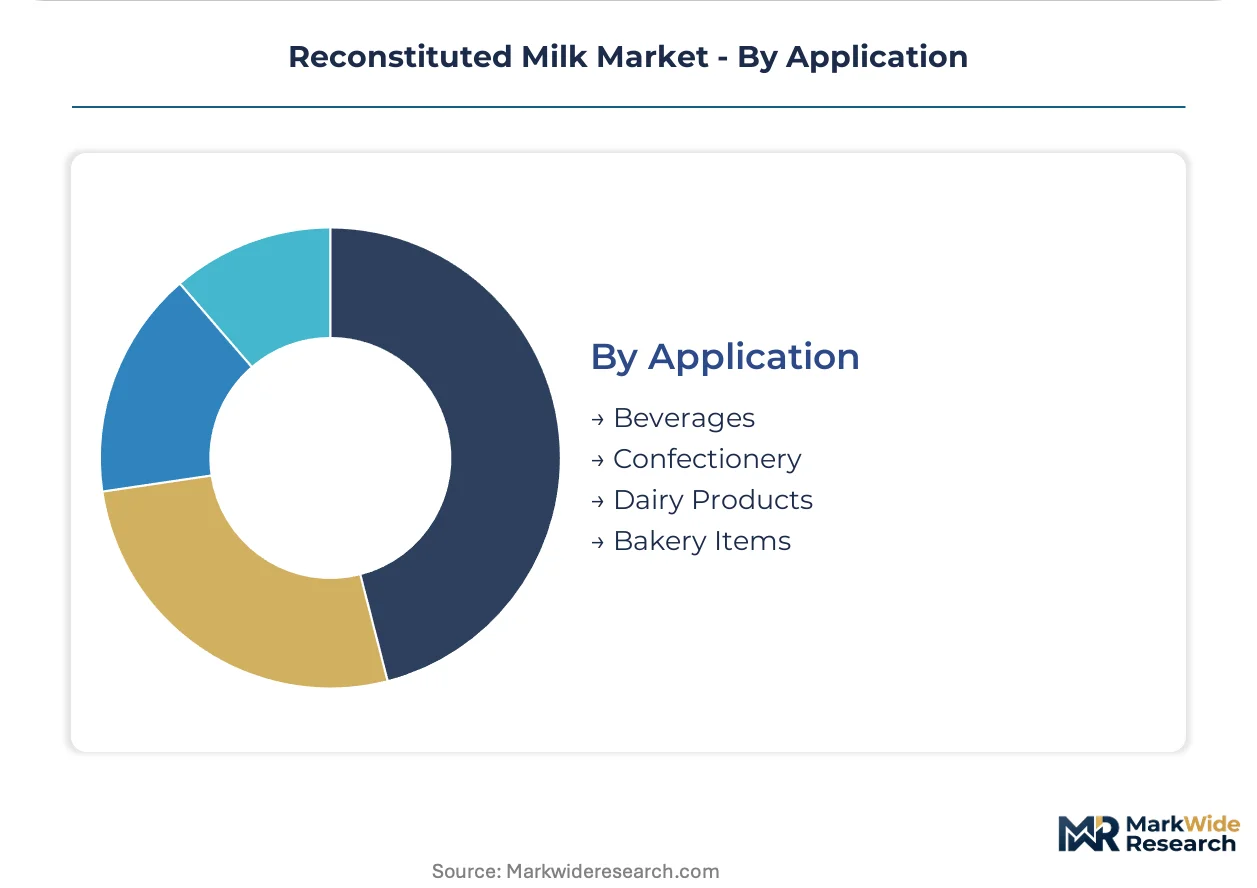
- Beverages:Reconstituted milk serves as base for UHT drinks, flavored milks, and fountain dispensed products. Southeast Asian urban consumption outpaces domestic fresh supply.
- Bakery Items:Bread, cake, and pastry applications requiring specific solids content and fat distribution for crumb structure and shelf life.
- Confectionery:Chocolate and candy manufacturing demanding precise milk fat ratios and low moisture content for texture control.
- Dairy Products:Yogurt, ice cream, and cheese production using reconstituted solids where fresh milk availability is seasonal or geographically constrained.
Beverages anchor current volume; Bakery Items show the steepest expansion trajectory as institutional feeding programs scale in Sub-Saharan Africa.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New Zealand's pastoral dairy base anchors powder production that feeds reconstitution demand across Southeast Asia and Sub-Saharan Africa. Geographic concentration of spray-drying capacity in Oceania and Europe creates supply-side dependencies that shape procurement patterns in deficit markets.
Indonesia
Urban dairy consumption in Jakarta and Surabaya outstrips domestic fresh milk supply by a factor of three, forcing beverage manufacturers to rely on reconstituted inputs. BIS quality specifications govern import standards for milk powder rehydration ratios. Quick-service restaurant chains in Java consolidate procurement through centralized platforms, bypassing traditional dairy distributors.
Vietnam
Ho Chi Minh City and Hanoi drive institutional demand for UHT beverages manufactured from reconstituted bases. The country's national food safety regulator enforces microbial thresholds for imported dairy solids. Vietnamese processors in the Mekong Delta region adopt membrane pre-concentration to reduce spray-dryer energy loads.
Germany
EU F-Gas Regulation mandates phasedown of hydrofluorocarbon refrigerants in industrial cooling systems through 2030. EFSA sustainability disclosure requirements tighten carbon accounting for Scope 2 emissions in spray-drying operations. Facilities in Bavaria and North Rhine-Westphalia retrofit ammonia-based refrigeration for powder storage.
Netherlands
Toll-processing capacity clusters around Rotterdam and the Gelderland corridor, creating geographic supply risk for Asian formulators. EU Green Deal carbon accounting incentivizes processors to source from renewable-powered facilities. Dutch dairy blend processors face accelerated depreciation schedules reconciling legacy equipment with compliance deadlines.
India
Maharashtra and Gujarat attract greenfield spray-drying investments under the PLI scheme for food processing infrastructure. FSSAI quality specifications certify rehydration ratios for institutional feeding programs. Dairy cooperatives in Anand and Mumbai supply reconstituted inputs to bakeries seeking cost-stable alternatives to fresh milk.
Reconstituted Milk Market Competitive Landscape
Global majors compete with regional champions across backward integration into milk powder processing and formulation consistency capabilities. The vendor base organizes around three tiers: Oceania-based cooperatives controlling upstream powder supply, European dairy conglomerates specializing in cream and blend outputs, and Asian processors leveraging proximity to deficit markets. Strategic moves concentrate on geographic expansion of blending facilities and membrane filtration technology licensing.
Within the cooperative archetype, Fonterra Co-operative Group exemplifies backward integration into spray-drying operations that anchor supply to Southeast Asian formulators. Nestlé S.A. and Lactalis occupy positions spanning premium dairy blends and mass-market powder distribution, representing the integrated multinational tier that bridges Oceania raw material access with European food service channel penetration.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Fonterra Co-operative Group |
| Lactalis |
| Arla Foods |
| Danone S.A. |
| Dairy Farmers of America |
| Saputo |
| Yili Group |
| Mengniu Dairy |
| Others |
Value Network & Pricing Analysis
Backward integration into Oceania spray-drying operations anchors both supply security and pricing power for processors serving Southeast Asian deficit markets. Fonterra's captive powder production in New Zealand insulates reconstitution margins from spot-market volatility while compressing procurement layers for Indonesian beverage manufacturers.
Pricing Analysis
After-sales service bundling separates contract structures in this market, with large Indonesian processors securing dedicated technical support and lot-traceability documentation that smaller Vietnamese bakeries forgo for lower unit costs. Three-tier pricing structure across premium, standard, and economy levels tracks fat content specifications and rehydration ratio precision, with EU-origin powders commanding premiums for EFSA-compliant carbon disclosures. Cost compression in economy tiers intensifies because Nigerian institutional buyers prioritize vegetable-fat dairy blends over pure milk solids. Quick-service restaurant chains exhibit lowest price sensitivity due to operational simplicity premiums, while artisan bakeries in Kenya face acute margin pressure.
Supply Chain Analysis
Single-source vulnerability sits with New Zealand and Netherlands toll-processing clusters, where geographic concentration of multi-stage spray-dryers creates supply risk for Asian formulators. Raw material flows draw from Oceania pastoral milk solids, European cream inputs, and Indian SMP exports under PLI scheme incentives. Tariff exposure runs through EU F-Gas Regulation compliance costs that accelerate facility depreciation schedules. Distribution runs through Rotterdam and Auckland port clusters before final-mile delivery to Jakarta and Ho Chi Minh City reconstitution plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spray-dryer capacity constraints in Oceania and Europe prop pricing premiums, with EU F-Gas retrofit timelines compressing available toll-processing slots through the projection horizon.
For Market Incumbents: Cement backward integration into renewable-powered spray-drying facilities in Gujarat and Maharashtra to capture PLI scheme subsidies and reduce Scope 2 exposure. Lock long-term offtake agreements with Indonesian quick-service chains before digital procurement platforms disintermediate distributor relationships. Prioritize membrane pre-concentration technology licensing to Thai and Malaysian processors seeking energy cost reductions.
For New Entrants and Emerging Players: Membrane filtration expertise offers entry leverage into Vietnamese UHT beverage manufacturing, where incumbent processors lag in ultrafiltration adoption. Target Sub-Saharan African institutional feeding programs in Nigeria and Kenya, where cold chain gaps favor shelf-stable reconstituted formats over fresh milk alternatives. Pursue direct-to-manufacturer e-procurement platforms connecting bakeries with Oceania powder exporters, bypassing layered wholesaler markups.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by Oceania cooperatives seeking Southeast Asian blending capacity, or vertical integration by quick-service restaurant chains controlling fountain beverage supply. Mid-cap dairy blend specialists with EU food service channel penetration and F-Gas-compliant refrigeration infrastructure represent priority targets. Watch membrane filtration adoption rates in Thai and Malaysian facilities as inflection indicator for energy cost competitiveness and facility relocation decisions.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Spray-Drying | Fonterra's New Zealand powder production secures supply to Indonesian beverage manufacturers. |
| Membrane Filtration Licensing | Ultrafiltration pre-concentration reduces energy loads for Thai UHT processors by fifteen to twenty percent. |
| Digital Procurement Platform Launch | Centralized ingredient platforms bypass traditional dairy distributors in Java and Manila. |
| Renewable-Powered Facility Siting | EU Green Deal carbon accounting incentivizes relocation to markets with lower renewable energy tariffs. |
| F-Gas Refrigerant Retrofit | Ammonia-based cooling systems in German and Dutch facilities reconcile legacy equipment with compliance deadlines. |
Research Methodology
Multi-period observation of spray-dryer capacity utilization, EU F-Gas retrofit timelines, and Southeast Asian import volumes anchored the trend analysis, supplemented by interviews with spray-drying plant engineers, Indonesian beverage procurement managers, Dutch dairy blend R&D directors, and Kenyan institutional feeding program coordinators. Secondary validation drew from customs trade data, EFSA sustainability disclosure filings, BIS quality specification registers, and SEC 10-K filings of listed dairy processors. Bottom-up facility capacity modeling and top-down consumption forecasting were triangulated against PLI scheme investment announcements.
Segment-weighting across product type, end user, and distribution channel dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from elasticity-adjusted consumption trajectories, with cross-segment calibration against membrane filtration adoption rates and quick-service restaurant fountain beverage consolidation patterns. Industry-specific inputs included EU F-Gas Regulation compliance cost curves and renewable energy tariff differentials across spray-drying facility locations.
Several conditions sit outside the modeled scope, including unannounced PLI scheme modifications, abrupt EU refrigerant phaseout accelerations, and plant-based protein isolate substitution rates in quick-service applications. Forecasts reflect documented assumptions about energy cost trajectories and trade flow continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
A2 Protein Milk Market
Dairy Products
Fat-Filled Milk Powder Market
Dairy Products
South America Flavored Milk Market
Dairy Products
Fat-Rich Dairy Products Market
Dairy Products
Saudi Arabia Camel Dairy Market
Dairy Products
Low Cholesterol Cheese Market
Dairy Products
US Cheese Market
Dairy Products
China Dairy Market
Dairy Products
Organic Dairy Products Market
Dairy Products
Recombined Milk Products Market
Dairy Products
US and Europe Nuts and Seeds Cheese Market
Dairy Products
Europe Milk Protein Market
Dairy Products
United States Milk Protein Market
Dairy Products
North America Milk Powder Market
Dairy Products
Asia-Pacific Yogurt Market
Dairy Products
Emmental Cheese Market