
 US Yogurt and Probiotic Drink Market | 2026-2036
US Yogurt and Probiotic Drink Market Size, Share, and Industry Trends Forecast 2026-2036
US Yogurt and Probiotic Drink Market Insights
Single-serve pouch formats is decoupling from multi-pack cup bundling, giving buyers flexibility to mix flavors without committing to bulk SKUs. Chobani LLC leverages its upstate New York manufacturing scale to anchor conventional retail shelf space. Danone competes through specialized probiotic strain portfolios that differentiate its drinkable yogurt lines. Lifeway Foods Inc. dominates the kefir subcategory with tight control over fermented dairy supply chains.
US Yogurt and Probiotic Drink encompasses cultured dairy and plant-based beverages containing live microbial cultures, typically formulated with Lactobacillus and Bifidobacterium strains at minimum counts of 10^8 CFU per serving, produced via controlled fermentation at 37–43°C for 4–12 hours to achieve target pH and texture. Greek Yogurt occupies the largest margin pool due to protein concentration and premium positioning, while Probiotic Shots represent the fastest-growing configuration as consumers prioritize convenience and targeted digestive health dosing. Drinkable Yogurt sustains volume leadership through broad supermarket distribution, though Traditional Yogurt faces maturity pressure from format innovation.
The FDA governs live culture identity labeling and health claim substantiation under FFDCA and DSHEA frameworks, while USDA Organic certification shapes ingredient sourcing requirements for premium tiers. State-level dairy inspection programs, particularly in California and Wisconsin, enforce additional safety protocols that influence regional production siting decisions. Stakeholders must monitor evolving positions from the FTC on gut health advertising claims as enforcement intensity fluctuates with administrative priorities.
Market Dynamics
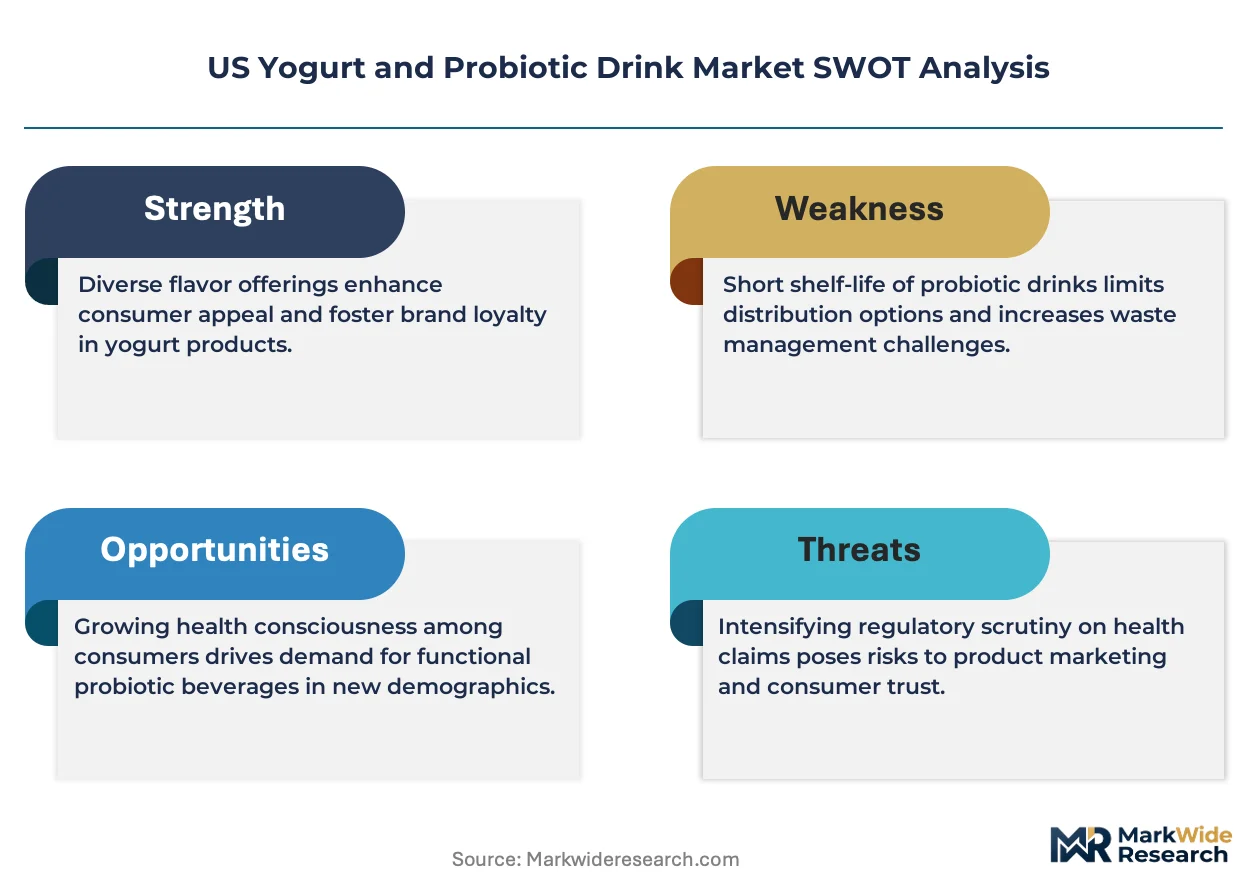
The FDA's updated Nutrition Facts labeling requirements for added sugars are forcing reformulation across conventional and Greek yogurt portfolios, compressing margin structures while creating openings for clean-label challengers.
Growth Catalysts
- Millennial Functional Beverage Demand:Health-conscious consumers aged 25-40 prioritize digestive wellness and protein density, driving trial of probiotic shots and drinkable formats in California's innovation corridor and Northeast premium retail channels.
- USDA Organic Certification Tailwinds:Premium tier expansion accelerates as ingredient sourcing requirements for organic dairy and plant-based bases attract price-insensitive households seeking live culture guarantees.
- Fermentation Process Innovation:Controlled fermentation at 37-43°C for 4-12 hours now achieves target pH and texture with reduced sugar substrates, enabling cleaner labels without sacrificing shelf stability.
Market Restraints
- Dairy Input Cost Volatility:Fluid milk price swings in Wisconsin and California concentrate margin pressure on conventional yogurt producers lacking contracted supply agreements.
- Live Culture Supply Concentration:Lactobacillus and Bifidobacterium strain production clusters with limited fermentation capacity providers, creating bottleneck risk for scaled probiotic drink launches.
- Plant-Based Substitution Threat:Oat and almond milk alternatives with added cultures capture lactose-intolerant and vegan households, eroding addressable market for dairy-based probiotic beverages.
Strategic Opportunities
- Single-Serve Pouch Format White Space:Flexible packaging decouples from multi-pack cup bundling, letting buyers mix flavors without bulk SKU commitment in convenience and club channels.
- FTC Gut Health Claim Clarity:Evolving enforcement positions on digestive advertising create first-mover advantage for substantiated probiotic strain portfolios with clinical documentation.
- Kefir Subcategory Expansion:Tight fermented dairy supply chain control enables geographic extension beyond current strongholds into underpenetrated Southwest and Mountain West metro markets.
Industry Challenges
- Fermentation Science Talent Scarcity:Industrial microbiologists with dairy culture expertise command premium compensation, constraining R&D velocity for mid-tier processors.
- Dual Certification Timeline Friction:Simultaneous FDA live culture identity compliance and USDA Organic accreditation extends new product introduction cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Yogurt and Probiotic Drink Market |
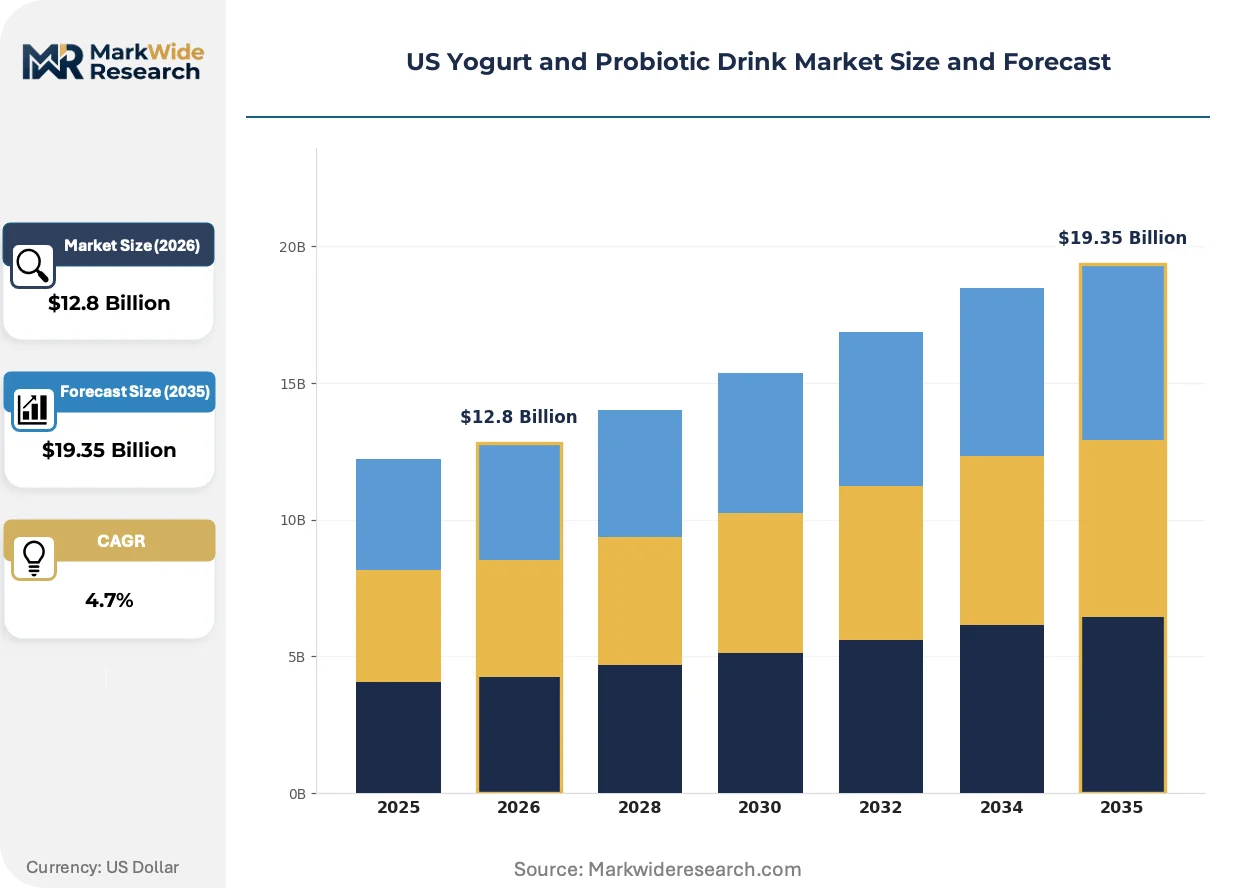
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $19.35 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Yogurt, Greek Yogurt, Drinkable Yogurt, Probiotic Shots Flavor: Vanilla, Strawberry, Blueberry, Peach Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Health Stores Packaging Type: Cups, Bottles, Pouches, Tetra Packs |
| Companies Covered | Lifeway Foods Inc., Califia Farms LLC, Chobani LLC, KeVita, Bio-K+ International, Danone, Grupo Lala, Goodbelly Probiotics, Yakult Honsha Co. Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Yogurt and Probiotic Drink Market Trends and Innovations
Precision fermentation and strain-specific clinical substantiation are rewriting competitive rules, separating commodity yogurt from premium probiotic positioning.
Aseptic processing technology is converging with high-pressure processing to extend refrigerated shelf life without thermal degradation of live cultures. Regional dairy processors in upstate New York and California's Central Valley adopt these hybrid systems to support direct-to-subscription models. The convergence is compressing traditional cold chain cost structures while enabling national distribution for previously local kefir and drinkable yogurt brands.
The FDA's updated Nutrition Facts labeling requirements for added sugars are mandating gram-level disclosure on front-facing panels. Reformulation teams are stripping sucrose and fruit concentrates from conventional lines, redirecting R&D spend toward natural sweetener blends and post-fermentation flavor systems. Greek yogurt portfolios face the steepest adjustment burden given their historical reliance on fruit preparations for palatability masking.
Subscription-based replenishment is displacing conventional supermarket stock-up behavior among urban millennial households. Direct-to-consumer platforms with customizable flavor rotations and flexible delivery intervals capture lifetime value from high-frequency probiotic users. This channel shift concentrates in Northeast corridor cities and Pacific Northwest metros where cold chain logistics density supports reliable home delivery economics.
US Yogurt and Probiotic Drink Market Segmentation
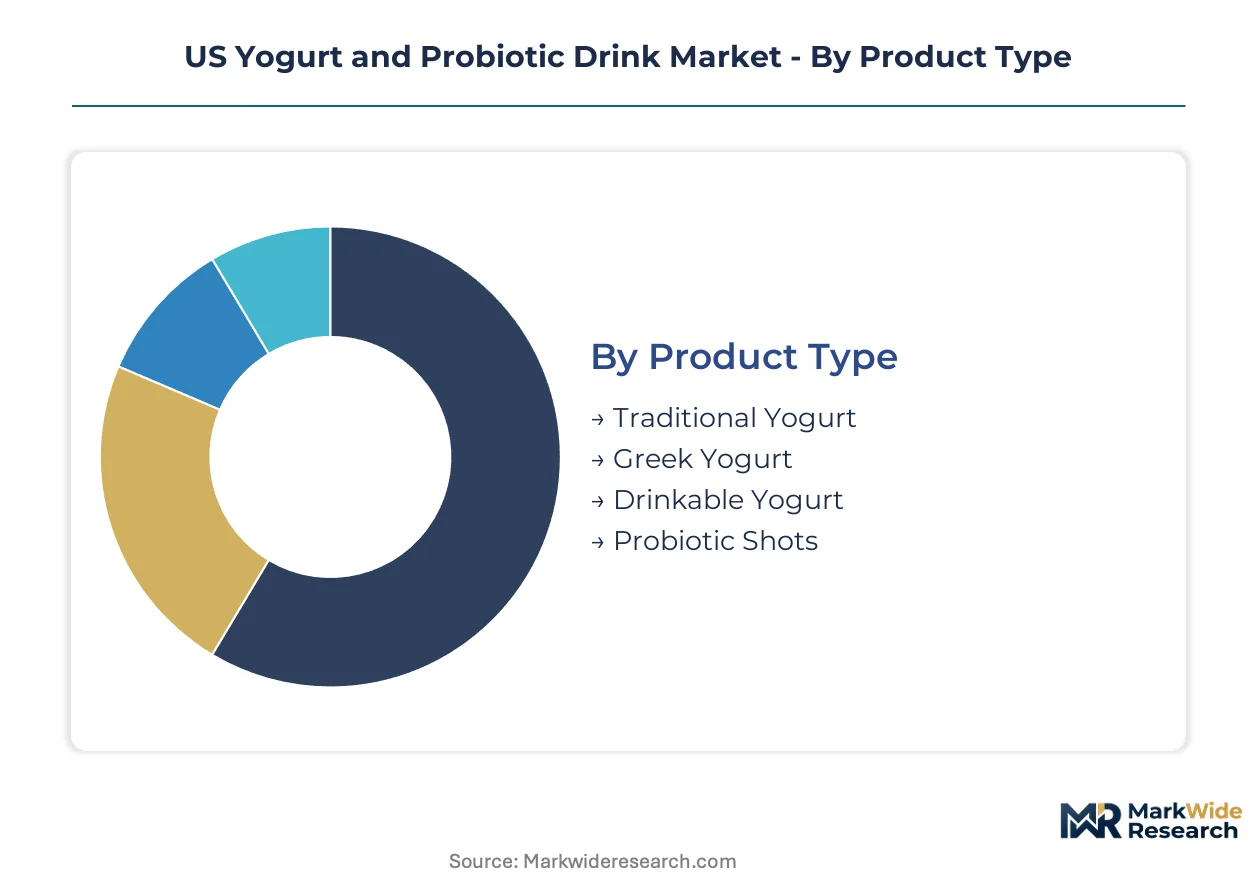
Segmentation in the US Yogurt and Probiotic Drink Market reveals how format innovation and channel strategy determine margin capture. Product architecture and packaging flexibility now outweigh flavor variety as primary purchase drivers among millennial households.
Product Type:
Customization intensity varies sharply across this category, from commodity bulk formats to precision-dosed functional shots requiring strain-specific fermentation protocols.
- Greek Yogurt:Protein concentration through straining removes whey and lactose, achieving 15-20g protein per serving. Demand concentrates in Northeast premium retail channels where USDA Organic certification commands price premiums. FDA added-sugar labeling compliance has forced reformulation of fruit preparations, compressing conventional line margins.
- Probiotic Shots:Concentrated 2-3 ounce formats deliver 10^10+ CFU per serving through controlled fermentation at 37-43°C. California's innovation corridor drives trial among health-conscious millennials prioritizing digestive wellness dosing over meal replacement. Strain-specific clinical substantiation separates premium positioning from commodity cultured dairy.
- Drinkable Yogurt:Fluid viscosity enables broad supermarket distribution through conventional cold chain logistics. Shelf-stable aseptic variants extend reach into convenience channels lacking refrigerated infrastructure.
- Traditional Yogurt:Mature cup formats face displacement from Greek and drinkable alternatives. Remains relevant for price-sensitive households and institutional foodservice procurement.
Leading the category by volume: Drinkable Yogurt. Growing fastest: Probiotic Shots.
Flavor:
Cost tier stratification in this category separates natural fruit preparations from artificial flavor systems, with organic certification premiums widening price spreads.
- Strawberry:Most purchased flavor profile across all age demographics, though reformulation costs spiked with FDA added-sugar disclosure requirements. Natural fruit concentrate substitution now dominates premium tier development.
- Blueberry:Antioxidant association drives placement in health store channels and subscription-based direct-to-consumer platforms. Pacific Northwest metro markets show disproportionate per-household consumption.
- Vanilla:Neutral base enables clean-label positioning with minimal ingredient complexity. Preferred by parents purchasing for children and households seeking versatile smoothie ingredients.
- Peach:Seasonal production cycles create supply volatility for fresh fruit preparations. Regional preference concentration in Southeast and Southwest markets.
Strawberry maintains volume leadership. Blueberry posts the steepest expansion trajectory through health-channel distribution.
Distribution Channel:
Customer type segmentation separates stock-up behavior from immediate consumption needs, with channel choice correlating to household size and urban density.
- Supermarkets:Primary volume channel for multi-pack cup bundling and Greek yogurt shelf placement. Chobani LLC anchors conventional retail space through upstate New York manufacturing scale.
- Online Retail:Subscription replenishment models capture lifetime value from high-frequency probiotic users. Cold chain logistics density in Northeast corridor and Pacific Northwest metros enables reliable home delivery economics.
- Convenience Stores:Single-serve pouch and bottle formats target immediate consumption occasions. Limited refrigerated space favors drinkable yogurt over cup formats.
- Health Stores:Specialized probiotic strain portfolios and USDA Organic certification drive placement. Danone and Lifeway Foods Inc. compete through differentiated culture claims and kefir subcategory dominance.
Supermarkets retain volume dominance. Online Retail climbs fastest through millennial household penetration.
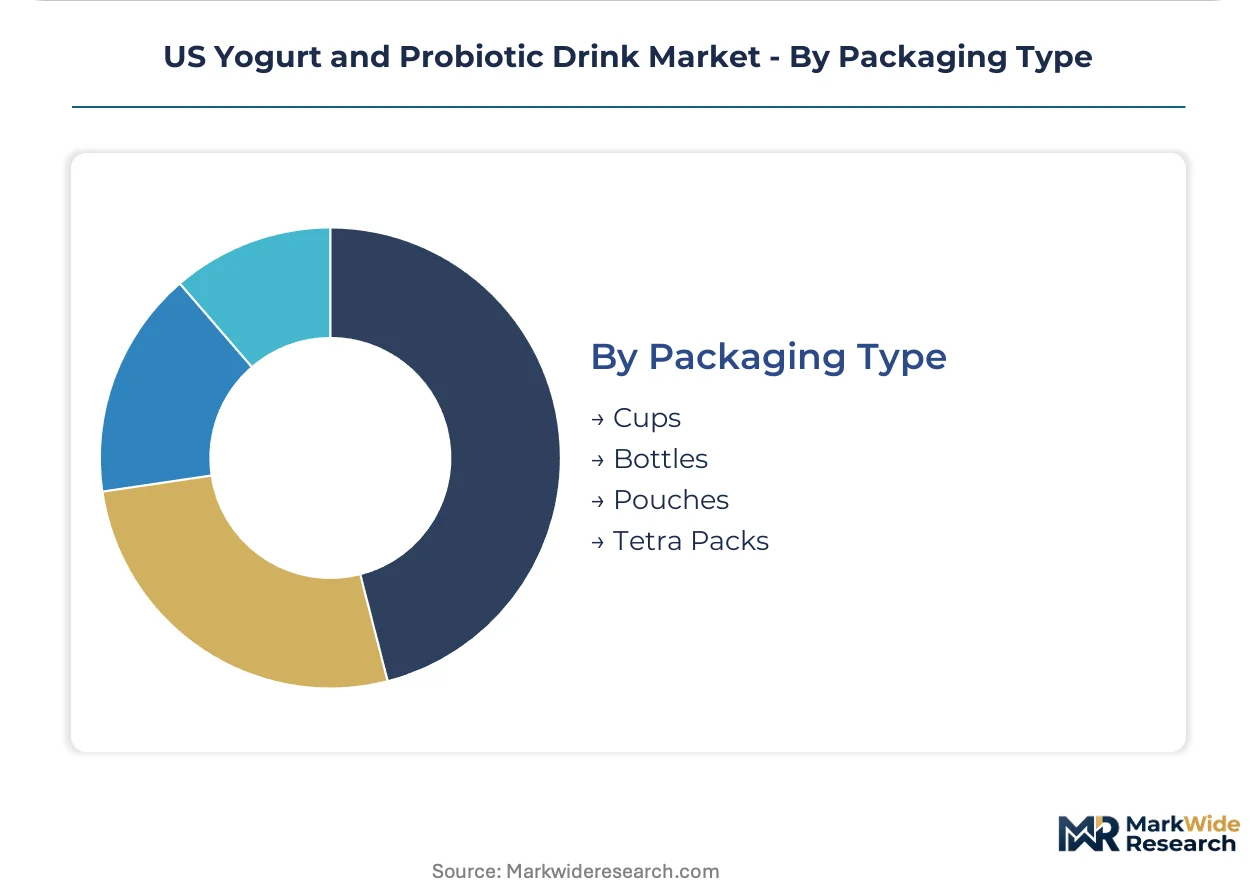
Packaging Type:
Supply concentration in flexible film and aseptic carton manufacturing shapes regional availability and cost structures for format innovation.
- Pouches:Flexible single-serve packaging decouples from multi-pack cup bundling, enabling flavor mixing without bulk SKU commitment. Adoption concentrates in convenience and club channels.
- Bottles:Drinkable yogurt standard format supports resealability and on-the-go consumption. PET and HDPE resin cost volatility affects margin structures.
- Cups:Mature format faces displacement despite established recycling infrastructure. Multi-pack bundling remains standard for traditional and Greek yogurt.
- Tetra Packs:Aseptic processing enables ambient distribution without cold chain dependency. Shelf-stable probiotic claims require high-pressure processing to preserve live culture viability.
Cups lead by volume. Pouches gain share fastest through format flexibility and channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Wisconsin and California's dairy belts while consumption tilts toward coastal metros with premium retail infrastructure. This geographic split shapes cold chain logistics investment and regional formulation priorities. State-level dairy inspection programs add compliance layers that influence siting decisions for new fermentation capacity.
California
Health-conscious millennials in Los Angeles and San Francisco drive trial of probiotic shots and plant-based alternatives. The California Department of Food and Agriculture enforces additional safety protocols beyond federal baselines. Central Valley dairy processors cluster near Modesto and Fresno to capture fluid milk supply while serving West Coast distribution networks.
New York
Upstate New York anchors conventional retail shelf space through scaled Greek yogurt manufacturing serving Northeast corridor demand. New York State Department of Agriculture and Markets operates stringent dairy inspection programs. The Finger Lakes region hosts fermentation science talent pools drawn from Cornell University research programs.
Wisconsin
Fluid milk price volatility concentrates margin pressure on processors lacking contracted supply agreements. The Wisconsin Department of Agriculture, Trade and Consumer Protection maintains legacy dairy grading infrastructure. Green Bay and Eau Claire metros concentrate kefir and traditional yogurt production leveraging regional milk cooperatives.
Texas
Population growth in Dallas-Fort Worth and Houston expands addressable market for drinkable yogurt formats in convenience channels. The Texas Department of State Health Services aligns with FDA frameworks for live culture identity labeling. Austin's innovation corridor attracts plant-based probiotic startups targeting lactose-intolerant households.
Florida
Retiree demographics sustain demand for digestive wellness positioning in probiotic beverages. The Florida Department of Agriculture and Consumer Services regulates dairy processing under state-specific inspection schedules. Miami-Dade and Tampa Bay metros concentrate distribution hubs serving Southeastern retail expansion.
US Yogurt and Probiotic Drink Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Danone and Grupo Lala leverage multinational dairy portfolios to secure retail shelf space through volume commitments. Three archetypes dominate: multinational CPG platforms with fermented dairy heritage, domestic specialists controlling kefir supply chains, and plant-based challengers substituting oat and almond bases. Competitive moves center on strain-specific clinical substantiation and aseptic processing capacity expansion.
Within the specialist tier, Lifeway Foods Inc. and Chobani LLC exemplify divergent scale strategies. Danone occupies a position bridging multinational resources with probiotic strain differentiation. These three anchors represent how geographic production clustering and format innovation separate margin capture across conventional, premium, and functional positioning tiers.
| Leading Market Players |
|---|
| Lifeway Foods Inc. |
| Califia Farms LLC |
| Chobani LLC |
| KeVita |
| Bio-K+ International |
| Danone |
| Grupo Lala |
| Goodbelly Probiotics |
| Yakult Honsha Co. Ltd. |
| Others |
Pricing and Supply Chain Analysis
Fluid milk price volatility in Wisconsin and California propagates through three-tier pricing structure across premium, standard, and economy levels, with organic certification and live culture density separating margin tiers. Contracted supply agreements insulate integrated processors from spot market swings while forcing smaller players toward commodity positioning.
Pricing Analysis
Margin tightening in conventional yogurt reflects FDA added-sugar labeling compliance costs and natural sweetener substitution. Three-tier pricing structure across premium, standard, and economy levels separates USDA Organic certified products with strain-specific clinical documentation from private-label alternatives. Cost compression accelerates as fruit preparation reformulation expenses concentrate in Greek yogurt portfolios. Price-sensitive households in institutional foodservice procurement drive volume, while health-conscious millennials in California's innovation corridor absorb premium positioning.
Supply Chain Analysis
Returns of expired probiotic inventory and temperature-compromised shipments flow back to regional dairy processors for disposal or animal feed diversion. Supply concentrates in Wisconsin, California, and upstate New York, drawing from fluid milk cooperatives, specialized Lactobacillus and Bifidobacterium strain providers, and aseptic packaging equipment manufacturers. Single-source vulnerability in live culture fermentation capacity creates bottleneck risk for scaled probiotic drink launches. Distribution runs through cold chain logistics networks serving supermarkets, with direct-to-subscription models bypassing traditional wholesale tiers in Northeast corridor and Pacific Northwest metros.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as FDA dual certification timelines and fermentation science talent scarcity force sub-scale processors toward exit or acquisition.
For Market Incumbents: Lock in contracted fluid milk supply agreements in Wisconsin and California to insulate margins from commodity volatility. Deepen backward integration into Lactobacillus and Bifidobacterium strain production to reduce dependency on limited fermentation capacity providers. Anchor shelf space through upstate New York manufacturing scale while defending against plant-based challengers with hybrid dairy-culture positioning. For New Entrants and Emerging Players: Precision fermentation technology offers entry path into probiotic shots segment where strain-specific clinical substantiation separates premium from commodity. Target underpenetrated Southwest and Mountain West metro markets for kefir subcategory expansion beyond current strongholds. Launch through direct-to-consumer subscription platforms with customizable flavor rotations to bypass incumbent-controlled retail gatekeeping. For Investors and Strategic Acquirers: FTC gut health claim enforcement intensity is the leading indicator that substantiated probiotic strain portfolios will command acquisition premiums. Mid-tier processors with USDA Organic certification and aseptic processing capacity present viable targets over a 5-10 year consolidation window. Watch for FDA live culture identity labeling clarifications as signal for regulatory moat widening.| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic Processing Capacity Expansion | Hybrid high-pressure processing systems enable national distribution for regional kefir brands. |
| Strain-Specific Clinical Substantiation | FDA-compliant health claim documentation differentiates premium probiotic positioning from commodity cultured dairy. |
| Direct-to-Consumer Channel Launch | Subscription replenishment models capture lifetime value from high-frequency urban millennial households. |
| USDA Organic Certification Investment | Organic dairy sourcing requirements attract price-insensitive households seeking live culture guarantees. |
| Single-Serve Pouch Format Introduction | Flexible packaging decouples flavor mixing from bulk SKU commitment in convenience channels. |
Research Methodology
USDA dairy production statistics, FDA enforcement action databases, and Nielsen retail audit data formed the secondary backbone, cross-referenced with primary interviews involving fermentation science directors at dairy processors, category buyers at Northeast supermarket chains, and supply chain managers at cold chain logistics providers. Bottom-up volume estimates from SKU-level retail tracking combined with top-down market sizing from fluid milk consumption patterns across the analysis window.
Historical trendline analysis of Greek yogurt protein concentration premiums and probiotic shot adoption rates informed projection modeling across product type, flavor, distribution channel, and packaging format dimensions. CAGRs derived from segmented growth rate differentials weighted by channel penetration trajectories. Forecast inputs incorporated USDA Organic certification expansion curves and FTC gut health claim enforcement intensity fluctuations.
Several conditions sit outside the modeled scope, including sudden fluid milk price spikes exceeding historical volatility bands, FDA live culture identity labeling requirement reversals, and plant-based alternative technological breakthroughs. Forecasts reflect documented assumptions about cold chain infrastructure investment continuity and millennial household formation patterns. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
South America Dairy Protein Market
Dairy Products
Asia-Pacific Flavored Milk Market
Dairy Products
Dairy Based Dressings Market
Dairy Products
Halal Cheese Market
Dairy Products
India Milk Protein Market
Dairy Products
Ready-To-Use Cheese Market
Dairy Products
Sweetened Condensed Milk Market
Dairy Products
A2 Milk Market
Dairy Products
Textured Butter Market
Dairy Products
Reduced Fat Dairy Market
Dairy Products
Middle East and Africa Whey Protein Market
Dairy Products
Africa Yogurt Market
Dairy Products
Cheese Packaging Market
Dairy Products
Lactic Butter Market
Dairy Products
Middle East and Africa UHT Milk Market
Dairy Products
Lactose Market