
 Americas Healthcare Archiving and Ediscovery Market | 2026-2036
Americas Healthcare Archiving and Ediscovery Market Size, Share, and Industry Trends Forecast 2026-2036
Americas Healthcare Archiving and Ediscovery Market Analysis
Legacy tape-to-cloud migration revenue is fragmenting across specialized service tiers as healthcare providers unbundle storage from legal-hold management. Microsoft Corporation leverages its Azure cloud fabric to anchor hybrid deployments across integrated delivery networks. IBM Corporation sustains mainframe-to-cloud bridge architectures for organizations with decades of patient records on legacy media. OpenText Corporation specializes in ediscovery workflows that tie directly into clinical document management systems.
Healthcare archiving and ediscovery encompasses the systematic retention, indexing, and legally defensible retrieval of electronic health records, diagnostic imaging, and administrative correspondence, typically requiring tamper-evident audit trails and chain-of-custody documentation for courtroom admissibility. The primary commercial purpose centers on enabling healthcare organizations to satisfy both operational continuity requirements and litigation discovery obligations without compromising patient privacy. Cloud Solutions now lead product-type revenue as hospitals exit capital-intensive on-premises data centers, while Managed Services within the service-type dimension capture expanding margin pools by assuming full operational responsibility for retention-policy enforcement and legal-hold execution. Hybrid Cloud deployment models are gaining fastest among mid-size regional hospital systems seeking to balance control with scalability.
The HIPAA Security Rule administered by the US Department of Health and Human Services mandates access controls and audit logging that directly shape archiving platform specifications, while state-level frameworks such as the California Consumer Privacy Act impose additional data-retention and deletion requirements on multi-state health systems. Health Canada's Personal Information Protection and Electronic Documents Act creates parallel compliance obligations for Canadian providers operating under provincial health authority structures. Stakeholders must monitor how cross-border data-localization disputes between US and Canadian regulators reshape cloud-provider selection criteria for transnational health systems.
Market Dynamics
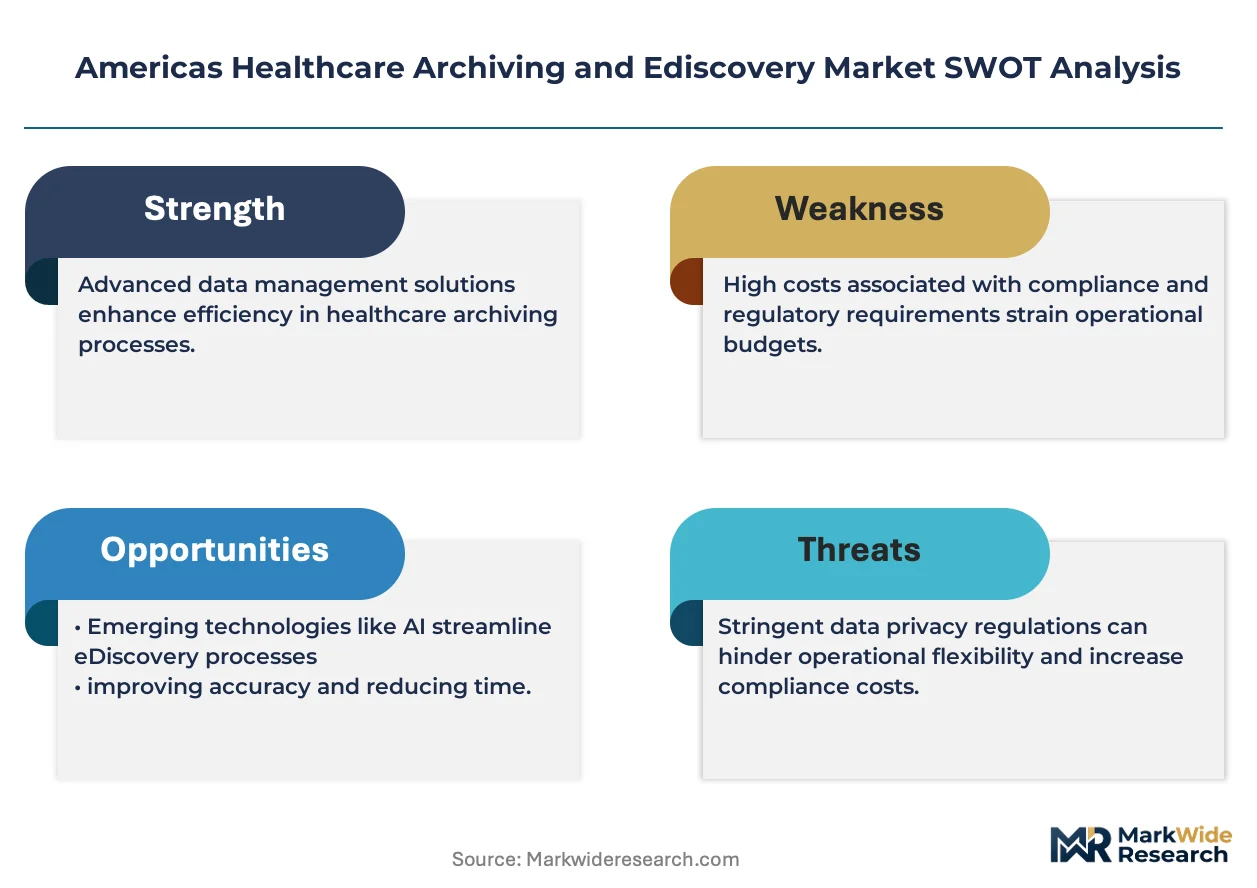
Hospital consolidation across the southeastern United States is compressing vendor relationships into single-source contracts that bundle archiving infrastructure with ediscovery legal-hold management, forcing mid-tier providers to specialize or exit.
Growth Catalysts
- HIPAA Security Rule mandates:Federal audit logging requirements compel healthcare systems to replace legacy tape archives with tamper-evident cloud platforms that satisfy chain-of-custody standards for courtroom admissibility.
- Diagnostic imaging volume:PACS systems generate petabyte-scale DICOM files that overwhelm on-premises storage, driving demand for elastic cloud retention with embedded ediscovery indexing.
- California Consumer Privacy Act:Deletion timelines and patient data portability rights force multi-state health networks to deploy unified archive governance across distributed cloud regions.
Market Restraints
- Cross-border data localization:Disputes between US and Canadian regulators restrict cloud-provider selection for transnational health systems operating under divergent sovereignty frameworks.
- Legacy media conversion costs:Decades of patient records stored on physical tape and optical media require expensive mainframe-to-cloud bridge architectures before cloud migration proceeds.
- Specialized talent scarcity:Clinical informaticists with dual expertise in HIPAA compliance and ediscovery legal-hold protocols command premium compensation that strains regional hospital budgets.
Strategic Opportunities
- Brazilian hospital digitization:Public and private health networks in São Paulo and Rio de Janeiro are launching first-generation digital record retention programs without legacy infrastructure constraints.
- AI-powered ediscovery automation:Natural language processing tools that extract clinical concepts from unstructured physician notes are converging with predictive coding for litigation document review.
- Subscription-based managed services:Regional hospital systems are outsourcing full operational responsibility for retention-policy enforcement to vendors assuming legal-hold execution liability.
Industry Challenges
- Interoperability with EHR systems:Archive platforms must maintain real-time synchronization with Epic, Cerner, and MEDITECH deployments without disrupting clinical workflow performance.
- Chain-of-custody documentation:Ediscovery workflows require immutable audit trails that withstand judicial scrutiny, complicating hybrid cloud architectures with multiple administrative control planes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Americas Healthcare Archiving and Ediscovery Market |
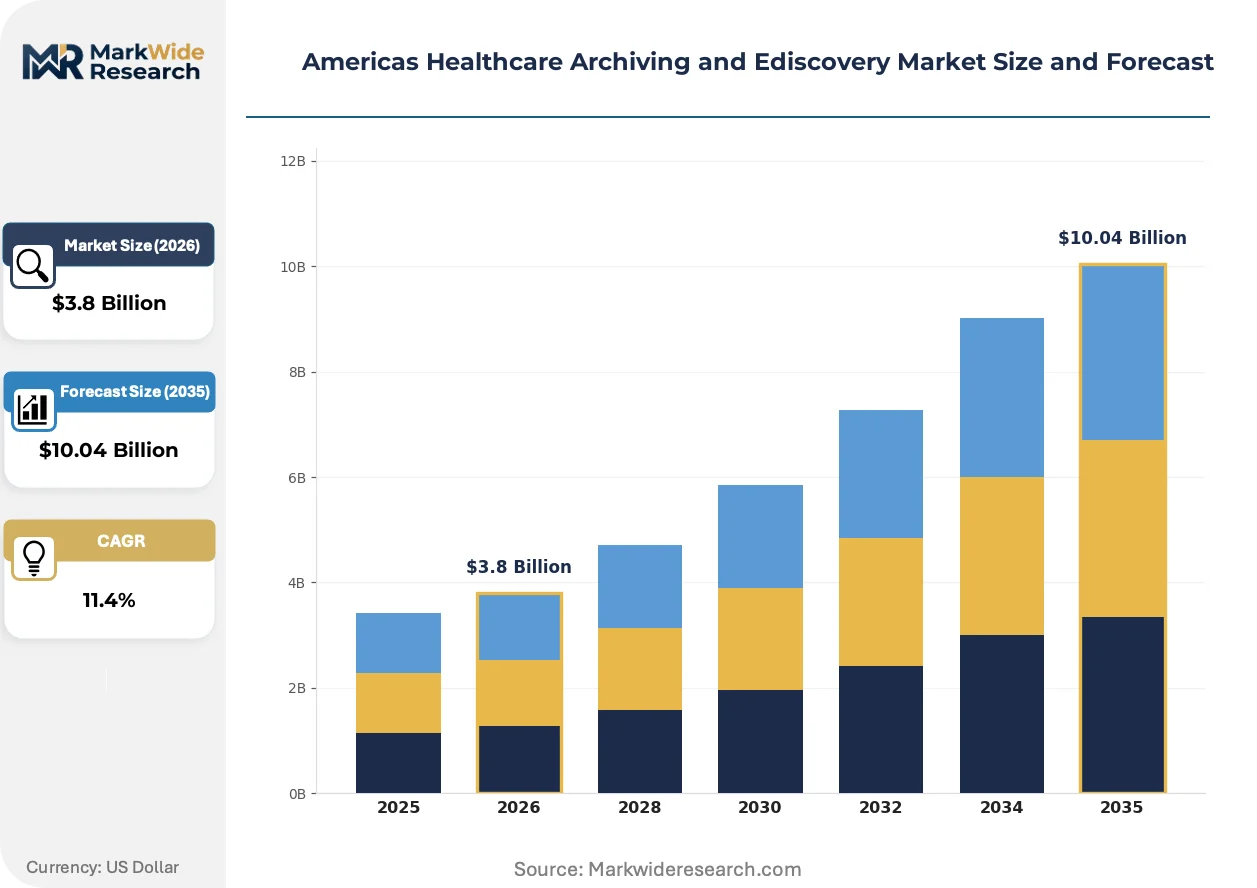
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
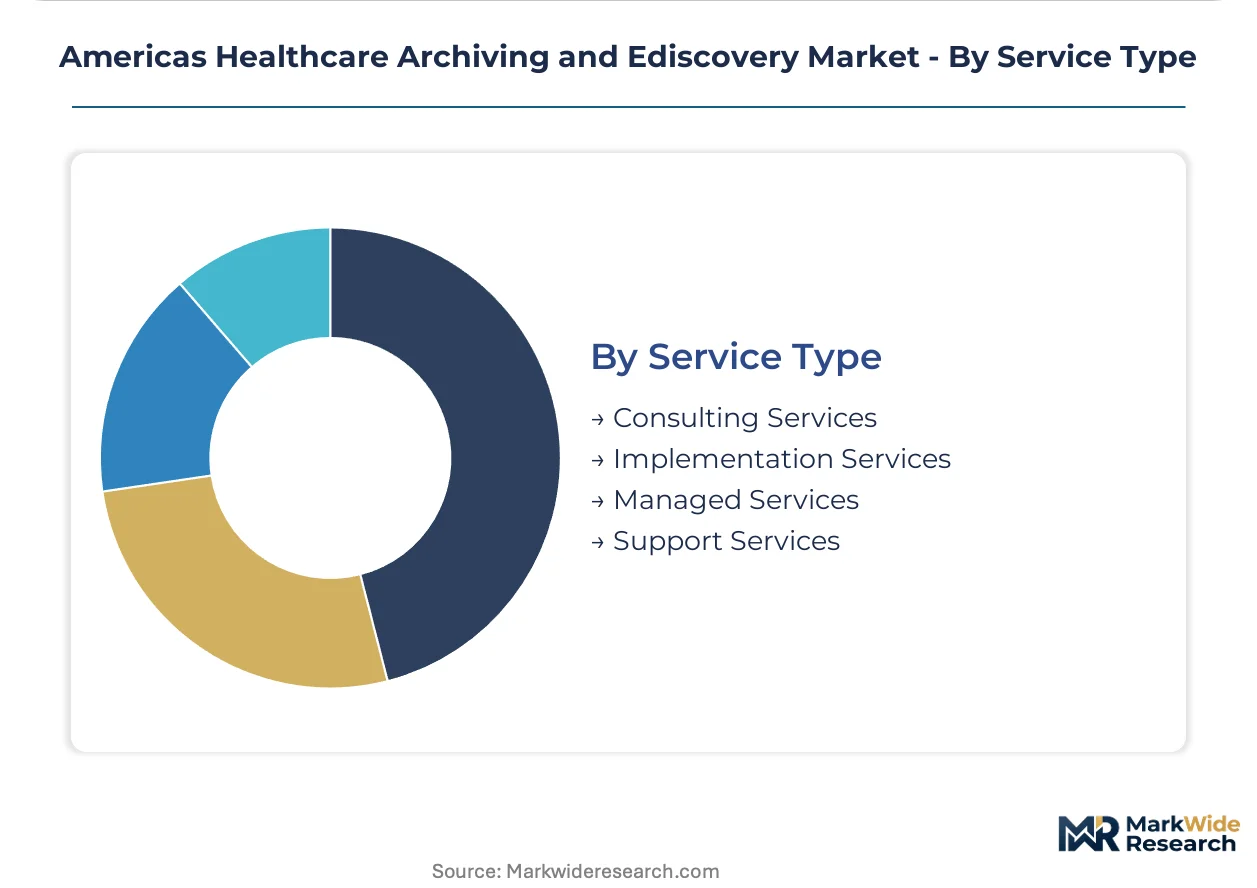
| Segmentation | Product Type: Cloud Solutions, On-Premises Solutions, Hybrid Solutions, Software Solutions End User: Hospitals, Clinics, Pharmacies, Research Institutions Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Service Type: Consulting Services, Implementation Services, Managed Services, Support Services |
| Companies Covered | GE Healthcare, IBM Corporation, Microsoft Corporation, OpenText Corporation, Veritas Technologies, Commvault, Stryker Corporation, Allscripts Healthcare Solutions, Hyland Software, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Americas Healthcare Archiving and Ediscovery Market Emerging Trajectories
Healthcare archiving is pivoting from passive storage repositories to active litigation readiness platforms that embed legal-hold automation directly into clinical document lifecycles.
Immutability-sealed cloud object storage is digitizing the evidentiary foundation of medical malpractice defense. Regional hospital systems in Texas and Florida are deploying write-once-read-many architectures that satisfy Federal Rules of Civil Procedure preservation obligations. This technology is digitizing how legal departments authenticate patient record provenance without retrieving physical media.
The California Consumer Privacy Act and emerging state-level privacy mandates in New York are compressing data-retention timelines while expanding deletion obligations. Health systems must now segment archives by patient residency to apply jurisdiction-specific rules. Integrated delivery networks operating across multiple states are responding by deploying policy engines that automate geographic data routing.
Hospital procurement departments are unbundling storage capacity from ediscovery legal-hold management, treating these as separate vendor relationships. Mid-size regional systems are displacing single-source contracts with specialized providers for each function. This pattern is most visible in the southeastern United States, where consolidated hospital networks negotiate distinct SLAs for clinical continuity versus litigation response.
Americas Healthcare Archiving and Ediscovery Market Segmentation
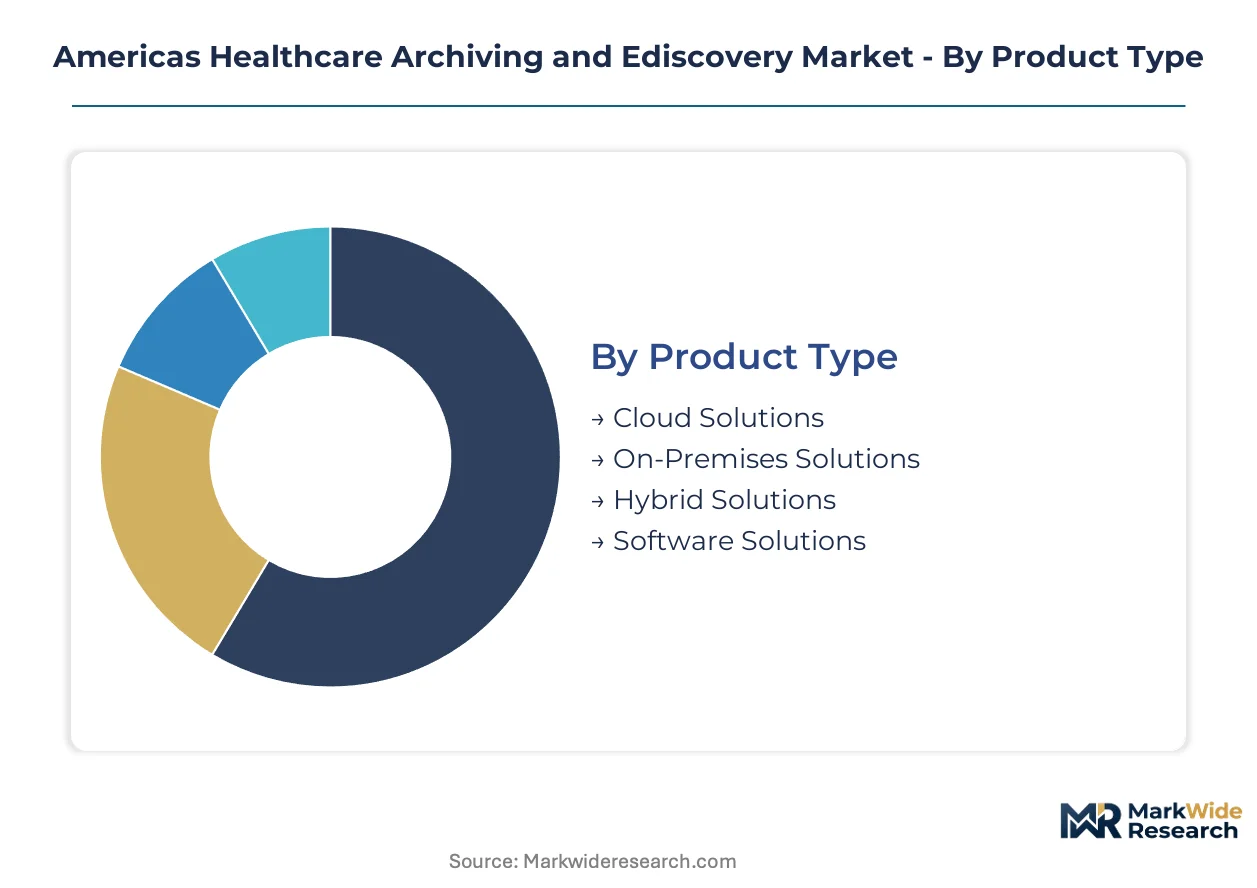
Healthcare archiving and ediscovery vendors configure their portfolios across four distinct dimensions. Each segmentation axis reflects different buyer priorities: capital structure, operational control, clinical setting, and risk tolerance.
Product Type:
Healthcare organizations span a use-case spectrum from fully outsourced cloud retention to tightly controlled on-premises vaults.
- Cloud Solutions:Elastic storage pools with embedded legal-hold indexing and automated retention-policy enforcement. Large hospital systems in Texas and Florida are consolidating vendor relationships around these platforms to satisfy HIPAA Security Rule audit logging mandates without capital expenditure.
- On-Premises Solutions:Dedicated hardware installations within hospital data centers, offering direct physical control over patient record custody. Regional systems in the southeastern United States with legacy compliance officers prefer these for perceived litigation defensibility despite higher operational overhead.
- Hybrid Solutions:Architectures splitting active clinical data on-site with aged archives in cloud tiers. These balance retrieval latency requirements against disaster recovery objectives.
- Software Solutions:Licensed applications deployed across customer-managed infrastructure, appealing to health networks with existing storage investments seeking ediscovery workflow layers.
Established volume favors On-Premises Solutions; emerging adoption favors Cloud Solutions.
End User:
Customer archetypes distribute across acute care, ambulatory, retail pharmacy, and research verticals with divergent retention burdens.
- Hospitals:Integrated delivery networks generating petabyte-scale diagnostic imaging and clinical documentation. Consolidated systems across the southeastern United States are unbundling storage from legal-hold management, creating dual vendor relationships for each function.
- Clinics:Smaller ambulatory settings with lighter archive volumes but identical chain-of-custody requirements for malpractice defense. These buyers favor subscription-based managed services to avoid specialized informaticist hires.
- Pharmacies:Retail chains managing prescription fulfillment records with shorter statutory retention periods than clinical providers. Their procurement emphasizes integration with existing inventory management systems.
- Research Institutions:Academic medical centers handling longitudinal patient cohort data with decades-long retention horizons. These facilities require immutable audit trails supporting federal grant compliance and patent litigation.
Revenue concentration sits with Hospitals; fastest expansion trajectory belongs to Research Institutions facing intensifying data governance scrutiny.
Deployment Model:
Infrastructure topology choices reflect organizational scale, risk appetite, and sovereignty constraints.
- Public Cloud:Shared-tenant environments from hyperscale providers delivering elastic capacity without capital commitment. Brazilian hospital networks in São Paulo are deploying these for first-generation digital retention programs unconstrained by legacy infrastructure.
- Private Cloud:Single-tenant dedicated instances offering administrative isolation for multi-state health systems navigating California Consumer Privacy Act and New York privacy mandate conflicts.
- Hybrid Cloud:Split architectures with clinical continuity systems on-premises and legal-hold archives in cloud tiers. Mid-size regional hospital systems are gaining share fastest here, balancing control with scalability.
- Multi-Cloud:Distributions across multiple provider fabrics to mitigate vendor lock-in and satisfy cross-border data-localization requirements for transnational health systems.
Procurement momentum clusters around Hybrid Cloud; Multi-Cloud remains nascent outside the largest integrated delivery networks.
Service Type:
Commercial relationships stratify by how much operational liability the vendor assumes.
- Managed Services:Full outsourcing of retention-policy enforcement and legal-hold execution, with vendors assuming compliance liability. Regional hospital systems are displacing in-house archive administration to avoid scarce clinical informaticist premiums.
- Consulting Services:Advisory engagements for HIPAA Security Rule gap assessments and legacy tape-to-cloud migration planning. These precede larger implementation contracts.
- Implementation Services:Project-based deployment of archive platforms with EHR system integration, typically scoped around Epic or Cerner synchronization requirements.
- Support Services:Ongoing technical assistance and break-fix coverage for self-managed installations, purchased predominantly by health networks with retained informatics capabilities.
Margin expansion concentrates in Managed Services; project revenue remains concentrated in Implementation Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across the Americas. Brazilian hospital networks prioritize capital-light cloud entry points, while United States integrated delivery networks absorb premium costs for litigation-ready audit trails and HIPAA-mandated chain-of-custody documentation.
United States
Southeastern hospital consolidation drives bundled procurement of archiving infrastructure with ediscovery legal-hold management. HIPAA Security Rule audit logging mandates compel replacement of legacy tape archives with tamper-evident cloud platforms. Texas and Florida regional systems deploy write-once-read-many architectures for medical malpractice defense.
Brazil
Public and private health networks in São Paulo and Rio de Janeiro launch first-generation digital record retention programs unconstrained by legacy infrastructure. ANVISA's evolving data governance framework shapes vendor selection criteria for cloud deployments. São Paulo-based hospital groups negotiate elastic capacity contracts without capital expenditure burdens.
Canada
Provincial health authority structures operate under Health Canada's Personal Information Protection and Electronic Documents Act. Cross-border data-localization disputes with US regulators restrict cloud-provider selection for transnational health systems. Ontario and Quebec integrated delivery networks deploy policy engines for geographic data routing.
Mexico
Federal health digitization initiatives accelerate demand for clinical document retention with embedded legal-hold capabilities. The national pharmaceutical regulator imposes traceability requirements that intersect with archiving platform specifications. Mexico City Metro hospital networks pilot hybrid cloud architectures balancing sovereignty with scalability.
Americas Healthcare Archiving and Ediscovery Market Vendor Landscape
Capability concentration sits with specialized ediscovery workflow vendors; scale advantage sits with hyperscale cloud fabric providers. The market structures around three tiers: legacy mainframe bridge architects, cloud-native platform operators, and vertical-specific clinical document specialists. Consolidation pressures intensify as southeastern United States hospital networks compress vendor relationships into single-source contracts. Dominant competitive moves include strategic partnerships between storage infrastructure and legal-hold management providers, plus geographic expansion into Brazilian first-generation digitization programs.
Within the cloud platform tier, Microsoft Corporation and IBM Corporation anchor hybrid deployment architectures across integrated delivery networks. OpenText Corporation occupies a position among specialized ediscovery workflow providers tying directly into clinical document management systems. These three exemplify the capability-scale tension reshaping procurement patterns.
| Leading Market Players |
|---|
| GE Healthcare |
| IBM Corporation |
| Microsoft Corporation |
| OpenText Corporation |
| Veritas Technologies |
| Commvault |
| Stryker Corporation |
| Allscripts Healthcare Solutions |
| Hyland Software |
| Others |
Supply Flow & Price Mechanics
Overcapacity in legacy tape-to-cloud migration services across the southeastern United States is compressing project margins while driving vendor consolidation toward bundled archiving and legal-hold contracts. This utilization imbalance forces mid-tier providers to specialize in high-margin managed services or exit, reshaping how hospital procurement teams negotiate lifetime value terms.
Pricing Analysis
Managed services revenue tiers now drive lifetime value more than upfront software licensing, with subscription-based legal-hold execution commanding premium positioning. Pricing stratifies across premium, standard, and economy tiers based on HIPAA Security Rule audit trail certification depth and after-sales support bundling. Cost compression in standard-tier cloud storage is intensifying because hyperscale providers are absorbing margin to capture hospital network consolidation contracts. Clinics and ambulatory settings exhibit highest price sensitivity, while research institutions absorb premium costs for immutable audit trail guarantees.
Supply Chain Analysis
Tariff exposure between the United States and Canada dominates supply chain risk for transnational health systems navigating cross-border data-localization disputes. Cloud infrastructure sourcing concentrates in the United States, Brazil, and Canada, with compute capacity drawing from hyperscale provider regions in São Paulo, Texas, and Ontario. Supply chain vulnerability rests on single-source dependencies for specialized clinical informaticist talent and legacy mainframe-to-cloud bridge hardware. Distribution runs through direct vendor relationships with integrated delivery networks, supplemented by group purchasing organization contracts for mid-size regional hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Managed services attach rates are expanding faster than hardware deployment revenue, creating a service-attach opportunity where vendors assume legal-hold execution liability and retention-policy enforcement responsibility.
For Market Incumbents: Insulate core hospital network relationships by embedding legal-hold automation directly into Epic and Cerner EHR synchronization workflows. Acquire specialized clinical document management capabilities to defend against cloud-native platform operators unbundling storage from ediscovery services. Vertical integration into AI-powered ediscovery indexing protects margin pools as predictive coding tools commoditize basic document review functions. For New Entrants and Emerging Players: Brazilian first-generation digitization programs in São Paulo and Rio de Janeiro represent the most penetrable entry point, with public and private health networks launching digital record retention without legacy infrastructure constraints. Mid-size regional hospital systems across Texas and Florida seeking hybrid cloud architectures offer secondary white-space opportunity. A go-to-market angle centered on ANVISA compliance consulting and elastic capacity contracting without capital expenditure requirements accelerates initial footprint. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among managed services providers assuming full operational responsibility for HIPAA-mandated retention-policy enforcement. Long-term viability over a multi-year horizon favors vendors with established legal-hold execution liability frameworks and embedded EHR integration capabilities. The signal to watch is hospital procurement unbundling velocity—accelerated displacement of single-source contracts indicates consolidation pressure and acquisition opportunity.| Strategic Initiative | Industry Significance |
|---|---|
| HIPAA-Compliant Cloud Migration | Replaces legacy tape archives with tamper-evident platforms satisfying Federal Rules of Civil Procedure. |
| AI-Powered Ediscovery Automation | Deploys natural language processing to extract clinical concepts from unstructured physician notes. |
| Managed Services Liability Assumption | Transfers legal-hold execution risk from hospital compliance officers to vendor operations teams. |
| EHR System Integration Partnership | Maintains real-time synchronization with Epic and Cerner deployments without clinical workflow disruption. |
| Brazilian Market Geographic Expansion | Captures first-generation digital retention demand in São Paulo unconstrained by legacy infrastructure. |
Methodological Framework
Operator-level perspectives from hospital compliance officers, clinical informaticists, health system procurement directors, and ediscovery legal-hold managers anchored the qualitative base. Primary interviews combined with secondary validation drawn from HIPAA Security Rule administrative guidance, hospital GPO contract databases, CMS Medicare audit documentation, and hyperscale cloud provider capacity disclosures. Bottom-up sizing of hospital network archive volumes triangulated against top-down market value estimates.
Scenario-bracketing around regulatory enforcement intensity and hospital consolidation velocity shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, deployment model, end user archetype, and service relationship structure, with CAGRs derived from elasticity-adjusted adoption curves and replacement cycle analysis. Forecast inputs incorporated diagnostic imaging volume growth from PACS systems and state-level privacy mandate expansion patterns.
Stress conditions across cross-border data-localization disputes, legacy media conversion cost inflation, and clinical informaticist wage premiums were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about HIPAA audit enforcement consistency and Brazilian ANVISA framework evolution. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Data Management
Global Healthcare Content Management System Market
Health Data Management
Hospital Management Software Market
Health Data Management
Medical Record Management System Market
Health Data Management
Global Big Data Analytics in Healthcare Market
Health Data Management
Point-Of-Care Data Management Software Market
Health Data Management
Global Healthcare Compliance Software Market
Health Data Management
Global Healthcare Data Storage Market
Health Data Management
Healthcare Archiving and Ediscovery Market
Health Data Management
Healthcare Analytics Market
Health Data Management
Europe Healthcare Big Data Analytics Market
Health Data Management
Healthcare Data De-Identification Assurance Market
Health Data Management
Healthcare Data Annotation Tools Market
Health Data Management
Data Democratization in Healthcare Market
Health Data Management
Wireless Healthcare Asset Management Market
Health Data Management
Data Monetization in Healthcare Market
Health Data Management
Patient Data Management Systems Market