
 Global Clinical Trial Supply Management Market | 2026-2036
Global Clinical Trial Supply Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global Clinical Trial Supply Management Market Foresight
Multi-source outsourcing is rebalancing toward integrated single-vendor partnerships as sponsors seek accountability consolidation. Thermo Fisher Scientific leverages end-to-end laboratory and logistics capabilities to anchor large-scale oncology programs. Catalent differentiates through specialized packaging and biologics distribution networks across North America and Europe. Almac sustains competitive positioning with patient-centric supply services and direct-to-patient trial models.
Clinical trial supply management encompasses the procurement, storage, distribution, and return of investigational medicinal products with temperature-controlled handling between minus eighty and plus twenty-five degrees Celsius depending on molecule stability. Its primary purpose ensures patient safety, protocol compliance, and regulatory adherence while minimizing drug waste across decentralized trial sites. Cold chain logistics commands the largest service type segment due to biologics proliferation and stringent stability requirements for cell therapies. Oncology trials represent the dominant application area with the most complex dosing regimens and highest patient volumes. Blockchain integration within technology platforms is gaining traction fastest for chain-of-custody verification and anti-counterfeiting protocols.
FDA oversight through 21 CFR Part 11 and ICH-GCP guidelines shapes electronic records management and audit trail standards for supply documentation. EMA's Clinical Trial Regulation and EU GDP guidelines mandate centralized trial portals and qualified person release for investigational products entering European sites. WHO prequalification programs and ISO 9001 quality management standards further influence vendor selection criteria in emerging markets. Stakeholders must monitor regulatory divergence between FDA risk-based approaches and EU centralized frameworks when designing multi-regional supply strategies.
Market Dynamics
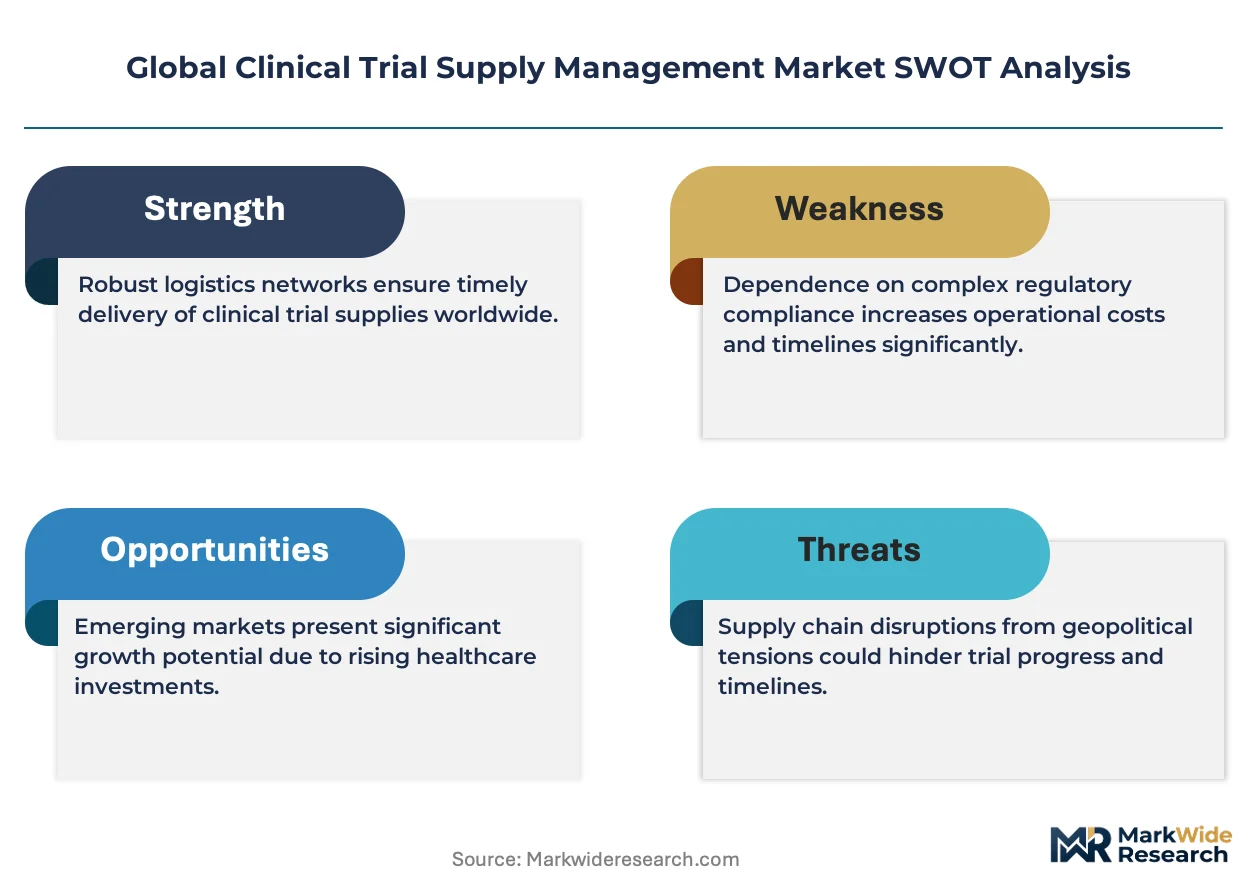
Biologics proliferation is compressing trial timelines and forcing supply chains to absorb ultra-cold infrastructure costs that small-molecule sponsors never faced, reshaping vendor economics across the contract landscape.
Growth Catalysts
- FDA Risk-Based Monitoring Framework:The agency's 2013 guidance and subsequent amendments incentivize sponsors to outsource supply chain oversight to specialized vendors with validated quality systems.
- Cell Therapy Pipeline Expansion:CAR-T and gene therapy trials require minus eighty-degree Celsius distribution networks that only dedicated clinical supply providers can operationalize.
- United States Phase III Concentration:The country's dominance in late-stage oncology trials generates disproportionate demand for integrated comparator sourcing and rescue medication programs.
Market Restraints
- Qualified Personnel Scarcity:The EU GDP mandate for named responsible persons creates bottlenecks as training pipelines fail to match clinical trial expansion rates.
- Specialized Packaging Input Costs:Temperature-validated shippers and phase-change materials face petrochemical price volatility that vendors cannot fully pass through.
- Comparator Sourcing Concentration:Originator drug manufacturers in Switzerland and Germany control release of reference products, creating single-source dependencies.
Strategic Opportunities
- Direct-to-Patient Distribution:Regulatory clarity from the FDA and MHRA enables decentralized trial models that bypass site-based inventory entirely.
- Blockchain-Enabled Chain of Custody:Distributed ledger technology is integrating with existing enterprise resource planning systems to create immutable documentation for regulatory audits.
- Latin American Expansion:Brazil's ANVISA harmonization with ICH-GCP standards reduces regulatory friction for sponsors seeking diverse patient populations.
Industry Challenges
- Cold Chain Qualification Timelines:Thermal packaging validation for cell therapies requires six to twelve months of stability testing that compresses protocol startup windows.
- Legacy System Integration:Sponsor enterprise platforms often lack application programming interfaces compatible with vendor inventory management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Clinical Trial Supply Management Market |
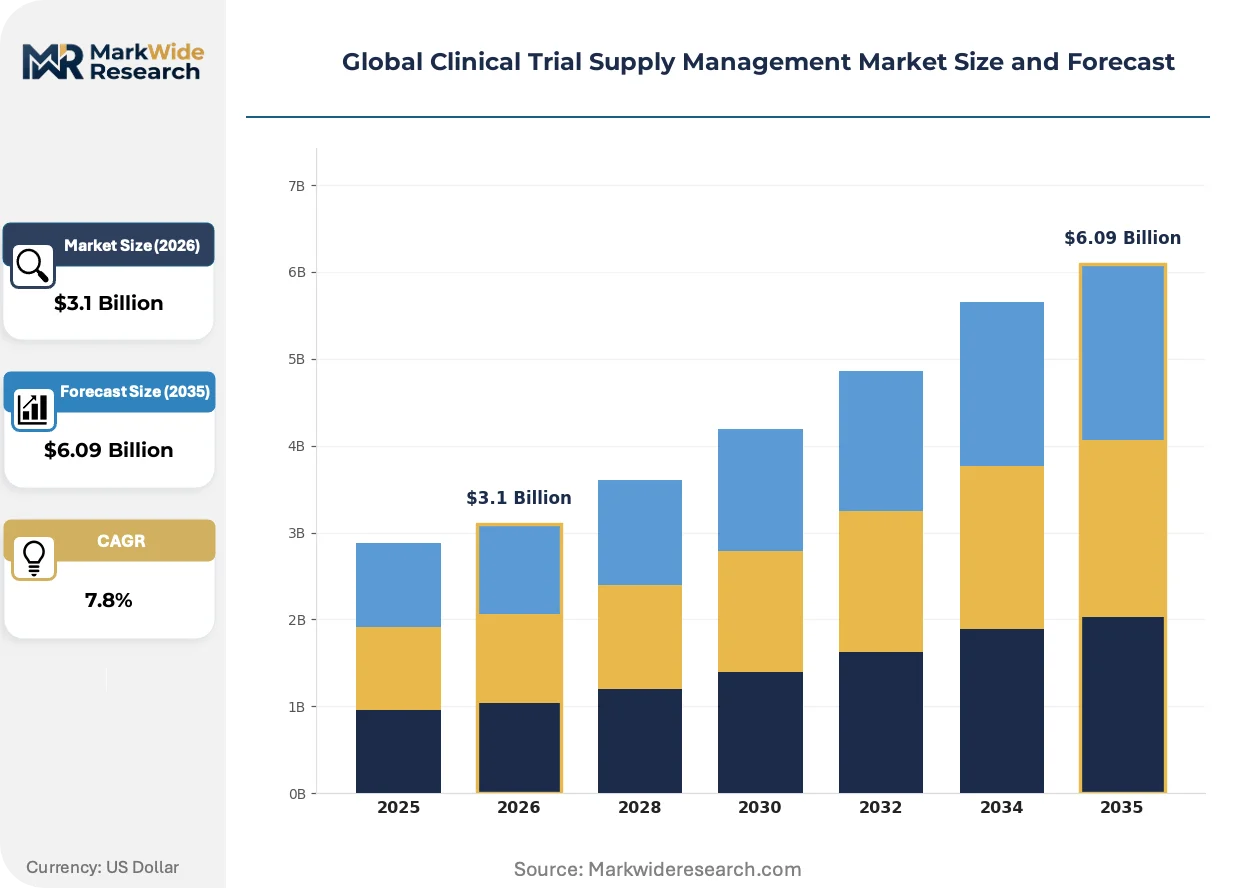
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $6.09 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Inventory Management, Cold Chain Logistics, Packaging Solutions, Distribution Services, Regulatory Compliance, Demand Forecasting Application: Oncology Trials, Cardiovascular Studies, Neurology Research, Infectious Disease Programs, Rare Disease Investigations, Autoimmune Disorders End User: Pharmaceutical Companies, Biotechnology Firms, Contract Research Organizations, Academic Institutes, Specialized Clinics, Government Agencies Technology: Track & Trace Systems, Real-Time Inventory Tracking, Automated Dispensing, Electronic Data Capture, Blockchain Integration, Cloud-Based Platforms |
| Companies Covered | Thermo Fisher Scientific Inc., Catalent Inc., Almac Group, Parexel International Corporation, PCI Pharma Services, Sharp Services, Marken, KLIFO, Lonza, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Clinical Trial Supply Management Market Shifts & Advancements
Digital traceability and decentralized trial infrastructure are displacing paper-based reconciliation and site-centric distribution as the default operating model for investigational product management.
Blockchain-based verification platforms are integrating with serialization databases to create real-time chain-of-custody records. Large pharmaceutical sponsors in oncology and rare disease programs are mandating these capabilities in vendor contracts. The technology is integrating previously siloed manufacturing, distribution, and clinical site data into unified audit trails.
EMA's Clinical Trial Regulation mandates centralized EU trial portals and harmonized submission formats across all member states. This regulatory consolidation eliminates country-specific packaging requirements that previously fragmented supply strategies. Sponsors running multi-national European trials are consolidating vendor relationships to manage single qualified person release processes.
Site-less trial models are compressing traditional distribution hierarchies by shipping investigational products directly to patient residences. This channel innovation demands last-mile cold chain capabilities that conventional logistics providers lack. The United Kingdom and Germany represent the most advanced adoption markets, driven by rare disease patient advocacy and regulatory flexibility.
Global Clinical Trial Supply Management Market Segmentation
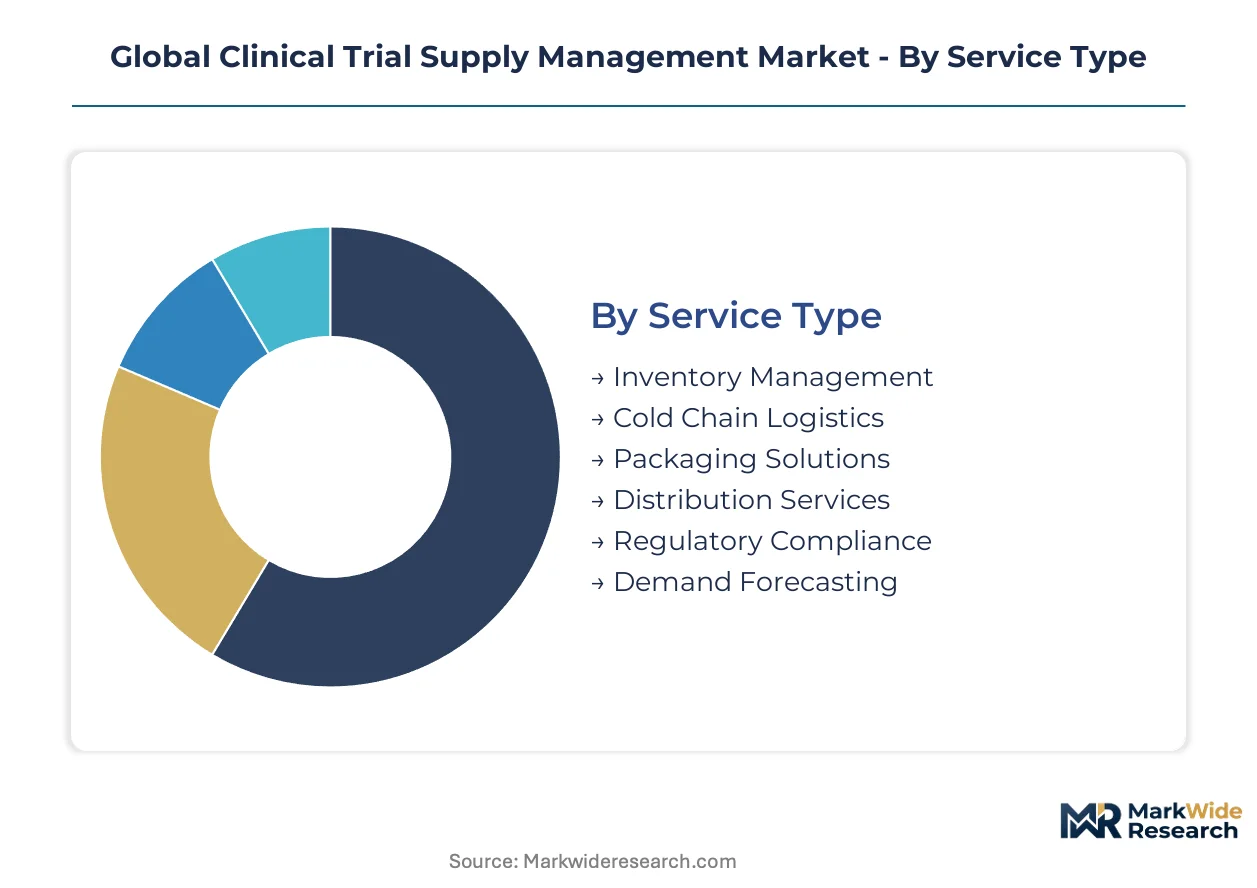
Service specialization within clinical trial supply management determines vendor selection criteria and margin structures across the contract landscape. Segment boundaries blur as integrated providers bundle multiple service layers to capture sponsor procurement consolidation.
Service Type:
Upgrade cycles from paper-based reconciliation to digital inventory platforms are compressing replacement timelines from five-year horizons to eighteen-month refresh mandates.
- Cold Chain Logistics:Temperature-controlled distribution networks spanning minus eighty to plus twenty-five degrees Celsius accommodate biologics stability requirements. Demand concentrates in United States oncology hubs where CAR-T trials require validated ultra-cold infrastructure that conventional logistics cannot operationalize.
- Inventory Management:Centralized depot operations with just-in-time replenishment algorithms minimize drug waste across decentralized site networks. Pharmaceutical sponsors in Germany and Switzerland prioritize vendors with EMA-qualified person release capabilities integrated into warehouse management systems.
- Packaging Solutions:Specialized primary and secondary packaging with temperature-validated shippers and phase-change materials.
- Distribution Services:Comparator sourcing and rescue medication programs with customs brokerage for multi-regional trials.
- Regulatory Compliance:Documentation management aligned with FDA 21 CFR Part 11 and ICH-GCP audit trail standards.
- Demand Forecasting:Predictive analytics for patient enrollment volatility and protocol amendment impacts.
Volume placements concentrate in Cold Chain Logistics; the faster expansion belongs to Demand Forecasting.
Application:
Cost tier differentiation separates complex multi-arm oncology protocols from standardized cardiovascular designs with predictable dosing schedules.
- Oncology Trials:Multi-arm adaptive designs with complex dosing regimens and high patient volumes drive the largest service contract values. Biotechnology sponsors in Massachusetts and California clusters demand integrated comparator sourcing for immuno-oncology combinations.
- Rare Disease Investigations:Small patient populations scattered across geographies require direct-to-patient distribution capabilities with individualized packaging. European sponsors leverage EMA's centralized trial portal to harmonize supply strategies across member states.
- Cardiovascular Studies:Large-scale outcomes trials with stable small-molecule formulations.
- Neurology Research:Longitudinal studies with cognitive assessment dependencies affecting site visit scheduling.
- Infectious Disease Programs:Pandemic response protocols with accelerated regulatory pathways.
- Autoimmune Disorders:Biologics-heavy pipelines with subcutaneous administration shifts.
Revenue concentration sits with Oncology Trials; Rare Disease Investigations are climbing the fastest as gene therapy pipelines mature.
End User:
Customer type determines procurement sophistication, with large pharmaceutical companies mandating enterprise system integration that smaller biotechnology firms cannot resource.
- Pharmaceutical Companies:Global sponsors with multi-protocol portfolios require end-to-end supply chain accountability consolidation. United States-based multinationals are driving single-vendor partnership structures that displace multi-source outsourcing arrangements.
- Contract Research Organizations:Full-service CROs bundle supply management into integrated trial execution contracts.
- Biotechnology Firms:Emerging sponsors with single-asset dependencies prioritize flexible, milestone-based pricing.
- Academic Institutes:Investigator-initiated studies with limited budgets and simplified regulatory pathways.
- Specialized Clinics:Site networks with direct-to-patient capabilities in rare disease recruitment.
- Government Agencies:Public health programs with pandemic preparedness stockpiling requirements.
Procurement volume aggregates with Pharmaceutical Companies; Contract Research Organizations are gaining share fastest through integrated service bundling.
Technology:
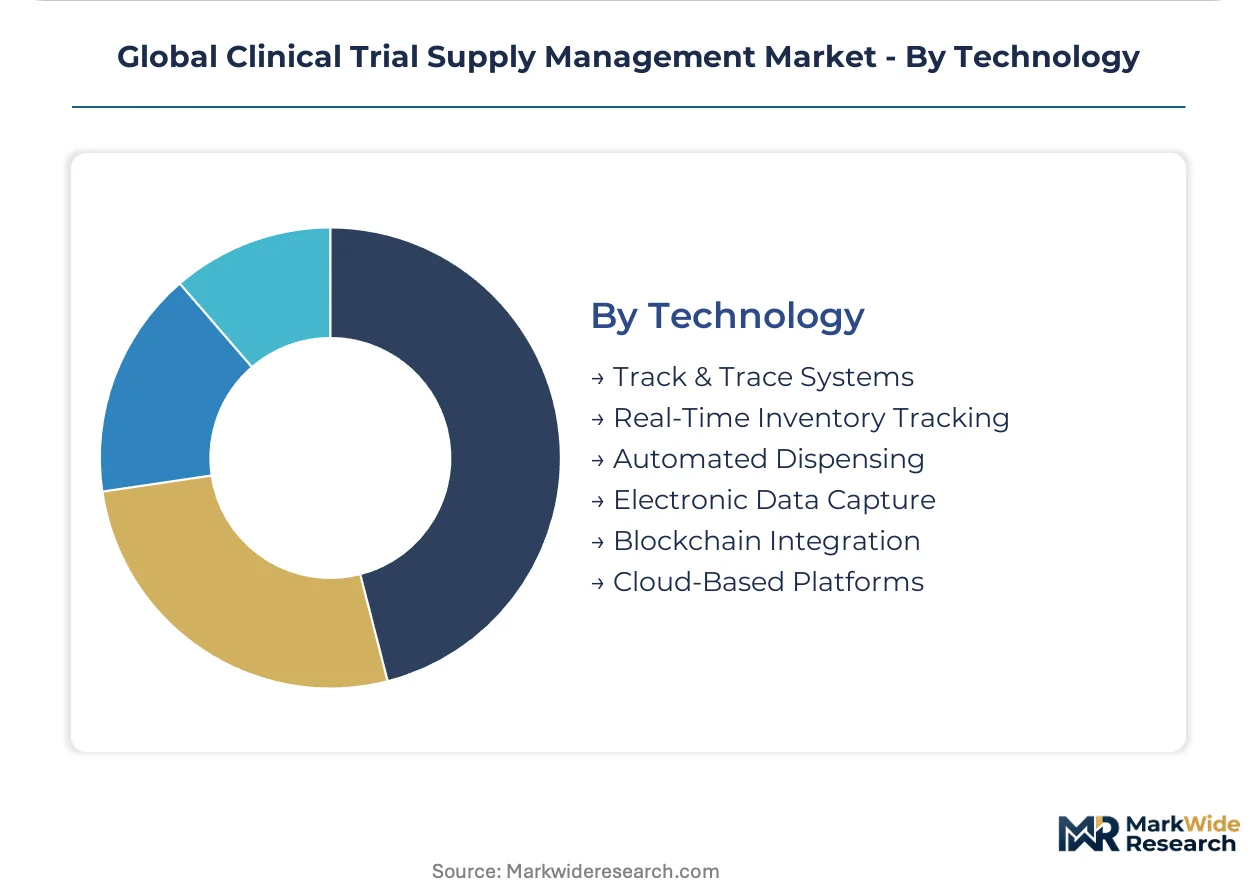
Supply concentration among cloud-native platforms is displacing on-premise legacy systems that lack API compatibility with vendor inventory management tools.
- Blockchain Integration:Distributed ledger technology creates immutable chain-of-custody records for regulatory audits. Large oncology sponsors in the United States and United Kingdom are mandating these capabilities in vendor qualification criteria.
- Real-Time Inventory Tracking:IoT-enabled sensors with GPS and temperature logging provide continuous visibility from depot to patient. Cold chain providers in Germany and the Netherlands deploy these systems to satisfy EMA GDP documentation requirements.
- Track & Trace Systems:Serialization databases aligned with anti-counterfeiting protocols.
- Automated Dispensing:Robotic pharmacy systems for site-based inventory management.
- Electronic Data Capture:EDC integration with supply status for protocol compliance monitoring.
- Cloud-Based Platforms:SaaS deployment models with multi-tenant architecture for sponsor collaboration.
Adoption runs deepest in Real-Time Inventory Tracking; Blockchain Integration carries the steepest expansion trajectory as sponsor contract mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Massachusetts and California biotech clusters anchor North American demand for ultra-cold chain infrastructure. European regulatory harmonization through EMA's centralized portal is compressing multi-country supply strategies. Asian markets are accelerating cold chain qualification timelines for cell therapy exports.
United States
Phase III oncology concentration in Massachusetts and California generates the largest contract values for integrated comparator sourcing. FDA's risk-based monitoring framework incentivizes sponsor outsourcing to vendors with validated 21 CFR Part 11 systems. The Greater Boston biotech corridor demands minus eighty-degree Celsius distribution networks that only specialized clinical supply providers operationalize.
Germany
EMA-qualified person release mandates concentrate vendor selection among depot operators with integrated warehouse management systems. EMA's Clinical Trial Regulation eliminates country-specific packaging requirements previously fragmenting supply strategies. The Rhine-Ruhr pharmaceutical manufacturing belt hosts comparator sourcing hubs serving multi-national European trials.
Switzerland
Originator drug manufacturers control reference product release, creating single-source dependencies for comparator programs. Swissmedic harmonization with ICH-GCP standards streamlines qualified person workflows for investigational products. The Basel pharmaceutical cluster anchors biologics distribution networks spanning Alpine transit corridors into EU member states.
United Kingdom
MHRA regulatory flexibility enables the most advanced direct-to-patient adoption outside North America. Brexit divergence from EMA centralized frameworks forces sponsors to maintain parallel qualified person release processes. The London-Oxford-Cambridge life sciences triangle drives demand for decentralized trial infrastructure with last-mile cold chain capabilities.
Brazil
ANVISA harmonization with ICH-GCP standards reduces regulatory friction for sponsors seeking diverse patient populations. The country's national pharmaceutical regulator mandates temperature documentation aligned with WHO prequalification programs. São Paulo's clinical research infrastructure anchors Latin American expansion for cold chain logistics providers.
Global Clinical Trial Supply Management Market Competitive Landscape
Global majors compete with regional champions across end-to-end accountability versus specialized service depth. The market structure concentrates around integrated platform providers capable of absorbing biologics infrastructure costs that fragment smaller competitors. Three archetypes dominate: laboratory-to-logistics conglomerates, biologics-specialized packaging distributors, and patient-centric direct-to-patient innovators. Competitive moves center on single-vendor partnership consolidation and blockchain-enabled chain-of-custody mandates in sponsor contracts.
Within the integrated platform tier, Thermo Fisher Scientific Inc. and Catalent Inc. exemplify end-to-end accountability structures. Almac Group occupies a position representing patient-centric supply specialization. These anchors reflect the market's bifurcation between scale-driven conglomerates and flexibility-oriented service architects.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Catalent Inc. |
| Almac Group |
| Parexel International Corporation |
| PCI Pharma Services |
| Sharp Services |
| Marken |
| KLIFO |
| Lonza |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up cold chain specialists have consolidated depot networks across Germany and the United States, creating pricing discipline through capacity control while compressing margins for independent packaging providers. Their ownership structure prioritizes yield optimization over volume capture, reshaping how sponsors negotiate comparator sourcing and ultra-cold distribution contracts.
Pricing Analysis
Warranty and service bundling separates premium-tier vendors offering qualified person release integration from unbundled economy providers focused on transactional depot storage. Project-based pricing dominates complex oncology trials with protocol amendment volatility, while subscription SaaS models capture demand forecasting and inventory platform contracts. Price differentiation hinges on EMA GDP certification tier and after-sales thermal packaging validation support. Cost compression in economy-tier logistics is intensifying because petrochemical input volatility erodes phase-change material margins. Biotechnology firms with single-asset dependencies exhibit highest price sensitivity; large pharmaceutical multinationals with multi-protocol portfolios prioritize accountability consolidation over unit cost.
Supply Chain Analysis
Direct-to-patient channels bypass traditional site-based depot hierarchies, demanding last-mile cold chain capabilities that conventional pharmaceutical distributors cannot operationalize. Manufacturing concentration for temperature-validated shippers rests on Germany, Switzerland, and the United States, with Rhine-Ruhr and Greater Boston anchoring specialized packaging production. Raw material dependencies include medical-grade polystyrene, phase-change paraffin blends, and lithium-ion battery packs for active thermal containers. Single-source vulnerability concentrates around Swiss originator manufacturers controlling comparator release for reference products. Distribution runs through qualified person release networks in the European Union and risk-based monitoring frameworks in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating as biologics infrastructure costs force sub-scale competitors into distressed exits. Ultra-cold chain capital requirements and EMA GDP compliance mandates are accelerating this winnowing.
For Market Incumbents: To counter margin erosion from petrochemical input volatility, Thermo Fisher Scientific and Catalent should deepen backward integration into phase-change material production and captive comparator sourcing networks. Capacity addition in the Greater Boston biotech corridor secures proximity to CAR-T trial sponsors while insulating against logistics chokepoints.
For New Entrants and Emerging Players: Launch via direct-to-patient distribution partnerships with rare disease advocacy networks in the United Kingdom and Germany, where regulatory flexibility enables site-less trial models. Latin American expansion through ANVISA-harmonized operations in São Paulo represents the most penetrable geography. White-space exists in blockchain-enabled chain-of-custody platforms for mid-tier oncology sponsors lacking enterprise integration resources.
For Investors and Strategic Acquirers: Sponsor contract mandates requiring blockchain integration are the leading indicator that technology-enabled compliance layers will command acquisition premiums. The five-to-ten year viability window favors vertically integrated cold chain providers with EMA-qualified person release capabilities and proprietary thermal packaging IP. Acquisition targets should display patient-centric supply service architectures and direct-to-patient operational scale.
| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain-Enabled Chain of Custody | FDA and EMA audit trail mandates are driving sponsor contract requirements for immutable documentation platforms. |
| Direct-to-Patient Distribution Scale-Up | MHRA regulatory clarity enables decentralized trial models that bypass traditional site-based inventory hierarchies. |
| Ultra-Cold Infrastructure Expansion | CAR-T and gene therapy pipelines require minus eighty-degree Celsius networks that fragment smaller competitors. |
| Comparator Sourcing Integration | Swiss and German originator dependencies create captive supply advantages for integrated platform providers. |
| EMA Qualified Person Consolidation | Centralized trial portal harmonization eliminates multi-country packaging fragmentation for single-vendor partners. |
Research Methodology
FDA filings, EMA centralized portal submissions, and ClinicalTrials.gov protocol registries formed the secondary backbone for supply chain mapping and regulatory pathway analysis. Primary interviews with drug development executives, regulatory affairs leads at sponsor organizations, clinical supply chain directors, and depot operations managers provided operational validation. Customs and trade data for temperature-controlled pharmaceutical shipments supplemented demand estimation. Bottom-up service-type segmentation and top-down regional market sizing were triangulated against sponsor procurement survey data.
Historical trendline analysis of cold chain logistics contract values informed the projection framework across the analysis window. Segmentation dimensions modeled include service type, application area, end-user archetype, and regional regulatory cluster. CAGRs were derived from sponsor outsourcing intention surveys and vendor capacity expansion announcements. Forecast inputs incorporated biologics pipeline maturation rates and EMA GDP qualified person training pipeline constraints.
The model assumes a particular technology adoption path; alternative pathways for blockchain integration or direct-to-patient regulatory harmonization would alter the outlook. Forecasts reflect base-case assumptions regarding sponsor procurement consolidation and biologics infrastructure investment cycles. Regulatory divergence between FDA risk-based frameworks and EMA centralized requirements, plus cold chain qualification timeline compression for cell therapies, constitute primary revision risks. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Research
Clinical Trials Outsourcing Market
Clinical Research
Humanized Mice Model Market
Clinical Research
Asia-Pacific Contract Research Organization Market
Clinical Research
Ecoa, Esource & Clinical Trials Market
Clinical Research
Global in Vivo Toxicology Market
Clinical Research
US Virtual Clinical Trials Market
Clinical Research
Preclinical CRO Market
Clinical Research
Synthetic Clinical Trial Data Market
Clinical Research
Global Clinical Trial Support Services Market
Clinical Research
Esource and Clinical Trials Market
Clinical Research
AI-Based Clinical Trial Solutions for Patient Matching Market
Clinical Research
Global Clinical Trial Management Systems Market
Clinical Research
Clinical Trial Logistics and Direct-to-Patient Delivery Platforms Market
Clinical Research
Patient-Reported Outcome Data Monetization Market
Clinical Research
Europe Clinical Trials Market
Clinical Research
Global in Silico Clinical Trials Market