
 Asia-Pacific Cane Sugar Market | 2026-2036
Asia-Pacific Cane Sugar Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Cane Sugar Market Outlook
Thailand's northeastern plateau expansion is reshaping raw sugar export capacity across the Mekong basin. Wilmar Sugar Australia Holdings Pty Ltd leverages its Queensland milling network to sustain bulk refined output for Asian food manufacturers. Rajshree Sugars & Chemicals Limited anchors India's northern plains with integrated distillery operations. Nanning Sugar Industry Co., Ltd. dominates Guangxi's processing corridor through state-backed cane collection infrastructure.
Asia-Pacific cane sugar denotes sucrose extracted from Saccharum officinarum stalks, typically yielding crystals with polarimetric purity above 99.5 percent after affination and crystallization stages. The commodity serves as the primary caloric sweetener for industrial food formulation, beverage production, and ethanol fermentation across tropical and subtropical manufacturing zones. Refined sugar commands the dominant value share within product type segmentation, while molasses generates disproportionate margin contribution through biofuel and distillery offtake. Liquid form leads distribution to beverage industry buyers, whereas granulated supply chains compete on bulk logistics efficiency for confectionery procurement.
FSSAI in India, China's SAMR under GB standards, and Thailand's Ministry of Industry collectively enforce sucrose purity thresholds, sulfur residue limits, and packaging traceability that determine market access for domestic and imported product. These frameworks elevate compliance costs for smaller mills while concentrating processing capacity among integrated operators with laboratory certification capabilities. Stakeholders must monitor biofuel blending mandate revisions across Indonesia, India, and the Philippines, as ethanol diversion from sugar streams will reset available refined volumes for food sector contracting.
Market Dynamics
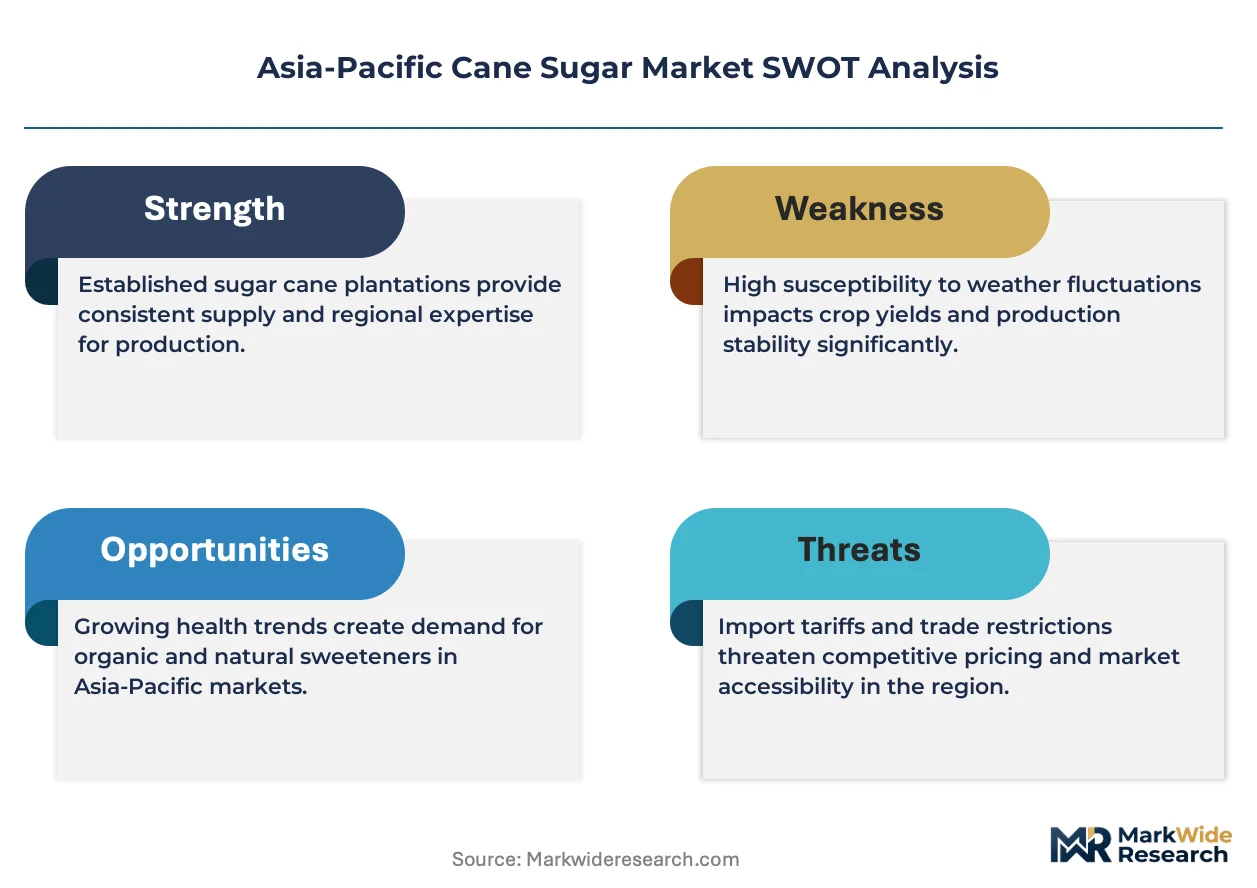
Ethanol diversion mandates across Indonesia, India, and the Philippines are compressing refined sugar availability for food sector buyers, forcing procurement strategies to pivot around biofuel policy calendars rather than agricultural cycles alone.
Growth Catalysts
- GB Standards Compliance:China's SAMR purity thresholds for sulfur residue and polarimetric content are consolidating processing capacity among certified mills, elevating barrier-to-entry protection for compliant operators.
- Beverage Sector Scaling:Indonesia's domestic soft drink manufacturers are expanding cane sugar offtake for carbonated and ready-to-drink formulations, anchoring volume demand within ASEAN.
- FSSAI Harmonization:India's food safety packaging traceability rules are standardizing supply chain documentation, reducing quality arbitrage between domestic and export-grade production.
Market Restraints
- Input Cost Volatility:Fertilizer and diesel price swings in Thailand's northeastern plateau directly transmit to crush economics, squeezing mill margins during monsoon-disrupted harvests.
- Supply Concentration Risk:Queensland's bulk refined output dominance through Wilmar's milling network creates single-geography dependency for Asian food manufacturers seeking standardized specifications.
- Substitution Threat:High-fructose corn syrup from China's starch processing corridor is displacing liquid cane sugar in cost-sensitive beverage formulations.
Strategic Opportunities
- Vietnam Underpenetration:The Mekong Delta's nascent distillery integration presents white space for backward-integrated mills to capture molasses-to-ethanol margin stacking.
- Philippines Biofuel Mandate:The country's Department of Energy ethanol blending requirements are diverting cane streams toward fuel, creating premium pricing windows for food-grade refined sugar contracting.
- Blockchain Traceability Convergence:Integration of distributed ledger systems with FSSAI and GB standards documentation is enabling real-time purity verification for export shipments.
Industry Challenges
- Laboratory Certification Timeline:Smaller mills face 18-24 month accreditation delays for FSSAI and SAMR testing protocols, locking them out of premium food-grade contracts.
- Capex Intensity for Affination:Crystallization stage upgrades to achieve 99.5 percent polarimetric purity require crushing line retrofits that strain balance sheets below 5,000 TCD capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Cane Sugar Market |
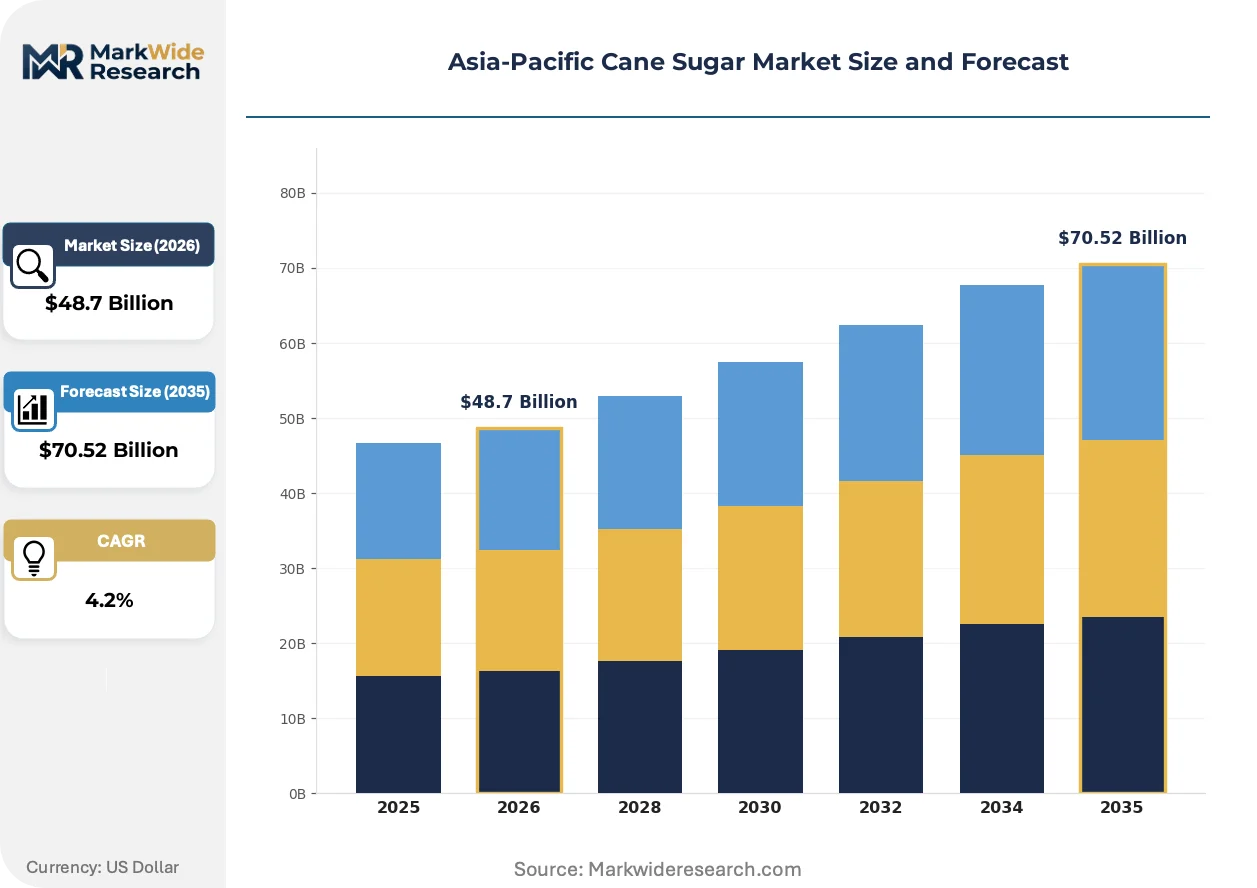
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $70.52 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Sugar, Refined Sugar, Molasses, Demerara Sugar End User: Food Industry, Beverage Industry, Confectionery, Biofuel Producers Distribution Channel: Direct Sales, Wholesale, Retail, Online Sales Form: Granulated, Liquid, Powdered, Crystalline |
| Companies Covered | American Sugar Refining, Inc., Rajshree Sugars & Chemicals Limited, Global Organics, Ltd., Nanning Sugar Industry Co., Ltd., Rana Sugars Limited, Louis Dreyfus Company B.V., Wilmar Sugar Australia Holdings Pty Ltd., Triveni Engineering & Industries Ltd, Tate & Lyle PLC, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Cane Sugar Market Strategic Shifts
Digitalization of cane collection logistics and fermentation process control is compressing the gap between field harvest and refined output quality consistency across tropical processing zones.
Membrane filtration technology for raw juice clarification is hybridizing traditional lime-sulfitation methods with cross-flow ceramic systems, reducing chemical input costs. Thai and Australian mills are retrofitting existing diffusion plants with nanofiltration skids at 200-400 TCD pilot scale. This convergence is enabling simultaneous sulfur reduction and color removal, compressing the capital threshold for direct consumption sugar production.
China's dual carbon goals under MEE oversight are tightening energy intensity benchmarks for Guangxi processing corridors, mandating bagasse cogeneration efficiency upgrades. Mills must demonstrate 85 percent thermal efficiency or face production quota restrictions. The policy is accelerating biomass boiler retrofits among state-backed operators while marginalizing smaller independent crushers lacking grid-tie capacity.
Long-term offtake agreements are displacing spot-market purchasing among Indonesian and Indian beverage conglomerates, compressing procurement cycles into 12-18 month locked contracts. This shift transfers price volatility risk upstream to millers while guaranteeing volume certainty for carbonated drink scaling. The pattern is most visible in Java's industrial corridors where Coca-Cola and local bottlers have consolidated supplier panels to three certified processors.
Asia-Pacific Cane Sugar Market Segmentation
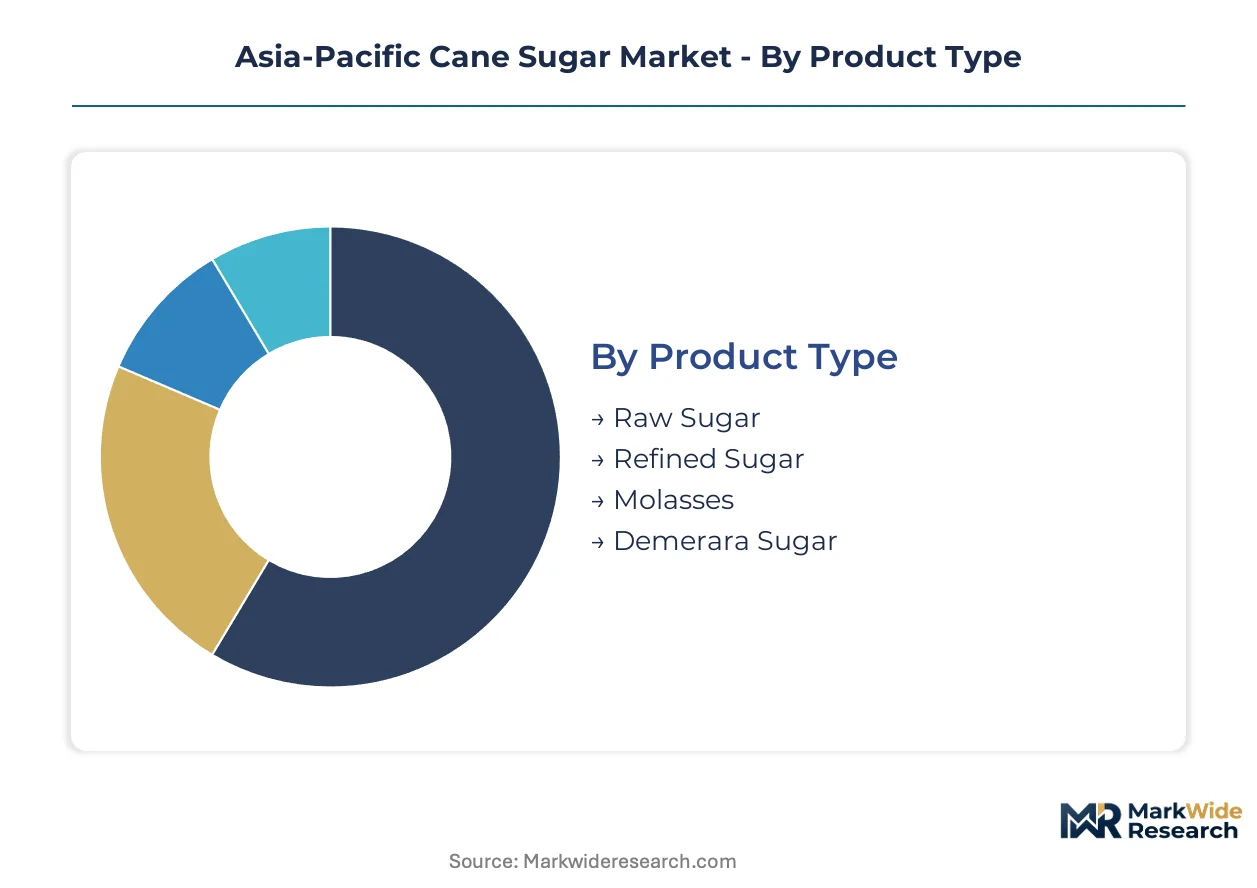
Segmentation in Asia-Pacific cane sugar reveals how procurement cycles, purity thresholds, and logistics constraints fragment contracting behavior across industrial buyers. Food-grade specifications from FSSAI and GB standards create divergent margin profiles that reshape capacity allocation among Thai, Indian, and Chinese mills.
Product Type:
Refined sugar commands the longest production cycle from crush to crystallization, while molasses turns over fastest through distillery offtake. Raw sugar sits mid-cycle, awaiting affination upgrades to meet beverage industry polarimetric thresholds.
- Refined Sugar:Achieves polarimetric purity above 99.5 percent through affination and multiple crystallization stages. Indonesian soft drink manufacturers concentrate procurement here, driven by carbonated beverage scaling and FSSAI-grade export requirements.
- Molasses:Fermentation-grade byproduct from final extraction stages, commanding disproportionate margin contribution through ethanol diversion mandates. Philippine biofuel producers anchor demand as Department of Energy blending requirements tighten.
- Raw Sugar:VHP and bulk plantation grades awaiting further processing. Thai northeastern plateau mills dominate export volume to Guangxi refineries.
- Demerara Sugar:Large golden crystals retaining trace molasses coating. Niche positioning within premium confectionery channels in Australia and Japan.
Refined sugar dominates installed base. Molasses is where expansion concentrates.
End User:
Cost tier stratification separates commodity-scale buyers from specification-sensitive contract accounts. Beverage industry procurement runs on 12-18 month locked agreements, while biofuel offtake fluctuates with mandate calendars.
- Beverage Industry:Carbonated and ready-to-drink manufacturers in Indonesia and Thailand drive liquid sugar volume. Java's industrial corridors have consolidated supplier panels to three certified processors under Coca-Cola procurement standards.
- Food Industry:Processed goods manufacturers across Southeast Asia expanding refined cane sugar procurement. Bakery and dairy applications in Vietnam's Mekong Delta present backward integration opportunities for distillery-integrated mills.
- Confectionery:Granulated specifications for hard candy and chocolate production. Australian and Japanese buyers prioritize color consistency and sulfur residue thresholds.
- Biofuel Producers:Ethanol fermentation from molasses streams. Indian and Philippine diversion mandates compress food-grade refined availability, creating premium contracting windows.
Beverage industry procurement commands volume concentration. Biofuel producers represent the steepest expansion trajectory as blending mandates tighten.
Distribution Channel:
Customer type determines channel selection: multinational beverage conglomerates bypass intermediaries, while regional food processors rely on wholesale aggregators for smaller lot flexibility.
- Direct Sales:Long-term offtake agreements between Indonesian bottlers and Thai mill networks. Transfers price volatility risk upstream while guaranteeing volume certainty.
- Wholesale:Bulk granulated supply chains competing on logistics efficiency for confectionery procurement across ASEAN. Aggregators manage port-to-warehouse coordination for mid-scale food manufacturers.
- Retail:Consumer-packaged sugar through supermarket and traditional trade channels. Limited volume contribution relative to industrial offtake.
- Online Sales:Emerging channel for specialty and organic-certified product. Urban Indian consumers drive trial through e-grocery platforms.
Direct sales dominate contract value. Wholesale channels handle shipment fragmentation.
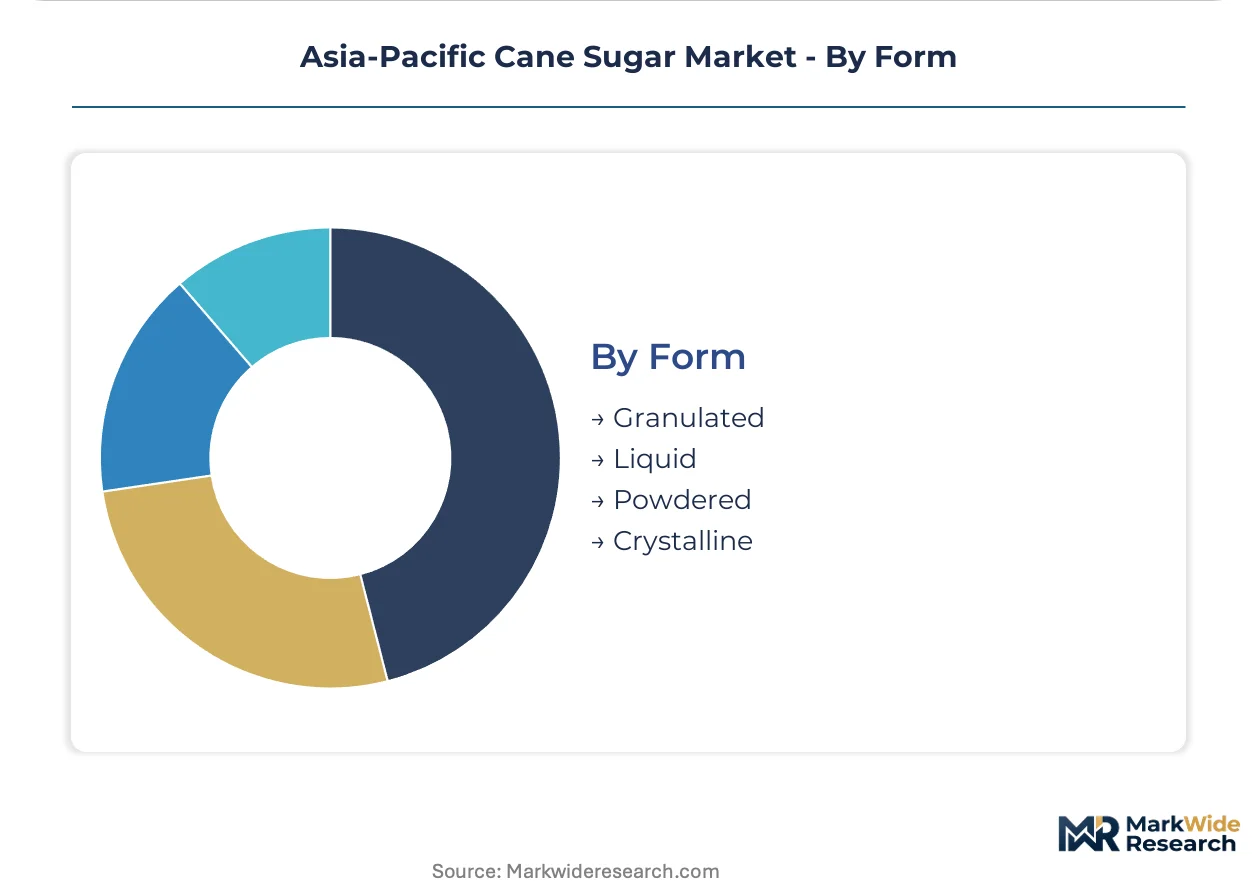
Form:
Application requirements dictate form selection: liquid enables continuous-process beverage manufacturing, while granulated suits batch confectionery operations with storage flexibility.
- Liquid:Invert syrup and liquid sucrose for continuous-process carbonated drink lines. Indonesian bottlers scale offtake fastest as domestic soft drink production expands.
- Granulated:Free-flowing crystals for bakery, confectionery, and household use. Queensland's bulk refined output sustains Asian food manufacturer specifications through Wilmar's milling network.
- Powdered:Fine grind for icing and instant beverage applications. Limited regional production capacity constrains supply.
- Crystalline:Large uniform crystals for pharmaceutical and premium food-grade use. SAMR purity thresholds elevate barrier-to-entry for certified production.
Granulated form commands logistics scale. Liquid form is gaining share fastest as beverage automation spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thai mill networks and Queensland refineries dominate bulk output for Asian food manufacturers. India's northern plains and Guangxi's processing corridors anchor domestic supply chains. Indonesian bottlers and Vietnamese food processors drive demand concentration across Southeast Asian industrial corridors.
Thailand
Northeastern plateau expansion is reshaping raw sugar export capacity across the Mekong basin. The Ministry of Industry enforces sucrose purity thresholds and sulfur residue limits that determine market access. Buriram and Khon Kaen provinces host mill clusters supplying VHP grades to Guangxi refineries.
China
Guangxi's state-backed cane collection infrastructure sustains Nanning Sugar Industry Co., Ltd.'s processing dominance. SAMR under GB standards mandates polarimetric content above 99.5 percent and packaging traceability for food-grade certification. Nanning and Chongzuo industrial corridors concentrate biomass cogeneration retrofits under MEE dual carbon goals.
India
Uttar Pradesh and Maharashtra mill networks anchor integrated distillery operations for ethanol diversion. FSSAI food safety standards tighten packaging traceability and laboratory certification timelines. Muzaffarnagar and Kolhapur clusters face 18-24 month accreditation delays that lock smaller mills out of premium contracts.
Indonesia
Domestic soft drink producers in Java's industrial corridors are scaling cane sugar offtake for carbonated formulations. Biofuel blending mandate revisions from the Ministry of Energy reset available refined volumes for food sector contracting. Surabaya and Jakarta bottlers have consolidated supplier panels to three certified processors.
Australia
Queensland's bulk refined output sustains Asian food manufacturer specifications through Wilmar's milling network. The country's national food safety regulator enforces sulfur residue thresholds for export-grade production. Mackay and Bundaberg regions create single-geography dependency risk for standardized granulated supply chains.
Asia-Pacific Cane Sugar Market Competitive Environment
Integrated conglomerates and regional specialists split the market between scale-driven bulk supply and specification-sensitive contracting. Thai and Australian mill networks concentrate export capacity through Queensland and northeastern plateau corridors. Indian and Chinese operators dominate domestic procurement under FSSAI and GB standards compliance. Competitive moves center on distillery integration for ethanol margin stacking and long-term offtake agreements that transfer price volatility risk upstream.
Within the integrated conglomerate tier, Wilmar Sugar Australia Holdings Pty Ltd and Nanning Sugar Industry Co., Ltd. exemplify state-backed and privately held models of cane collection infrastructure control. Rajshree Sugars & Chemicals Limited occupies a position among Indian operators with distillery-integrated northern plains capacity. These three entities represent divergent geographic anchoring—Australian export orientation, Chinese domestic processing dominance, and Indian ethanol-food grade flexibility—without overlapping procurement territories.
| Leading Market Players |
|---|
| American Sugar Refining, Inc. |
| Rajshree Sugars & Chemicals Limited |
| Global Organics, Ltd. |
| Nanning Sugar Industry Co., Ltd. |
| Rana Sugars Limited |
| Louis Dreyfus Company B.V. |
| Wilmar Sugar Australia Holdings Pty Ltd. |
| Triveni Engineering & Industries Ltd |
| Tate & Lyle PLC |
| Others |
Value Chain & Pricing Dynamics
Queensland's Mackay and Bundaberg mill clusters concentrate bulk refined output capacity, granting Wilmar's milling network substantial leverage over Asian food manufacturer contract terms. This geographic anchoring compresses procurement alternatives and elevates sulfur-residue-certified product premiums.
Pricing Analysis
FSSAI and GB standards dictate the pricing tier structure across the Asia-Pacific cane sugar market. Three-tier pricing structure across premium, standard, and economy levels separates FSSAI-certified laboratory-grade output from GB-compliant food-grade and uncertified industrial molasses. Cost compression in standard-grade refined sugar is intensifying because Philippine and Indonesian ethanol diversion mandates divert cane streams toward biofuel. Beverage conglomerates locked in 12-18 month offtake agreements show least price sensitivity, while mid-scale Vietnamese food processors remain most exposed to spot-market volatility.
Supply Chain Analysis
China's dual carbon goals under MEE oversight function as export-control regime equivalents for energy-intensive processing equipment, limiting biomass cogeneration technology flows to certified state-backed operators. Thailand, India, and Australia concentrate geographic supply for raw and refined grades. Crush economics draw from fertilizer and diesel input costs, bagasse cogeneration efficiency, and polarimetric purity certification timelines. Single-source vulnerability runs through Queensland's bulk refined dominance for standardized Asian food manufacturer specifications. Distribution runs through direct long-term offtake agreements with Indonesian bottlers and wholesale aggregators for ASEAN confectionery procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific cane sugar markets reward service-attach strategies. Laboratory certification services and FSSAI compliance documentation generate recurring revenue expanding faster than commodity crush volumes.
For Market Incumbents: Harden distillery integration depth to capture ethanol margin stacking as Philippine and Indonesian biofuel mandates tighten. Expand backward integration into northeastern Thai plateau cane collection infrastructure to defend against Wilmar's Queensland network consolidation. Prioritize blockchain-traceability certification investment to lock in Coca-Cola and domestic Indonesian bottler supplier panel positions. For New Entrants and Emerging Players: Establish a beachhead in Vietnam's Mekong Delta food processing corridor, where backward-integrated distillery capacity remains underpenetrated. Target bakery and dairy applications with granulated specifications as the most penetrable segment. Lead with FSSAI certification services bundled with refined sugar supply to bypass 18-24 month laboratory accreditation barriers facing smaller mills. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because FSSAI and GB standards compliance timelines structurally exclude sub-5,000 TCD capacity operators from premium food-grade contracting. Acquisition target archetype: distillery-integrated mills with existing laboratory certification and state-backed cane collection infrastructure. Watch Philippine Department of Energy ethanol blending mandate revisions as the signal for refined sugar availability inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Distillery Integration | Captures molasses-to-ethanol margin stacking under Philippine biofuel mandates. |
| Blockchain Traceability Deployment | Enables real-time FSSAI and GB standards verification for export shipments. |
| Biomass Cogeneration Retrofit | Secures MEE dual carbon compliance for Guangxi processing corridor operators. |
| Long-term Offtake Agreement | Transfers price volatility risk upstream while guaranteeing volume for Indonesian bottlers. |
| Laboratory Certification Investment | Unlocks 18-24 month FSSAI accreditation barriers blocking smaller mill competition. |
Study Parameters
Operator-level perspectives from mill procurement directors, FSSAI laboratory certification officers, Indonesian beverage bottler supply chain managers, and Thai northeastern plateau cane collection coordinators anchored the qualitative base. These primary interviews combined with secondary validation from customs and trade data, FSSAI regulatory filings, SAMR GB standards documentation, and SEC 10-K disclosures from listed processors. Bottom-up crush volume estimates and top-down regional demand aggregation provided triangulation.
Scenario-bracketing framed the analytical approach across the projection horizon. Segmentation dimensions modeled include product type tier, end-use industry vertical, distribution channel structure, and form specification. CAGRs derived from weighted average growth rates across these segments, incorporating ethanol diversion mandate calendars, FSSAI harmonization timelines, and beverage sector automation penetration as industry-specific forecast inputs.
Stress conditions across fertilizer and diesel price volatility, monsoon disruption severity, and biofuel blending mandate revision timing were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory compliance timelines and crush capacity utilization. Material shifts in Philippine or Indonesian ethanol policy stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Digestion Resistant Maltodextrin Market
Sweeteners
Canada Food Sweetener Market
Sweeteners
Natural Malt Sweeteners Market
Sweeteners
Caramelized Sugars Market
Sweeteners
Monk Fruit Sugar Market
Sweeteners
Asia Pacific Food Sweetener Market
Sweeteners
Crystalline Fructose Market
Sweeteners
Indonesia Food Sweetener Market
Sweeteners
Europe B2B Brown Sugar Market
Sweeteners
Dextrose Syrup Market
Sweeteners
Global Stevia Sugar Blends Market
Sweeteners
Smoked Sugar Market
Sweeteners
Methyl Glucose Market
Sweeteners
Sugar Market
Sweeteners
Turbinado Sugar Market
Sweeteners
Global Artificial Sweeteners Market