
 Sugar Beet Juice Extract Market | 2026-2036
Sugar Beet Juice Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Sugar Beet Juice Extract Market Outlook
France is reshaping European supply dynamics through expanded beet processing infrastructure near the Champagne-Ardenne cluster. Südzucker AG leverages integrated agricultural operations across German growing regions to sustain raw material security. Nordzucker AG anchors Nordic supply through specialized extraction technology. Tereos S.A. competes on fermentation-derived co-product streams that extend value capture beyond sucrose recovery.
Sugar beet juice extract comprises aqueous and concentrated preparations obtained by diffusion or pressing of Beta vulgaris roots, typically standardized to specific Brix levels for industrial use. The extract serves primarily as a fermentable substrate, natural sweetening base, and functional ingredient carrier across formulated goods. Powder formats lead margin capture due to stability advantages in cross-border logistics and extended shelf requirements. Liquid concentrates represent the fastest-growing category within food and beverage applications, where manufacturers seek pumpable, meterable inputs for continuous processing lines. Nutraceutical applications occupy a narrower but higher-margin position, with health brands specifying betaine-standardized grades for dietary supplement inclusion.
EU Green Deal targets and REACH chemical safety protocols jointly constrain processing chemistry choices while opening preferential pathways for bio-based extraction methods. EFSA purity standards for food-grade botanical extracts directly shape certificate-of-analysis requirements that govern B2B procurement decisions. FDA GRAS notifications govern U.S. import eligibility for European processors seeking transatlantic distribution. Stakeholders must monitor evolving betaine content thresholds in supplement regulations and calibrate extraction intensity accordingly.
Market Dynamics
Clean-label formulation mandates under EFSA guidance are compressing synthetic sweetener volumes while redirecting procurement budgets toward beet-derived alternatives with traceable agricultural provenance.
Growth Catalysts
- EFSA Purity Standards:Food-grade botanical extract certificates now mandate specific Brix standardization, forcing manufacturers to upgrade diffusion and pressing infrastructure to qualify for B2B supply contracts.
- Fermentation Substrate Demand:Industrial biotechnology facilities across Germany and France specify beet juice extract as a preferred carbon source for precision fermentation processes producing bio-based chemicals.
- Reduced-Sugar Product Lines:Health brands in the Champagne-Ardenne cluster and Nordic markets are reformulating with concentrated preparations to achieve clean-label positioning without artificial alternatives.
Market Restraints
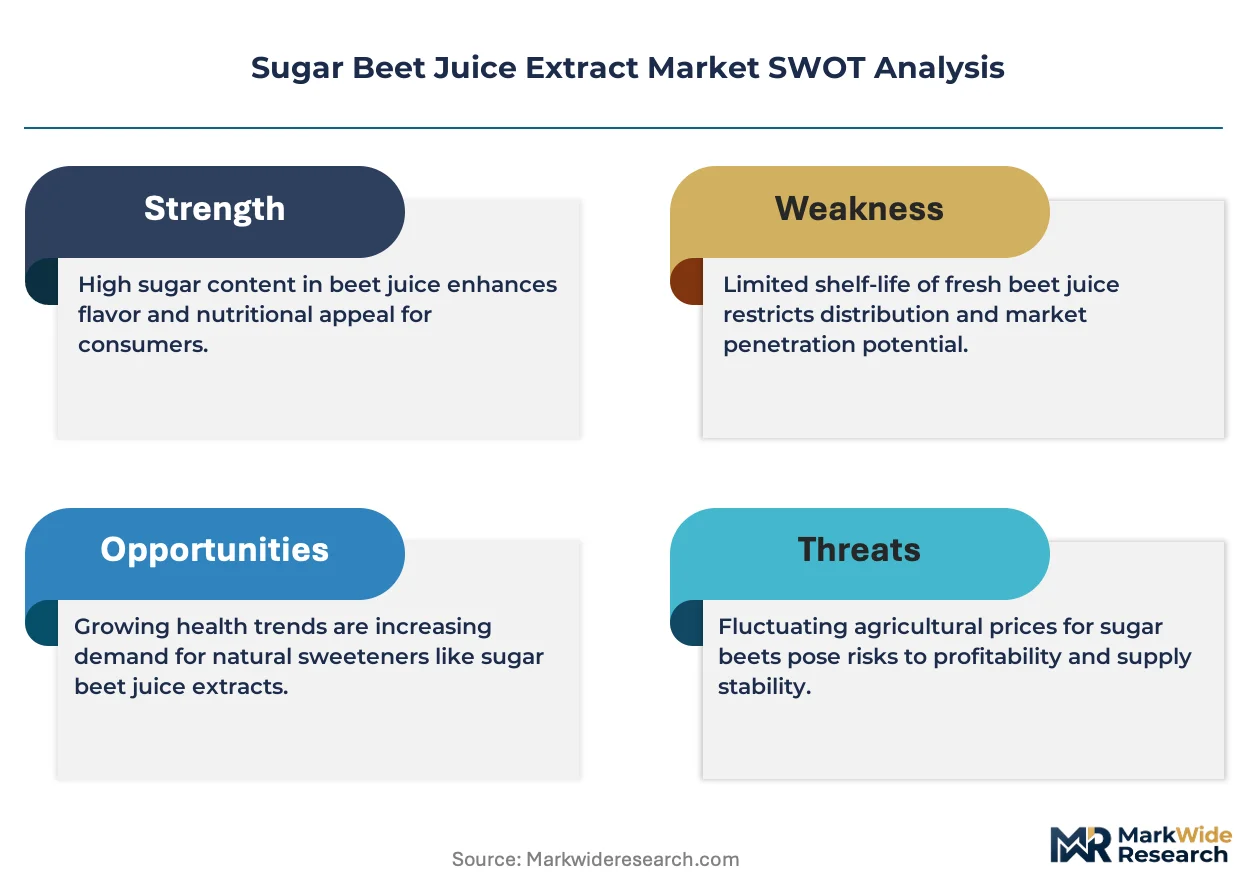
- Input Cost Volatility:Sugar beet root prices fluctuate with weather-induced yield variations across the North European Plain, compressing processor margins during poor harvest cycles.
- Supply Concentration Risk:Downstream demand aggregates heavily in Germany and France, creating geographic dependency that amplifies disruption impacts from regional logistics constraints or crop disease.
- Substitution Threat:Stevia and monk fruit extracts compete for clean-label sweetening applications, particularly in beverage formulations where taste masking requirements are less stringent.
Strategic Opportunities
- Nutraceutical Standardization:Betaine-standardized grades for dietary supplements command premium positioning, with health brands specifying extraction intensity thresholds that extend value capture beyond commodity sucrose recovery.
- EU Green Deal Pathways:Bio-based extraction methods receive preferential treatment under REACH chemical safety protocols, rewarding processors who eliminate petroleum-derived solvents from diffusion operations.
- Powder Format Expansion:Stability advantages in cross-border logistics enable margin capture through extended shelf-life specifications, particularly for manufacturers serving dispersed bakery and confectionery clients.
Industry Challenges
- Certification Timeline Compression:FDA GRAS notification requirements for U.S. import eligibility extend validation cycles, delaying transatlantic revenue recognition for European processors.
- Extraction Technology Integration:Specialized diffusion equipment requires significant capital deployment, straining mid-scale processors attempting to match Nordzucker AG's extraction efficiency benchmarks.
- Betaine Threshold Calibration:Evolving supplement regulations demand continuous analytical adjustment, forcing quality teams to maintain redundant testing protocols across multiple jurisdictional standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sugar Beet Juice Extract Market |
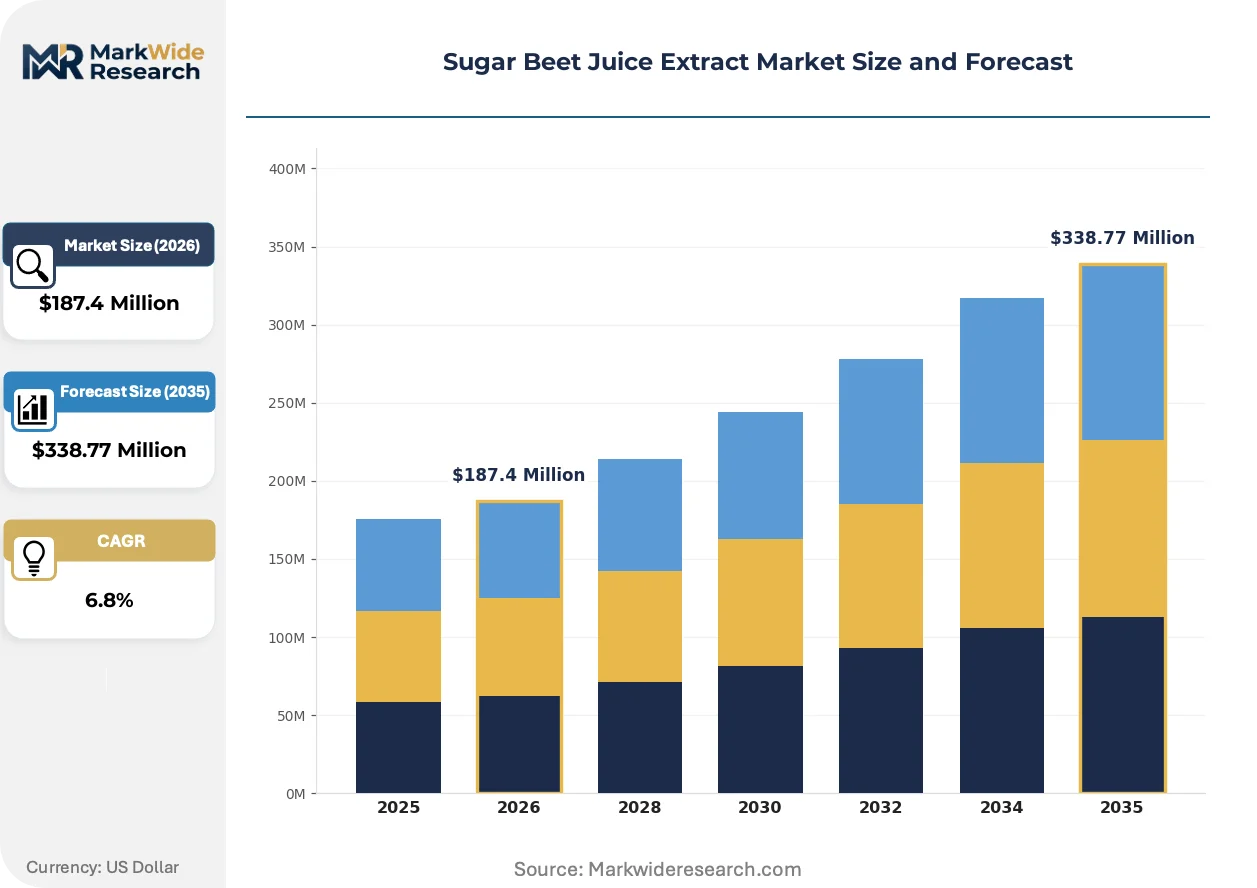
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrate, Powder, Liquid, Granules Application: Food & Beverage, Nutraceuticals, Cosmetics, Animal Feed End User: Food Manufacturers, Beverage Companies, Health Brands, Cosmetic Firms Distribution Channel: Online Retail, Supermarkets, Wholesalers, Specialty Stores |
| Companies Covered | Südzucker AG, Nordzucker AG, Tereos S.A., Amalgamated Sugar Company, AGRANA Beteiligungs-AG, BMA Braunschweigische Maschinenbauanstalt AG, British Sugar Plc, CropEnergies AG, Southern Minnesota Beet Sugar Cooperative, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sugar Beet Juice Extract Market Strategic Shifts
Digital process control and regulatory alignment are converging to reshape extraction economics, with automation investments compressing batch-to-batch variability while sustainability protocols redefine acceptable chemistry choices.
Membrane filtration technology is virtualizing traditional evaporation stages in beet juice concentration. German processors deploy nanofiltration systems to reduce thermal degradation of heat-sensitive betaine compounds. Food manufacturers purchasing liquid concentrates benefit from improved functional consistency in continuous processing lines.
REACH chemical safety protocols and EU Green Deal targets jointly constrain solvent selection in diffusion operations. Processors adopting aqueous extraction methods secure preferential supplier status with sustainability-focused procurement teams. Nordic markets demonstrate strongest compliance acceleration, with Danish and Swedish facilities completing chemistry transitions ahead of continental competitors.
Direct contracting between extract processors and health brands is displacing traditional ingredient distributor intermediation. Supplement manufacturers in France and Germany now specify betaine content thresholds directly in supply agreements. This pattern concentrates most visibly in the Champagne-Ardenne cluster, where co-located agricultural processing and formulation R&D enable rapid specification iteration.
Sugar Beet Juice Extract Market Segmentation
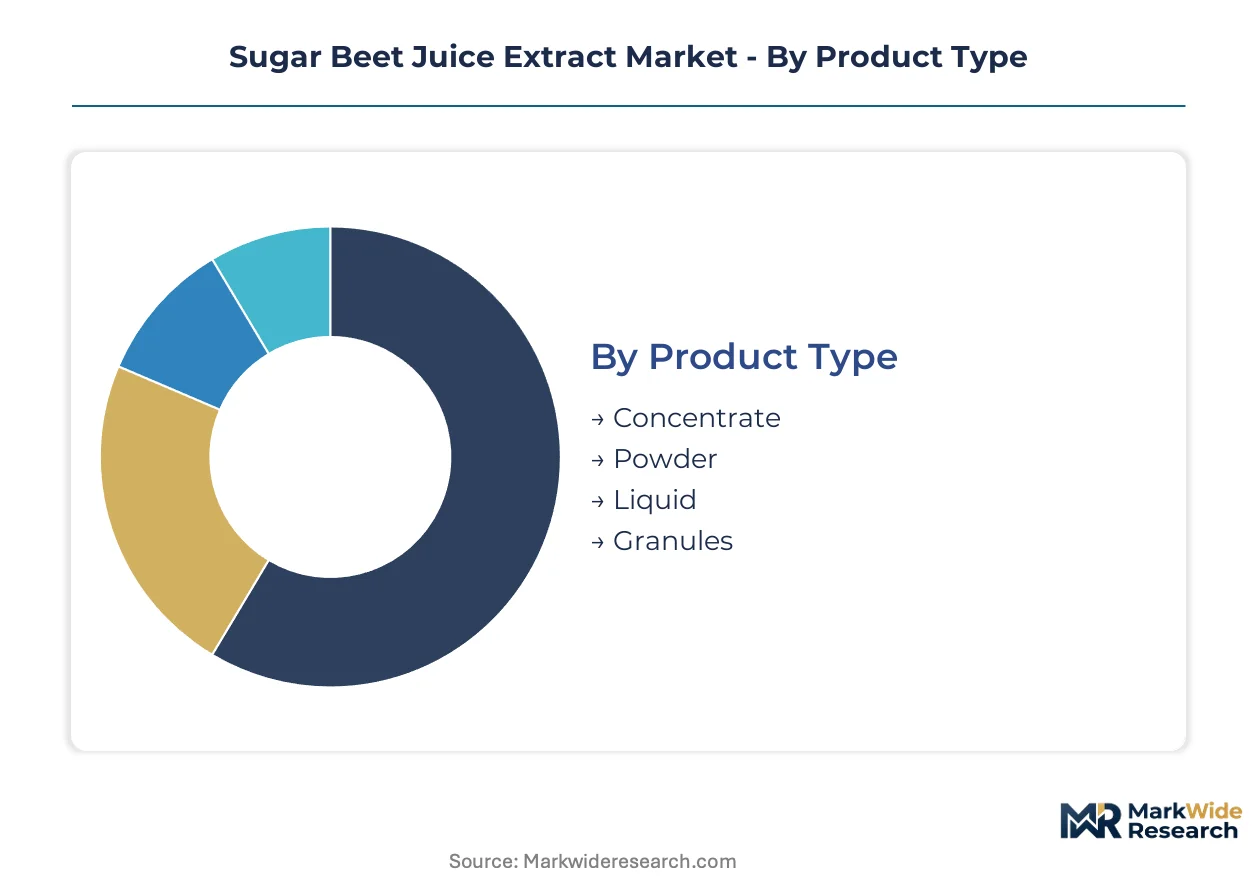
Segmentation in sugar beet juice extract markets reveals how technical specifications and channel structures determine margin capture. Product format choices directly constrain formulation flexibility, while application-driven purity requirements reshape procurement patterns across downstream verticals.
Product Type:
After-sales service intensity varies sharply by physical state—powder and granule formats demand minimal technical support, while liquid concentrates require viscosity calibration assistance and storage condition monitoring for industrial buyers.
- Concentrate:Standardized to specific Brix levels through controlled evaporation, these pumpable preparations enable continuous metering on beverage processing lines. Beverage manufacturers in Germany specify concentrate grades to achieve clean-label reformulation targets without batch-to-batch viscosity drift.
- Powder:Spray-dried or freeze-dried preparations with extended shelf stability reduce logistics complexity for dispersed bakery and confectionery clients. Cross-border distribution economics favor powder for health brands sourcing from Nordic extraction facilities.
- Liquid:Aqueous preparations obtained directly from diffusion or pressing operations serve fermentation substrate applications with minimal processing.
- Granules:Agglomerated formats bridge powder flowability with liquid dispersibility for specialty nutraceutical tableting operations.
Powder holds the largest share; momentum sits with concentrate as beverage manufacturers accelerate clean-label transitions.
Application:
Cost tier stratification separates commodity fermentation feedstocks from premium nutraceutical grades, with extraction intensity and betaine standardization driving price multiples.
- Food & Beverage:Natural sweetening base and functional carrier across reduced-sugar product lines, with EFSA purity standards governing B2B procurement specifications. French health brands in the Champagne-Ardenne cluster drive concentrate adoption for reformulated confectionery and dairy applications.
- Nutraceuticals:Betaine-standardized grades for dietary supplement inclusion command premium positioning through specified extraction intensity thresholds. German supplement manufacturers specify direct supply agreements with processors to secure consistent analytical certificates.
- Cosmetics:Humectant and conditioning agent applications leverage beet-derived osmolyte properties for topical formulation.
- Animal Feed:Fermentable carbohydrate source and palatability enhancer for livestock nutrition formulations.
Food & Beverage dominates volume; Nutraceuticals climb the fastest on margin expansion from standardized grades.
End User:
Customer type determines specification complexity, with health brands imposing the most stringent certificate-of-analysis requirements while animal feed buyers prioritize volume scalability.
- Food Manufacturers:Industrial bakery and confectionery operations specifying powder formats for extended shelf-life requirements in dispersed supply chains.
- Beverage Companies:Continuous processing lines demanding pumpable concentrate grades with documented Brix consistency for clean-label positioning.
- Health Brands:Direct contracting with processors for betaine-standardized extracts, displacing traditional distributor intermediation in France and Germany.
- Cosmetic Firms:Niche procurement of osmolyte-functional grades for moisturizing and anti-irritant claims.
Food Manufacturers anchor demand volume; Health Brands gain share fastest through direct processor relationships.
Distribution Channel:
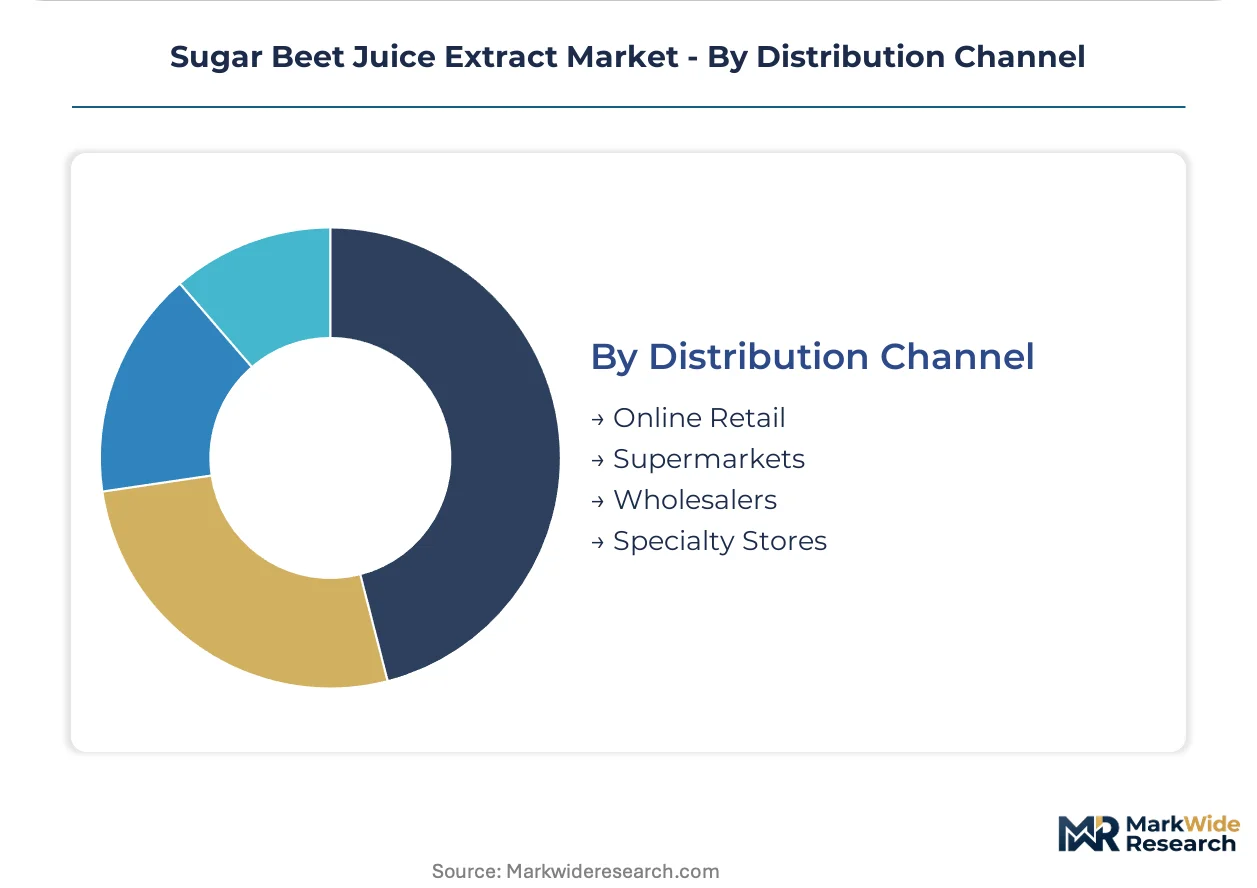
Supply concentration in extraction clusters favors wholesaler dominance for commodity grades, while specialty grades migrate toward direct procurement or specialized retail.
- Online Retail:Small-volume nutraceutical and cosmetic ingredient sourcing enabling rapid specification comparison.
- Supermarkets:Limited presence for consumer-packaged formats; minimal industrial relevance.
- Wholesalers:Primary channel for food and beverage manufacturers procuring standardized concentrate and powder volumes.
- Specialty Stores:Technical ingredient suppliers serving cosmetic formulators and artisan food producers requiring application guidance.
Wholesalers hold the largest share; momentum sits with direct channels as health brands bypass intermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and French food manufacturers consume concentrated liquid formats for beverage reformulation, while Nordic health brands prioritize powder stability for cross-border nutraceutical distribution. This consumption-mix differential separates continuous-processing demand from shelf-life logistics optimization.
Germany
Beverage companies in Bavaria and North Rhine-Westphalia specify pumpable concentrate grades for clean-label reformulation of reduced-sugar product lines. REACH chemical safety protocols constrain solvent selection in diffusion operations, rewarding aqueous extraction methods. The Rhineland agricultural processing corridor hosts integrated beet processing infrastructure sustaining raw material security for fermentation substrate applications.
France
Health brands in the Champagne-Ardenne cluster drive concentrate adoption for reformulated confectionery and dairy applications with traceable agricultural provenance. EFSA purity standards for food-grade botanical extracts directly shape certificate-of-analysis requirements governing B2B procurement decisions. Direct contracting between extract processors and supplement manufacturers concentrates in this cluster, displacing traditional distributor intermediation.
Sweden
Nordic health brands specify betaine-standardized powder grades for dietary supplement inclusion with extended shelf-life requirements. EU Green Deal targets accelerate chemistry transitions ahead of continental competitors, with Swedish facilities completing bio-based extraction method adoption. Specialized extraction technology anchors supply security for dispersed bakery and confectionery clients across Scandinavian markets.
United States
FDA GRAS notification requirements govern import eligibility for European processors seeking transatlantic distribution, extending validation cycles for beet-derived sweetener categories. Health-conscious consumers in California and the Northeast drive demand for clean-label alternatives in functional beverages. Domestic beet sugar cooperatives in the Upper Midwest maintain fermentation substrate supply for industrial biotechnology facilities.
Poland
Emerging food manufacturers in the Greater Poland and Silesian regions procure standardized concentrate volumes for private-label reformulation initiatives. EU Green Deal compliance timelines pressure mid-scale processors to upgrade diffusion infrastructure for preferential supplier status. Agricultural processing clusters near Poznań leverage proximity to German distribution networks for cross-border logistics efficiency.
Sugar Beet Juice Extract Market Competitive Environment
Capability concentration sits with integrated agricultural processors commanding extraction technology and raw material security; scale advantage sits with diversified sugar conglomerates spreading fixed costs across multiple sweetener categories. The market structures around three tiers: beet-specific extract specialists, diversified sugar processors with downstream fermentation integration, and regional cooperative processors serving captive agricultural supply bases. Dominant competitive moves include backward integration into agricultural operations and technology licensing for membrane filtration concentration systems.
Within the integrated processor tier, Südzucker AG and Nordzucker AG exemplify archetypes combining agricultural operations with specialized extraction infrastructure. Tereos S.A. occupies a position representing fermentation-derived co-product value capture. Among cooperative structures, Amalgamated Sugar Company and Southern Minnesota Beet Sugar Cooperative anchor regional supply security through farmer-owned governance models. AGRANA Beteiligungs-AG represents diversified processing capabilities spanning multiple botanical extract categories.
| Leading Market Players |
|---|
| Südzucker AG |
| Nordzucker AG |
| Tereos S.A. |
| Amalgamated Sugar Company |
| AGRANA Beteiligungs-AG |
| BMA Braunschweigische Maschinenbauanstalt AG |
| British Sugar Plc |
| CropEnergies AG |
| Southern Minnesota Beet Sugar Cooperative |
| Others |
Value Chain & Pricing Dynamics
Commodity beet root price volatility across the North European Plain determines both margin compression severity and processor decisions on backward integration depth. Weather-induced yield variations force a pricing spread between aqueous extraction grades and betaine-standardized nutraceutical tiers while simultaneously reshaping regional procurement network configurations.
Pricing Analysis
German beverage manufacturers pay premium spreads over Polish processors for concentrate grades with documented Brix consistency and REACH-compliant aqueous extraction certificates. Three-tier pricing structure across premium nutraceutical, standard food-grade, and economy fermentation substrate levels reflects betaine standardization intensity and EFSA purity documentation depth. Pricing pressure stems from stevia and monk fruit substitution threats in clean-label beverage applications. Animal feed buyers exhibit highest price sensitivity due to volume scalability requirements and low switching costs between carbohydrate sources.
Supply Chain Analysis
EU dual-use export controls on specialized membrane filtration concentration technology limit equipment flows to non-member processing facilities and constrain capacity expansion outside the customs union. Raw material security draws from agricultural operations concentrated in Germany, France, and Poland, with diffusion equipment and nanofiltration membranes sourced from specialized German engineering suppliers. Single-source vulnerability concentrates in Rhineland agricultural processing corridor infrastructure serving fermentation substrate demand. Distribution runs through wholesaler networks for standardized concentrate and powder volumes, with direct contracting displacing intermediation for nutraceutical grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sugar beet juice extract markets track agricultural commodity cycles, with recovery momentum tied to clean-label reformulation waves tightening EFSA guidance enforcement across European food manufacturing.
For Market Incumbents: Build regulatory certification moats by securing FDA GRAS notifications for transatlantic eligibility and investing in aqueous extraction technology ahead of REACH chemical safety protocol deadlines. Defensive consolidation should target membrane filtration specialists in Germany to match Nordzucker AG's extraction efficiency benchmarks. Capacity addition in Poland leverages proximity to German distribution networks while diversifying geographic concentration risk from Champagne-Ardenne cluster dependency. For New Entrants and Emerging Players: Establish a beachhead in Polish private-label reformulation initiatives where EU Green Deal compliance timelines pressure mid-scale processors and create procurement gaps for standardized concentrate volumes. The most penetrable segment sits in emerging food manufacturers across Greater Poland and Silesian regions seeking cross-border logistics efficiency. A direct-to-processor sales model bypassing traditional wholesaler intermediation captures margin from health brands already displacing distributor relationships in France and Germany. For Investors and Strategic Acquirers: EU Green Deal target acceleration reshapes the acquisition landscape by rewarding processors with completed bio-based extraction chemistry transitions ahead of continental competitors. Long-term viability centers on integrated agricultural operations commanding captive beet supply and specialized extraction infrastructure rather than toll-processing models. Acquisition target archetypes include Nordic facilities with betaine-standardization capabilities and Swedish processors demonstrating fastest REACH compliance acceleration. The signal to watch is evolving betaine content thresholds in supplement regulations forcing quality team redundancy investments across multiple jurisdictional standards.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Agricultural Operations | Südzucker AG's integrated growing regions sustain raw material security against weather-induced yield volatility. |
| Membrane Filtration Technology Licensing | German nanofiltration deployment reduces thermal degradation of heat-sensitive betaine compounds for beverage clients. |
| Direct-to-Health-Brand Supply Agreements | French supplement manufacturers in Champagne-Ardenne now specify extraction intensity thresholds without distributor markup. |
| FDA GRAS Notification Completion | European processors securing U.S. import eligibility extend validation cycles but unlock transatlantic revenue recognition. |
| Aqueous Extraction Method Transition | REACH chemical safety protocol compliance secures preferential supplier status with sustainability-focused procurement teams. |
Study Parameters
The analysis maps beet-specific extract specialists, diversified sugar processors, and regional cooperative structures, each validated through extraction technology directors, food manufacturer procurement leads, health brand formulation scientists, and fermentation facility supply managers. Primary interview data triangulates against customs and trade flow records, EFSA guidance documentation, REACH chemical safety protocol filings, and SEC disclosures from diversified processors. Bottom-up volume modeling across product format, application vertical, and end-user archetype converges with top-down agricultural production and processing capacity assessments.
Assumptions held fixed include EFSA purity standard enforcement intensity, REACH solvent restriction timelines, and FDA GRAS notification processing cadence, while variables included clean-label reformulation adoption rates, membrane filtration technology diffusion, and betaine supplement regulation evolution. Segmentation dimensions span physical state, application vertical, customer type, and distribution channel, with additional modeling of extraction intensity tiers for nutraceutical standardization. CAGRs derive from historical volume trajectories adjusted for regulatory inflection points and procurement pattern shifts, incorporating beet root yield volatility cycles and fermentation substrate demand from industrial biotechnology facilities.
Sensitivities concentrate around EFSA guidance revision timing, REACH chemical safety protocol expansion scope, and FDA GRAS notification backlog duration. Forecasts reflect documented assumptions on regulatory enforcement consistency and agricultural yield stability. Material shifts in EU Green Deal target acceleration or betaine threshold calibration in major supplement jurisdictions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
United States Xylitol Market
Sweeteners
Sugar Alcohol Market
Sweeteners
Floral Nectar Market
Sweeteners
Erythritol Market
Sweeteners
Global Stevia Sugar Blends Market
Sweeteners
Europe B2B Brown Sugar Market
Sweeteners
Saccharin Market
Sweeteners
South America Low-Calorie Sweeteners Market
Sweeteners
Resistant Maltodextrin Market
Sweeteners
Palm Sugar Market
Sweeteners
Maltodextrin Market
Sweeteners
North America Food Sweetener Market
Sweeteners
Caramelized Sugars Market
Sweeteners
Vanilla Sugar Market
Sweeteners
Allulose Market
Sweeteners
D-Mannose Market