
 Asia-Pacific Sugar Substitute Market | 2026-2036
Asia-Pacific Sugar Substitute Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Sugar Substitute Market Outlook
Subscription-based formulation services is realigning how ingredient suppliers monetize sweetness systems in the Asia-Pacific sugar substitute market. Tate & Lyle PLC leverages its Singapore technical center to anchor beverage reformulation partnerships across Southeast Asia. Cargill Incorporated sustains supply security through its Indian corn-based erythritol and polyol infrastructure. Ajinomoto Inc. differentiates on amino acid-derived sweetener science, competing for share in Japan's precision-nutrition segment.
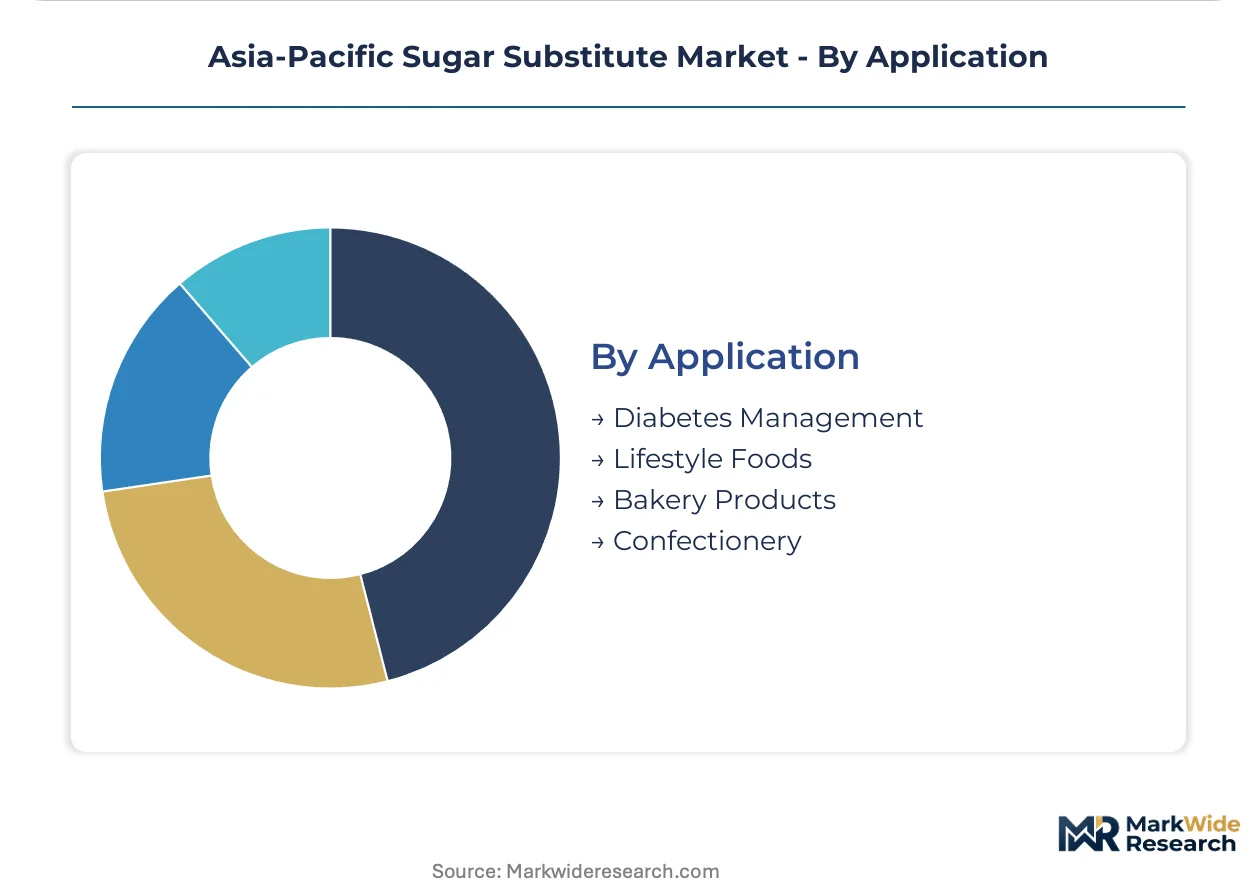
Asia-Pacific sugar substitutes comprise non-caloric and reduced-caloric compounds—steviol glycosides, aspartame, sucralose, and mogrosides—engineered to replicate sucrose's temporal sweetness profile while delivering sub-4 kcal/g energy density for diabetic and weight-management applications. Stevia leads product type volumes as extraction yields from Chinese leaf cultivation improve, though monk fruit commands premium positioning in clean-label confectionery. Bakery and confectionery applications within the application dimension absorb the fastest growth as India's PLI scheme for food processing incentivizes domestic reformulation capacity.
India's FSSAI mandates incremental sugar reduction timelines, while China's SAMR enforces GB standards for non-sugar sweetener maximum usage levels in dairy analogs. Japan's Consumer Affairs Agency maintains positive-list governance for functional sweetener claims, constraining market entry for unvalidated novel extracts. Stakeholders must monitor regulatory divergence between national positive-list systems and harmonized Codex frameworks to preempt formulation lock-in risks.
Market Dynamics
India's FSSAI front-of-pack labeling rules are compressing formulation timelines for beverage and confectionery manufacturers, forcing rapid procurement switches toward natural sweetening systems that satisfy both regulatory thresholds and clean-label consumer expectations.
Growth Catalysts
- FSSAI sugar reduction mandates:India's phased sugar reduction timelines for packaged foods are compelling manufacturers to reformulate with steviol glycosides and monk fruit extracts to maintain shelf positioning.
- Functional beverage startups:China's tier-one city entrepreneurs are driving concentrated uptake of precision-blended natural sweeteners in protein waters and kombucha variants.
- PLI scheme incentives:India's production-linked incentive scheme for food processing is accelerating domestic erythritol and polyol manufacturing capacity expansion.
Market Restraints
- Leaf supply concentration:Stevia raw material dependence on specific Chinese cultivation regions creates harvest volatility and price instability for extractors.
- Positive-list governance:Japan's Consumer Affairs Agency maintains strict validation requirements that block rapid commercialization of novel plant-derived sweeteners.
- Sucrose cost competitiveness:Refined cane sugar remains economically advantaged in mass-market bakery applications, limiting penetration in price-sensitive Indian rural markets.
Strategic Opportunities
- Clean-label confectionery:Monk fruit positioning in premium chocolate and gummy segments offers margin expansion potential in South Korea and Australia's specialty retail channels.
- Technical service subscriptions:Ingredient suppliers can monetize ongoing beverage reformulation partnerships rather than transactional bulk sweetener sales.
- Dairy analog compliance:China's SAMR GB standards for non-sugar sweetener maximums in plant-based milks create first-mover advantage for compliant formulation platforms.
Industry Challenges
- Sensory matching complexity:Replicating sucrose's temporal sweetness profile across multiple applications requires specialized flavor chemist talent that remains scarce in Southeast Asian markets.
- Regulatory divergence risk:National positive-list systems in Japan, China, and India lack harmonization with Codex frameworks, forcing redundant safety studies and formulation lock-in.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Sugar Substitute Market |
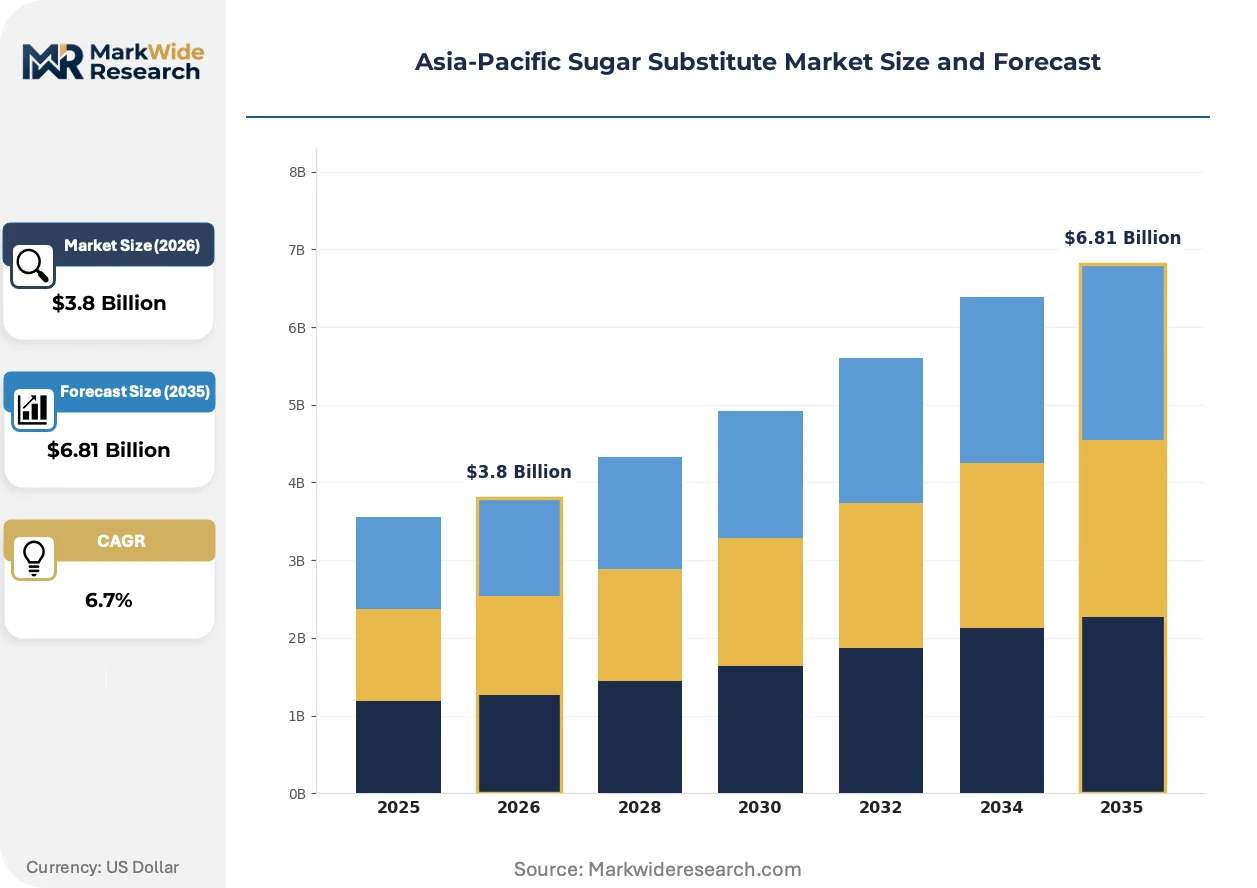
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stevia, Aspartame, Sucralose, Monk Fruit End User: Food Manufacturers, Beverages, Nutraceuticals, Bakeries Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale Application: Diabetes Management, Lifestyle Foods, Bakery Products, Confectionery |
| Companies Covered | Tate & Lyle PLC, DuPont de Nemours Inc., Cargill Incorporated, PureCircle, Roquette Freres, Archer Daniels Midland Company, Ingredion Incorporated, International Flavors & Fragrances Inc., Ajinomoto Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Sugar Substitute Market Strategic Shifts
Bioprocess engineering and regulatory science are converging to reshape how sweetness systems are manufactured, validated, and commercialized across the Asia-Pacific region.
Precision fermentation of steviol glycosides is electrifying supply economics for rare glycoside variants previously constrained by leaf extraction yields. Singapore-based biotech facilities are scaling Reb M and Reb D production for premium beverage clients. This biotechnology is compressing cost structures that once limited these high-purity sweeteners to niche pharmaceutical applications.
China's SAMR enforcement of GB 2760 maximum usage levels for non-sugar sweeteners in dairy analogs is tightening formulation boundaries. Manufacturers must now engineer multi-sweetener blends rather than single-ingredient solutions. The plant-based milk segment is responding by investing in sensory mapping laboratories to optimize glycoside-polyol ratios.
Subscription-based technical partnerships are displacing spot-market sweetener procurement among mid-size beverage brands. Southeast Asian co-manufacturers now demand embedded formulation support from ingredient suppliers rather than standalone product shipments. This service bundling is most visible in Thailand and Vietnam where functional drink contract manufacturing is concentrating.
Asia-Pacific Sugar Substitute Market Segmentation
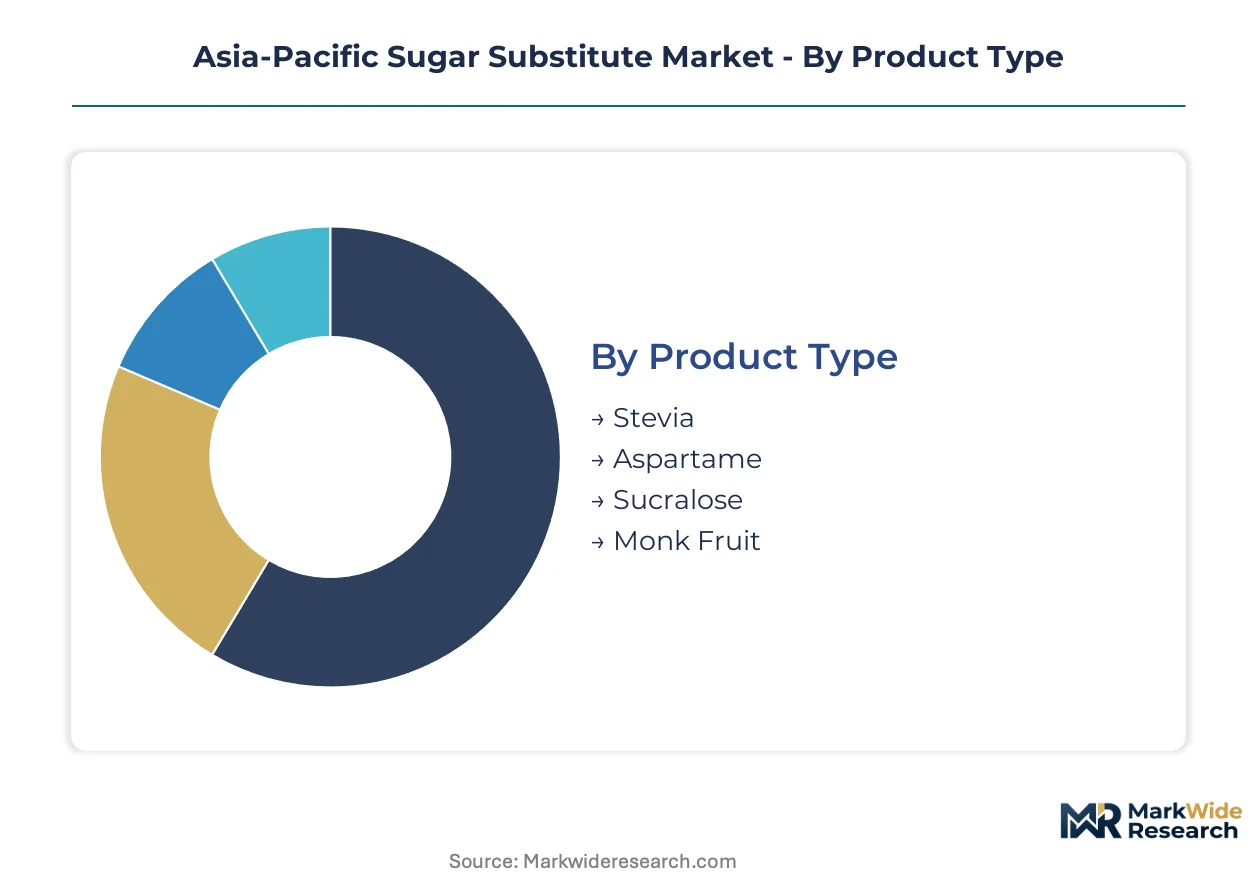
Sugar substitute procurement in Asia-Pacific segments across four critical dimensions. Product chemistry determines regulatory pathway and clean-label positioning. End-user concentration shapes technical service requirements and formulation partnership intensity.
Product Type:
Reformulation cycles accelerate as FSSAI sugar reduction mandates force manufacturers to replace sucrose with compliant alternatives across beverage and confectionery portfolios.
- Stevia:Steviol glycosides extracted from Chinese leaf cultivation dominate volume procurement across the region. Extraction yield improvements and Reb M/Reb D bioprocess engineering are compressing cost structures for premium beverage applications in China's tier-one cities.
- Monk Fruit:Mogrosides from Guangxi cultivation regions command 40-60% price premiums over stevia extracts. Clean-label confectionery manufacturers in South Korea and Australia absorb concentrated supply for premium chocolate and gummy positioning.
- Aspartame:Amino acid-derived synthetic sweetener maintains cost advantage in mass-market carbonated drinks despite clean-label headwinds.
- Sucralose:Chlorinated sugar derivative sustains thermal stability advantages for baked good applications requiring high-temperature processing.
Volume placements concentrate in Stevia; the faster expansion belongs to Monk Fruit.
End User:
Customer type stratification reveals divergent technical service intensity and procurement scale economics across the value chain.
- Food Manufacturers:Packaged goods producers across India and Southeast Asia drive bulk sweetener procurement for reformulated sauces, dressings, and dairy analogs. FSSAI front-of-pack labeling compliance compresses formulation timelines toward natural systems.
- Beverages:Functional drink startups in Shanghai, Beijing, and Shenzhen concentrate demand for precision-blended natural sweeteners in protein waters and kombucha variants. Subscription-based technical partnerships are displacing spot-market procurement among mid-size brands.
- Nutraceuticals:Precision-nutrition formulators in Japan's functional foods segment require amino acid-derived and rare glycoside variants for diabetic and weight-management positioning.
- Bakeries:India's PLI scheme for food processing incentivizes domestic reformulation capacity for reduced-sugar bread and pastry applications.
Procurement scale peaks with Food Manufacturers; the steepest service intensity expansion tracks Beverages.
Distribution Channel:
Channel configuration determines formulation support embedding and customer acquisition economics for ingredient suppliers.
- Online Retail:Direct-to-manufacturer platforms enable small-batch procurement for startup beverage brands and regional confectioners. Technical documentation and sensory matching resources accompany digital transactions.
- Supermarkets:Mass-market retail absorption of finished reduced-sugar products indirectly channels bulk sweetener demand through co-manufacturer networks.
- Specialty Stores:Premium ingredient distributors in Singapore and Sydney serve clean-label chocolatiers and artisanal bakery segments.
- Wholesale:Traditional bulk distribution maintains dominance in price-sensitive Indian rural markets where sucrose cost competitiveness limits substitute penetration.
Transaction volume flows through Wholesale; the channel gaining share fastest is Online Retail.
Application:
Application-specific formulation requirements dictate sweetener blend complexity and regulatory validation burden.
- Diabetes Management:Clinical nutrition and therapeutic food applications demand glycemic index documentation and physician channel validation. Japan's Consumer Affairs Agency positive-list governance constrains novel extract commercialization.
- Lifestyle Foods:Wellness-positioned packaged goods across China's SAMR-regulated dairy analog segment require multi-sweetener blends to comply with GB 2760 maximum usage levels.
- Bakery Products:Thermal stability and Maillard reaction compatibility drive sucralose and erythritol preference for reduced-sugar bread and pastry in India's expanding domestic processing capacity.
- Confectionery:Clean-label gummies and premium chocolates in South Korea and Australia absorb monk fruit supply for specialty retail positioning.
Current formulation investment clusters in Lifestyle Foods; the application climbing fastest is Confectionery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates stevia leaf cultivation and extraction capacity, while consumption gravity shifts toward India's reformulating packaged food sector and Southeast Asia's functional beverage manufacturing hubs. This production-consumption divide shapes procurement patterns and technical service deployment across the region.
China
Guangxi and Fujian provinces dominate steviol glycoside extraction, supplying global beverage reformulators with improving Reb A yields. SAMR enforces GB 2760 maximum usage levels for non-sugar sweeteners in dairy analogs, forcing multi-ingredient blend engineering. Shanghai and Shenzhen functional drink startups concentrate demand for precision-fermented rare glycosides in protein waters and kombucha variants.
India
FSSAI front-of-pack labeling rules compress formulation timelines for packaged food manufacturers seeking reduced-sugar positioning. The PLI scheme for food processing incentivizes domestic erythritol and polyol manufacturing capacity expansion in Maharashtra and Gujarat. Tier-one city beverage brands accelerate procurement switches toward monk fruit and stevia systems to maintain shelf compliance.
Japan
The Consumer Affairs Agency maintains positive-list governance for functional sweetener claims, constraining novel extract commercialization. Amino acid-derived sweetener science anchors competition in Tokyo and Osaka precision-nutrition segments. Domestic formulators prioritize validated glycoside variants for diabetic and weight-management therapeutic food applications.
South Korea
Clean-label confectionery manufacturers in Seoul and Gyeonggi-do absorb concentrated monk fruit supply for premium chocolate and gummy positioning. Specialty retail channels drive 40-60% price premiums over stevia extracts. Domestic distributors serve artisanal bakery segments with technical documentation and sensory matching resources.
Australia
Sydney and Melbourne specialty ingredient distributors anchor clean-label procurement for premium confectionery and artisanal bakery segments. Natural sweetening systems penetrate specialty retail faster than mass-market channels where sucrose cost competitiveness persists. Technical partnerships with Southeast Asian co-manufacturers extend regional service reach.
Asia-Pacific Sugar Substitute Market Competitive Environment
Top-tier vendors anchor technical service bundling, while mid-scale extractors compete on yield economics and regional cultivation access. The vendor base stratifies across multinational ingredient conglomerates with integrated formulation capabilities and specialized stevia or monk fruit extractors serving clean-label niches. Three archetypes dominate: fermentation-science biotechs, leaf-extraction specialists, and full-service sweetness system integrators. Capacity expansion in Chinese bioprocess facilities and subscription-based partnership models represent the dominant competitive vectors reshaping procurement relationships.
Among Asia-Pacific headquartered specialists, Ajinomoto Inc. occupies a position within amino acid-derived sweetener science, while PureCircle exemplifies steviol glycoside extraction scale. Tate & Lyle PLC anchors the technical service tier through Singapore-based beverage reformulation partnerships. These three represent distinct archetypes—fermentation precision, agricultural extraction, and integrated formulation support—competing for share across Japan's regulated therapeutic segment, China's tier-one functional beverage startups, and India's compliance-driven packaged food reformulation.
| Leading Market Players |
|---|
| Tate & Lyle PLC |
| DuPont de Nemours Inc. |
| Cargill Incorporated |
| PureCircle |
| Roquette Freres |
| Archer Daniels Midland Company |
| Ingredion Incorporated |
| International Flavors & Fragrances Inc. |
| Ajinomoto Inc. |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between FSSAI-compliant natural sweeteners and commodity-grade synthetic alternatives manifests in both procurement premiums and supply chain bifurcation. India's front-of-pack labeling rules compress formulation timelines toward validated steviol glycosides and monk fruit extracts, while Chinese leaf cultivation concentration shapes raw material cost structures across the region.
Pricing Analysis
Cost compression in mass-market stevia extracts accelerates as Chinese bioprocess engineering scales Reb M and Reb D production. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade rare glycosides from beverage-grade Reb A and commodity Reb C extracts. Price differentiation traces to FSSAI validation requirements and extraction purity grades. Rural Indian bakery manufacturers exhibit highest price sensitivity; functional beverage startups in Shanghai and Shenzhen absorb premium positioning with least resistance.
Supply Chain Analysis
Returns and quality rejection flows from FSSAI non-compliance audits create reverse-logistics complexity for reformulated product batches. Raw material sourcing concentrates in Guangxi and Fujian provinces for stevia leaf cultivation, with monk fruit extraction anchored in Guangxi and erythritol fermentation scaling in Maharashtra and Gujarat. Supply chain risk centers on single-source vulnerability from Chinese harvest volatility and monsoon-dependent leaf yields. Distribution runs through Singapore technical centers for formulation-embedded partnerships and Mumbai bulk distribution for price-sensitive packaged food manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where India's FSSAI sugar reduction mandates erect barrier-to-entry moats favoring validated natural sweetener suppliers over unvalidated novel extractors.
For Market Incumbents: Cement technical service bundling through Singapore and Mumbai formulation centers to lock in beverage reformulation partnerships before bioprocess engineering commoditizes rare glycoside premiums. Expand captive stevia leaf cultivation contracts in Guangxi to offset harvest volatility threatening supply security. Capacity addition in Indian erythritol fermentation infrastructure captures PLI scheme incentives while synthetic sweetener price erosion from Chinese biotech scaling threatens legacy margins. For New Entrants and Emerging Players: The 40-60% price premium gap between monk fruit and stevia extracts creates white-space opportunity for precision-fermented rare glycoside production at mid-tier pricing. Target South Korean clean-label confectionery manufacturers seeking alternatives to Chinese supply concentration. Penetrate Australia's specialty ingredient distributor channel with technical documentation and sensory matching resources as the fastest viable go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with bioprocess-engineering specialists given precision fermentation's compression of rare glycoside cost structures. Long-term viability favors fermentation-science platforms over agricultural extraction models across the analysis window. Acquisition target archetype: Singapore-based technical service integrators with embedded beverage brand partnerships. Monitor FSSAI enforcement intensity and SAMR GB 2760 maximum usage level revisions as regulatory inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Reb M and Reb D bioprocess engineering collapses cost structures for premium beverage applications. |
| FSSAI Compliance Certification | Validated natural sweetener status creates procurement preference in India's reformulating packaged food sector. |
| Technical Service Subscription Model | Singapore-based formulation partnerships displace transactional bulk sweetener procurement among mid-size brands. |
| Backward Integration into Leaf Cultivation | Captive Guangxi stevia contracts mitigate harvest volatility and price instability for extractors. |
| Multi-Sweetener Blend Engineering | GB 2760 maximum usage compliance in Chinese dairy analogs requires glycoside-polyol ratio optimization. |
Study Parameters
Regulatory filings from FSSAI, SAMR, and Japan's Consumer Affairs Agency, trade data from Indian customs and Chinese export statistics, and industry association reports from Singapore food ingredient federations formed the secondary backbone. Primary interviews with beverage reformulation directors, FSSAI compliance officers at packaged food manufacturers, stevia extraction plant managers in Guangxi, and monk fruit cultivation cooperative leaders in Guangxi validated demand assumptions. Bottom-up volume estimates from application-specific procurement patterns triangulated against top-down market sizing from trade flow analysis.
Bottom-up modeling segmented procurement by product chemistry, end-user concentration, and regulatory pathway complexity. Analytical framework projected adoption curves for natural versus synthetic sweeteners across beverage, confectionery, bakery, and nutraceutical applications. CAGRs derived from regression analysis of historical procurement volumes against regulatory enforcement intensity and consumer clean-label preference indices. Industry-specific forecast inputs incorporated FSSAI sugar reduction timeline compliance rates and Chinese bioprocess facility capacity expansion announcements.
Inputs from SAMR GB standard enforcement records and FSSAI front-of-pack labeling implementation audits were available through the study window; gaps in real-time monk fruit harvest yield data and proprietary extraction cost structures introduce uncertainty bands around price elasticity assumptions. Forecasts reflect documented regulatory timelines and announced capacity investments. Practitioners should monitor FSSAI penalty enforcement rates and Chinese leaf cultivation region weather patterns for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Monk Fruit Sweetener Market
Sweeteners
Italy Food Sweetener Market
Sweeteners
Global Brown Sugar Market
Sweeteners
Europe Sugar Substitute Market
Sweeteners
Sugar Market
Sweeteners
Asia-Pacific Low-Calorie Sweeteners Market
Sweeteners
Steviol Glycoside Market
Sweeteners
Organic Palm Sugar Market
Sweeteners
India Food Sweetener Market
Sweeteners
Natural Caloric Sweeteners Market
Sweeteners
North America High-Intensity Sweeteners Market
Sweeteners
South Korea Allulose Market
Sweeteners
Dry Molasses Market
Sweeteners
Tapioca Maltodextrin Market
Sweeteners
China Food Sweetener Market
Sweeteners
South America Food Sweetener Market