
 Sanding Sugar Market | 2026-2036
Sanding Sugar Market Size, Share, and Industry Trends Forecast 2026-2036
Sanding Sugar Market Analytics
Multi-source procurement among industrial bakers is consolidating toward vertically integrated sugar refiners with certified food-grade operations. Cargill leverages its North American beet and cane processing network to secure long-term contracts with national bakery chains. Sudzucker AG anchors European supply through specialized crystallization lines that yield consistent particle-size distribution for decorative applications. Sensient Technologies differentiates via integrated color-coating capabilities that merge sanding sugar with certified pigment systems for confectionery clients.
Sanding sugar consists of large-crystal sucrose particles, typically ranging from 0.5 to 2.0 millimeters, manufactured through controlled cooling and crystallization of supersaturated sugar syrups to produce non-melting decorative toppings that retain structural integrity during baking. Coarse and extra coarse grades dominate industrial volume due to their visual impact on premium cookies and artisan breads, while colored variants command higher margins through custom formulation services tied to seasonal and private-label programs. The application split tilts toward baking and confectionery, where food manufacturers seek batch-to-batch consistency for automated decorating lines.
The FDA enforces Current Good Manufacturing Practice regulations and allergen labeling requirements that dictate sanding sugar purity standards and facility segregation protocols for colored additive variants. The EPA oversees wastewater discharge limits from cane and beet processing facilities, directly affecting refinery location decisions and capital allocation for North American producers. Stakeholders must monitor evolving state-level sugar taxes and clean-label certification programs that could redirect formulation choices toward reduced-sugar decorative alternatives or natural colorant systems.
Market Dynamics
Industrial bakers are consolidating procurement around vertically integrated refiners with certified food-grade operations, compressing supplier lists and elevating batch-to-batch consistency requirements for automated decorating lines.
Growth Catalysts
- Artisanal Baking Expansion:Premium cookie and artisan bread programs at national bakery chains are scaling decorative finishing, pulling volume toward coarse-grade sanding sugar with visual impact specifications.
- FDA Traceability Mandates:The Food Safety Modernization Act's updated ingredient traceability requirements are reshaping supplier qualification protocols, advantaging refiners with integrated beet and cane processing networks.
- Seasonal Color Programming:Confectionery manufacturers are expanding private-label and holiday-themed product lines, driving demand for custom-formulated colored variants with certified pigment systems.
Market Restraints
- Beet Sugar Input Volatility:Weather-driven yield fluctuations in North American beet-growing regions create raw material cost instability for domestic refiners.
- Processing Concentration Risk:A limited number of specialized crystallization lines capable of producing consistent particle-size distribution for decorative applications creates supply bottleneck vulnerability.
- Clean-Label Substitution Pressure:State-level sugar taxes and reduced-sugar certification programs are redirecting some formulation choices toward alternative decorative toppings.
Strategic Opportunities
- Natural Colorant Convergence:Integration of plant-derived pigment systems with traditional sanding sugar production is opening premium positioning for clean-label confectionery lines.
- EPA Compliance Advantage:Refineries with advanced wastewater treatment infrastructure can secure expansion permits in cane and beet processing regions where discharge limits are tightening.
- E-Commerce Channel Development:Direct-to-baker distribution platforms are emerging as a procurement alternative for small-batch artisan producers seeking specialty grades.
Industry Challenges
- Particle-Size Engineering Talent:Crystallization process expertise for controlled cooling applications remains concentrated among legacy refinery technical staff approaching retirement.
- Allergen Segregation Infrastructure:Colored additive variants require dedicated facility zones and cleaning protocols, extending capital deployment timelines for multi-product refiners.
- Legacy Equipment Integration:Automated decorating lines at industrial bakeries demand precise flow characteristics, creating friction when retrofitting older production systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sanding Sugar Market |
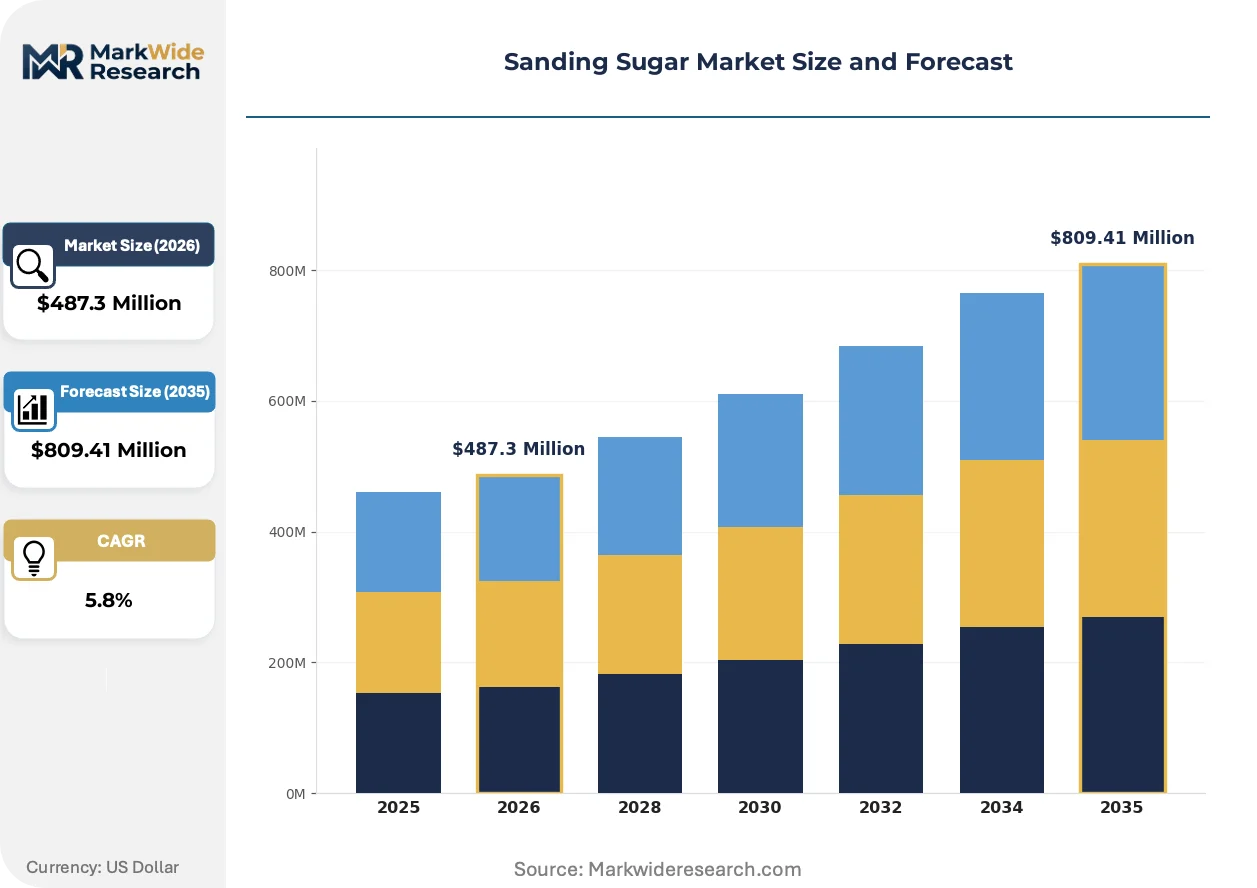
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Superfine, Coarse, Extra Coarse, Colored Application: Baking, Confectionery, Beverages, Dairy Products Distribution Channel: Online Retailers, Supermarkets, Specialty Stores, Wholesale End User: Food Manufacturers, Bakeries, Retailers, Restaurants |
| Companies Covered | Cargill, Tate & Lyle, Ingredion, Kerry Group, Sensient Technologies, Sudzucker AG, Associated British Foods, Louis Dreyfus Company, Tereos, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sanding Sugar Market Evolving Landscape
Precision crystallization technology and regulatory traceability mandates are converging to reshape how decorative sugar products are specified, sourced, and validated across industrial baking and confectionery supply chains.
Controlled cooling crystallization systems with real-time particle-size monitoring are rewriting quality assurance protocols for decorative sugar production. National bakery chains with automated decorating lines are adopting these systems at accelerating pace to eliminate batch-to-batch variation. The technology is compressing tolerance windows for visual consistency, forcing smaller refiners toward contract tolling arrangements.
The FDA's updated Food Safety Modernization Act traceability requirements are mandating lot-level documentation from raw sugar source through finished product distribution. Industrial bakers are responding by narrowing approved supplier lists to refiners with integrated processing and certified segregation protocols. Colored sanding sugar variants face the most stringent documentation burden due to additive handling requirements.
Bakery procurement departments are consolidating annual contracts around vertically integrated suppliers with captive beet and cane sourcing. Multi-source buying patterns that once characterized the category are giving way to sole-source or dual-source arrangements with volume guarantees. This concentration is most visible among North American national bakery chains seeking to simplify supplier audits and reduce qualification overhead.
Sanding Sugar Market Segmentation
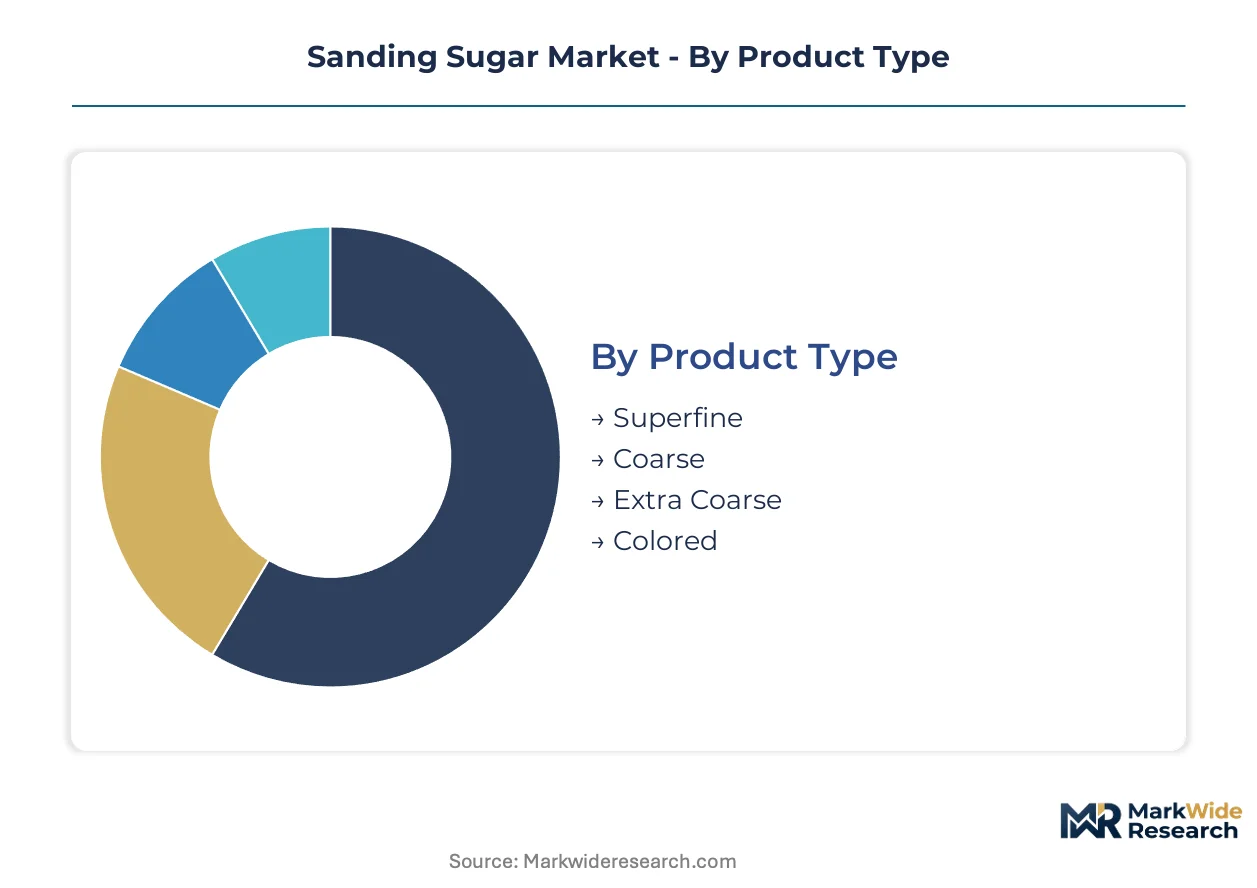
Sanding sugar buyers select grades based on thermal stability requirements and visual impact specifications for automated decorating lines. Product differentiation across crystal size and color certification drives procurement consolidation toward suppliers with integrated processing capabilities.
Product Type:
Buyers differentiate by thermal performance needs and decorating equipment compatibility, with coarse grades commanding premium positioning for artisan applications.
- Coarse:Crystal size ranges from 1.0 to 2.0 millimeters, produced through extended cooling cycles that yield structural integrity under oven temperatures. National bakery chains in the United States specify this grade for automated cookie lines where visual impact drives consumer purchase decisions.
- Extra Coarse:Particles exceed 2.0 millimeters, manufactured via specialized seed-crystallization techniques that prevent dissolution during proofing. Artisan bread programs at regional bakery chains favor this grade for rustic finishing where texture contrast commands shelf price premiums.
- Superfine:Sub-0.5 millimeter crystals suit beverage rim applications and delicate pastry work where rapid dissolution is required.
- Colored:Pigment-infused variants incorporate certified colorant systems with dedicated allergen-segregation protocols for seasonal confectionery programs.
Coarse grades lead volumes today; colored variants are gaining share fastest.
Application:
Volume concentration tracks capital deployment in automated decorating infrastructure, with baking operations pulling the majority of industrial-grade supply.
- Baking:Cookie, bread, and pastry applications demand batch-to-batch consistency for high-speed finishing lines. FDA traceability mandates are compressing supplier lists to refiners with certified food-grade operations and documented lot-level sourcing.
- Confectionery:Hard candy, chocolate garnish, and seasonal novelty production requires precise flow characteristics for mechanized coating systems. Private-label holiday programs at major confectionery houses are expanding custom color formulation services.
- Beverages:Rim garnishing for premium cocktail programs and ready-to-drink formulations drives specialty-grade procurement.
- Dairy Products:Frozen dessert topping applications favor non-melting crystal structures that retain definition under cold storage conditions.
Baking applications dominate current procurement volumes; confectionery represents the steepest expansion trajectory.
Distribution Channel:
Channel selection reflects order scale and technical service requirements, with bulk operations consolidating around direct refinery relationships.
- Wholesale:Industrial bakeries and food manufacturers procure through annual volume contracts with integrated refiners. Cargill's North American beet and cane processing network secures long-term supply agreements with national bakery chains seeking simplified qualification overhead.
- Online Retailers:Small-batch artisan producers access specialty grades through direct-to-baker platforms. E-commerce channels are emerging as procurement alternatives for producers requiring custom particle-size specifications below minimum order thresholds.
- Supermarkets:Consumer-packaged goods for home baking applications flow through retail grocery networks.
- Specialty Stores:Professional supply outlets serve independent bakeries with technical consultation and sample validation services.
Wholesale channels capture the largest transaction values; online retail is climbing the fastest.
End User:
User type determines specification rigor, with food manufacturers enforcing the tightest tolerance windows for automated production systems.
- Food Manufacturers:Industrial-scale operations require certified segregation protocols and documented allergen controls for colored additive variants. Multi-source procurement patterns are consolidating toward vertically integrated suppliers with captive sourcing and integrated crystallization lines.
- Bakeries:National chains deploy automated decorating lines that demand precise flow characteristics, while artisan operators prioritize visual impact specifications for hand-finished products.
- Retailers:Private-label program development drives seasonal color programming and custom formulation services.
- Restaurants:Dessert presentation and beverage garnish applications favor specialty grades with rapid-dissolution or non-melting properties.
Food manufacturers lead absolute consumption; bakeries are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States industrial baking corridors anchor decorative sugar procurement volumes. FDA traceability mandates and artisanal baking expansion are compressing supplier lists toward vertically integrated refiners with certified food-grade operations. National bakery chains in Chicago, New York, and Los Angeles metro areas are consolidating annual contracts around captive beet and cane sourcing networks.
United States
National bakery chains scale automated decorating lines across Midwest and Northeast corridors, pulling coarse-grade volumes for premium cookie programs. FDA Food Safety Modernization Act requirements mandate lot-level documentation from raw sugar source through distribution. Industrial refiners in Minnesota and Michigan beet-growing regions are securing long-term supply agreements with simplified qualification protocols.
Germany
Artisan bread programs at regional bakery chains favor extra coarse grades for rustic finishing applications. EFSA additive regulations and REACH compliance frameworks govern certified pigment systems for colored variants. Specialized crystallization facilities in Bavaria and North Rhine-Westphalia yield consistent particle-size distribution for confectionery export markets.
France
Luxury confectionery houses expand private-label holiday programs requiring custom color formulation services. ANSM oversees colorant certification for decorative sugar applications in food contact materials. Paris and Lyon metropolitan clusters concentrate seasonal production facilities for European confectionery distribution.
United Kingdom
Industrial bakers deploy high-speed finishing lines demanding batch-to-batch consistency for automated decorating systems. FSA allergen labeling requirements dictate facility segregation protocols for colored additive variants. Greater London and West Midlands baking corridors consolidate procurement around refiners with integrated processing capabilities.
Canada
Cross-border supply agreements with United States refiners dominate procurement for national bakery chains. Health Canada establishes purity standards for decorative sugar imports and domestic production. Ontario and Quebec industrial baking clusters leverage proximity to Michigan beet processing facilities for volume contracts.
Sanding Sugar Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue natural colorant convergence and e-commerce channel development. The supplier base concentrates around vertically integrated sugar refiners with captive beet and cane sourcing networks. Three archetypes dominate: integrated agricultural processors with crystallization expertise, specialized color-coating technology providers, and regional tolling refiners serving artisan segments. Capacity expansion and strategic partnerships represent the dominant competitive vectors as batch-to-batch consistency requirements tighten.
Among North American agricultural processors, Cargill anchors the integrated refiner archetype with beet and cane network coverage. Sudzucker AG exemplifies European crystallization specialization through controlled cooling production systems. Sensient Technologies occupies the color-coating technology tier, merging decorative sugar with certified pigment systems for confectionery applications. These three entities represent the consolidation trajectory reshaping supplier qualification protocols.
| Leading Market Players |
|---|
| Cargill |
| Tate & Lyle |
| Ingredion |
| Kerry Group |
| Sensient Technologies |
| Sudzucker AG |
| Associated British Foods |
| Louis Dreyfus Company |
| Tereos |
| Others |
Value Network & Pricing Analysis
Automated decorating line specifications at United States national bakery chains are compressing tolerance windows for batch-to-batch consistency, forcing supply response through dedicated crystallization capacity and certified segregation infrastructure that elevates pricing for compliant tiers.
Pricing Analysis
Input-cost pass-through from North American beet sugar volatility flows directly into coarse-grade quotations, with weather-driven yield fluctuations in Minnesota and Michigan growing regions creating quarterly price adjustments in contract structures. Three-tier pricing structure across premium, standard, and economy levels separates FDA-certified colored variants with full traceability documentation from industrial white-grade volumes and toll-processed artisan grades. Pricing pressure stems from clean-label substitution campaigns in states with sugar tax exposure. Small-batch artisan bakers exhibit highest price sensitivity; national chains with sole-source arrangements absorb premiums for supply security.
Supply Chain Analysis
Certification and qualification gating through FDA Food Safety Modernization Act traceability mandates is consolidating approved supplier lists toward vertically integrated refiners with captive beet and cane sourcing. Production concentrates in the United States, Germany, and France, where integrated agricultural processors maintain controlled cooling crystallization lines. Raw material flows draw from North American beet-growing corridors, Brazilian cane harvests, and European sugar beet cooperatives. Single-source vulnerability concentrates in specialized seed-crystallization equipment for extra coarse grades. Distribution runs through direct refinery contracts for industrial volume, with e-commerce platforms emerging for specialty-grade fragmentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory arbitrage between EPA wastewater discharge limits in United States cane processing regions and EFSA additive frameworks in Europe creates cost-differential opportunities for refiners with transferable compliance infrastructure.
For Market Incumbents: Cement market position through backward integration into captive beet sourcing in Michigan and Minnesota growing regions, while deploying allergen-segregation infrastructure ahead of FDA enforcement waves. Natural colorant convergence threatens pigment-infused margin tiers; counter through certified clean-label formulation services. Capacity addition in Bavaria crystallization facilities secures European confectionery export continuity. For New Entrants and Emerging Players: Small-batch artisan bakeries seeking custom particle-size specifications below minimum order thresholds represent the most penetrable buyer archetype. White-space targets include direct-to-baker e-commerce platforms with technical consultation services, and toll-processing arrangements for legacy refiners lacking real-time particle-size monitoring. Geographic entry priority sits with Ontario and Quebec industrial baking clusters leveraging cross-border supply agreements. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale refiners possessing EPA-compliant wastewater infrastructure in tightening discharge regions. Long-term viability frames around crystallization process expertise transfer as legacy technical staff approach retirement. Acquisition target archetype: regional tolling refiners with established artisan relationships and expandable certification scope. Signal to watch: FDA lot-level documentation enforcement intensity at colored variant facilities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Beet Sourcing | Secures raw material cost stability against weather-driven yield fluctuations in North American growing regions. |
| Natural Colorant Certification Program | Positions premium tiers for clean-label confectionery lines under EFSA and FDA evolving pigment frameworks. |
| Direct-to-Baker E-Commerce Platform | Captures small-batch artisan volume below traditional wholesale minimum order thresholds. |
| EPA Wastewater Infrastructure Upgrade | Unlocks expansion permits in cane and beet processing regions where discharge limits are tightening. |
| Crystallization Process Expertise Transfer | Mitigates concentration risk as legacy refinery technical staff approach retirement age. |
Research Methodology
Direct dialogue with refinery operations managers, national bakery chain procurement directors, confectionery house R&D leads, and FDA compliance officers grounded qualitative findings, cross-referenced against SEC 10-K filings from integrated agricultural processors, EPA discharge permit databases, USDA crop yield reports, and customs trade records for sugar product flows. Bottom-up volume estimates from crystallization line capacity and top-down demand validation from automated decorating line deployments were triangulated for convergence.
Segment-level projections across crystal size grades, application categories, and distribution channels were generated through the analytical framework over the projection horizon. CAGRs were derived from regression analysis against bakery capital expenditure cycles and confectionery seasonal programming intensity. Industry-specific inputs included FDA traceability mandate implementation timelines and EPA wastewater permit issuance patterns.
Underlying measurement precision varies by segment; coarse and extra coarse grades carry tighter precision than superfine variants due to clearer industrial volume tracking. Forecasts reflect assumptions about regulatory enforcement continuity and clean-label substitution elasticity. A model refresh is warranted upon material change in FDA lot-level documentation requirements or state-level sugar tax expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Global Alternative Sweeteners Market
Sweeteners
Canada Food Sweetener Market
Sweeteners
Japan Food Sweetener Market
Sweeteners
North America Starch Sweetener Market
Sweeteners
Sour Sugar Market
Sweeteners
India Food Sweetener Market
Sweeteners
Organic Palm Sugar Market
Sweeteners
Xylose Market
Sweeteners
Glucose-Fructose Syrup (GFS) Market
Sweeteners
Floral Nectar Market
Sweeteners
Invert Sugar Market
Sweeteners
Global Brown Sugar Market
Sweeteners
Europe Food Sweetener Market
Sweeteners
Russia Food Sweetener Market
Sweeteners
Smoked Sugar Market
Sweeteners
Sugar Polyols Market