
 Clams, Cockles, Ark Shells Market | 2026-2036
Clams, Cockles, Ark Shells Market Size, Share, and Industry Trends Forecast 2026-2036
Clams, Cockles, Ark Shells Market Intelligence
Direct-to-restaurant distribution is rewriting procurement patterns across the bivalve supply chain. Clifton Seafood Company leverages long-standing relationships with East Coast dining establishments to sustain premium pricing for live product. Krijn Verwijs Yerseke anchors European supply through its vertically controlled Dutch harvesting and conditioning operations.
Clams, cockles, and ark shells comprise edible marine bivalve mollusks characterized by hinged calcium carbonate shells, filter-feeding physiology, and protein content ranging from twelve to twenty percent wet weight; these species serve commercial markets as raw seafood, processed ingredients, and aquaculture seed stock. The product type dimension shows cockles commanding mature volume in European retail while razor clams represent the fastest-growing North American restaurant segment due to their extended shelf appeal and distinctive texture. Aquaculture-based harvesting dominates margin pools through predictable supply and certification premiums, whereas wild dredging occupies commoditized channels with thinner returns.
NOAA Fisheries in the United States enforces strict quotas and seasonal closures that shape harvest volumes and pricing volatility for wild stocks. The EU's EFSA hygiene standards and national shellfish sanitation programs in France and Spain regulate depuration protocols and market access for live exports. Stakeholders must monitor evolving water quality classifications and climate-driven range shifts in key growing areas to secure supply continuity and certification status.
Market Dynamics
The EU's Common Fisheries Policy and tightening national aquaculture licensing regimes in Spain and France are forcing supply chain reconfiguration toward full traceability systems. This regulatory pressure is compressing margins for wild-harvest operators while accelerating investment in certified aquaculture infrastructure across European and Asian production zones.
Growth Catalysts
- EFSA Hygiene Standards:The EU's enhanced depuration protocols are creating certification premiums for compliant suppliers. French and Spanish processors are capturing margin expansion through verified live-export channels.
- Ready-to-Eat Seafood Manufacturers:Food manufacturers are absorbing processed bivalve ingredients at expanding volumes. Shandong and Fujian processing clusters are scaling output to meet this ingredient demand.
- Live Seafood Market Density:China's coastal provinces maintain concentrated consumption gravity. Wholesale markets in Guangdong and Zhejiang are driving volume throughput for domestic circulation and re-export.
Market Restraints
- Fuel and Labor Input Volatility:Wild dredging operations face margin compression from diesel price swings and deckhand wage inflation. Dutch and French fleets are consolidating to spread fixed costs.
- NOAA Quota Rigidities:Strict seasonal closures and biomass limits on US Atlantic stocks create supply discontinuities. East Coast distributors absorb pricing volatility through inventory carry costs.
- Filter-Feeder Substitution:Mussel and oyster products compete for the same food-service placement. European retail chains are rotating shelf space toward these alternative bivalves.
Strategic Opportunities
- Depuration Technology Convergence:UV-C treatment systems are integrating with automated sorting robotics. Dutch conditioning facilities are piloting these combined systems for labor reduction.
- Direct-to-Restaurant Channels:Bypassing wholesale layers allows capture of premium pricing. East Coast US distributors are building captive chef relationships.
- India's Underpenetrated Processing Base:The subcontinent's bivalve aquaculture remains nascent against its coastline length. Kerala and Tamil Nadu harbor greenfield development potential for export-oriented units.
Industry Challenges
- HACCP Certification Timelines:New market entrants face extended approval periods for EU export eligibility. Depuration facility validation requires 12-18 month track records.
- Climate-Driven Range Shifts:Warming water temperatures are displacing traditional growing areas. Spanish producers are relocating seed stock operations northward along Galician coasts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clams, Cockles, Ark Shells Market |
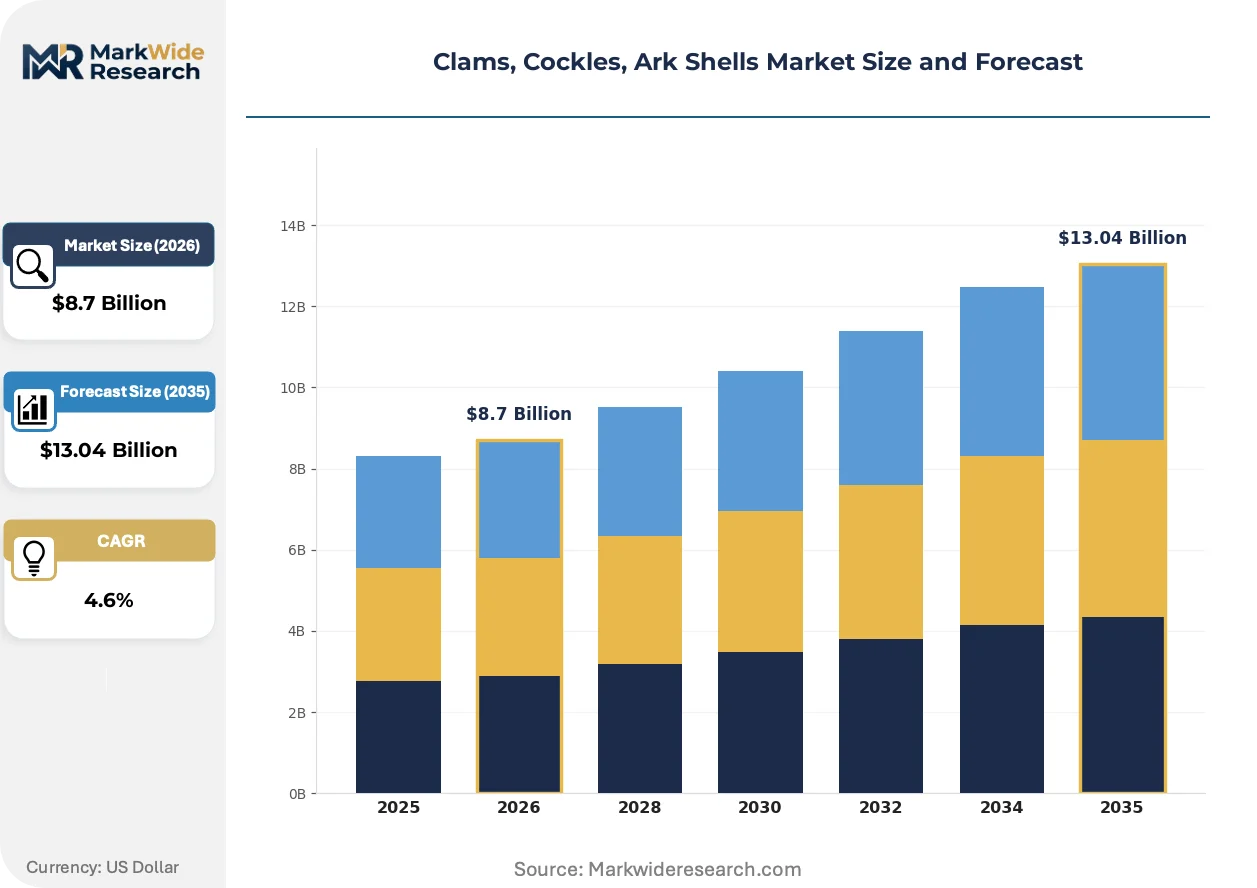
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clams, Cockles, Ark Shells, Razor Clams Distribution Channel: Retail, Wholesale, Online, Direct Sales End User: Restaurants, Home Cooks, Food Manufacturers, Seafood Markets Harvesting Method: Dredging, Hand-Harvesting, Aquaculture, Trenching |
| Companies Covered | Clifton Seafood Company, John Lake Shellfish, Krijn Verwijs Yerseke, PanaPesca USA, Penn Cove Shellfish, Seacore Seafood, Van der Lee Seafish, Cape Cod Shellfish, Aqua Blue Seafood, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clams, Cockles, Ark Shells Market Strategic Shifts & Innovations
Processing automation and live-holding conditioning systems are compressing labor dependence while extending shelf stability. These shifts are redrawing competitive advantage toward capital-intensive operators with controlled-environment capabilities.
Recirculating aquaculture systems for bivalve conditioning are migrating from experimental pilot scale to commercial deployment. Dutch and Belgian operators are adopting these systems to maintain supply continuity through seasonal closures. The technology is enabling year-round market presence that wild-only harvesters cannot match.
REACH chemical traceability requirements and EU Green Deal sustainability mandates are tightening input documentation for shellfish aquaculture. French producers are restructuring feed sourcing and vessel fuel profiles to maintain market access. The live-export segment to Asian markets faces the most stringent compliance verification.
Chef procurement patterns are rotating toward specified-origin contracts with embedded traceability data. US fine-dining establishments are bypassing traditional seafood houses to source directly from conditioned-holding facilities. This channel compression is most pronounced in New York and San Francisco metropolitan supply sheds.
Clams, Cockles, Ark Shells Market Segmentation
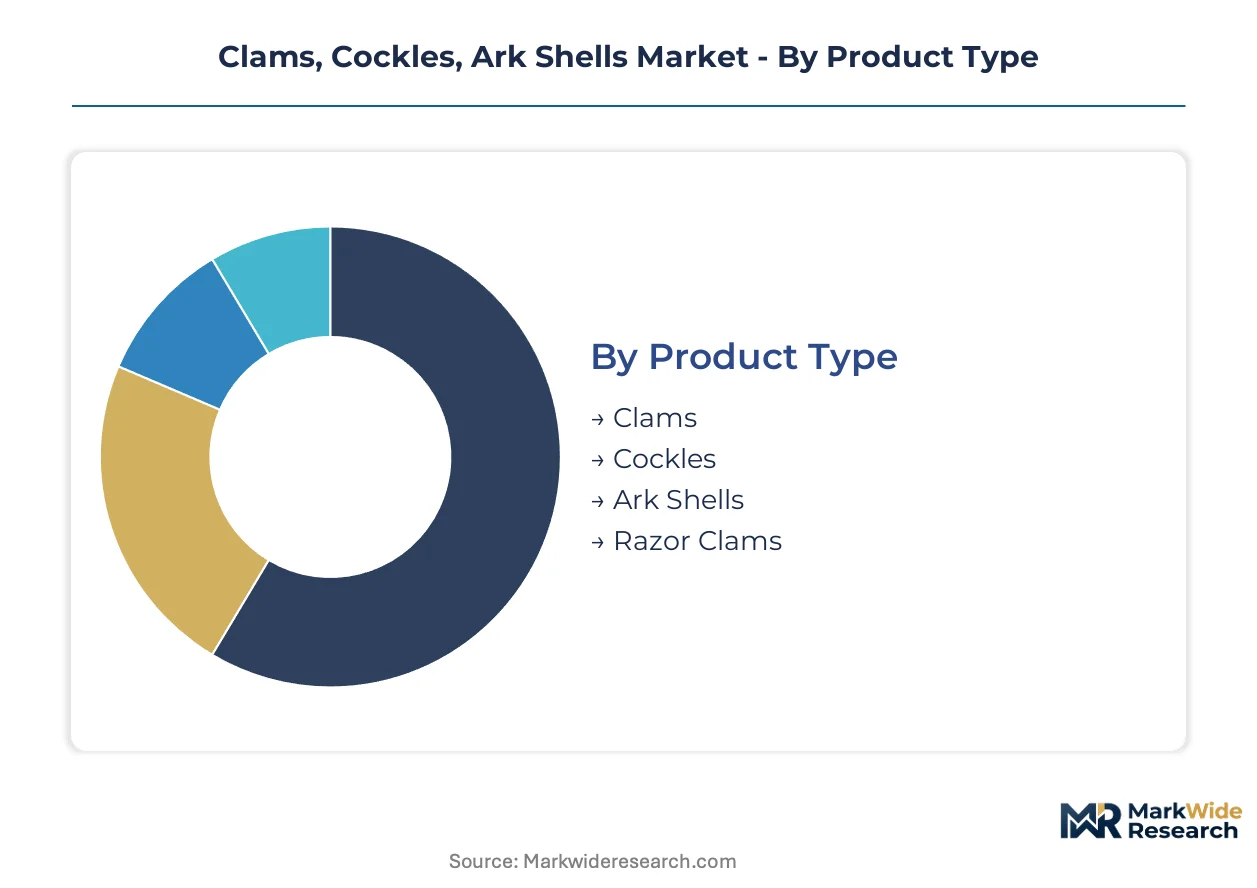
Segmentation in the bivalve trade separates commodity flows from premium live-product channels. Each dimension carries distinct margin profiles, certification requirements, and customer loyalty dynamics that shape supplier strategy.
Product Type:
After-sales service intensity runs highest for live-holding systems where mortality replacement guarantees and conditioning support determine repeat purchasing.
- Clams:Hard-shell varieties dominate North American chowder manufacturing and casino buffet procurement. Chesapeake Bay and Gulf of Mexico wild stocks supply volume, while Florida aquaculture operations capture premium live-market pricing through controlled-environment certification.
- Cockles:Cerastoderma edulis and related species anchor European retail fresh counters with established consumer recognition. Galician hand-harvesting cooperatives maintain Protected Designation of Origin status, commanding shelf price premiums in French and Spanish supermarket chains.
- Ark Shells:Anadara species concentrate in Asian processing channels for dried and canned export.
- Razor Clams:Ensis and Siliqua genera extend shelf life through burrowing behavior, supporting extended logistics windows.
By volume, clams lead. By growth pace, razor clams are ahead.
Distribution Channel:
Cost tier separation distinguishes capital-intensive conditioned-holding infrastructure from arm's-length brokerage arrangements.
- Retail:Supermarket chains and fishmonger counters require depuration certification and cold-chain integrity. French retail groups are consolidating supplier panels to reduce audit burden, favoring multi-species aquaculture operators with integrated logistics.
- Wholesale:Centralized procurement at Rungis, Billingsgate, and Tsukiji successor markets aggregates fragmented supply. Dutch auction systems price product by live-weight grade, with quality premiums for reduced sand content and extended out-of-water survival.
- Online:Direct-to-consumer platforms bypass traditional quality verification layers.
- Direct Sales:Chef-facing distributors capture margin through origin specification and just-in-time delivery.
Wholesale channels move the most tonnage. Direct sales channels are expanding most quickly.
End User:
Application requirements vary sharply between raw consumption and ingredient processing.
- Restaurants:Fine-dining establishments specify live-product provenance with embedded traceability data. New York and San Francisco metropolitan chefs are bypassing seafood houses to source directly from conditioned-holding facilities, compressing supply layers.
- Food Manufacturers:Ready-to-eat seafood producers absorb processed bivalve ingredients at expanding volumes. Shandong and Fujian processing clusters scale output for soup, sauce, and frozen meal applications.
- Home Cooks:Retail fresh counter purchases dominate this segment.
- Seafood Markets:Live-tank display requirements drive sourcing from specialized conditioning operations.
Food manufacturers absorb the greatest volume. Restaurants drive the steepest expansion trajectory.
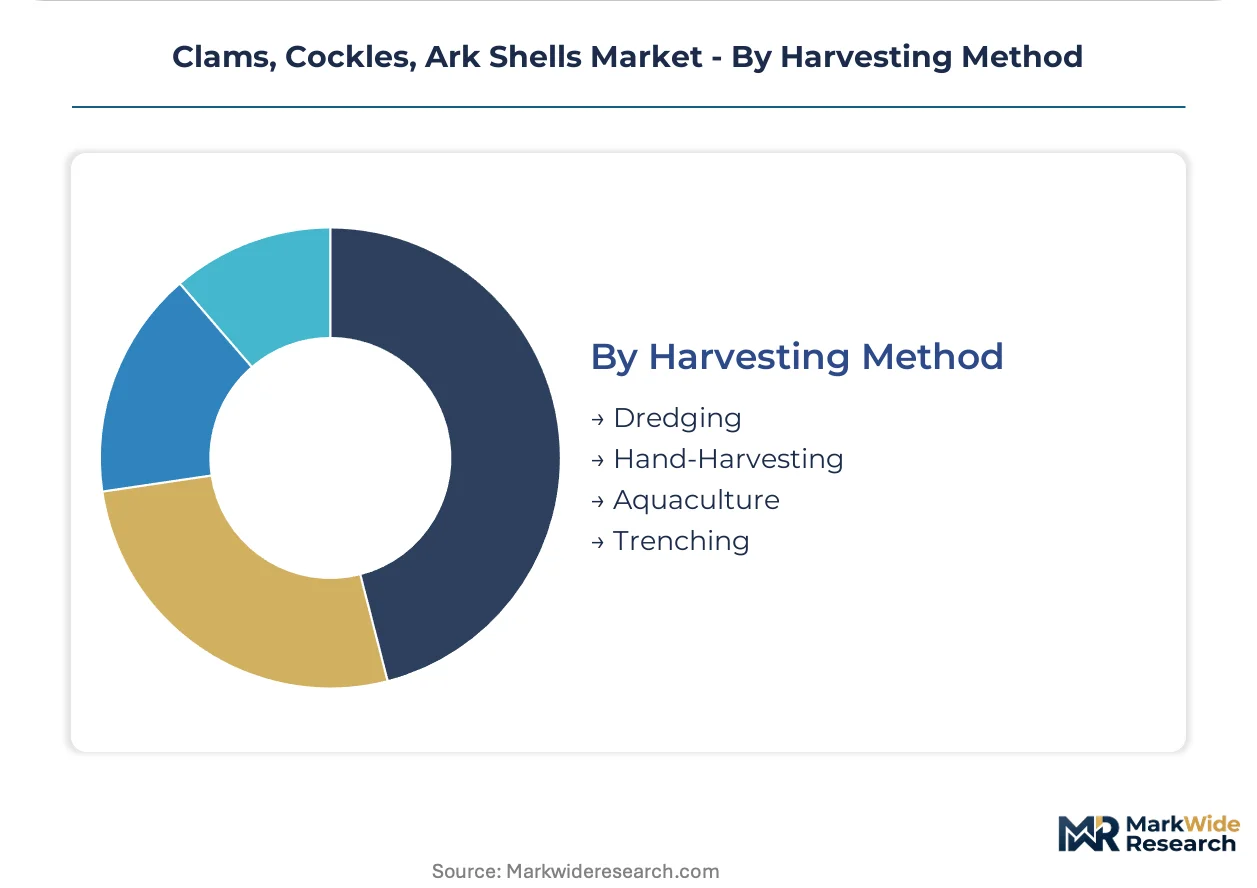
Harvesting Method:
Supply concentration favors predictable aquaculture output over wild-catch variability.
- Aquaculture:Controlled-environment production dominates margin pools through certification premiums and year-round availability. Dutch and Belgian recirculating systems are migrating from pilot to commercial scale, enabling supply continuity through seasonal closures.
- Hand-Harvesting:Labor-intensive collection on intertidal flats sustains Protected Designation of Origin products. Galician and Brittany cooperatives maintain traditional gathering rights, capturing price premiums through geographic indication status.
- Dredging:Mechanical wild harvest occupies commoditized channels with thinner returns.
- Trenching:Semi-culture methods bridge wild and farmed production systems.
Aquaculture leads by volume. Hand-harvesting gains share fastest through premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal sustainability mandates and tightening traceability requirements are redrawing production geography across the bivalve trade. National aquaculture licensing regimes in Spain and France now enforce full-chain documentation. These policy shifts favor capital-intensive operators with controlled-environment capabilities over wild-harvest dependent competitors.
United States
NOAA Fisheries enforces strict seasonal closures and biomass quotas on Atlantic wild stocks. East Coast distributors absorb pricing volatility through inventory carry costs. Processing clusters in Chesapeake Bay and the Gulf of Mexico supply volume to chowder manufacturers and casino buffet operators.
China
Live seafood markets in Guangdong and Zhejiang provinces drive concentrated consumption gravity. Shandong and Fujian processing clusters scale output for soup, sauce, and frozen meal applications. The country's dual carbon goals are pressuring coastal aquaculture operations to document energy inputs and vessel fuel profiles.
Netherlands
Recirculating aquaculture systems for bivalve conditioning are migrating from pilot to commercial scale in Dutch facilities. Krijn Verwijs Yerseke anchors European supply through vertically controlled harvesting and conditioning operations. REACH chemical traceability requirements are tightening input documentation for shellfish aquaculture.
Spain
Galician hand-harvesting cooperatives maintain Protected Designation of Origin status for cockle products. EFSA hygiene standards regulate depuration protocols and market access for live exports. Spanish producers are relocating seed stock operations northward along Galician coasts as warming water temperatures displace traditional growing areas.
France
French retail groups consolidate supplier panels to reduce audit burden, favoring multi-species aquaculture operators with integrated logistics. National shellfish sanitation programs regulate depuration protocols through ANSM oversight. Brittany cooperatives maintain traditional gathering rights, capturing price premiums through geographic indication status.
Clams, Cockles, Ark Shells Market Key Industry Players
On the supply side, the industry is bifurcating between capital-intensive aquaculture operators with controlled-environment certification and wild-harvest dependent competitors facing margin compression. Dutch and Belgian recirculating system specialists occupy the premium tier through year-round availability guarantees. Three archetypes dominate: vertically integrated conditioning-holding facilities, cooperative-based hand-harvesting operations with geographic indication status, and scale-driven processors serving ingredient manufacturing. Competitive moves concentrate on direct-to-restaurant channel capture and depuration technology convergence with automated sorting robotics.
Among North American distributors, Clifton Seafood Company represents the direct-to-restaurant archetype through long-standing East Coast dining establishment relationships. Dutch operators Krijn Verwijs Yerseke and Van der Lee Seafish exemplify the vertically integrated conditioning model with controlled-environment capabilities. These three anchors illustrate how geographic positioning and channel strategy determine margin capture in the current regulatory environment.
| Leading Market Players |
|---|
| Clifton Seafood Company |
| John Lake Shellfish |
| Krijn Verwijs Yerseke |
| PanaPesca USA |
| Penn Cove Shellfish |
| Seacore Seafood |
| Van der Lee Seafish |
| Cape Cod Shellfish |
| Aqua Blue Seafood |
| Others |
Cost & Logistics Intelligence
Overcapacity in Dutch conditioning facilities is compressing spot-market premiums while forcing Galician hand-harvesters toward longer-term offtake contracts. This utilization dynamic rewards capital-intensive aquaculture operators with year-round pricing power and squeezes wild-harvest margins during seasonal gluts.
Pricing Analysis
Three-tier pricing structure across premium live-holding, standard wholesale, and economy processing grades separates certified aquaculture output from wild-dredged commodity flows. Price differentiation hinges on EFSA depuration certification and live-weight survival guarantees, with New York and San Francisco metropolitan chefs absorbing the steepest premiums for traceable provenance. Cost compression in the economy tier is intensifying because diesel input volatility and deckhand wage inflation erode dredging margins. Food manufacturers exhibit the highest price sensitivity due to volume procurement and ingredient substitutability, while fine-dining establishments show inelastic demand for specified-origin live product.
Supply Chain Analysis
Upstream seed stock and broodstock operations draw from Netherlands, Spain, and China production zones, with Galician nurseries supplying European grow-out facilities and Shandong hatcheries feeding Asian processing clusters. Feed inputs center on phytoplankton culture systems, conditioning facility energy profiles, and vessel fuel sourcing for wild harvest operations. Single-source vulnerability concentrates in Dutch recirculating system technology providers, where equipment lead times create bottlenecks for capacity expansion. Distribution runs through Rungis and Billingsgate wholesale markets for European circulation, with direct-to-restaurant channels capturing margin in North American metropolitan supply sheds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is cycling through a recovery phase anchored to EFSA regulatory tightening, which is compressing wild-harvest margins and reallocating volume toward certified aquaculture infrastructure.
For Market Incumbents: Build regulatory compliance moats through accelerated HACCP certification investment and captive depuration facility expansion. Dutch operators should deepen backward integration into seed stock genetics to lock in supply continuity, while Galician cooperatives must defend Protected Designation of Origin status against climate-driven range shifts that threaten traditional harvesting grounds. For New Entrants and Emerging Players: Build out greenfield recirculating aquaculture capacity in India's Kerala and Tamil Nadu coastal zones, where bivalve processing infrastructure remains underpenetrated relative to coastline length. Target ready-to-eat seafood manufacturers in Shandong processing clusters with automated conditioning systems that reduce labor dependence and extend shelf stability for ingredient supply contracts. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated conditioning-holding facilities with direct-to-restaurant channel control and year-round availability guarantees. Long-term viability across the analysis window favors operators with captive supply of certified seed stock and embedded traceability systems that satisfy EU Green Deal documentation requirements. Monitor EFSA hygiene standard enforcement intensity as the inflection indicator for margin expansion in compliant versus non-compliant supply tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Depuration Technology Convergence | UV-C treatment integration with automated sorting robotics reduces Dutch facility labor costs and mortality rates. |
| Direct-to-Restaurant Channel Capture | East Coast US distributors bypass wholesale layers to capture premium pricing through chef relationship captivity. |
| Backward Integration into Seed Stock | Spanish producers relocate breeding operations northward along Galician coasts to secure climate-resilient supply. |
| Certification Infrastructure Investment | Twelve-to-eighteen month HACCP validation timelines create barriers against new EU export market entrants. |
| Geographic Diversification into India | Kerala and Tamil Nadu harbor export-oriented greenfield potential for underpenetrated bivalve processing capacity. |
Research Approach
A standing panel of aquaculture facility managers, seafood procurement directors at ready-to-eat manufacturers, EFSA regulatory compliance officers, and Dutch auction system operators provided ongoing calibration throughout the study period. Primary interview data combined with secondary validation from EU Common Fisheries Policy documentation, NOAA Fisheries harvest quota records, and French ANSM shellfish sanitation program filings. Bottom-up volume modeling across harvesting method and distribution channel segments was triangulated against top-down value estimates derived from trade flow analysis.
Scenario-bracketing around regulatory enforcement intensity, fuel price volatility bands, and climate-driven growing area displacement shaped the projection framework. Segmentation dimensions modeled include product type, distribution channel, end user application, and harvesting method across the analysis window. CAGRs were derived from fitted growth curves applied to volume and value trajectories, with aquaculture capacity expansion schedules and EFSA compliance timelines serving as key forecast inputs.
Stress conditions across diesel price spikes, EFSA hygiene standard enforcement delays, and warming water temperature displacement were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory stability and input cost trajectories. Material shifts in EU Green Deal sustainability mandate timing or NOAA quota rigidity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aquaculture Innovations
Aquaculture Additives Market
Aquaculture Innovations
GCC Fish Farming Market
Aquaculture Innovations
Ornamental Fish Market
Aquaculture Innovations
Oman Aquaculture Market
Aquaculture Innovations
Vietnam Aquaculture Market
Aquaculture Innovations
Aquaculture Pumps Market
Aquaculture Innovations
Global Aquaculture Vaccine Market
Aquaculture Innovations
Hatchery Product Market
Aquaculture Innovations
Europe Organic Aquaculture Market
Aquaculture Innovations
Global Precision Aquaculture Market
Aquaculture Innovations
Aquaculture Healthcare Market
Aquaculture Innovations
Aquaculture Therapeutics Market
Aquaculture Innovations
Fish Oil for Aquafeed Market
Aquaculture Innovations
Egypt Aquafeed Market
Aquaculture Innovations
Aquaculture Water Quality and Biomass Monitoring Test Equipment Market
Aquaculture Innovations
Microalgae-Based Aquafeed Market