
 Global Commercial Seaweeds Market | 2026-2036
Global Commercial Seaweeds Market Size, Share, and Industry Trends Forecast 2026-2036
Global Commercial Seaweeds Market Analysis
Buyer concentration in the food additive sector is pivoting toward multinational ingredient houses that negotiate long-term offtake agreements for carrageenan and alginate volumes. Cargill Inc. leverages its global commodity infrastructure to secure bulk supply contracts across Southeast Asian farming cooperatives. CP Kelco sustains technology leadership in refined hydrocolloid extraction, commanding premium positioning in stabilizer formulations for dairy and plant-based beverages. Acadian Seaplants Limited anchors North Atlantic supply through vertically controlled cultivation sites in Nova Scotia and Prince Edward Island.
Commercial seaweeds comprise macroalgae biomass harvested from marine or aquaculture systems, processed into functional hydrocolloids, whole foods, or bioactive extracts with defined gel strength, viscosity, and ash content specifications. Kappa carrageenan dominates value capture due to its irreplaceable functionality in dairy protein stabilization, while alginates command margin pools in pharmaceutical controlled-release and wound-dressing applications where pharmacopeial grades justify price premiums. The powder form category leads volume throughput for industrial compounders, though liquid extracts are gaining formulation share in precision agriculture foliar sprays and cosmetic serums where dosing accuracy reduces manufacturing waste.
EMA pharmacopeial standards govern alginate purity grades for wound care and drug delivery access in Europe, while China's SAMR enforces GB standards on heavy metal limits and food additive labeling for domestically processed seaweed derivatives. The EU Green Deal's carbon border adjustments and F-Gas Regulation refrigerant constraints are reshaping energy-intensive drying and extraction facility siting decisions across coastal processing zones. Stakeholders must monitor regulatory divergence between REACH-aligned hazard classifications and China's evolving MEE discharge permits for marine biomass processors, as compliance cost asymmetries will determine competitive access to premium formulation segments.
Market Dynamics
Consolidation among Asian hydrocolloid processors is compressing margins for European and North American traders, as state-backed aquaculture expansion in China feeds captive extraction capacity that bypasses traditional spot-market channels.
Growth Catalysts
- EU Green Deal carbon border adjustments:The EU's carbon border mechanism rewards low-carbon seaweed cultivation methods, creating preferential market access for sustainably harvested biomass entering European food and pharmaceutical formulation supply chains.
- Plant-based dairy stabilization demand:Formulators of oat, almond, and pea protein beverages require kappa carrageenan for texture and suspension, pulling volume through long-term offtake contracts with refined hydrocolloid suppliers.
- China's coastal processing clusters:State-directed aquaculture expansion along Fujian and Shandong coastlines secures raw material pipelines that reduce feedstock volatility for domestic alginate and carrageenan processors.
Market Restraints
- Wild harvest supply concentration:Premium gel-strength carrageenan depends on specific Gracilaria and Eucheuma species concentrated in Indonesian and Philippine farming cooperatives, exposing processors to climate-driven yield volatility.
- F-Gas Regulation refrigerant constraints:The EU's phasedown of hydrofluorocarbon refrigerants raises capital costs for energy-intensive spray-drying and extraction facilities sited in coastal processing zones.
- Cellulose gum substitution in beverages:CMC and microcrystalline cellulose displace alginate in certain neutral-pH beverage applications where cost sensitivity outweighs gel-strength requirements.
Strategic Opportunities
- Bioactive peptide extraction from red algae:Cosmetic and nutraceutical formulators seek collagen-boosting fucoidan and phlorotannin concentrates, opening premium revenue pools beyond commodity hydrocolloids.
- Controlled-release pharmaceutical alginates:EMA pharmacopeial-grade sodium alginate for tablet matrix and wound dressing applications commands price premiums that justify dedicated purification capacity.
- Precision agriculture foliar sprays:Liquid seaweed extracts with standardized cytokinin and auxin content replace synthetic biostimulants in organic farming systems across Brazil and Australia.
Industry Challenges
- Pharmacopeial certification timelines:EMA and USP-grade alginate qualification requires 18-24 month stability documentation and audit cycles that delay market entry for new extraction facilities.
- Specialized marine biochemistry expertise:Refineries lack sufficient process engineers trained in polysaccharide rheology and heavy metal chelation, constraining capacity expansion beyond current operational sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Commercial Seaweeds Market |
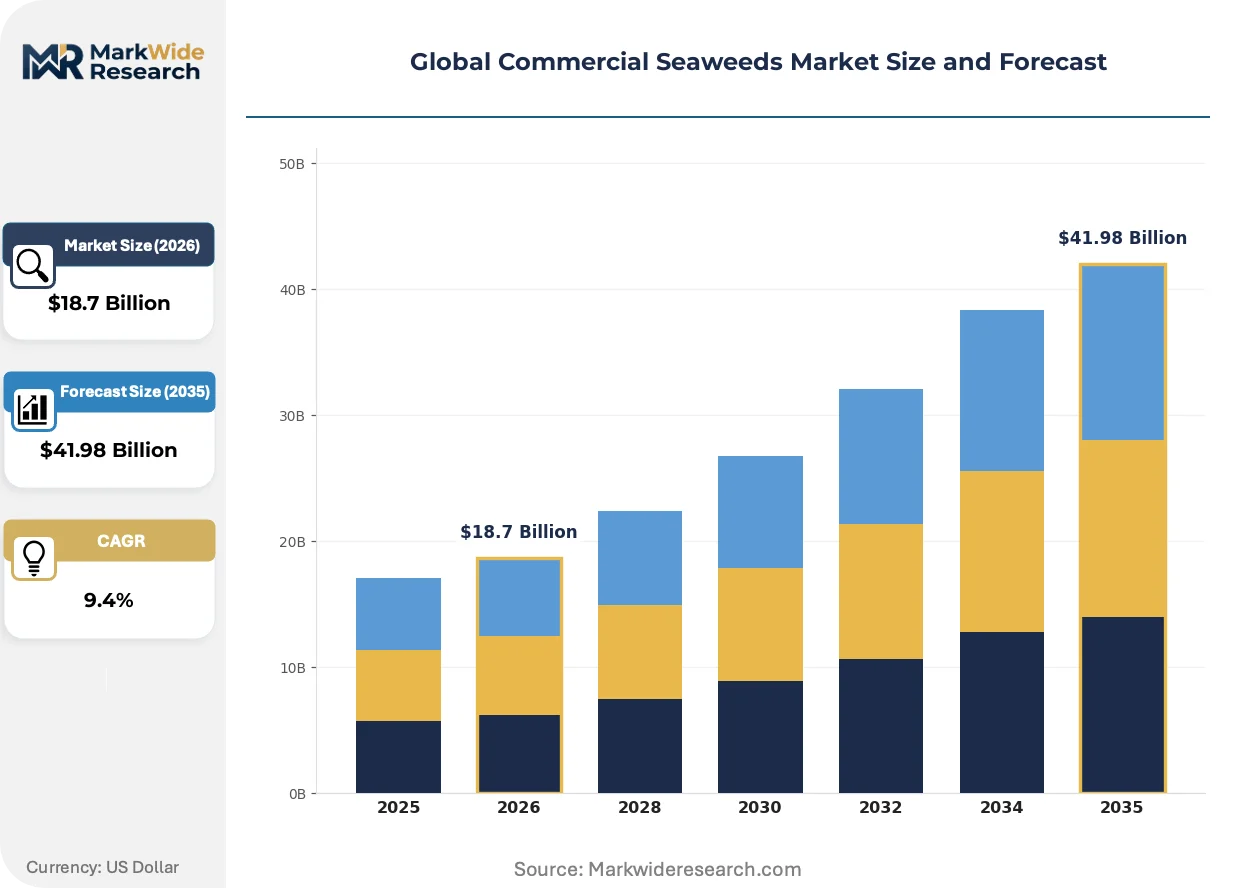
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Kappa Carrageenan, Agar, Alginates, Nori End User: Food Industry, Pharmaceutical, Cosmetics, Agriculture Form: Powder, Flakes, Sheets, Liquid Application: Food Additive, Thickener, Stabilizer, Fertilizer |
| Companies Covered | Cargill Inc., CP Kelco, Acadian Seaplants Limited, DuPont de Nemours and Company, Roullier Group, Gelymar SA, Seasol International Pty Ltd, Biostadt India Limited, Qingdao Seawin Biotech Group Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Commercial Seaweeds Market Emerging Trajectories
Enzymatic extraction methods and precision fermentation of seaweed-derived metabolites are compressing traditional solvent-based processing, while regulatory carbon accounting and buyer consolidation reshape competitive positioning.
Membrane filtration and enzyme-assisted extraction is consolidating refined hydrocolloid production around integrated processors with captive fermentation capacity. Dairy and plant-based beverage formulators now specify gel strength and viscosity tolerances in procurement contracts that exclude spot-market traders. This technology compression favors capital-intensive facilities with in-house R&D over toll-processing arrangements.
REACH-aligned hazard classifications and China's evolving MEE discharge permits for marine biomass processors are diverging compliance cost structures across coastal extraction zones. European facilities face stricter effluent monitoring and refrigerant phaseout schedules under the F-Gas Regulation. Pharmaceutical-grade alginate suppliers are responding by dual-siting purification capacity across regulatory jurisdictions to maintain EMA and NMPA market access.
Ingredient houses now negotiate multi-year offtake agreements directly with farming cooperatives, disintermediating regional traders who historically managed spot-price arbitrage. This channel compression is most visible in Southeast Asian carrageenan supply chains, where Cargill and CP Kelco structure volume commitments with Indonesian Eucheuma cultivators that lock in preferential raw material access for refined product lines.
Global Commercial Seaweeds Market Segmentation
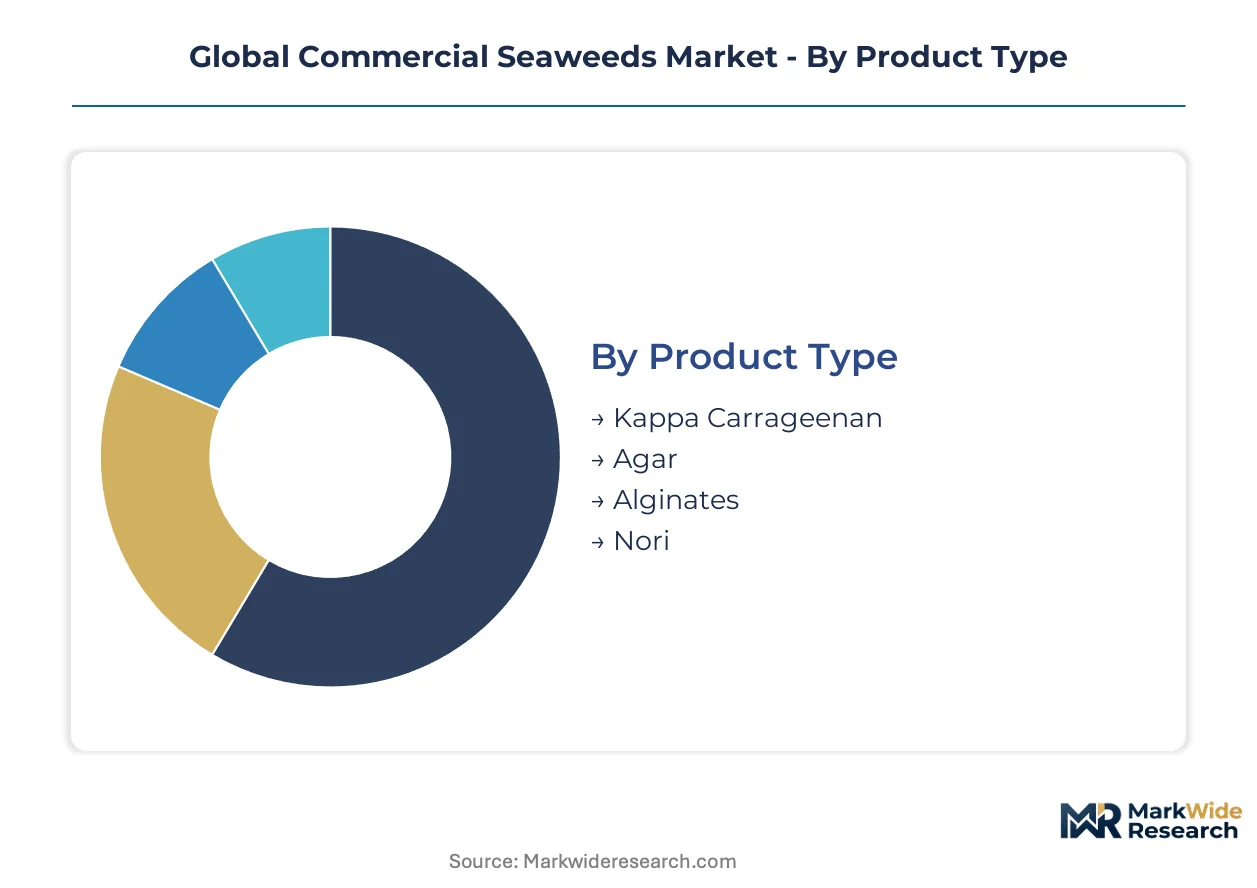
Seaweed derivatives command divergent pricing and certification requirements based on functional purity and end-use specifications. Procurement contracts now specify gel strength, viscosity, and heavy metal thresholds that segment supply chains into pharmaceutical-grade, food-grade, and agricultural-grade channels. This stratification determines which processors can access premium formulation markets versus commodity hydrocolloid volumes.
Product Type:
Customization intensity varies sharply across this category, from standardized commodity hydrocolloids to pharmacopeial-grade alginates requiring dedicated purification lines.
- Kappa Carrageenan:Extracted from Eucheuma and Kappaphycus species, this sulfated polysaccharide delivers irreproducible dairy protein stabilization at low concentrations. Dairy and plant-based beverage formulators in Indonesia and the Philippines specify gel strength tolerances in multi-year offtake agreements that bypass spot markets. Demand concentrates where farming cooperatives can guarantee consistent KCl reactivity for protein suspension applications.
- Alginates:Sodium and calcium salts from brown algae (Laminaria, Macrocystis) form thermo-irreversible gels critical to pharmaceutical controlled-release matrices and wound dressings. EMA pharmacopeial standards govern European market access, while China's NMPA enforces parallel purity requirements that dual-sited processors must satisfy. The 18-24 month certification timelines create barriers that justify dedicated capacity for premium grades.
- Agar:Gelose polysaccharide from Gelidium and Gracilaria species serves microbiological culture media and confectionery applications where clarity and low gelling temperatures matter.
- Nori:Dried Porphyra sheets dominate whole-food consumption in East Asian markets, with cultivation concentrated in China's Fujian and Jiangsu coastal zones.
Most installed capacity flows through Kappa Carrageenan. Expansion is steepest in Alginates.
End User:
Volume concentration versus margin capture defines the cost tier structure across this category, with pharmaceutical buyers paying pharmacopeial premiums and agricultural users driving commodity throughput.
- Food Industry:Hydrocolloid processors supply carrageenan and alginate to dairy, confectionery, and plant-based protein formulators who specify gel strength, viscosity, and ash content in procurement contracts. China's SAMR enforces GB standards on heavy metal limits and additive labeling that domestic processors must document for market access.
- Pharmaceutical:Sodium alginate for tablet matrix systems and wound dressings commands price premiums contingent on EMA, USP, or NMPA pharmacopeial certification. The qualification burden favors established suppliers with existing audit relationships and stability documentation libraries.
- Cosmetics:Bioactive peptide extracts—fucoidan from brown algae, phlorotannin from red algae—target collagen-boosting claims in premium skincare formulations.
- Agriculture:Liquid seaweed extracts with standardized cytokinin and auxin content replace synthetic biostimulants in organic farming systems across Brazil and Australia, where foliar spray dosing accuracy reduces manufacturing waste.
Food Industry absorbs the largest volume share. Pharmaceutical generates the highest unit margins.
Form:
Customer type determines form selection, with industrial compounders preferring bulk powder throughput and precision agriculture users requiring liquid dosing flexibility.
- Powder:Spray-dried hydrocolloids dominate industrial compounder procurement for food additive and thickener applications where bulk handling efficiency outweighs reconstitution time. The EU F-Gas Regulation's hydrofluorocarbon phasedown raises capital costs for energy-intensive drying facilities in European coastal zones.
- Liquid:Standardized extracts enable precise dosing in precision agriculture foliar sprays and cosmetic serums where manufacturing waste reduction justifies per-unit premiums. Formulators in Australia's organic farming cooperatives specify auxin and cytokinin content tolerances that liquid processing can deliver.
- Flakes:Intermediate moisture format suits regional traders managing spot-price arbitrage in Southeast Asian supply chains.
- Sheets:Dried nori and other whole-algae products serve direct consumption and culinary applications in East Asian markets.
Powder commands the greatest installed drying capacity. Liquid is gaining share fastest in precision agriculture channels.
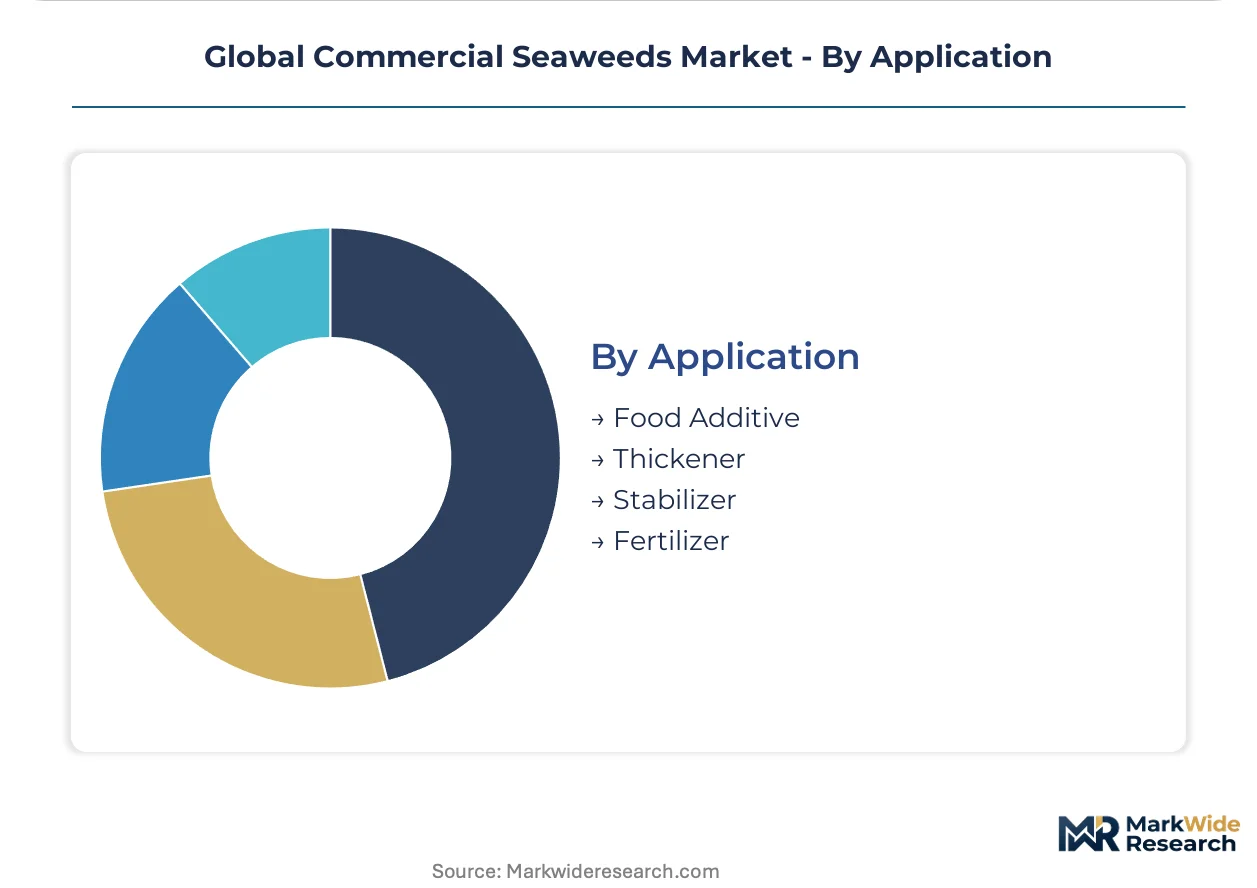
Application:
Supply concentration shapes application access, with stabilizer and thickener specifications controlled by multinational ingredient houses while fertilizer applications fragment across regional biostimulant blenders.
- Stabilizer:Kappa carrageenan stabilizes dairy and plant-based proteins against phase separation in oat, almond, and pea protein beverages. Cargill and CP Kelco structure long-term offtake agreements with Indonesian Eucheuma cultivators that lock in preferential raw material access for refined stabilizer lines.
- Food Additive:Alginate and carrageenan serve gelling, thickening, and suspending functions across processed food categories where SAMR and FDA labeling requirements govern market access. China's coastal processing clusters in Fujian and Shandong feed captive extraction capacity that reduces feedstock volatility for domestic additive processors.
- Thickener:Viscosity modification in sauces, dressings, and bakery applications where cost sensitivity drives competition with cellulose gum alternatives.
- Fertilizer:Seaweed-derived biostimulants replace synthetic inputs in organic farming systems, with liquid extracts standardized for phytohormone content.
Stabilizer applications anchor the largest contract volumes. Food Additive is climbing the fastest as plant-based protein expansion accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's state-directed aquaculture expansion contrasts sharply with Indonesia's climate-exposed farming cooperatives, revealing how governance models reshape raw material security for hydrocolloid processors worldwide.
China
Fujian and Shandong coastal clusters feed captive carrageenan and alginate extraction capacity through SAMR-enforced GB standards on heavy metal limits. State-backed aquaculture expansion along these coastlines secures raw material pipelines that reduce feedstock volatility for domestic processors serving food additive and pharmaceutical formulation markets.
Indonesia
Eucheuma and Gracilaria farming cooperatives in Sulawesi and Nusa Tenggara supply premium gel-strength carrageenan to multinational ingredient houses. The country's national food and drug regulator enforces additive labeling requirements that align with export market access protocols for dairy stabilization applications.
United States
FDA-regulated food additive specifications drive procurement contracts for refined hydrocolloids in plant-based protein beverages. California and Maine coastal processing facilities face EPA effluent monitoring requirements that influence extraction technology selection and capacity siting decisions.
Norway
Laminaria harvesting from Arctic waters supplies pharmaceutical-grade alginate precursors under EMA pharmacopeial standards. Tromsø and Trondheim processing clusters leverage EU Green Deal carbon border adjustments to secure preferential market access for low-carbon marine biomass derivatives.
Brazil
Organic farming cooperatives in São Paulo and Minas Gerais states specify standardized cytokinin and auxin content in liquid seaweed extract procurement for precision agriculture foliar sprays. The national agricultural regulator enforces biostimulant registration requirements that favor suppliers with documented phytohormone standardization protocols.
Global Commercial Seaweeds Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered supply channels where scale advantages clash with customization capabilities. Multinational ingredient houses leverage global commodity infrastructure to secure bulk supply contracts, while regional processors defend niche positions through pharmacopeial certification and captive cultivation sites. Three archetypes dominate: integrated conglomerates with cross-sector resource allocation, hydrocolloid specialists with refined extraction technology, and coastal cultivators with vertically controlled biomass supply. Competitive intensity manifests through long-term offtake agreement structures and dual-sited purification capacity investments that straddle regulatory jurisdictions.
Among North Atlantic cultivators, Acadian Seaplants Limited exemplifies the vertically controlled biomass archetype through Nova Scotia and Prince Edward Island production sites. Cargill Inc. and CP Kelco occupy positions at the scale-driven end of the ingredient house spectrum, representing how multinational commodity infrastructure reshapes procurement channel structures across Southeast Asian farming cooperatives. These three anchors illustrate the competitive tension between geographic concentration and global distribution reach.
| Leading Market Players |
|---|
| Cargill Inc. |
| CP Kelco |
| Acadian Seaplants Limited |
| DuPont de Nemours and Company |
| Roullier Group |
| Gelymar SA |
| Seasol International Pty Ltd |
| Biostadt India Limited |
| Qingdao Seawin Biotech Group Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements for kappa carrageenan from Indonesian Eucheuma farming cooperatives are compressing spot-market arbitrage margins and forcing European traders to absorb higher feedstock costs or exit refined hydrocolloid channels entirely. This procurement consolidation is reshaping price discovery mechanisms across Southeast Asian supply chains.
Pricing Analysis
Capacity additions in China's Fujian and Shandong coastal clusters are reshaping price floors for food-grade carrageenan and alginate derivatives. Three-tier pricing structure across pharmaceutical-grade, food-grade, and agricultural-grade certification levels captures margin pools tied to EMA pharmacopeial standards and SAMR-enforced heavy metal thresholds. Cost compression in commodity hydrocolloids is intensifying because state-backed aquaculture expansion feeds captive extraction capacity that bypasses traditional trading channels. Agricultural-grade liquid extracts exhibit highest price sensitivity due to substitution risk from synthetic biostimulants, while pharmaceutical-grade alginates maintain pricing power through 18-24 month certification barriers.
Supply Chain Analysis
Dual-sourcing requirements from multinational ingredient houses now mandate multi-supplier qualification across Indonesian, Philippine, and Chinese farming cooperatives to secure premium gel-strength carrageenan volumes. Raw material pipelines draw from Eucheuma and Gracilaria seaweed biomass, potassium chloride for gel activation, and pharmaceutical-grade solvents for alginate purification. Single-source vulnerability concentrates in Sulawesi and Nusa Tenggara climate-exposed cultivation zones where typhoon-driven yield volatility disrupts contract fulfillment. Distribution runs through vertically integrated processors with captive fermentation capacity rather than regional toll-processing arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in pharmaceutical-grade alginate purification and bioactive peptide extraction, where EMA pharmacopeial certification and cosmetic collagen-boosting claims justify dedicated capacity investments.
For Market Incumbents: Acquire captive cultivation sites in Nova Scotia or Prince Edward Island to secure North Atlantic Laminaria biomass pipelines against Indonesian climate volatility. Defend market position by accelerating enzymatic extraction technology deployment ahead of F-Gas Regulation refrigerant constraints that will strand conventional solvent-based capacity. Lock in multi-year offtake agreements with Brazilian organic farming cooperatives before regional biostimulant blenders consolidate precision agriculture channels. For New Entrants and Emerging Players: EU Green Deal carbon border adjustments in Europe open a window for low-carbon seaweed cultivation methods to capture preferential market access in dairy and plant-based beverage stabilization. Target precision agriculture foliar sprays in Australia's organic farming systems where standardized cytokinin and auxin content specifications remain undersupplied by incumbent liquid extract processors. Pursue toll-processing partnerships with established pharmacopeial-grade facilities to bypass 18-24 month certification timelines while building proprietary purification expertise. For Investors and Strategic Acquirers: Asymmetric upside sits with coastal cultivators with vertically controlled biomass supply and existing EMA audit relationships. Long-term viability over the projection horizon hinges on dual-sited purification capacity that maintains simultaneous European and Chinese regulatory access. Watch for inflection signals in MEE discharge permit enforcement that would raise compliance cost asymmetries between REACH-aligned European facilities and Chinese coastal processors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation | Secures raw material pipelines against climate-driven yield volatility in Indonesian farming cooperatives. |
| Pharmacopeial Certification Investment | Unlocks EMA-governed wound dressing and tablet matrix markets with 18-24 month qualification barriers. |
| Enzymatic Extraction Technology Deployment | Compresses energy-intensive solvent processing ahead of F-Gas Regulation refrigerant phasedown deadlines. |
| Dual-Sited Purification Capacity | Maintains simultaneous European and NMPA market access amid diverging REACH and MEE compliance regimes. |
| Long-Term Offtake Agreement Structuring | Locks in preferential Indonesian Eucheuma biomass access for refined stabilizer product lines. |
Methodological Framework
Coverage spans North Atlantic, Southeast Asian, and South American cultivation zones, with primary inputs from each region's processing clusters. The analysis combines structured interviews with hydrocolloid extraction plant managers, procurement leads at multinational ingredient houses, regulatory affairs specialists navigating EMA and SAMR frameworks, and distribution channel partners managing spot-market arbitrage. Secondary validation draws from customs and trade data on seaweed derivative flows, SEC filings from diversified conglomerates with marine biomass segments, and EMA pharmacopeial submission databases. Bottom-up volume modeling and top-down value triangulation reconcile farmer cooperative output estimates with processor capacity utilization rates.
Rate-of-change decomposition separates volume drivers from price realization factors across the analysis window. Segmentation dimensions include hydrocolloid product type, end-use industry vertical, pharmacopeial certification tier, and regional regulatory cluster alignment. CAGRs derive from fitted growth curves applied to disclosed capacity expansion timelines and offtake contract renewal patterns. Industry-specific forecast inputs incorporate F-Gas Regulation implementation schedules and China's dual carbon goals affecting coastal processing energy costs.
Revisions become necessary when EMA pharmacopeial standard updates, MEE discharge permit enforcement intensification, or cellulose gum substitution acceleration in neutral-pH beverages materialize beyond baseline assumptions. Deviation in Indonesian climate patterns or Chinese state-backed aquaculture subsidy levels would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
India Compound Feed Market
Agriculture and Agri Products
Greenhouse Horticulture Market
Agriculture and Agri Products
E-Commerce of Agricultural Products Market
Agriculture and Agri Products
Aquatic Feed Ingredients and Products Market
Agriculture and Agri Products
Live Goods Market
Agriculture and Agri Products
Asia-Pacific Compound Feed Market
Agriculture and Agri Products
Henequen Market
Agriculture and Agri Products
Asia-Pacific Poultry Meat Market
Agriculture and Agri Products
Tarragon Market
Agriculture and Agri Products
Global Quail Eggs Market
Agriculture and Agri Products
Poultry Fat Market
Agriculture and Agri Products
Cassava Starch Market
Agriculture and Agri Products
Malaysia Floriculture Market
Agriculture and Agri Products
Kenya Floriculture Market
Agriculture and Agri Products
Australia Floriculture Market
Agriculture and Agri Products
Africa Animal Protein Market