
 Fish Oil for Aquafeed Market | 2026-2036
Fish Oil for Aquafeed Market Size, Share, and Industry Trends Forecast 2026-2036
Fish Oil for Aquafeed Market Insights
Premium-grade omega-3 concentration tiers is unwinding a measurable shift in procurement standards across aquaculture feed systems. Darling Ingredients Inc. leverages integrated rendering operations to secure consistent raw material flows for aquafeed oil production. Omega Protein Corporation anchors its position through marine ingredient harvesting along the Gulf of Mexico and Atlantic coastlines. Pelagia AS competes via specialized pelagic fish processing infrastructure serving Nordic salmon feed manufacturers.
Fish oil for aquafeed denotes refined lipid extracts derived from pelagic species such as anchovy, menhaden, and sand eel, typically containing 18-33% eicosapentaenoic acid and docosahexaenoic acid by weight, produced through wet rendering or cold-extraction methods to preserve polyunsaturated fatty acid profiles for essential dietary supplementation in farmed species. Concentrated oils command the dominant margin pool within product type segmentation due to their higher EPA/DHA payload per unit volume and compatibility with high-performance salmon diets. Salmon farming leads application segmentation in value terms, while shrimp farming represents the fastest-expanding demand category driven by intensification in Southeast Asian production zones.
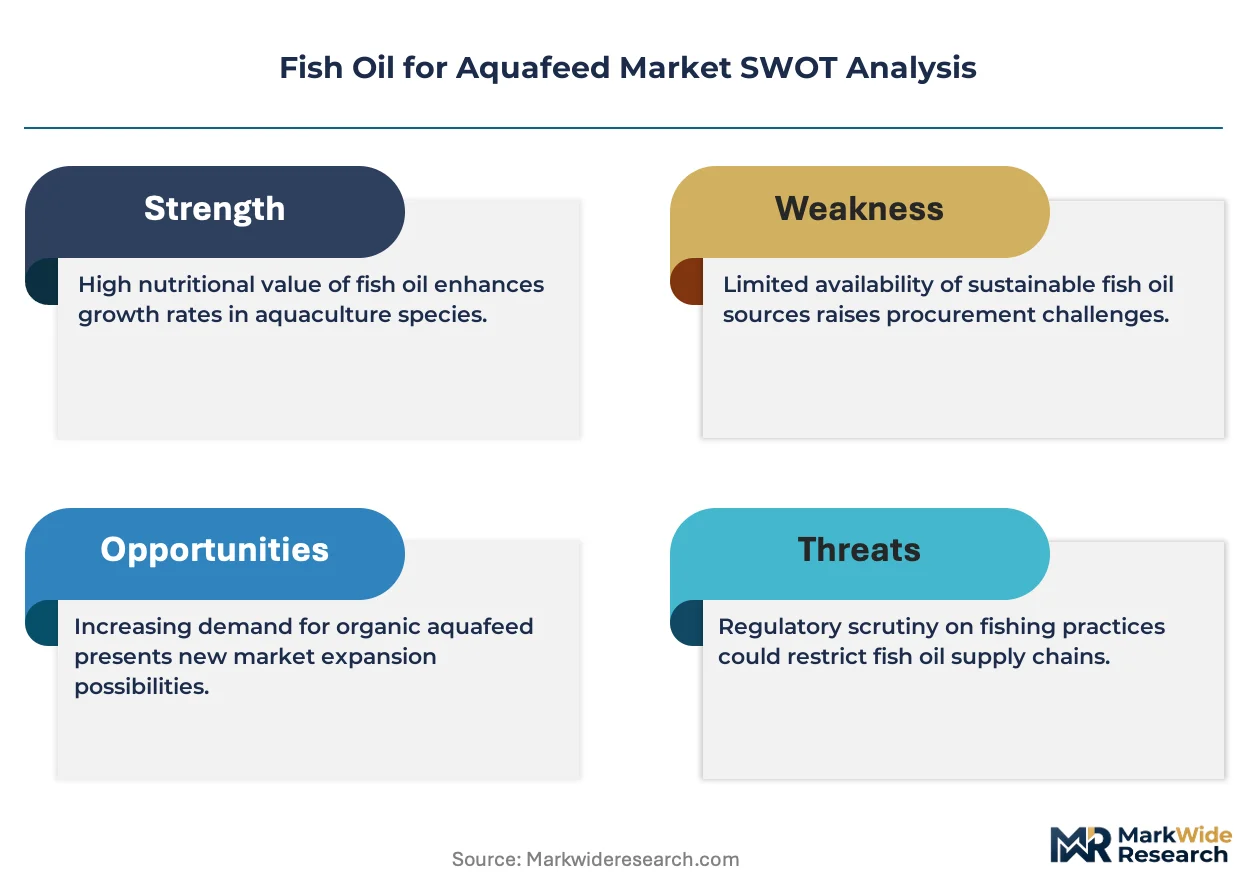
EU REACH and F-Gas Regulation frameworks govern chemical handling and environmental discharge standards at fish oil processing facilities across European coastal operations. The U.S. FDA and NOAA Fisheries jointly administer inspection protocols for marine ingredient imports entering American aquafeed supply chains. Peruvian production authority PRODUCE and Chile's SUBPESCA enforce seasonal catch quotas that directly constrain raw material availability for international oil refiners. Stakeholders must monitor how marine stewardship certification schemes evolve their criteria for forage fish sourcing to anticipate eligibility shifts for major retail supply contracts.
Market Dynamics
Marine stewardship certification schemes are tightening eligibility criteria for forage fish sourcing, forcing feed manufacturers to requalify supply chains or lose access to major retail contracts in European and North American salmon markets.
Growth Catalysts
- EU Feed Hygiene Regulation:Mandatory traceability standards for marine ingredients are upgrading procurement protocols across Nordic salmon feed operations, creating compliant supplier premiums.
- Shrimp intensification:Southeast Asian aquaculture zones are expanding formulated feed penetration in previously extensive farming systems, opening new volume channels for EPA/DHA concentrates.
- Wet rendering advancement:Cold-extraction methods preserving polyunsaturated fatty acid profiles are enabling premium-grade oil differentiation against heat-degraded alternatives.
Market Restraints
- Anchovy supply concentration:Peruvian and Chilean catch quotas administered by PRODUCE and SUBPESCA constrain raw material flows to international refiners during El Niño events.
- Algal oil substitution:Fermentation-derived omega-3 alternatives are capturing share in high-margin pharmaceutical and premium pet food applications outside aquaculture.
- REACH compliance costs:ECHA chemical handling and environmental discharge standards impose capital burdens on European coastal processing facilities.
Strategic Opportunities
- Indian aquaculture expansion:Shrimp and freshwater species farming in Andhra Pradesh and Gujarat remains underpenetrated by formulated feeds, offering first-mover positioning for certified oil suppliers.
- Integrated rendering networks:Backward integration into byproduct capture from food-grade fish processing is securing captive raw material streams independent of volatile pelagic fisheries.
- Retailer certification mandates:ASC and BAP standards evolution is creating eligibility barriers that favor pre-qualified oil suppliers with documented chain-of-custody systems.
Industry Challenges
- Marine chemist scarcity:Specialized expertise in polyunsaturated fatty acid preservation and oxidation control remains concentrated among legacy Nordic and Japanese technical centers.
- Multi-certification stacking:Simultaneous compliance with ASC, BAP, and national organic standards requires redundant audit trails and documentation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fish Oil for Aquafeed Market |
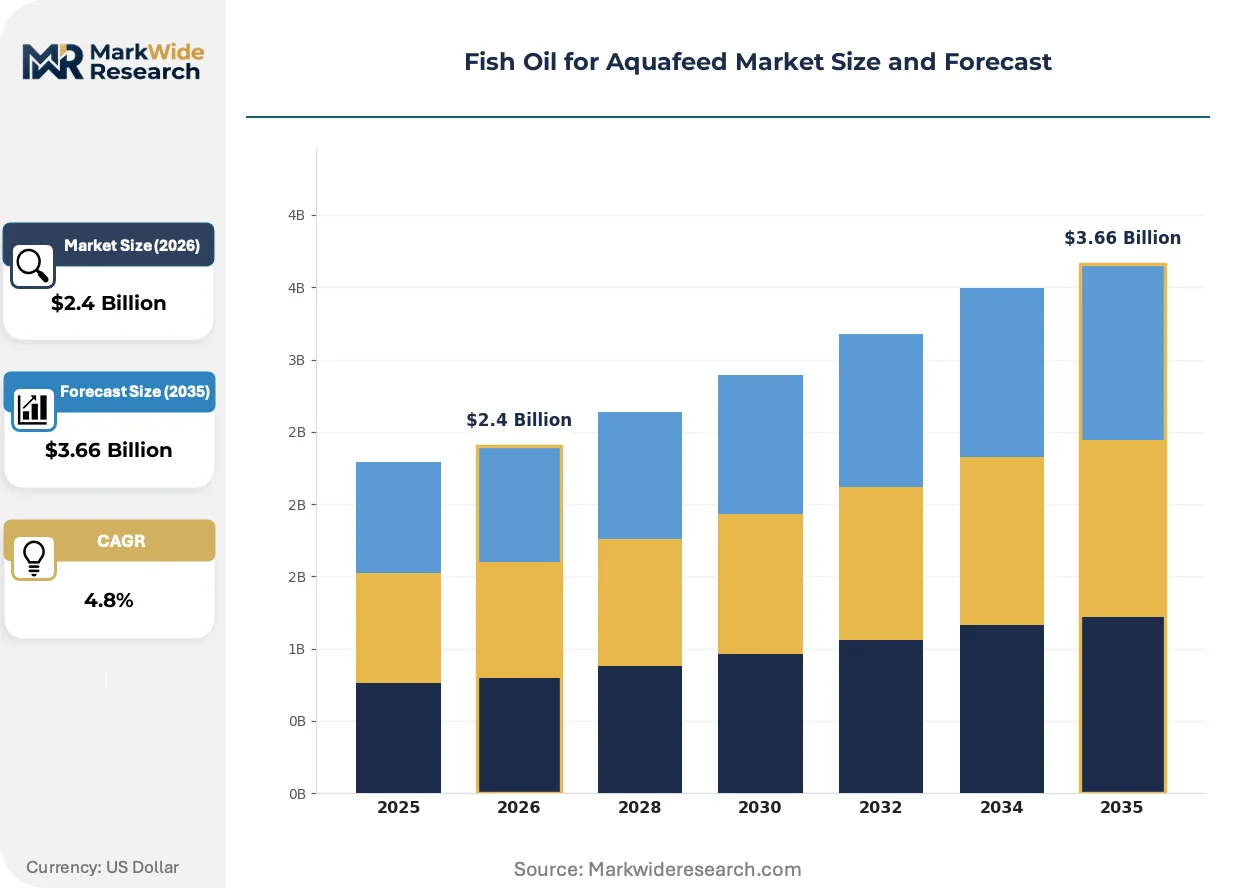
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.66 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrated Oils, Emulsified Oils, Omega-3 Supplements, Fish Meal Application: Salmon Farming, Shrimp Farming, Tilapia Farming, Marine Fish Farming End User: Aquaculture Farms, Feed Manufacturers, Research Institutions, Nutritionists Distribution Channel: Online Sales, Retail Stores, Direct Sales, Distributors |
| Companies Covered | Darling Ingredients Inc., The Lauridsen Group Inc., SARIA Group, Sera Scandia, Lican Food, Puretein Agri LLC., Veos Group, Pelagia AS, Omega Protein Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fish Oil for Aquafeed Market Trends and Innovations
Processing technology and sourcing protocols are diverging between premium salmon feed tiers and cost-optimized shrimp formulations, creating parallel innovation tracks within the same ingredient category.
Enzymatic refining protocols are displacing traditional wet rendering in high-value salmon oil production. Norwegian and Chilean salmon feed manufacturers are adopting these systems to achieve EPA/DHA retention rates above 95%. This technology is displacing heat-based extraction infrastructure and compressing margin structures for conventional refiners unable to upgrade.
EU F-Gas Regulation frameworks are phasing down hydrofluorocarbon use in refrigeration systems at fish oil processing plants. Coastal facilities in Denmark and Norway face retrofit timelines to maintain operating licenses. Cold-chain dependent processors are responding by consolidating operations at fewer, larger sites with upgraded cooling infrastructure.
Direct contracting between salmon farming groups and marine ingredient harvesters is shortening traditional trading house intermediation. Norwegian integrators are negotiating multi-year offtake agreements with Peruvian anchovy fleet cooperatives. This pattern is most visible in the North Atlantic salmon belt where vertical coordination secures volume certainty against quota volatility.
Fish Oil for Aquafeed Market Segmentation
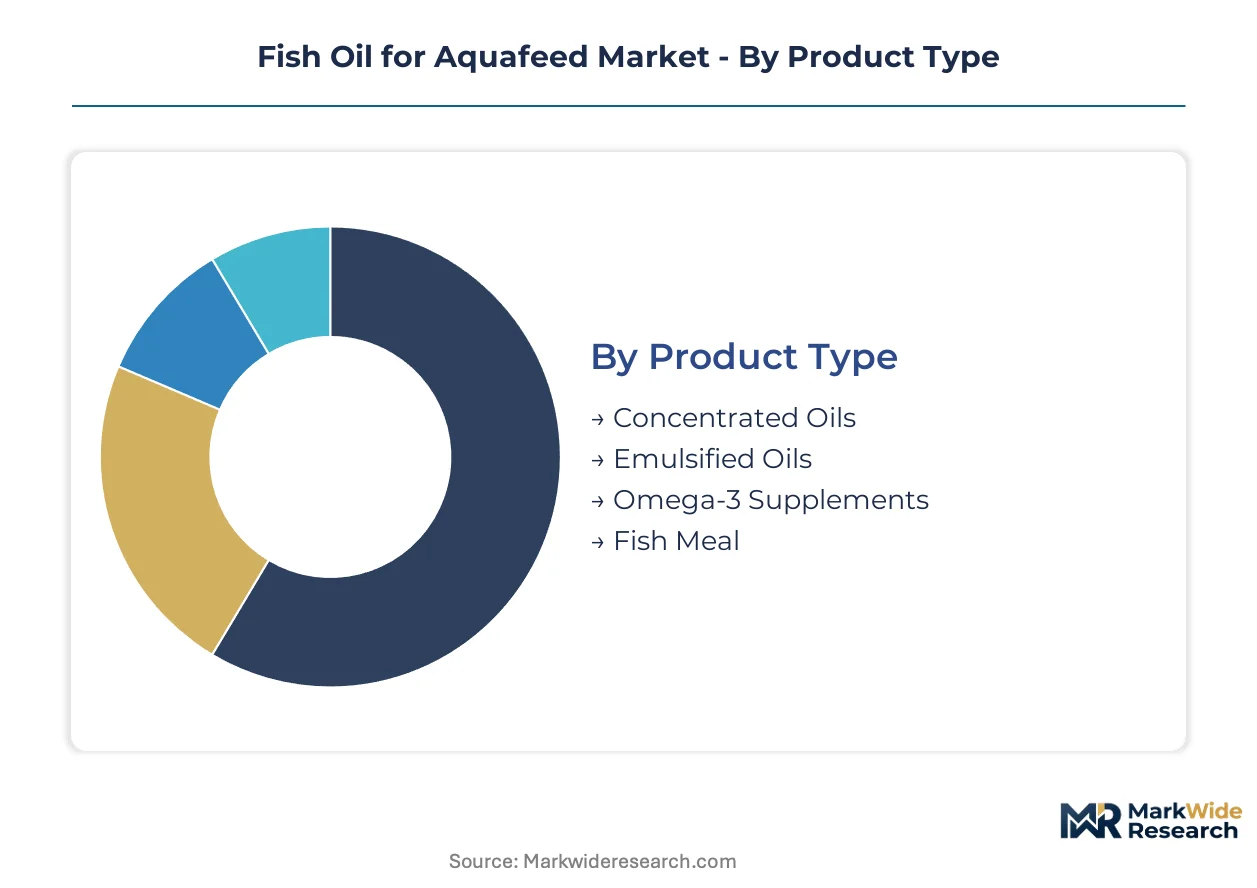
Segmentation in fish oil for aquafeed reveals divergent value capture between premium salmon feed formulations and cost-optimized shrimp diets. Procurement patterns split between direct contracting by integrated salmon groups and distributor-mediated sales serving fragmented shrimp farming operations across Southeast Asia.
Product Type:
Concentrated oils dominate export-led supply chains serving Norwegian and Chilean salmon integrators, while emulsified variants find stronger domestic uptake in regional Asian feed mills.
- Concentrated Oils:Refined extracts with 30-60% EPA/DHA concentration by weight, produced through molecular distillation or enzymatic processing. Norwegian salmon feed manufacturers specify these grades for fillet quality certification under ASC and BAP retailer mandates. Cold-extraction infrastructure investments in Peru and Chile secure raw material flows against El Niño quota disruptions.
- Emulsified Oils:Water-dispersible lipid formulations enabling uniform feed pellet coating and improved digestibility in warm-water species. Demand concentrates in Vietnamese and Thai shrimp feed mills where lower-cost emulsification meets intensive pond production economics. Processing flexibility allows regional refiners to substitute varying raw material qualities.
- Omega-3 Supplements:Blended additives targeting specific fatty acid ratios for broodstock and larval nutrition programs in hatchery operations.
- Fish Meal:Protein-rich coproduct from rendering operations, co-processed with oil extraction in integrated Peruvian and Chilean facilities.
Concentrated oils command the established base. The steepest expansion runs through emulsified oils.
Application:
Cost tier differentiation separates premium salmon diets with mandatory omega-3 minimums from volume-driven shrimp formulations where EPA/DHA serves as a growth promoter rather than fillet quality determinant.
- Salmon Farming:Atlantic and Pacific salmon operations in Norway, Chile, and Scotland specify high-omega-3 feed formulations to meet retailer certification requirements and achieve premium fillet grading. EU Feed Hygiene Regulation traceability mandates drive compliant supplier consolidation.
- Shrimp Farming:Pacific whiteleg shrimp intensification across Vietnam, Indonesia, and India expands formulated feed penetration from extensive to semi-intensive systems. EPA/DHA supplementation improves molt survival and growth rates in high-density pond culture.
- Tilapia Farming:Nile tilapia producers in China and Egypt utilize lower-inclusion fish oil rates, with vegetable oil partial substitution limiting omega-3 premium capture.
- Marine Fish Farming:European seabass and gilthead bream operations in Greece and Turkey adopt salmon-grade formulations for flesh quality differentiation in Mediterranean markets.
Salmon farming anchors revenue concentration. Shrimp farming gains share fastest.
End User:
Customer type fragmentation creates parallel supply channels: direct technical sales to integrated aquaculture groups versus specification selling through feed manufacturer procurement offices.
- Aquaculture Farms:Large-scale salmon integrators in Norway and Chile negotiate multi-year offtake agreements directly with Peruvian anchovy cooperatives, bypassing traditional trading houses. Volume certainty secures against seasonal quota volatility.
- Feed Manufacturers:Compound feed mills in Vietnam, Thailand, and Indonesia source through regional distributors with technical support for formulation optimization. Procurement teams balance cost targets against certification eligibility requirements.
- Research Institutions:Universities and government aquaculture centers in Japan and Norway conduct trials on alternative omega-3 sources and fatty acid retention in farmed species.
- Nutritionists:Independent feed formulators serving specialized marine fish hatcheries specify precise EPA/DHA ratios for larval development protocols.
Feed manufacturers represent the volume foundation. Aquaculture farms drive margin expansion through direct contracting.
Distribution Channel:
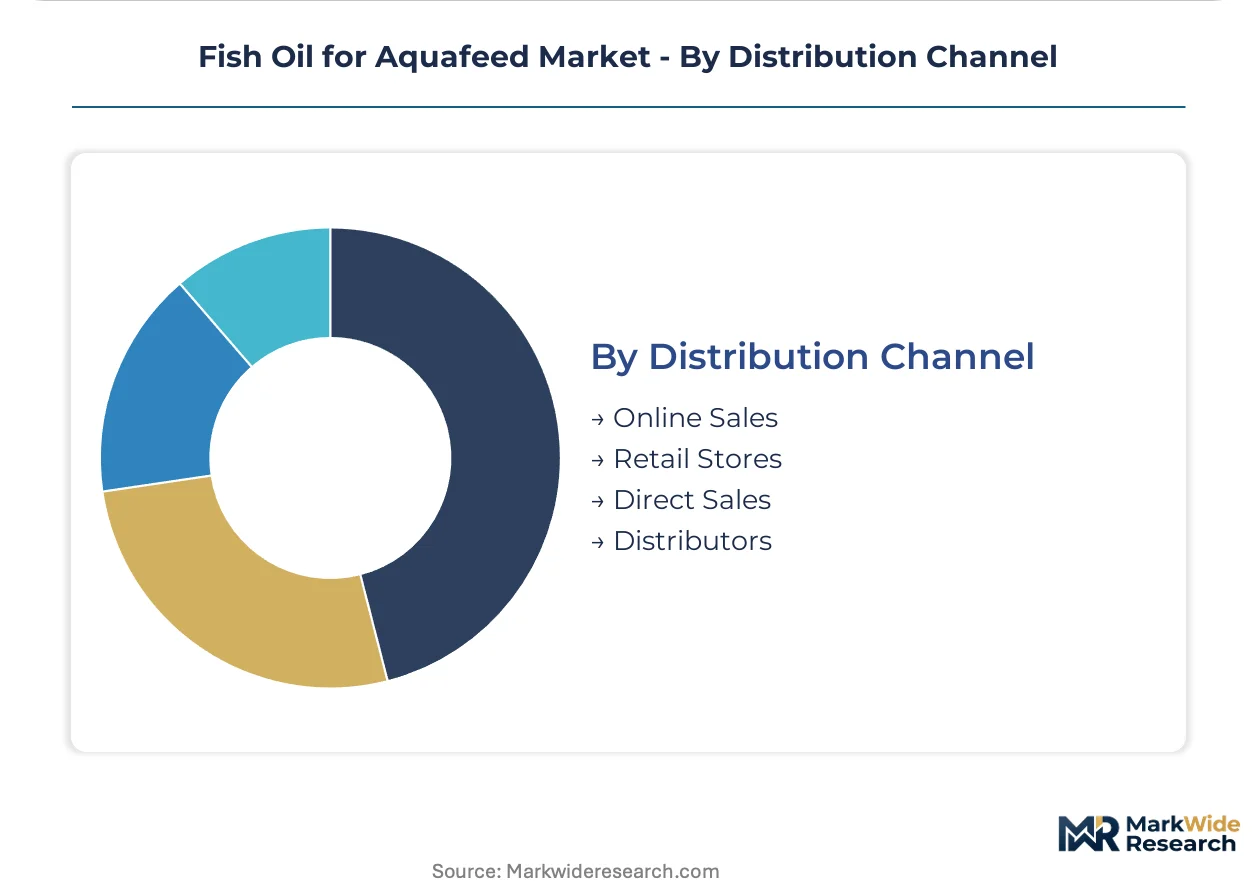
Supply concentration in marine ingredient harvesting geography shapes channel selection, with Peruvian and Chilean origins favoring direct sales while Southeast Asian demand relies on distributor networks.
- Direct Sales:Norwegian and Chilean salmon groups contract directly with Omega Protein and Pelagia AS for marine ingredient supply, securing chain-of-custody documentation for certification compliance. Multi-year agreements lock in volume against quota uncertainty.
- Distributors:Regional trading houses in Bangkok, Ho Chi Minh City, and Jakarta aggregate demand from fragmented shrimp feed mills, providing inventory financing and technical service. Margin compression from intermediary layering limits price transparency.
- Online Sales:Specialty omega-3 supplements for hatchery and research applications move through B2B platforms serving smaller-volume institutional buyers.
- Retail Stores:Limited presence for aquafeed-grade products, confined to regional agricultural supply cooperatives in coastal farming communities.
Distributors handle the established volume base. Direct sales channels expand most quickly among integrated salmon operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Peruvian anchovy exports supply Norwegian salmon integrators through direct multi-year contracting, while Chilean catches feed both domestic aquaculture and Asian shrimp feed mills via trading house intermediation.
Norway
Atlantic salmon farming operations in Nordland and Troms counties drive premium-grade omega-3 procurement for ASC-certified fillet production. The Norwegian Food Safety Authority enforces strict marine ingredient traceability under EU Feed Hygiene Regulation alignment. Bergen hosts Pelagia AS processing infrastructure serving integrated feed manufacturers.
Chile
Los Lagos and Aysén regions expand salmon smolt stocking programs requiring EPA/DHA concentrates for flesh quality grading. SUBPESCA administers seasonal anchovy quotas constraining raw material flows to Puerto Montt refiners. Direct contracting between salmon groups and Peruvian fleet cooperatives shortens traditional trading channels.
Peru
Chimbote and Paita anchovy landing sites supply international oil refiners through PRODUCE-regulated catch quotas. El Niño events trigger supply volatility that Norwegian integrators hedge via forward agreements. Coastal wet-rendering facilities preserve polyunsaturated fatty acid profiles for salmon feed certification compliance.
Vietnam
Mekong Delta shrimp intensification expands formulated feed penetration from extensive to semi-intensive pond systems. The Ministry of Agriculture and Rural Development promotes aquaculture modernization through technical standards adoption. Ho Chi Minh City distributors aggregate fragmented demand from regional feed mills.
India
Andhra Pradesh and Gujarat shrimp farming remains underpenetrated by certified fish oil suppliers despite rapid production growth. The Marine Products Export Development Authority regulates seafood quality standards for EU market access. Visakhapatnam processing clusters attract first-mover positioning from international ingredient suppliers.
Fish Oil for Aquafeed Market Competitive Landscape
Listed leaders compete with private specialists across supply chain integration depth, creating a tiered structure where public companies leverage capital markets for capacity expansion while family-held operators optimize niche harvesting relationships. Three archetypes dominate: integrated renderers with captive byproduct streams, marine ingredient harvesters controlling pelagic fisheries access, and regional processors serving single-species feed markets. Consolidation pressure runs through backward integration moves and multi-year offtake contracting.
Among North American integrated renderers, Darling Ingredients Inc. and Omega Protein Corporation occupy positions exemplifying scale-driven supply security. Pelagia AS represents the Nordic marine processing specialist archetype with concentrated pelagic infrastructure. These three anchors illustrate how geographic proximity to either salmon farming clusters or forage fish harvesting grounds shapes competitive positioning.
| Leading Market Players |
|---|
| Darling Ingredients Inc. |
| The Lauridsen Group Inc. |
| SARIA Group |
| Sera Scandia |
| Lican Food |
| Puretein Agri LLC. |
| Veos Group |
| Pelagia AS |
| Omega Protein Corporation |
| Others |
Pricing and Supply Chain Analysis
Multi-year offtake agreements between Norwegian salmon integrators and Peruvian anchovy cooperatives lock in both volume certainty against El Niño quota volatility and price visibility across volatile commodity cycles. These contract structures compress spot market liquidity while creating compliant supplier premiums under tightening EU Feed Hygiene Regulation traceability mandates.
Pricing Analysis
Enzymatic refining infrastructure commands pricing premiums over conventional wet-rendering systems due to superior EPA/DHA retention rates exceeding 95%. Pricing stratifies across ASC-certified premium grades, standard commercial tiers, and economy emulsified variants for Asian shrimp feed mills. Cost compression in emulsified oils is intensifying because regional refiners substitute varying raw material qualities to meet Vietnamese and Thai pond production economics. Shrimp feed manufacturers exhibit highest price sensitivity, while Norwegian salmon integrators prioritize certification compliance over unit cost.
Supply Chain Analysis
Container availability constraints on the Callao-to-Rotterdam trade lane periodically disrupt just-in-time delivery schedules for Nordic feed manufacturers. Raw material flows draw from Peruvian and Chilean anchovy harvests, Gulf of Mexico menhaden catches, and North Sea sand eel quotas. Single-source vulnerability concentrates in the Humboldt Current ecosystem where PRODUCE-administered seasonal quotas constrain international refiner access. Distribution runs through direct sales channels for integrated salmon operators and regional distributor networks serving fragmented Southeast Asian feed mills.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across certification standards, species-specific formulations, and geographic production clusters creates multiple niche entry points for specialized suppliers. Shrimp intensification in previously extensive farming systems generates demand pockets underserved by incumbent salmon-focused oil refiners.
For Market Incumbents: Secure backward integration into byproduct capture from food-grade fish processing to reduce dependency on volatile pelagic fisheries. Invest in enzymatic refining capacity upgrades to defend margin position against algal oil substitution threats in pharmaceutical and premium pet food applications. Prioritize ASC and BAP certification maintenance to retain access to major European and North American retail supply contracts. For New Entrants and Emerging Players: ASC certification fast-track programs enable rapid eligibility for European salmon feed procurement tenders. Target Andhra Pradesh and Gujarat shrimp farming zones in India where certified fish oil penetration remains minimal despite rapid production growth. Deploy technical sales teams with formulation optimization expertise to differentiate against commodity distributor offerings. For Investors and Strategic Acquirers: Regional processors with established pelagic harvesting relationships and cold-extraction infrastructure represent compelling acquisition targets. Long-term viability hinges on positioning within marine stewardship certification schemes as eligibility criteria tighten. Monitor SUBPESCA and PRODUCE quota announcements as inflection indicators for raw material cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Byproduct Capture | Darling Ingredients leverages rendering operations to secure captive raw material streams independent of quota volatility. |
| Enzymatic Refining Capacity Expansion | Norwegian and Chilean salmon feed manufacturers specify these systems for EPA/DHA retention above 95%. |
| Multi-Certification Compliance Investment | ASC and BAP standards evolution creates eligibility barriers favoring pre-qualified suppliers with documented chain-of-custody. |
| Direct Contracting with Fleet Cooperatives | Multi-year offtake agreements with Peruvian anchovy operations shorten traditional trading house intermediation. |
| Regional Distribution Network Buildout | Ho Chi Minh City and Bangkok trading houses aggregate fragmented shrimp feed mill demand with inventory financing. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with salmon feed formulators, shrimp farm technical directors, marine ingredient procurement managers, and Peruvian fleet cooperative representatives. Secondary validation drew from PRODUCE catch quota announcements, SUBPESCA regulatory filings, EU Feed Hygiene Regulation documentation, and customs trade data. Bottom-up volume modeling triangulated against top-down market sizing across product type, application, and geographic segments.
Across the analysis window, forecasts incorporate product type splits between concentrated oils, emulsified variants, and omega-3 supplements; application segmentation spanning salmon, shrimp, tilapia, and marine fish farming; and end-user categories including aquaculture farms, feed manufacturers, and research institutions. CAGRs were derived from trend extrapolation anchored to documented production capacity expansions and regulatory implementation timelines. Key inputs include El Niño cycle patterns affecting anchovy biomass and enzymatic refining adoption rates in premium salmon feed supply chains.
Decision-makers should treat outputs as directional under assumptions of stable EU Feed Hygiene Regulation enforcement and no structural disruption to Peruvian anchovy harvest quotas; material deviation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aquaculture Innovations
Aquaculture Additives Market
Aquaculture Innovations
Fish Farming Market
Aquaculture Innovations
Seaweed Cultivation Market
Aquaculture Innovations
Egypt Aquafeed Market
Aquaculture Innovations
GCC Fish Farming Market
Aquaculture Innovations
Clams, Cockles, Ark Shells Market
Aquaculture Innovations
Thailand Aquafeed Market
Aquaculture Innovations
Oman Aquaculture Market
Aquaculture Innovations
China Shrimp Market
Aquaculture Innovations
Aquaculture Products Market
Aquaculture Innovations
Global Aquafeed and Aquaculture Additives Market
Aquaculture Innovations
Japan Aquafeed Market
Aquaculture Innovations
Ornamental Fish Market
Aquaculture Innovations
Aquaculture Healthcare Market
Aquaculture Innovations
China Shrimp Feed Market
Aquaculture Innovations
Saudi Arabia Aquaculture Market