
 GCC Fish Farming Market | 2026-2036
GCC Fish Farming Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Fish Farming Market Insights
Recirculating aquaculture system technology is narrowing the cost gap between offshore wild catch and land-based production across the Arabian Peninsula. National Aquaculture Group (NAQUA) leverages its Red Sea coastal infrastructure to dominate barramundi and shrimp output. Saudi Fisheries Company anchors government-backed expansion targets through integrated hatchery-to-harvest operations. Fish Farm LLC differentiates via boutique-scale tilapia production serving UAE hospitality channels.
GCC fish farming denotes the controlled cultivation of finfish in marine, brackish, or freshwater environments using tanks, cages, or ponds, with water quality maintained through mechanical filtration, oxygenation, and temperature management to achieve harvest weights of 300–800 grams within 8–14 months depending on species. The practice supplies protein to foodservice, retail, and export buyers across a region importing over seventy percent of consumed seafood. Tilapia occupies the volume lead due to tolerance for saline groundwater and high stocking densities in Saudi and UAE facilities. Recirculating aquaculture systems capture the fastest expansion as land scarcity and water conservation mandates intensify across the Gulf. Cage culture sustains margin concentration in Omani coastal waters where deeper fjords reduce environmental conflict.
MOHAP in the UAE and Saudi Arabia's Ministry of Environment, Water and Agriculture enforce hatchery biosecurity protocols, effluent discharge limits, and veterinary drug residue standards that determine market access for domestic producers. BIS-equivalent Gulf Standardization Organization benchmarks for imported feed ingredients and broodstock genetics shape input cost structures and supply security. SAMAQ and Oman Fisheries Development Company must navigate dual permitting from fisheries authorities and coastal development zones. Stakeholders should monitor how desalination co-location partnerships and algae-based feed trials alter unit economics before committing capital to greenfield sites.
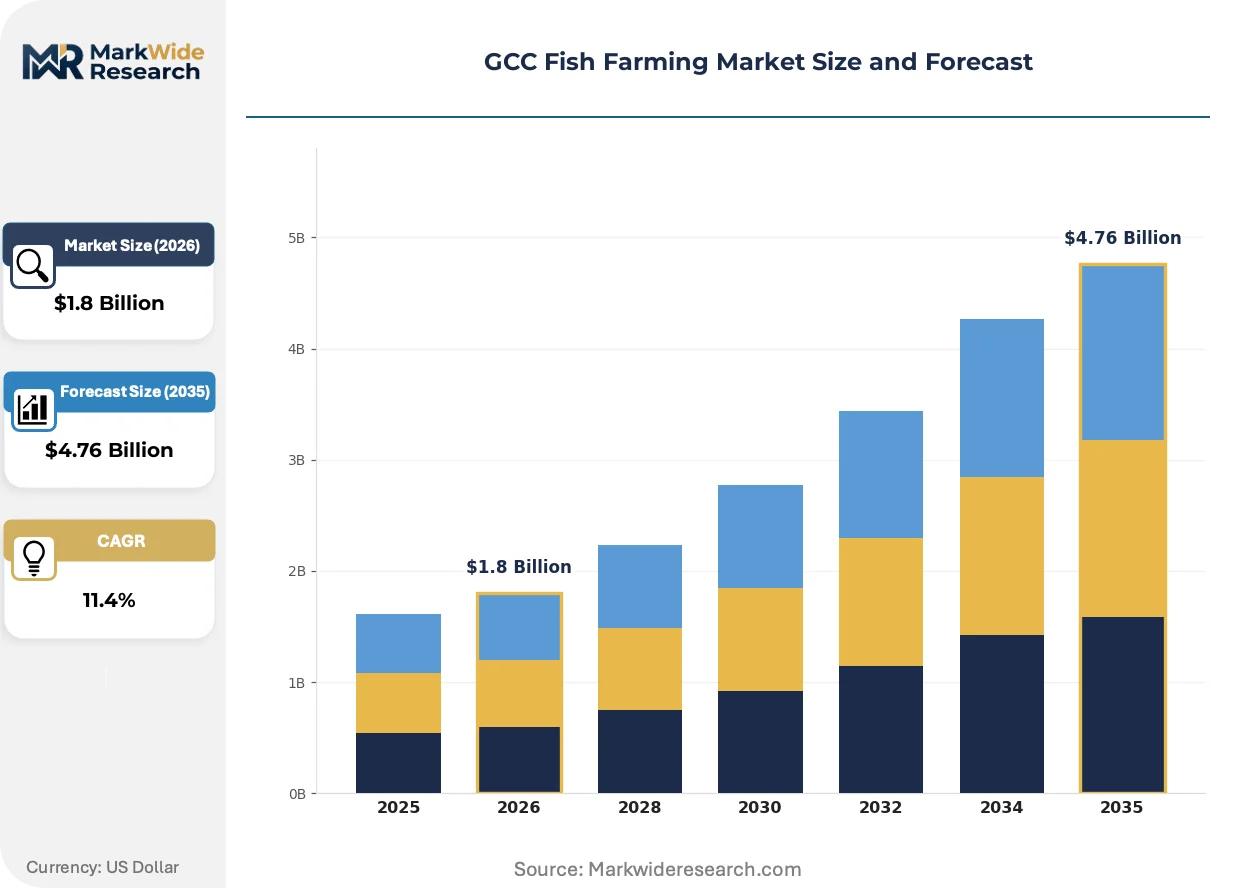
Market Dynamics
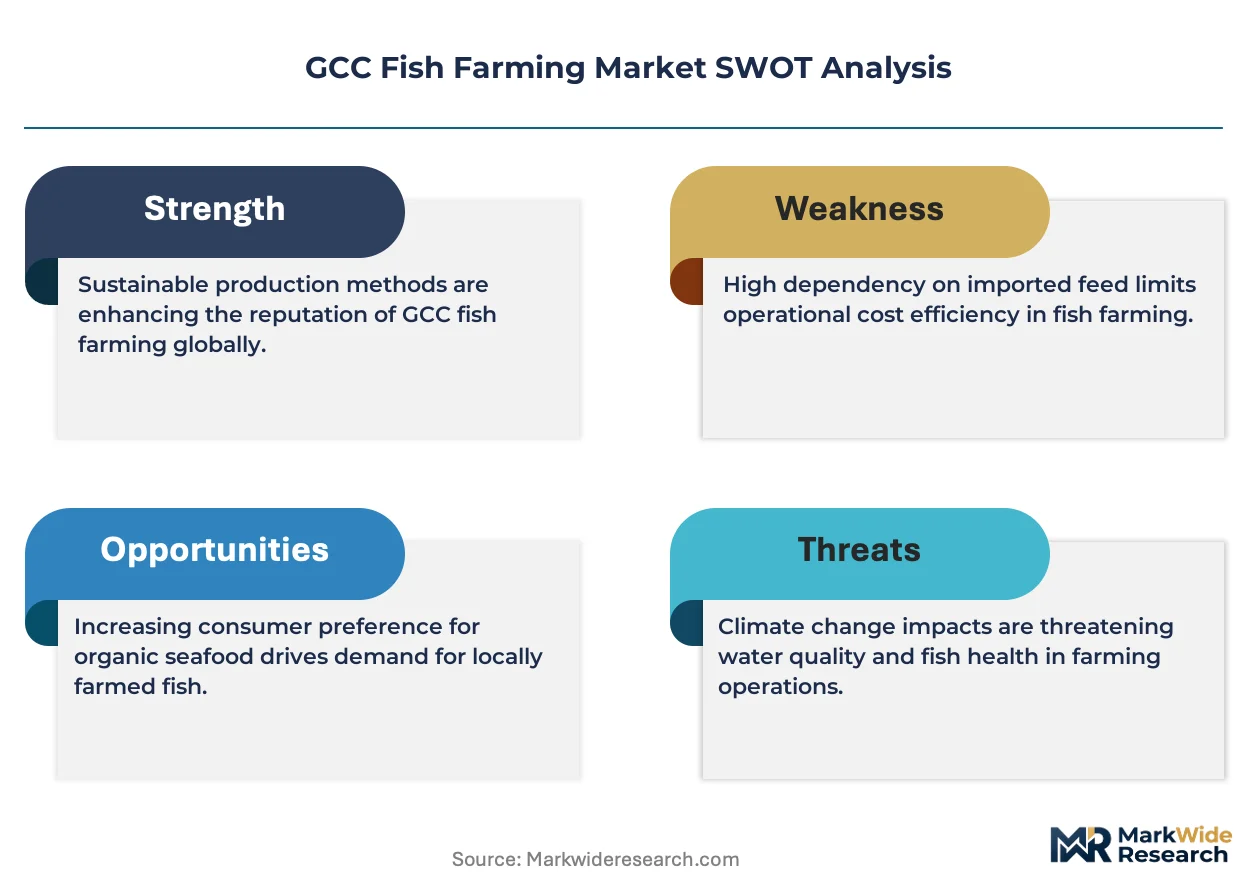
Recirculating aquaculture system technology is collapsing the cost premium of land-based finfish production versus offshore wild catch across Saudi Arabia and the UAE, triggering capital redeployment from cage culture toward controlled-environment facilities.
Growth Catalysts
- Saudi aquaculture licensing reforms:Streamlined farm permits and environmental compliance protocols from the Ministry of Environment, Water and Agriculture are accelerating project approvals in Jazan and the Eastern Province.
- Hotel and restaurant procurement:Foodservice buyers across the Gulf are mandating locally farmed barramundi and tilapia for supply chain security and freshness guarantees.
- Integrated saltwater recirculating systems:Water conservation mandates and land scarcity are concentrating new capacity in closed-loop facilities that recycle ninety percent of system volume.
Market Restraints
- Broodstock genetics concentration:GCC producers remain dependent on imported fry and genetic material, exposing operations to biosecurity disruptions and currency fluctuations.
- Feed ingredient cost volatility:Fishmeal and soy protein concentrate prices track global commodity markets, compressing margins during supply shocks.
- Desalination energy coupling:Recirculating system economics tie directly to regional electricity tariffs, creating vulnerability to utility pricing reforms.
Strategic Opportunities
- Omani coastal fjords:Deep-water cage culture sites in Musandam and Dhofar offer lower environmental conflict potential and reduced land competition versus Saudi and UAE markets.
- Algae-based feed trials:Partnerships between aquafeed manufacturers and regional algae cultivators promise to localize protein inputs and reduce import dependency.
- Desalination co-location:Brine discharge from coastal desalination plants provides ready saline water infrastructure for integrated aquaculture parks.
Industry Challenges
- Recirculating system engineering talent:Shortage of technicians trained in biofiltration management and water chemistry monitoring limits facility commissioning speed.
- Dual permitting complexity:Operators must secure concurrent approvals from fisheries authorities and coastal development zones, extending project timelines.
- Veterinary drug residue compliance:MOHAP and Saudi Ministry of Environment, Water and Agriculture enforcement of maximum residue limits requires rigorous traceability systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Fish Farming Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tilapia, Salmon, Catfish, Barramundi Technology: Recirculating Aquaculture Systems, Cage Culture, Integrated Multi-Trophic Aquaculture, Flow-Through Systems End User: Restaurants, Retail Chains, Supermarkets, Exporters Distribution Channel: Online Sales, Wholesale, Direct Sales, Distributors |
| Companies Covered | National Aquaculture Group (NAQUA), Tabuk Fisheries Company, Oman Fisheries Development Company, Aqua Bridge, Fish Farm LLC, Saudi Fisheries Company, SAMAQ, Emirates Aquaculture Company, Almarai, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Fish Farming Market Trends and Innovations
Technology convergence and regulatory tightening are compressing production cycles while elevating biosecurity standards across Gulf aquaculture operations.
Sensor-integrated water quality monitoring is collapsing the labor intensity of daily parameter checks across Saudi recirculating facilities. Jazan-based operators are deploying dissolved oxygen and ammonia probes with automated alert systems, reducing mortality events and enabling higher stocking densities. This automation is collapsing the historical staffing advantage of cage culture versus land-based systems.
Saudi Arabia's Ministry of Environment, Water and Agriculture has mandated hatchery biosecurity protocols and effluent discharge limits that exceed prior voluntary industry standards. These rules force facility retrofits and exclude subscale operators from formal supply chains. UAE foodservice distributors are now requiring veterinary drug residue documentation aligned with MOHAP standards as a procurement precondition.
Direct contracting between hotel groups and single-source farms is displacing traditional seafood auction and wholesale intermediaries across Dubai and Riyadh. Large hospitality chains are securing multi-year offtake agreements with named barramundi producers, specifying harvest size and delivery schedules. This channel consolidation is most advanced in UAE five-star properties seeking provenance marketing claims.
GCC Fish Farming Market Segmentation
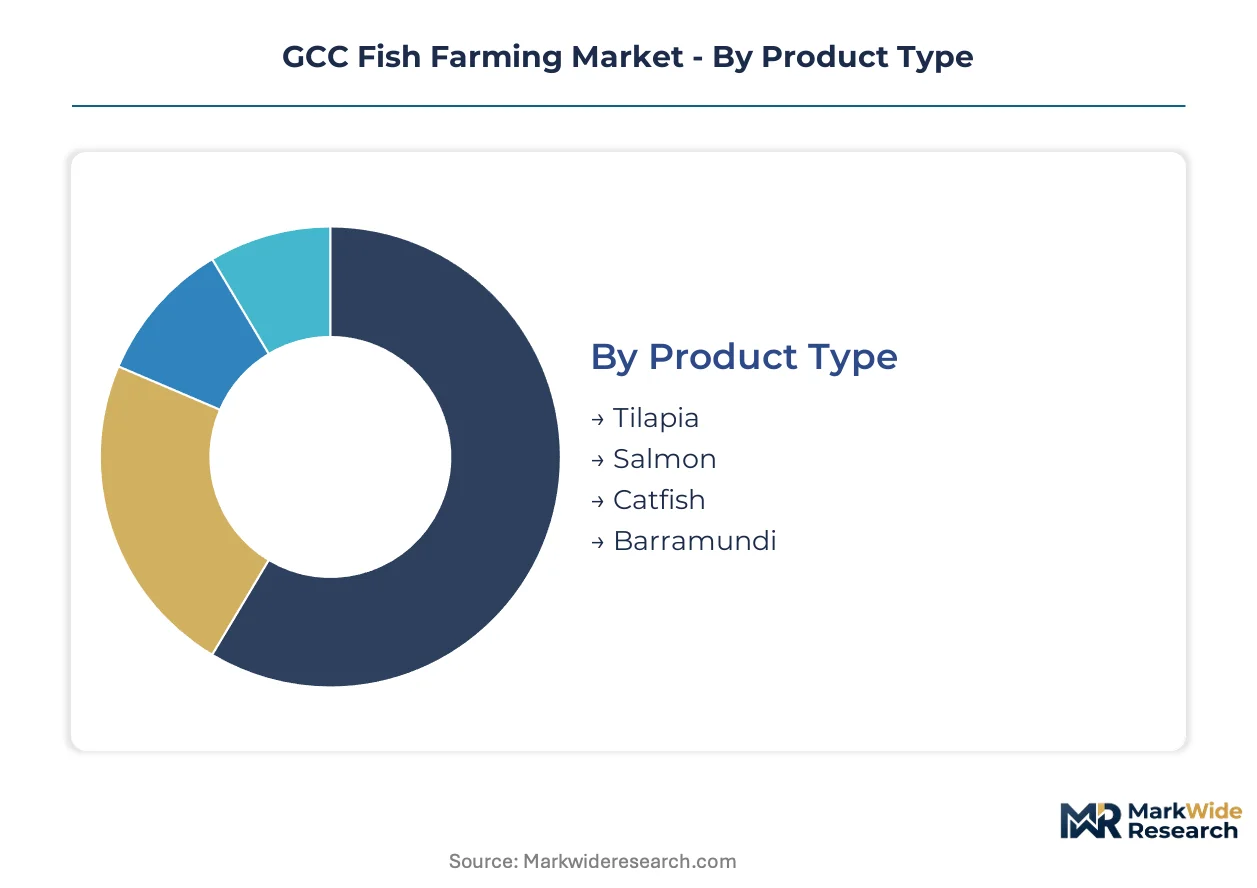
Species selection and production technology determine capital intensity, harvest cycles, and buyer access across Gulf aquaculture operations. End-user procurement patterns and distribution channel configurations further stratify margin capture between commodity volume and premium positioning.
Product Type:
Species tolerance for saline groundwater and stocking density economics span distinct use-case spectrums from mass-market protein to hospitality-grade fillets.
- Tilapia:Hardy Oreochromis niloticus strains tolerate brackish groundwater with salinities up to 15 ppt, enabling high-density tank culture in Saudi Arabia's Eastern Province and UAE inland facilities. Restaurant chains in Dubai and Riyadh specify 400-600 gram whole fish for live-tank display service, driving contract farming agreements with named suppliers.
- Barramundi:Lates calcarifer commands premium positioning through Red Sea cage culture and recirculating systems near Jazan, with harvest weights of 800 grams yielding plate-sized fillets for five-star hotel procurement. MOHAP residue documentation requirements and traceability mandates concentrate supply among integrated operators capable of hatchery-to-harvest control.
- Salmon:Atlantic salmon production remains experimental across the Gulf due to thermal tolerance constraints, with pilot RAS facilities in Oman testing temperature-controlled grow-out for niche export positioning.
- Catfish:Clarias gariepinus occupies budget retail and institutional catering segments through Egyptian broodstock imports, with shorter 6-8 month cycles appealing to first-time Saudi entrants seeking rapid cash conversion.
Established volume favors tilapia; emerging adoption favors barramundi.
Technology:
Capital deployment and operating cost structures stratify across technology maturity curves from proven cage systems to precision-controlled closed loops.
- Recirculating Aquaculture Systems:Mechanical filtration, biofilm reactors, and oxygen injection recycle 90 percent of system water, collapsing land and seawater requirements for Saudi and UAE greenfield sites. Jazan-based operators deploy sensor-integrated monitoring to compress mortality events and justify premium pricing to hotel buyers.
- Cage Culture:Deep-water net pens in Omani fjords leverage natural currents for waste dispersal, sustaining lower feed conversion ratios than land-based alternatives while avoiding coastal land competition.
- Integrated Multi-Trophic Aquaculture:Co-cultivation of finfish with seaweed and shellfish extractors remains pilot-scale across the Gulf, with algae-based feed trials promising to localize protein inputs and reduce fishmeal import dependency.
- Flow-Through Systems:Single-pass freshwater raceways concentrate in Saudi groundwater zones near Qassim, serving domestic tilapia demand with lower capital barriers than closed-loop alternatives but higher water consumption exposure to conservation mandates.
Capital intensity concentrates in recirculating systems; operational simplicity sustains cage culture margins.
End User:
Procurement specifications and traceability requirements diverge sharply between foodservice freshness mandates and retail shelf-life constraints.
- Restaurants:Dubai and Riyadh hospitality groups mandate live-tank or same-day harvested supply with veterinary documentation, displacing traditional auction intermediaries through direct farm contracting.
- Retail Chains:Supermarket buyers specify chilled fillet presentation with 7-day shelf life, favoring integrated operators with on-site processing and HACCP certification.
- Supermarkets:Hypermarket volume procurement in Saudi Arabia and the UAE concentrates on frozen tilapia imports, with domestic farmed supply capturing premium positioning through "locally produced" labeling.
- Exporters:Air-freight live fish to Asian markets and frozen fillet shipments to Europe require SFDA and destination-country residue compliance, filtering supply to NAQUA-scale integrated producers.
Direct contracting reshapes restaurant supply; retail consolidation favors scale-certified operators.
Distribution Channel:
Channel selection determines margin retention and buyer relationship depth across fragmented Gulf seafood wholesale networks.
- Direct Sales:Named farm-to-hotel agreements in Dubai secure multi-year offtake with specified harvest windows, capturing 15-20 point margin premiums over auction clearing.
- Wholesale:Traditional seafood markets in Jeddah and Abu Dhabi aggregate mixed-origin supply, compressing domestic farmed fish into commodity pricing tiers alongside imports.
- Distributors:Cold-chain logistics specialists with MOHAP licensing intermediate between farms and retail chains, absorbing traceability documentation burdens for smaller producers.
- Online Sales:E-commerce platforms for home delivery of live fish remain nascent, constrained by last-mile oxygenated transport infrastructure gaps outside Riyadh and Dubai metropolitan zones.
Relationship depth favors direct sales; coverage extension favors distributor networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Five-star hotel procurement directors in Dubai and Riyadh anchor regional demand for traceable, locally farmed barramundi and tilapia. This buyer concentration shapes capacity deployment across coastal zones.
Saudi Arabia
Red Sea coastal demand from Jazan hospitality clusters drives barramundi recirculating system investments. The Ministry of Environment, Water and Agriculture streamlined aquaculture licensing in 2024, collapsing permit timelines from 18 to 8 months. Eastern Province tilapia facilities near Dammam exploit saline groundwater tolerance to achieve 400-gram harvest weights in 10-month cycles.
United Arab Emirates
Dubai's hotel groups mandate MOHAP-certified residue documentation for live-tank fish supply, filtering procurement to integrated operators. Federal aquaculture regulations under the Ministry of Climate Change and Environment require hatchery biosecurity protocols matching EU import standards. Ras Al Khaimah's coastal development zones host the Emirates' fastest-scaling recirculating capacity.
Oman
Deep-water cage culture in Musandam fjords sustains lower feed conversion ratios than land-based alternatives. The Ministry of Agriculture, Fisheries and Water Resources permits dual-use coastal leases that reduce land competition. Dhofar Governorate's cooler monsoon waters host pilot Atlantic salmon recirculating trials targeting niche export positioning.
Qatar
Food security mandates from the Ministry of Municipality and Environment accelerate tilapia capacity additions to reduce import dependency. Hamad Port logistics infrastructure enables air-freight live fish exports to Asian markets. Umm Salal Mohammed's integrated aquaculture park leverages desalination brine discharge for saline water supply.
Kuwait
Retail chain procurement concentrates on chilled tilapia fillets with 7-day shelf life specifications. The Environment Public Authority enforces effluent discharge limits that exclude subscale operators from formal supply chains. Bubiyan Island's coastal zone planning reserves parcels for multi-trophic aquaculture integration.
GCC Fish Farming Market Competitive Landscape
Channel-controlling players compete with product-specialist players across procurement tiers. The vendor base stratifies between integrated hatchery-to-harvest operators and boutique-scale hospitality suppliers. Two archetypes dominate: Red Sea coastal infrastructure holders leveraging cage and recirculating capacity; and UAE-based specialists securing direct hotel contracts through live-tank service models. Competitive moves center on multi-year offtake agreements with named buyers and backward integration into hatchery genetics control.
Within the integrated infrastructure tier, National Aquaculture Group anchors barramundi and shrimp output through Red Sea coastal assets. Fish Farm LLC occupies the boutique-specialist position serving UAE hospitality channels with tilapia live-tank supply. SAMAQ represents the government-backed expansion archetype through Eastern Province hatchery-to-harvest operations. These three exemplify how scale concentration, channel depth, and public-sector alignment stratify competitive positioning across the Gulf.
| Leading Market Players |
|---|
| National Aquaculture Group (NAQUA) |
| Tabuk Fisheries Company |
| Oman Fisheries Development Company |
| Aqua Bridge |
| Fish Farm LLC |
| Saudi Fisheries Company |
| SAMAQ |
| Emirates Aquaculture Company |
| Almarai |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Saudi Red Sea recirculating aquaculture facilities is driving supplier discipline and premium pricing power for barramundi producers serving Jazan hospitality clusters. The Ministry of Environment, Water and Agriculture's streamlined permitting has not yet collapsed project timelines sufficiently to flood capacity, sustaining margin capture for integrated operators.
Pricing Analysis
Cost-plus contracts with fishmeal price indexation dominate feed procurement agreements between Saudi tilapia producers and global aquafeed suppliers. Three-tier pricing structure across premium, standard, and economy levels separates MOHAP-certified barramundi for Dubai five-star hotels from Eastern Province tilapia for retail chains and Egyptian-broodstock catfish for institutional catering. Pricing pressure stems from volatile soy protein concentrate and fishmeal import costs. Retail supermarket buyers exhibit highest price sensitivity, while hospitality procurement directors prioritize traceability documentation over unit cost.
Supply Chain Analysis
Extended payment terms from UAE hospitality groups strain working capital for boutique tilapia suppliers serving Dubai live-tank contracts. Broodstock genetics concentrate in Norway, Thailand, and Egypt, with fry import dependencies exposing Saudi and UAE operators to biosecurity disruptions. Feed ingredient sourcing draws from Peruvian fishmeal fisheries and Brazilian soy crushing capacity. Single-source vulnerability in desalination energy coupling creates tariff exposure to regional electricity pricing reforms. Distribution runs through cold-chain logistics specialists with MOHAP licensing that intermediate between farms and retail chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against frozen tilapia import substitution from Southeast Asian producers that undercut domestic farmed supply on price in Saudi retail channels.
For Market Incumbents: Pre-empt margin compression from frozen import substitution by securing multi-year offtake agreements with named hotel groups in Riyadh and Dubai that specify local provenance requirements. Backward integration into hatchery genetics control reduces biosecurity vulnerability from Norwegian and Thai fry suppliers. Channel control through direct farm-to-hotel contracts captures 15-20 point margin premiums over wholesale auction clearing. For New Entrants and Emerging Players: Build out boutique-scale recirculating capacity in Ras Al Khaimah coastal development zones to serve UAE hospitality live-tank demand with MOHAP-certified residue documentation. The most penetrable segment is mid-tier hotel chains seeking provenance marketing claims without NAQUA-scale volume commitments. Go-to-market angle centers on same-day harvest guarantees with automated sensor-integrated water quality monitoring that reduces mortality risk. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated operators with hatchery-to-harvest control and multi-year hospitality offtake agreements. Long-term viability favors assets with desalination co-location partnerships that lock in saline water infrastructure costs. Acquisition target archetype: Jazan-based barramundi producers with Red Sea coastal leases and existing MOHAP certification. Signal to watch is algae-based feed trial scale-up that would localize protein inputs and collapse import dependency.| Strategic Initiative | Industry Significance |
|---|---|
| Hatchery Genetics Backward Integration | Captive broodstock control insulates Saudi operators from Norwegian fry supply disruptions. |
| Desalination Co-location Partnership | Brine discharge access collapses saline water infrastructure costs for Red Sea facilities. |
| Direct Hotel Contracting | Named farm agreements with Dubai hospitality groups displace traditional wholesale intermediaries. |
| Algae-based Feed Trials | Regional protein cultivation reduces fishmeal import exposure to Peruvian supply volatility. |
| Sensor-integrated Water Monitoring | Automated dissolved oxygen probes enable higher stocking densities in Jazan recirculating systems. |
Research Methodology
Initial hypotheses were tested against primary input from aquaculture facility managers, hospitality procurement directors, veterinary drug residue compliance officers, and aquafeed procurement leads and refined through secondary validation against Saudi Ministry of Environment, Water and Agriculture licensing records, MOHAP biosecurity protocol filings, GCC customs trade data for fishmeal and fry imports, and operator financial disclosures. Bottom-up capacity tallies across Jazan and Eastern Province facilities were triangulated against top-down protein demand estimates from hotel and restaurant sector reports.
Demand-supply balance modeling across the projection horizon anchored volume forecasts, with segmentation by species, production technology, and end-user procurement tier. CAGRs were derived from fitted growth curves calibrated to licensing velocity and capital deployment patterns. Industry-specific inputs included desalination energy tariff trajectories, fishmeal price index movements, and hospitality sector expansion pipelines in Riyadh and Dubai.
Stress conditions across electricity pricing reforms, fishmeal supply disruptions, and fry import biosecurity events were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory streamlining pace and hospitality procurement shift timing. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aquaculture Innovations
China Aquafeed Market
Aquaculture Innovations
Japan Aquafeed Market
Aquaculture Innovations
Fish Farming Equipment Market
Aquaculture Innovations
North America Shrimp Feed Market
Aquaculture Innovations
Aquaculture Products Market
Aquaculture Innovations
Aquaculture Market
Aquaculture Innovations
Hatchery Product Market
Aquaculture Innovations
United Arab Emirates Fisheries and Aquaculture Market
Aquaculture Innovations
Vietnam Aquaculture Market
Aquaculture Innovations
South Korea Aquaculture Market
Aquaculture Innovations
Global Ornamental Fish Feed Market
Aquaculture Innovations
Fish Oil for Aquafeed Market
Aquaculture Innovations
Global Aquafeed and Aquaculture Additives Market
Aquaculture Innovations
Aquaculture Pumps Market
Aquaculture Innovations
Ornamental Tropical Fish Feed Market
Aquaculture Innovations
Global Precision Aquaculture Market