
 Microalgae-Based Aquafeed Market | 2026-2036
Microalgae-Based Aquafeed Market Size, Share, and Industry Trends Forecast 2026-2036
Microalgae-Based Aquafeed Market Intelligence
Customized formulation services based on species-specific nutritional requirements is hardening the value proposition beyond simple bulk ingredient sales. Corbion N.V. leverages its expertise in fermentation to produce high-DHA algal oils. Koninklijke DSM N.V. competes on the basis of its extensive R&D in nutritional solutions and broad market access. Cargill, Incorporated extends its influence through its vast global distribution network for feed ingredients.
Microalgae-based aquafeed refers to nutritional formulations for aquaculture species that incorporate microalgae as a primary ingredient. These feeds are engineered to deliver high concentrations of omega-3 fatty acids like EPA and DHA. Their purpose is to provide a sustainable alternative to fish oil, enhancing animal health. While powdered forms serve early-stage use in hatcheries, the pellet format is crucial for commercial producers in applications such as shrimp and fish farming.
Market access is governed by stringent feed safety regulations. The FDA in the United States and the European Food Safety Authority (EFSA) both oversee ingredient approvals and safety assessments. Concurrently, standards from China's Ministry of Agriculture and Rural Affairs influence formulation choices in Asia's largest market. Stakeholders must now decide whether to prioritize upstream investment in proprietary algal strain development or focus on downstream partnerships to secure market channels.
Market Dynamics
The central tension shaping the market is the aquaculture industry's structural imperative to de-risk its supply chain from the price volatility and ecological limits of marine-derived fish oil, creating a direct pull for scalable, consistent alternatives like microalgae.
Growth Catalysts
- High-Yield Cultivation:Advances in closed-loop photobioreactor and fermentation technologies are improving biomass density and lipid yields. This enhancement in production efficiency makes microalgae more cost-competitive against traditional feed inputs for large-scale aquaculture.
- Shrimp Farming Demand:The global shrimp farming industry requires feed with specific nutritional profiles, particularly high levels of DHA, for optimal health and growth. Microalgae-based ingredients directly meet this species-specific need, driving adoption in major production hubs.
- Regulatory Pressures:Sustainability mandates, such as those within the EU Green Deal's Farm to Fork strategy, encourage a shift away from wild-caught fish for feed. This policy framework creates a powerful incentive for aquaculture operators to incorporate alternatives.
Market Restraints
- High Capital Expenditure:The construction and operation of advanced cultivation facilities, whether photobioreactors or large-scale fermenters, require significant upfront investment. This capital intensity creates a high barrier to entry for new producers compared to traditional feed ingredient processing.
- Production Scale Mismatch:While growing, the total global production volume of aquafeed-grade microalgae has yet to reach a scale that can fully displace the immense volume of fish meal and fish oil used by the aquaculture industry, limiting its substitution capacity.
- Competition from Other Oils:Microalgae-based oils face competition from a growing array of alternative lipid sources. These include terrestrial plant-based oils from genetically modified crops and emerging insect-based oils, which also target the aquafeed market.
Strategic Opportunities
- Geographic Expansion:Significant opportunity exists in penetrating the rapidly expanding aquaculture markets of Southeast Asia, particularly for species like tilapia and barramundi. This involves adapting formulations for local farming systems beyond the established salmon and shrimp sectors.
- Broodstock Nutrition Niche:There is an unmet need for specialized, high-potency algal formulations designed for broodstock conditioning. Such products can improve fecundity, egg quality, and larval survival, creating a high-value market segment.
- Strain Bioprospecting:The discovery and commercialization of novel microalgae strains with unique properties, such as faster growth rates or resistance to contamination, present a key opportunity. This focus on upstream R&D can yield significant competitive advantages through intellectual property.
Industry Challenges
- Quality Standardization Deficit:The market lacks universally accepted standards for assessing the quality and bioavailability of nutrients in microalgae products. This inconsistency complicates feed formulation and makes it difficult for buyers to compare offerings from different suppliers.
- Intellectual Property Navigation:The development of proprietary algal strains and cultivation methods is creating a complex landscape of patents and licensing agreements. Securing freedom to operate and defending unique genetic assets is a growing operational challenge for producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microalgae-Based Aquafeed Market |
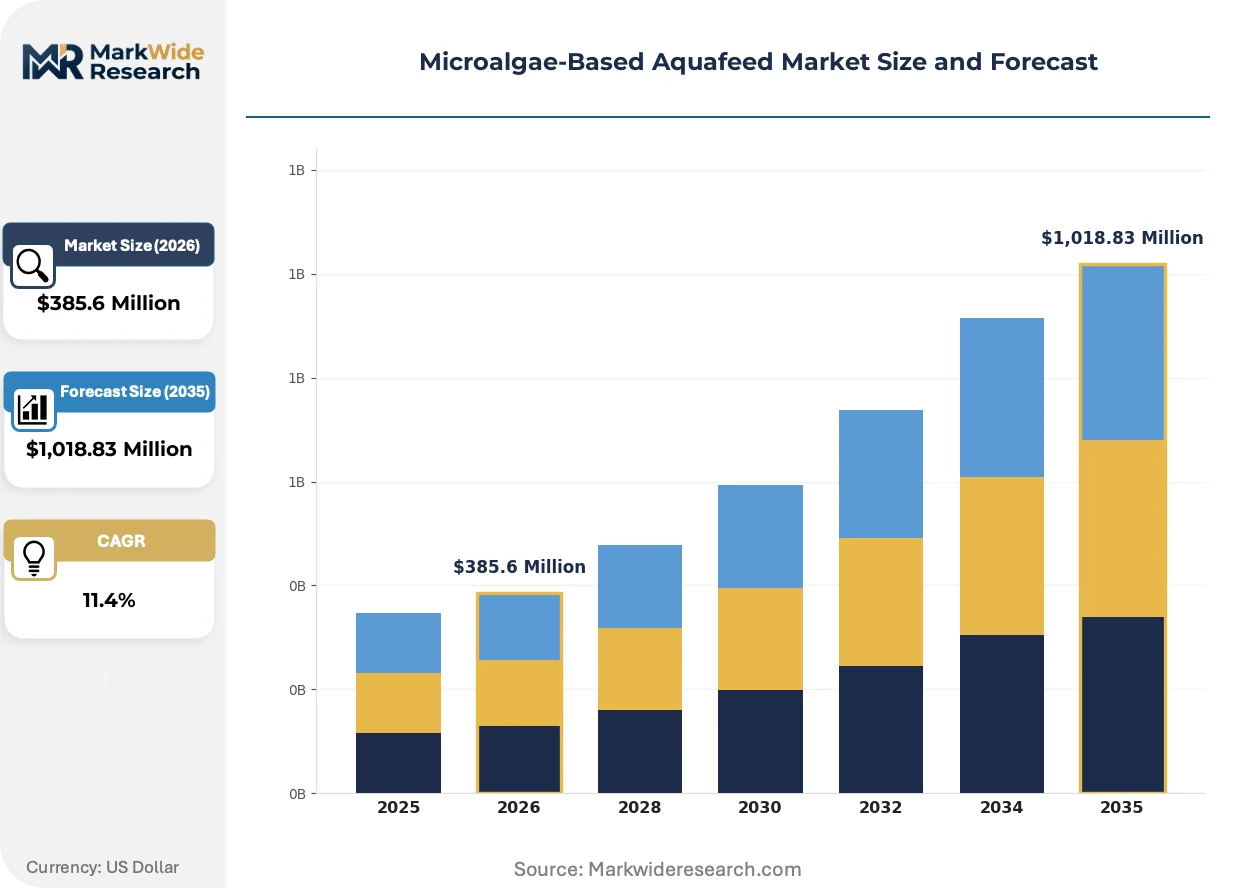
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $1,018.83 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powdered, Pellets, Flakes, Liquid Concentrate Application: Fish Farming, Shellfish Cultivation, Shrimp Farming, Ornamental Aquaculture End User: Commercial Producers, Research Institutes, Aquatic Nurseries, Hatcheries Distribution Channel: Direct Sales, Online Retailers, Distributors, Agricultural Cooperatives |
| Companies Covered | Corbion N.V., Cellana Inc., Koninklijke DSM N.V., The Archer-Daniels-Midland Company, A4F Algae for the Future, BioMar Group, Cargill, Incorporated, Alltech, Allmicroalgae, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microalgae-Based Aquafeed Market Strategic Shifts & Innovations
Maturation from a niche ingredient to a strategic component for supply chain resilience defines the market's current trajectory. This shift is driven by a convergence of bioprocessing advancements, tightening sustainability regulations, and evolving procurement standards in commercial aquaculture.
Fermentation-based production of algal biomass and oils represents a significant technological evolution. This closed-loop process allows for precise control over growth conditions, eliminating environmental variability and ensuring consistent output of high-DHA products. Large-scale feed manufacturers are the primary adopters, seeking reliable inputs. This technology is absorbing the supply chain risk and price volatility inherent in sourcing marine-derived fish oil.
European Union sustainability policies, particularly the Farm to Fork strategy, are creating a powerful regulatory tailwind. This framework mandates a reduction in the environmental footprint of food production, directly incentivizing the use of sustainable feed ingredients like microalgae. Salmon producers in Norway and sea bass farmers in Greece are most affected, actively reformulating their feeds to meet these new standards and maintain market access.
A preference for complete supply chain traceability is altering aquafeed ingredient purchasing. This disrupts the traditional, often opaque, model of sourcing bulk commodities, with buyers now demanding verifiable proof of origin and sustainability. This shift in procurement is most pronounced within the high-value salmon industry, where retailers in Europe and North America pass consumer demands for transparency back up the supply chain.
Microalgae-Based Aquafeed Market Segmentation
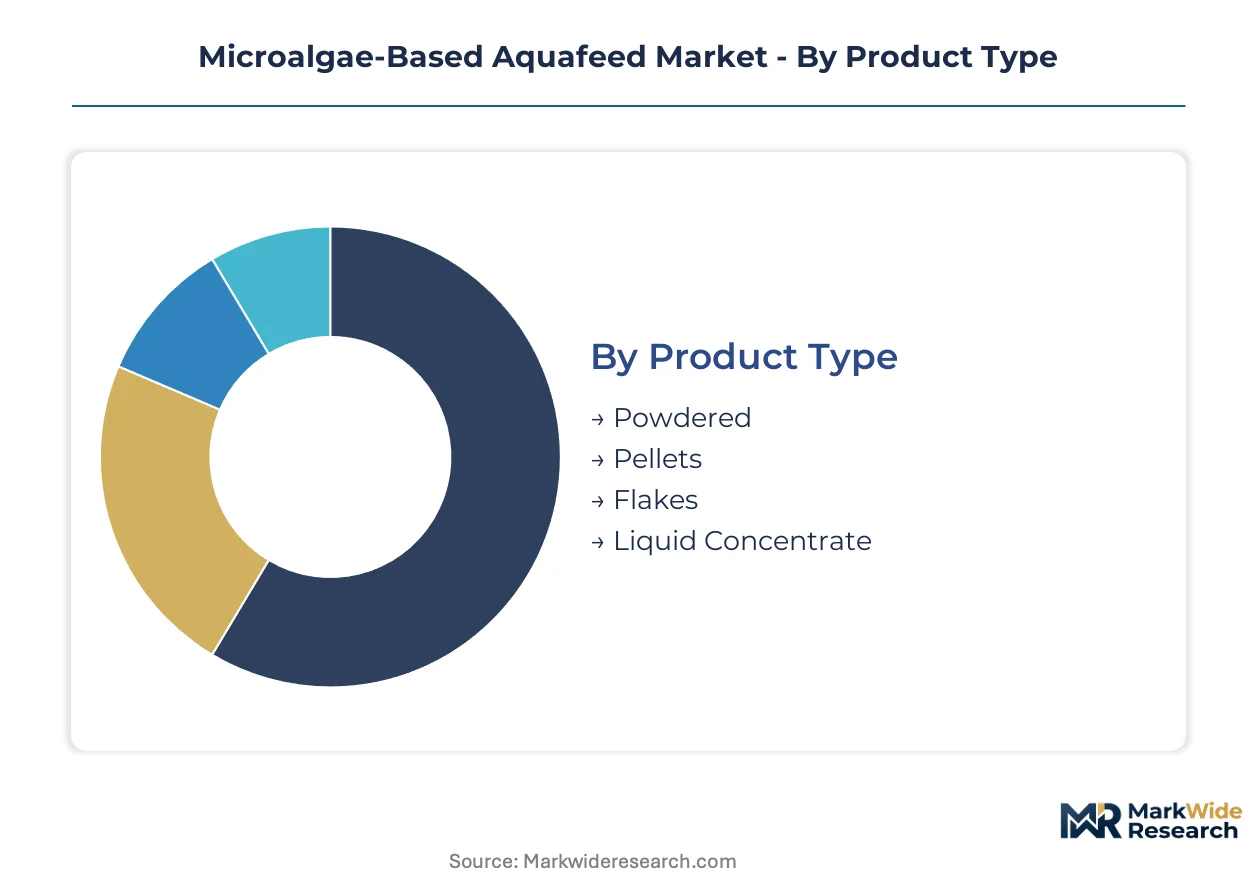
The microalgae-based aquafeed market stratifies across several dimensions, reflecting the diverse needs of aquaculture operators and the varied forms of feed products. Understanding these distinctions is critical for producers to tailor offerings and for buyers to optimize nutritional strategies.
Product Type:
Buyer preferences in this category are differentiated by the physical form factor of the microalgae feed, impacting application and handling in various cultivation systems.
- Pellets:These compressed, cylindrical feed items are designed for larger, more mature aquaculture species like fish and shrimp, ensuring nutrient stability and controlled feeding. Pellets are crucial for commercial producers, providing a durable and efficient delivery method for essential omega-3 fatty acids in grow-out phases.
- Powdered:Comprising finely ground microalgae biomass, this form is essential for larval stages and early-stage aquatic organisms in hatcheries due to its high digestibility. Demand for powdered microalgae concentrates in the early life cycle nutrition for shrimp and finfish, supporting initial growth and immune development.
- Flakes:Thin, dried sheets of microalgae offer a palatable and easily digestible option for smaller fish and ornamental species.
- Liquid Concentrate:This high-density suspension provides a direct, bioavailable nutrient source, often used in specialized applications or for enriching live feeds.
Pellets lead volumes today; Liquid Concentrate is gaining share fastest.
Application:
The application segment differentiates market demand based on the specific aquaculture species being cultivated, each possessing unique dietary requirements and metabolic profiles.
- Shrimp Farming:This application demands microalgae-based feeds rich in DHA and other essential nutrients to support rapid growth, disease resistance, and reproductive health in shrimp. The global shrimp farming industry, particularly in Asia, drives significant adoption to improve feed conversion ratios and reduce reliance on marine-derived ingredients.
- Fish Farming:Encompassing a wide array of species from salmon to tilapia, fish farming utilizes microalgae feeds to enhance omega-3 content, improve flesh quality, and support overall fish health. European salmon producers and Asian tilapia farmers represent major demand centers, driven by sustainability mandates and consumer preferences for healthier seafood.
- Shellfish Cultivation:Microalgae serve as a primary food source for filter-feeding shellfish like oysters and clams, supporting their growth and reproductive cycles.
- Ornamental Aquaculture:This niche segment uses microalgae feeds to boost coloration, vitality, and health in aquarium fish and other aquatic pets.
Shrimp Farming commands the largest share, while Ornamental Aquaculture shows the steepest expansion trajectory.
End User:
Customer type within the end-user segment reflects varying operational scales and nutritional requirements, from large-scale commercial operations to specialized research facilities.
- Commercial Producers:These are large-scale aquaculture operations, including vast fish farms and shrimp hatcheries, that require high volumes of consistent, cost-effective microalgae-based aquafeed. Commercial producers prioritize feed efficiency and sustainability to meet market demands for seafood.
- Hatcheries:Specializing in the early life stages of aquatic organisms, hatcheries require highly digestible, nutrient-dense microalgae formulations to ensure optimal larval development and survival rates. This segment prioritizes precise nutritional profiles for sensitive young aquatic animals.
- Research Institutes:Academic and private research entities utilize microalgae feeds for controlled studies on aquatic nutrition, disease prevention, and sustainable aquaculture practices.
- Aquatic Nurseries:These facilities bridge the gap between hatcheries and grow-out farms, using microalgae feeds to support the growth of juvenile aquatic species before their transfer.
Commercial Producers generate the bulk of demand, with Research Institutes expanding most quickly.
Distribution Channel:
The distribution channel segment highlights how microalgae-based aquafeed reaches its diverse customer base, influencing market access and product availability across different regions.
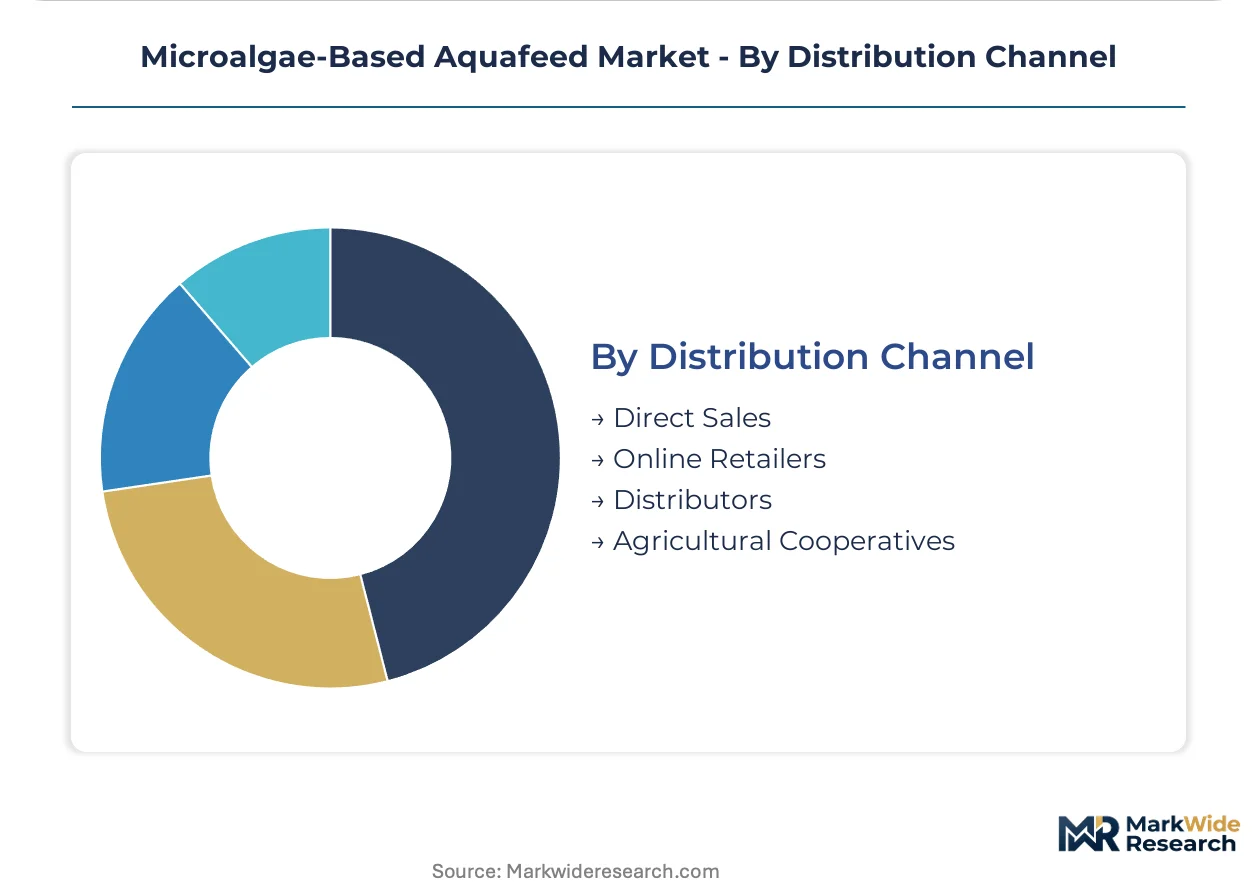
- Direct Sales:This channel involves producers selling microalgae-based aquafeed directly to large commercial aquaculture farms or specialized buyers, often for customized formulations or bulk orders. Direct sales foster strong client relationships and allow for tailored product delivery.
- Distributors:Independent distributors and aggregators play a crucial role in reaching a broader base of small to medium-sized aquaculture operations, leveraging existing networks and logistical capabilities. Distributors provide essential market access, particularly in fragmented regional markets.
- Online Retailers:E-commerce platforms facilitate the sale of microalgae aquafeed, especially for niche products, smaller quantities, or ornamental aquaculture hobbyists.
- Agricultural Cooperatives:Farmer-owned cooperatives pool purchasing power for their members, securing better pricing and access to microalgae-based feeds for collective benefit.
Distributors ensure widespread availability, and Online Retailers are climbing the fastest in market penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norway's established salmon aquaculture industry and China's vast shrimp farming sector present distinct opportunities for microalgae-based aquafeed producers. These regions demonstrate contrasting scales of adoption and regulatory landscapes influencing market development. Significant demand centers are emerging across various continents, each with unique drivers and regulatory frameworks for sustainable aquaculture ingredients.
Norway
Norway's salmon industry drives demand for high-quality, sustainable feed ingredients to maintain its premium market position. The EU Green Deal's Farm to Fork strategy encourages a shift away from wild-caught fish for feed, directly impacting Norwegian producers. Bergen and Trondheim serve as key aquaculture research and innovation hubs, fostering ingredient development and adoption.
China
China's extensive shrimp and finfish farming operations require large volumes of nutrient-rich feeds to support rapid growth cycles. The Ministry of Agriculture and Rural Affairs influences feed formulation choices through its quality and safety standards for aquaculture inputs. Guangdong and Fujian provinces, major aquaculture regions, are seeing increased interest in microalgae to enhance feed efficiency.
United States
Aquaculture expansion in the United States, particularly for species like tilapia and shrimp, creates a growing need for alternative protein and lipid sources. The FDA oversees ingredient approvals and safety assessments for novel feed components, ensuring product integrity. Facilities in Florida and Hawaii are actively developing and scaling microalgae cultivation for various aquafeed applications.
India
India's burgeoning aquaculture sector, particularly for shrimp and carp, seeks cost-effective and sustainable feed solutions to improve productivity. The Food Safety and Standards Authority of India (FSSAI) establishes guidelines for feed ingredient quality and safety. Andhra Pradesh and West Bengal, major aquaculture states, are exploring microalgae to reduce reliance on traditional fishmeal.
Microalgae-Based Aquafeed Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, reflecting varied strategic priorities within the microalgae-based aquafeed market. This landscape features a mix of established ingredient suppliers and specialized biotechnology firms. Strategic archetypes include large-scale ingredient producers, niche formulation experts, and technology providers. Dominant competitive moves involve capacity expansion through advanced cultivation technologies and strategic partnerships to secure market channels.
Fermentation expertise anchors Corbion N.V., a Netherlands-based company, which represents a key player in high-DHA algal oil production. Koninklijke DSM N.V., another Dutch-based entity, exemplifies a diversified nutrition solutions provider with broad market access. Cargill, Incorporated, a US-based agricultural and food conglomerate, occupies a position leveraging its vast global distribution network for feed ingredients.
| Leading Market Players |
|---|
| Corbion N.V. |
| Cellana Inc. |
| Koninklijke DSM N.V. |
| The Archer-Daniels-Midland Company |
| A4F Algae for the Future |
| BioMar Group |
| Cargill, Incorporated |
| Alltech |
| Allmicroalgae |
| Others |
Cost & Logistics Intelligence
Commercial producers' demand for consistent, high-quality feed ingredients drives a contract-based pricing model in the microalgae-based aquafeed market. This ensures stable supply and predictable costs for large-scale aquaculture operations.
Pricing Analysis
Capacity additions in Southeast Asia are reshaping price floors for commodity-grade microalgae ingredients. The dominant pricing model is contract-based long-term offtake for commercial producers. Price differentiation stems from quality grade, particularly DHA content, and certification level, such as EFSA approval. Pricing pressure stems from the increasing competition from alternative lipid sources. Hatcheries exhibit the highest price sensitivity for powdered forms, while specialized broodstock formulations command premium pricing.
Supply Chain Analysis
Single-source vulnerability sits with specialized photobioreactor component manufacturers, impacting production scalability. Geographic supply concentration is evident in the Netherlands for advanced fermentation and in China for high-volume biomass production. Raw material dependencies include specific microalgae strains and energy inputs for cultivation facilities. Commodity price volatility for these energy inputs presents a structural risk. Distribution runs through a network of specialized feed ingredient distributors and direct sales to large aquaculture farms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a late-cycle quality story, driven by the aquaculture industry's shift towards species-specific nutritional requirements for optimal health and growth. This demand for premium specifications reinforces the value proposition of microalgae.
For Market Incumbents: Acquire proprietary algal strain libraries to secure intellectual property and enhance product differentiation. Consolidate production through strategic partnerships with technology providers to scale advanced cultivation facilities. This defends against the threat of generic alternative lipid sources and leverages R&D in high-yield photobioreactors.
For New Entrants and Emerging Players: Agricultural cooperatives represent a penetrable channel for reaching smaller and medium-sized aquaculture farms. Target the broodstock nutrition niche with specialized, high-potency formulations to improve fecundity and larval survival. A go-to-market angle focusing on verifiable sustainability credentials will resonate with ethical procurement standards.
For Investors and Strategic Acquirers: Diversified nutrition solutions providers are the most active acquirer in this space, seeking to expand their sustainable ingredient portfolios. Long-term viability hinges on continued advancements in bioprocessing efficiency and regulatory support for novel feed ingredients. The signal to watch is the widespread adoption of microalgae in mainstream aquaculture species beyond salmon and shrimp.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Scaling production facilities in key aquaculture regions like Southeast Asia meets growing demand. |
| Proprietary Strain Development | Developing novel microalgae strains offers competitive advantages through unique nutritional profiles. |
| Strategic Partnership with Feed Manufacturers | Collaborating with large feed producers ensures broad market access and integration into existing supply chains. |
| Certification Investment | Achieving recognized feed safety and sustainability certifications enhances market credibility and buyer trust. |
| Targeted Broodstock Formulation | Developing high-value feeds for broodstock improves reproductive performance and larval survival rates. |
Research Approach
Coverage spans Europe, North America, and Asia-Pacific, with primary inputs from each region. The analysis combines in-depth interviews with aquaculture farm managers, feed formulators, and biotechnology R&D scientists, validated through extensive secondary research. Secondary sources include FDA filings, EFSA reports, FAO aquaculture statistics, and peer-reviewed academic journals. This approach ensures robust bottom-up and top-down triangulation of market data.
Granularity-level modeling addresses market dynamics across product type, application, end user, distribution channel, and cultivation method. The analytical framework projects growth across the modeling period, with compound annual growth rates derived from historical trends and anticipated industry shifts. Key forecast inputs include global aquaculture production volumes and evolving omega-3 demand trends in animal nutrition.
Revisions become necessary when significant advancements in cultivation technology or unexpected shifts in marine-derived ingredient prices materialize. Forecasts reflect assumptions regarding regulatory stability and sustained investment in sustainable aquafeed alternatives. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aquaculture Innovations
Europe Organic Aquaculture Market
Aquaculture Innovations
Saudi Arabia Aquaculture Market
Aquaculture Innovations
GCC Fish Farming Market
Aquaculture Innovations
Aquaculture Additives Market
Aquaculture Innovations
Fish Oil for Aquafeed Market
Aquaculture Innovations
Aquaculture Feed and Pharmaceuticals Market
Aquaculture Innovations
Global Aquaculture Vaccine Market
Aquaculture Innovations
Bahrain Fisheries and Aquaculture Market
Aquaculture Innovations
Aquaculture Market
Aquaculture Innovations
Aquaculture Healthcare Market
Aquaculture Innovations
Aquaponics Market
Aquaculture Innovations
Aquaculture Pumps Market
Aquaculture Innovations
North America Shrimp Market
Aquaculture Innovations
Japan Aquafeed Market
Aquaculture Innovations
North America Aqua Feed Market
Aquaculture Innovations
China Shrimp Feed Market