
 Vietnam Aquaculture Market | 2026-2036
Vietnam Aquaculture Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Aquaculture Market Intelligence
Multi-source feed procurement is decoupling from traditional single-supplier contracts across Vietnamese aquaculture operations. Minh Phu Seafood Corporation leverages backward integration into hatchery operations to secure broodstock quality. Vinh Hoan Corporation dominates pangasius fillet exports through vertical control of processing plants in the Mekong Delta. Hung Vuong Corporation anchors its position via intensive pond systems and branded retail distribution.
Vietnam aquaculture encompasses the controlled cultivation of finfish, crustaceans, and mollusks in freshwater, brackish, and marine environments using ponds, cages, or recirculating systems, with shrimp and pangasius representing the dominant species by export volume. The sector serves industrial food processing, foodservice channels, and direct export markets, requiring strict adherence to antibiotic residue limits and traceability protocols. Shrimp production leads export value among product types, while recirculating systems represent the fastest-growing technology segment as water scarcity and disease pressure intensify. Food processing channels capture the largest margin pool among end users, whereas direct sales to exporters remain the highest-volume distribution pathway.
Vietnam's Ministry of Agriculture and Rural Development enforces aquaculture facility licensing and environmental monitoring, while the National Agro-Forestry-Fisheries Quality Assurance Department manages export certification and maximum residue limit compliance for EU and US-bound shipments. These frameworks shape capital requirements for pond upgrades and filter technology investments. Stakeholders must monitor evolving EU deforestation regulation traceability mandates and domestic wastewater discharge standards to preserve market access and avoid shipment detention.
Market Dynamics
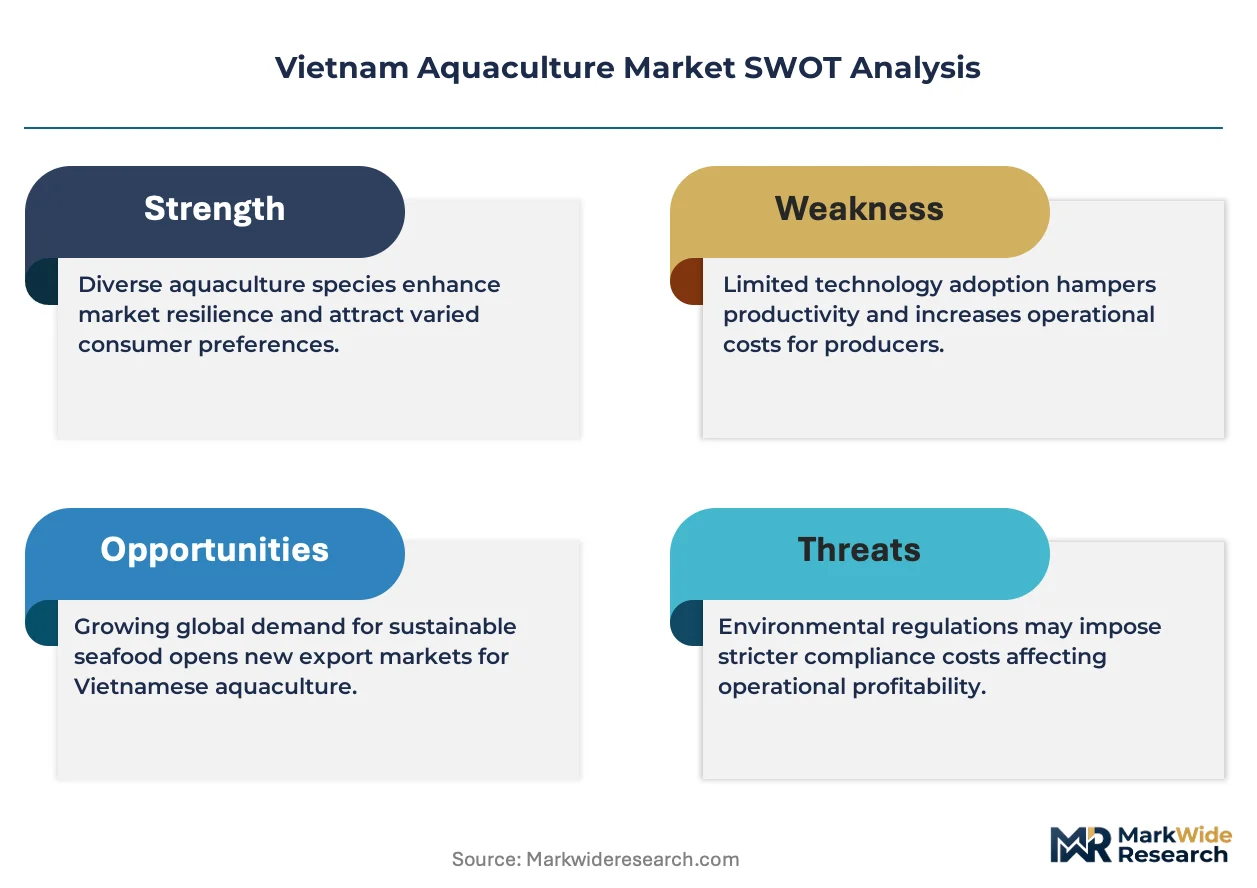
Certification requirements from Vietnam's Ministry of Agriculture and Rural Development are forcing capital reallocation toward wastewater treatment and traceability infrastructure across Mekong Delta operations.
Growth Catalysts
- EU Deforestation Regulation traceability mandates:Vietnamese exporters are retrofitting pond systems with digital tagging to maintain access to European food processing channels.
- Recirculating aquaculture system adoption:Water-scarce provinces are deploying closed-loop filtration to reduce disease pressure and discharge volumes.
- Ca Mau-Soc Trang cluster concentration:Proximity to hatcheries and cold-chain nodes is lowering logistics costs for shrimp producers targeting foodservice exports.
Market Restraints
- Antibiotic residue compliance costs:National Agro-Forestry-Fisheries Quality Assurance Department testing protocols require laboratory infrastructure that smallholder pond operators cannot finance.
- Broodstock import dependency:Domestic hatcheries rely on SPF shrimp seed from Hawaii and Florida suppliers, exposing margins to currency and biosecurity volatility.
- Processing overcapacity in pangasius:Fillet line investments in An Giang and Dong Thap provinces exceed current EU and US quota absorption rates.
Strategic Opportunities
- Central Highlands freshwater expansion:Tilapia and carp producers are establishing pond networks in Lam Dong and Dak Lak provinces outside flood-prone delta zones.
- Domestic retail branded distribution:Supermarket chains in Ho Chi Minh City and Hanoi are creating shelf space for ASC-certified packaged seafood.
- Carbon credit monetization for mangrove-shrimp integration:The Ministry of Agriculture and Rural Development is piloting verified carbon standards for extensive pond systems.
Industry Challenges
- Multi-species disease diagnostics expertise:Early mortality syndrome and white spot syndrome virus detection requires molecular pathology capabilities that provincial extension services lack.
- Legacy pond-to-RAS conversion timelines:Farmers holding 10-year land use certificates face displacement risk during infrastructure upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Aquaculture Market |
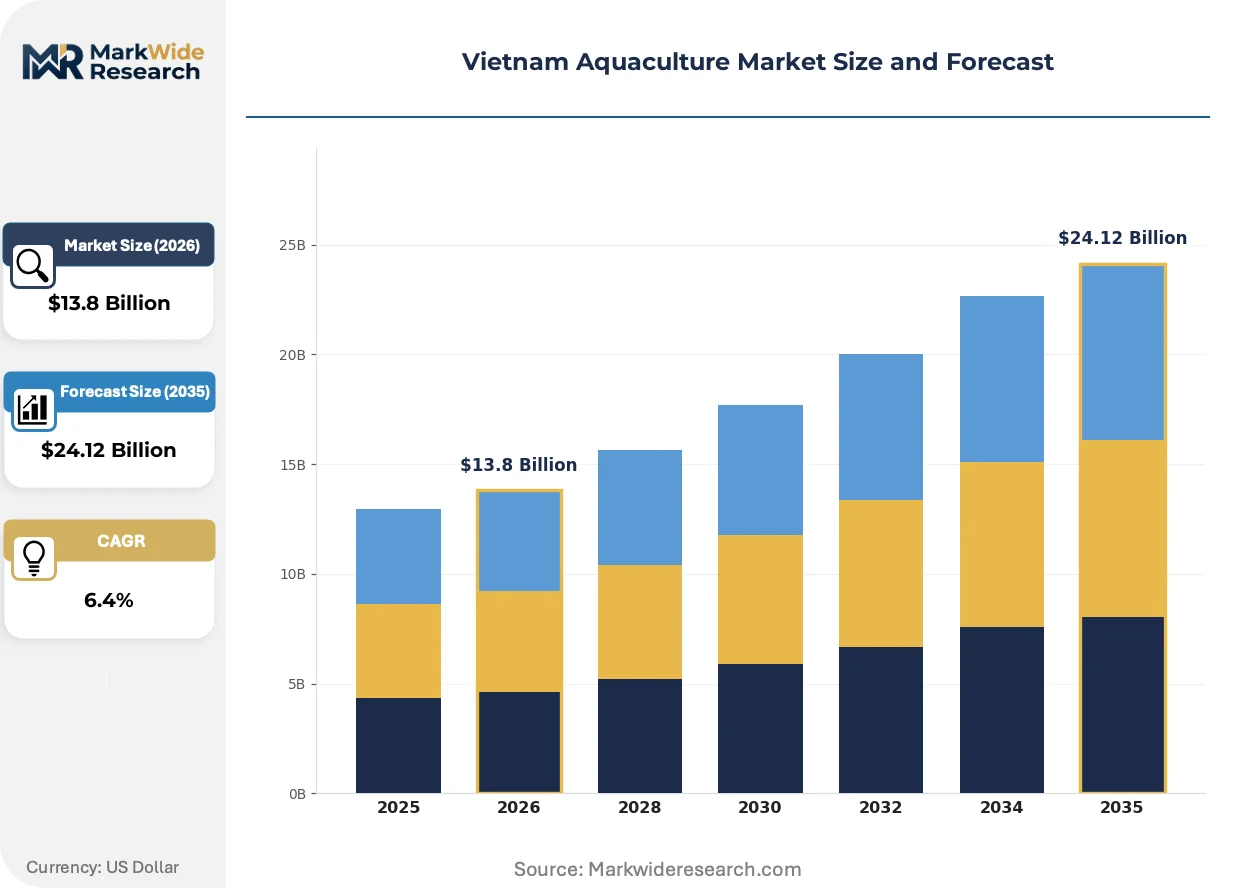
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $24.12 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fish, Shrimp, Mollusks, Crustaceans End User: Exporters, Local Markets, Restaurants, Food Processing Technology: Recirculating Systems, Integrated Multi-Trophic Aquaculture, Cage Culture, Pond Systems Distribution Channel: Direct Sales, Retail Outlets, Online, Wholesale |
| Companies Covered | Hung Vuong Corporation, Dong Nam Seafood, Minh Phu Seafood Corporation, Ngoc Sinh Seafood, Phuong Dong Seafood, Vinh Hoan Corporation, Quoc Viet Seafood, SOC Trang Seafood Joint Stock Company, Ca Mau Seafood Processing & Service Joint Stock Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Aquaculture Market Strategic Shifts & Innovations
Biosecurity automation and alternative protein feed formulations are compressing operating cost structures while regulatory traceability mandates reshape capital deployment priorities across Vietnamese aquaculture.
Automated feeding systems using acoustic sensors and machine vision are converging with cloud-based water quality monitoring platforms. Intensive pond operators in Soc Trang province are deploying these integrated stacks to reduce labor dependency and optimize feed conversion ratios. The technology convergence is compressing break-even timelines for mid-scale farms while raising technical barriers for non-adopters.
Vietnam's National Agro-Forestry-Fisheries Quality Assurance Department has tightened maximum residue limit enforcement for EU-bound shipments. Processing plants in the Mekong Delta are responding by building in-house testing laboratories and rejecting raw material from non-certified pond sources. Smallholder producers without VASEP-supported traceability systems are losing market access to industrial exporters.
Foodservice buyers in Japan and South Korea are demanding lot-level blockchain verification for imported pangasius and shrimp. Exporters are bypassing traditional auction intermediaries to contract directly with certified pond clusters. The disintermediation is most visible in Ca Mau province, where integrated processor-hatchery operations are capturing margin previously allocated to trading houses.
Vietnam Aquaculture Market Segmentation
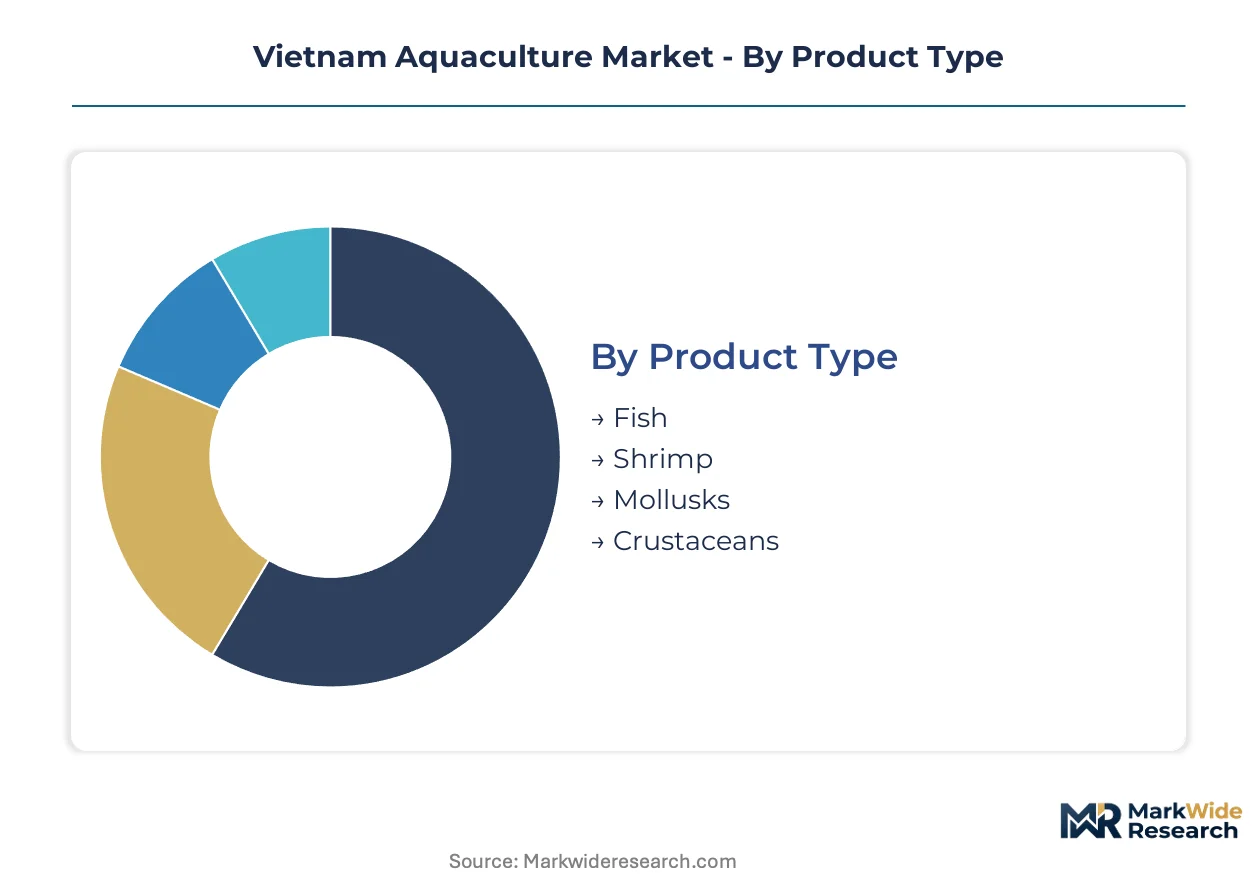
Vietnamese aquaculture producers configure operations around species biology, regulatory compliance tiers, and export certification requirements. Each segmentation axis determines capital intensity, biosecurity protocols, and margin capture potential across Mekong Delta pond clusters and emerging Central Highlands sites.
Product Type:
Standardization dominates fish and pangasius processing for EU quota markets, while shrimp operations customize broodstock sourcing and disease management protocols to buyer specifications.
- Shrimp:Black tiger and whiteleg varieties drive export value through intensive pond systems in Ca Mau and Soc Trang provinces. Foodservice buyers in Japan and South Korea mandate SPF seed traceability and antibiotic-free certification, forcing hatchery backward integration among major processors.
- Fish:Pangasius fillet production concentrates in An Giang and Dong Thap processing corridors with vertical control over pond-to-plate traceability. EU deforestation regulation compliance requires geolocation tagging of all pond sources, raising documentation costs for smallholder suppliers.
- Mollusks:Clam and oyster operations in coastal provinces serve lower-margin domestic food processing channels with minimal certification overhead.
- Crustaceans:Mud crab and freshwater prawn segments supply Ho Chi Minh City restaurant wholesale markets with limited export penetration.
Leading the category by volume: Fish. Growing fastest: Shrimp.
End User:
Margin capture varies sharply across customer types, with exporters demanding full traceability documentation while local markets absorb uncertified production.
- Food Processing:Industrial filleting and value-added product lines in the Mekong Delta require HACCP-certified raw material with batch-level antibiotic testing. Vinh Hoan and Minh Phu operations dominate this channel through captive pond networks and in-house laboratory infrastructure.
- Exporters:Direct shipment to EU, US, and Japanese markets demands National Agro-Forestry-Fisheries Quality Assurance Department certification and blockchain-verified lot tracking. Smallholders without VASEP-supported systems face systematic exclusion from this channel.
- Restaurants:Ho Chi Minh City and Hanoi foodservice operators purchase live or fresh-chilled product through wholesale auction markets with minimal documentation requirements.
- Local Markets:Wet market distribution absorbs pond output that fails export residue testing, creating a price-discounted secondary channel for non-compliant producers.
Highest margin concentration: Food Processing. Steepest expansion trajectory: Exporters.
Technology:
Capital deployment separates automated recirculating installations from labor-intensive extensive systems, with water access and land tenure security driving technology selection.
- Recirculating Systems:Closed-loop filtration with mechanical and biological treatment enables production in water-scarce Central Highlands provinces. Lam Dong tilapia operators deploy these systems to escape Mekong Delta flood risk and disease pressure, though energy costs constrain adoption.
- Pond Systems:Earthen and lined ponds remain the dominant production infrastructure across the Mekong Delta, with 10-year land use certificates creating displacement friction during infrastructure upgrades.
- Cage Culture:Marine and reservoir-based net cage operations concentrate in coastal Khanh Hoa and Phu Yen provinces for high-value finfish species.
- Integrated Multi-Trophic Aquaculture:Mangrove-shrimp polyculture in Ca Mau extensive ponds qualifies for emerging carbon credit verification pilots under Ministry of Agriculture and Rural Development standards.
Widest installed base: Pond Systems. Climbing the fastest: Recirculating Systems.
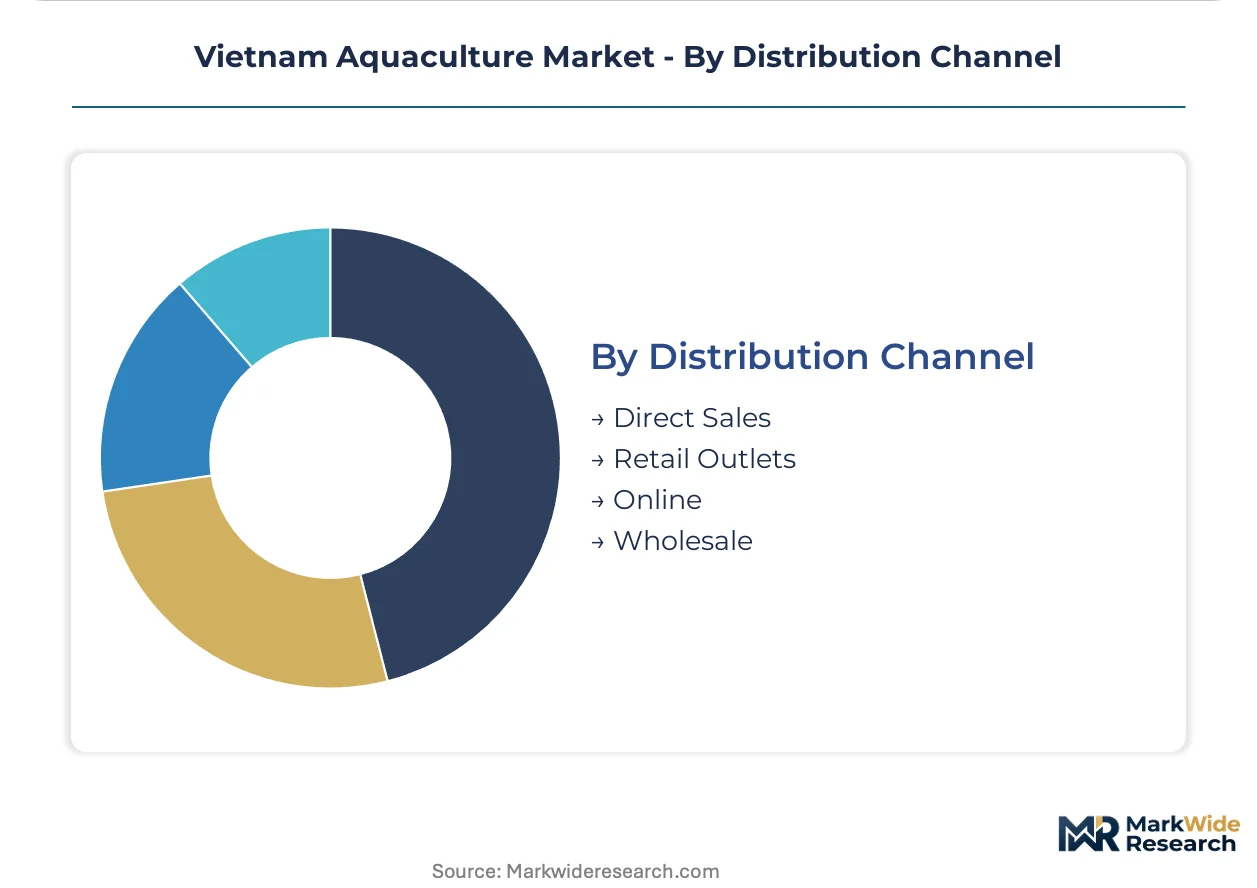
Distribution Channel:
Channel selection determines working capital requirements and price realization, with direct sales to integrated processors displacing traditional auction intermediaries.
- Direct Sales:Contract farming arrangements with Minh Phu, Vinh Hoan, and Hung Vuong processing plants provide price certainty and technical extension support. Blockchain-enabled lot tracking satisfies EU and Japanese foodservice traceability mandates.
- Wholesale:Traditional trading houses in Ca Mau and Soc Trang aggregate smallholder production for auction to export-oriented processors, capturing margin that integrated operations now internalize.
- Retail Outlets:Supermarket chains in Hanoi and Ho Chi Minh City are creating dedicated shelf space for ASC-certified packaged seafood, bypassing wet market intermediation.
- Online:E-commerce platforms serve urban consumer direct delivery of live product with limited current penetration in aquaculture compared to other protein categories.
Largest volume flow: Direct Sales. Gaining share fastest: Retail Outlets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for Vietnamese aquaculture concentrates in the Mekong Delta provinces, where pond systems and shrimp hatcheries cluster around Ca Mau and Soc Trang. Cold-chain logistics improvements are enabling Southeast Asian seafood exporters to expand procurement from these production zones.
Mekong Delta
Shrimp and pangasius production dominates export volume through intensive pond systems in Ca Mau and Soc Trang provinces. The Ministry of Agriculture and Rural Development enforces facility licensing and environmental monitoring that shapes capital requirements for pond upgrades. Processing corridors in An Giang and Dong Thap provinces concentrate fillet line investments for EU and US quota markets.
Southeast Coast
Marine cage culture for high-value finfish species concentrates in Khanh Hoa and Phu Yen provinces. The National Agro-Forestry-Fisheries Quality Assurance Department manages export certification and maximum residue limit compliance for shipments bound to Japan and South Korea. Coastal clam and oyster operations serve domestic food processing channels with minimal certification overhead.
Central Highlands
Tilapia and carp producers are establishing pond networks in Lam Dong and Dak Lak provinces outside flood-prone delta zones. Water-scarce conditions are accelerating recirculating aquaculture system adoption with closed-loop filtration technology. These installations enable production escape from Mekong Delta disease pressure and seasonal flooding risks.
Southeast Region
Ho Chi Minh City anchors domestic retail demand through supermarket chains creating shelf space for ASC-certified packaged seafood. The city's foodservice operators purchase live or fresh-chilled product through wholesale auction markets. Urban consumer direct delivery platforms serve limited aquaculture penetration compared to other protein categories.
Vietnam Aquaculture Market Key Industry Players
Backward integration into hatchery operations dominates the current landscape as processors secure broodstock quality and traceability compliance. The market structures around vertically integrated corporations controlling captive pond networks alongside fragmented smallholder suppliers. Three archetypes prevail: integrated processor-hatchery operations, mid-scale intensive pond specialists, and export-oriented trading houses. Capacity expansion in fillet processing and strategic partnerships for cold-chain logistics represent the dominant competitive moves.
Among integrated processor-hatchery operators, Minh Phu Seafood Corporation, Vinh Hoan Corporation, and Hung Vuong Corporation exemplify the archetype of vertical control over production inputs. These entities occupy positions defined by captive supply of certified raw material and in-house laboratory infrastructure for residue testing. Their market presence anchors the premium tier of export certification compliance, while smaller trading houses aggregate non-captive pond output for secondary channels.
| Leading Market Players |
|---|
| Hung Vuong Corporation |
| Dong Nam Seafood |
| Minh Phu Seafood Corporation |
| Ngoc Sinh Seafood |
| Phuong Dong Seafood |
| Vinh Hoan Corporation |
| Quoc Viet Seafood |
| SOC Trang Seafood Joint Stock Company |
| Ca Mau Seafood Processing & Service Joint Stock Corporation |
| Others |
Cost & Logistics Intelligence
Shrimp hatchery technician concentrations across Ca Mau and Soc Trang provinces create labor-cost differentials that widen spreads between premium certified and uncertified pond output tiers. Pond operators with in-house SPF broodstock capabilities command pricing premiums against smallholders dependent on imported seed subject to currency volatility.
Pricing Analysis
Certification-bundled pricing separates ASC-certified export lots from domestic wet-market grades with traceability documentation unbundled as a surcharge item. Three-tier pricing structure across premium, standard, and economy levels reflects EU deforestation regulation compliance status, antibiotic residue testing depth, and cold-chain integrity guarantees. Pricing pressure stems from processing overcapacity in An Giang and Dong Thap fillet corridors exceeding quota absorption rates. Smallholder pond operators without VASEP-supported traceability systems exhibit highest price sensitivity while integrated processor-hatchery operations capture margin through captive supply networks.
Supply Chain Analysis
Single-source vulnerability sits with Hawaii and Florida SPF shrimp seed suppliers exposing domestic hatcheries to biosecurity and currency risks. Broodstock import dependency draws from United States suppliers while pangasius fingerling sourcing rests on Mekong Delta hatchery clusters. Supply chain risk centers on antibiotic residue testing failures triggering National Agro-Forestry-Fisheries Quality Assurance Department shipment detention. Distribution runs through direct contract farming arrangements with Minh Phu, Vinh Hoan, and Hung Vuong processing plants displacing traditional Ca Mau and Soc Trang trading house intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnamese aquaculture sits in a technology-transition phase where recirculating aquaculture system deployment displaces legacy earthen pond infrastructure across water-scarce provinces.
For Market Incumbents: Cement market position through backward integration into hatchery operations securing SPF broodstock quality and traceability compliance against emerging mid-scale RAS specialists. Expand laboratory infrastructure for antibiotic residue testing to preempt National Agro-Forestry-Fisheries Quality Assurance Department enforcement tightening. Prioritize cold-chain node investments in Ca Mau and Soc Trang corridors to capture logistics margin from fragmented smallholder aggregation. For New Entrants and Emerging Players: EU Deforestation Regulation traceability mandates in European markets open a window for digital tagging and blockchain verification service providers targeting non-integrated pond clusters. White-space concentration sits with Central Highlands recirculating system installation for tilapia and carp production outside flood-prone delta zones. Penetrate through technical extension partnerships offering water quality monitoring platforms to Lam Dong and Dak Lak operators escaping Mekong Delta disease pressure. For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale intensive pond specialists possessing captive hatchery capacity and ASC certification given accelerating EU and Japanese foodservice traceability mandates. Long-term viability favors operators with demonstrated molecular pathology capabilities for early mortality syndrome and white spot syndrome virus detection. Monitor Ministry of Agriculture and Rural Development carbon credit verification pilots for mangrove-shrimp integration as inflection signal for extensive pond system valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Hatchery Backward Integration | Captive SPF broodstock supply secures traceability compliance for EU-bound shrimp exports. |
| RAS Technology Deployment | Closed-loop filtration enables production escape from Mekong Delta seasonal flooding risks. |
| Blockchain Traceability Implementation | Digital lot verification satisfies Japanese and South Korean foodservice buyer mandates. |
| Carbon Credit Verification Pilot | Ministry of Agriculture and Rural Development standards create new revenue streams for mangrove-shrimp operations. |
| In-House Laboratory Infrastructure | Antibiotic residue testing capabilities preempt National Agro-Forestry-Fisheries Quality Assurance Department shipment detention. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs alongside primary interviews with hatchery managers, processing plant quality directors, provincial extension officers, and cold-chain logistics operators. Vietnam Association of Seafood Exporters and Producers reports, National Agro-Forestry-Fisheries Quality Assurance Department certification databases, and Mekong Delta provincial agricultural statistics provided demand-side validation. Bottom-up pond production estimates and top-down export value reconciliation ensured cross-verification across data streams.
Production volume and export value outputs reconciled trade statistics, facility licensing records, and processor capacity disclosures across the modeling period. Segmentation dimensions modeled included species type, technology tier, end-user channel, and provincial production cluster. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and technology adoption S-curves. SPF seed import volumes, EU quota utilization rates, and RAS energy cost curves informed forecast sensitivity testing.
The model assumes a particular technology adoption path; alternative pathways for recirculating aquaculture system diffusion would alter the outlook if energy cost structures shift or land tenure security deteriorates. Forecasts reflect assumptions around EU deforestation regulation enforcement timing and Ministry of Agriculture and Rural Development wastewater standard implementation. Disease outbreak severity, currency volatility affecting broodstock imports, and cold-chain infrastructure buildout pace constitute revision risks. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aquaculture Innovations
Ornamental Fish Market
Aquaculture Innovations
Fish Oil for Aquafeed Market
Aquaculture Innovations
Hatchery Product Market
Aquaculture Innovations
North America Aqua Feed Market
Aquaculture Innovations
Qatar Fisheries and Aquaculture Market
Aquaculture Innovations
Smart Aquaculture Systems Market
Aquaculture Innovations
Aquaculture Additives Market
Aquaculture Innovations
United Arab Emirates Fisheries and Aquaculture Market
Aquaculture Innovations
South America Aqua Feed Market
Aquaculture Innovations
South Korea Aquaculture Market
Aquaculture Innovations
Tilapia Market
Aquaculture Innovations
Aquaculture Cage Market
Aquaculture Innovations
United States Ornamental Fish Market
Aquaculture Innovations
Oman Aquaculture Market
Aquaculture Innovations
Seaweed Cultivation Market
Aquaculture Innovations
Global Plant Based Fish Feed Market