
 Alfalfa Protein Concentrate Market | 2026-2036
Alfalfa Protein Concentrate Market Size, Share, and Industry Trends Forecast 2026-2036
Alfalfa Protein Concentrate Market Outlook
The gap between pharmaceutical-grade alfalfa protein isolate and commodity feed-grade concentrate is expanding as buyers impose stricter amino acid profiles and heavy metal thresholds. Bioriginal Food & Science Corporation leverages its North American extraction infrastructure to supply nutraceutical clients with certified organic grades. Desialis SAS anchors European supply through its French cultivation base and specialized dehydration protocols. Xi'an Tianrui Biotech Co., Ltd. dominates Asian distribution by controlling regional distributor networks and customizing flake specifications for local feed compounders.
Alfalfa protein concentrate is a dehydrated, partially defatted green leaf protein product typically containing 40-55% crude protein by dry weight, obtained through mechanical pressing, solvent extraction, or aqueous separation of Medicago sativa foliage, primarily serving as a functional protein source in formulated animal diets and human supplement matrices. Powder formats lead value capture in dietary supplements and nutraceuticals due to superior solubility and dosing precision, while granules sustain margin pools in ruminant feed applications where pelleting compatibility determines procurement decisions. Aquaculture end users represent the fastest-expanding demand pool as shrimp and finfish producers substitute fishmeal with plant protein to meet sustainability audit requirements.
FDA feed ingredient guidelines, EU REACH chemical safety registrations, and China's GB standards for feed additives collectively shape product specifications, testing burdens, and cross-border market access for concentrate suppliers. The EU Green Deal's protein autonomy targets are redirecting agricultural subsidies toward domestic legume cultivation, indirectly pressuring imported alfalfa pricing. Stakeholders must monitor how divergent mycotoxin limits across jurisdictions fragment certification requirements and influence sourcing geography decisions.
Market Dynamics
The alfalfa protein concentrate market pivots on the divergence between pharmaceutical-grade isolate specifications and commodity feed-grade tolerances, with buyers enforcing stricter amino acid completeness and heavy metal ceilings that split supplier capabilities into two irreconcilable tiers.
Growth Catalysts
- EU Green Deal protein autonomy targets:Agricultural subsidies redirect toward domestic legume cultivation, creating captive demand for alfalfa-derived inputs within European compound feed manufacturing.
- Aquaculture sustainability audits:Shrimp and finfish producers face third-party certification requirements that mandate fishmeal displacement, accelerating plant protein concentrate uptake.
- Aqueous separation technology:Advanced mechanical pressing methods reduce solvent residues below detectable thresholds, unlocking nutraceutical-grade output from standard cultivation batches.
Market Restraints
- Input cost volatility:Alfalfa hay pricing fluctuates with drought cycles in California's Central Valley and Argentina's Córdoba province, compressing processor margins without pass-through mechanisms.
- Supply concentration risk:French dehydration infrastructure controls European pharmaceutical-grade flake output, creating single-point vulnerability for certified organic supply chains.
- Regulatory friction:China's GB standards for feed additives impose mycotoxin limits stricter than Codex Alimentarius, forcing dual certification runs for exporters serving multiple jurisdictions.
Strategic Opportunities
- Underpenetrated human nutrition:Sports nutrition formulators in Germany and the Netherlands trial alfalfa isolate for vegan protein fortification, representing white space beyond traditional animal feed channels.
- Regulatory tailwind:India's PLI scheme for food processing incentivizes domestic protein concentrate manufacturing, reducing import dependency for its expanding poultry sector.
- Technology convergence:Integration of near-infrared spectroscopy with automated pressing lines enables real-time protein content adjustment, differentiating output for premium versus standard tiers without batch segregation.
Industry Challenges
- Specialized extraction talent scarcity:Operators capable of managing solvent recovery systems while maintaining organic certification traceability command wage premiums that erode facility economics.
- Capex intensity:Pharmaceutical-grade isolation requires stainless steel membrane filtration arrays and cleanroom packaging suites that demand seven-figure capital commitments per production line.
- Certification timeline compression:REACH registration updates and evolving FDA Generally Recognized as Safe determinations force simultaneous compliance sprints across multiple regulatory frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alfalfa Protein Concentrate Market |
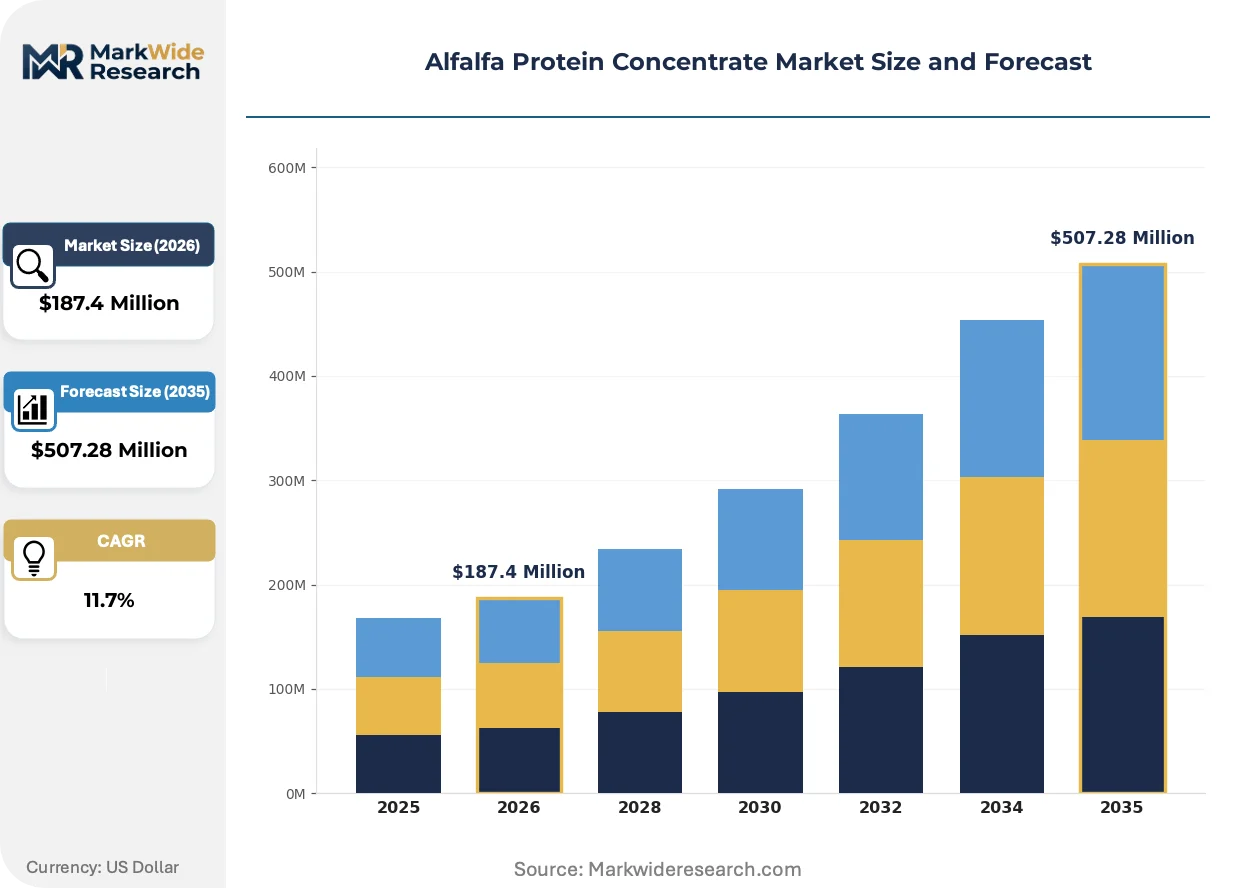
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Flakes, Concentrate Application: Animal Feed, Dietary Supplements, Food Additives, Nutraceuticals End User: Poultry, Ruminants, Aquaculture, Pet Food Distribution Channel: Online Retail, Offline Retail, Distributors, Direct Sales |
| Companies Covered | Bioriginal Food & Science Corporation, Swanson Vitamins, Desialis SAS, Alfalfas Sat Ansó, Conduzioni Aziende Agricole Forte, Hindustan Animal Feeds, Xi'an Tianrui Biotech Co., Ltd., Acetar Biotech, Unan Nutramax Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alfalfa Protein Concentrate Market Strategic Shifts
Processing technology and procurement logic are restructuring competitive position in alfalfa protein concentrate, with automation and certification protocols replacing scale as the primary margin determinant.
Membrane filtration coupled with pulsed electric field pre-treatment is electrifying protein recovery rates from alfalfa foliage, pushing yields past conventional solvent extraction ceilings. Dutch feed compounders and Danish aquafeed manufacturers are retrofitting intake specifications to accommodate this higher-purity output. The technology is compressing the viable supplier base to processors capable of capital-intensive equipment upgrades.
REACH chemical safety registrations in Europe now mandate expanded substance dossiers for protein concentrates entering nutraceutical channels, extending approval timelines by twelve to eighteen months. German and French ingredient distributors are pre-qualifying suppliers based on existing registration depth rather than price positioning. Pharmaceutical-grade concentrate categories face the heaviest documentation burden, accelerating consolidation among registrant-holding processors.
Compound feed manufacturers are consolidating supplier rosters around vertically integrated alfalfa processors capable of certifying cultivation-to-flake traceability. Large poultry integrators in Spain and Italy now require batch-level mycotoxin documentation that spot-market traders cannot provide. This behavioral shift is most pronounced in Mediterranean markets where retail meat buyers enforce farm-to-fork transparency mandates.
Alfalfa Protein Concentrate Market Segmentation
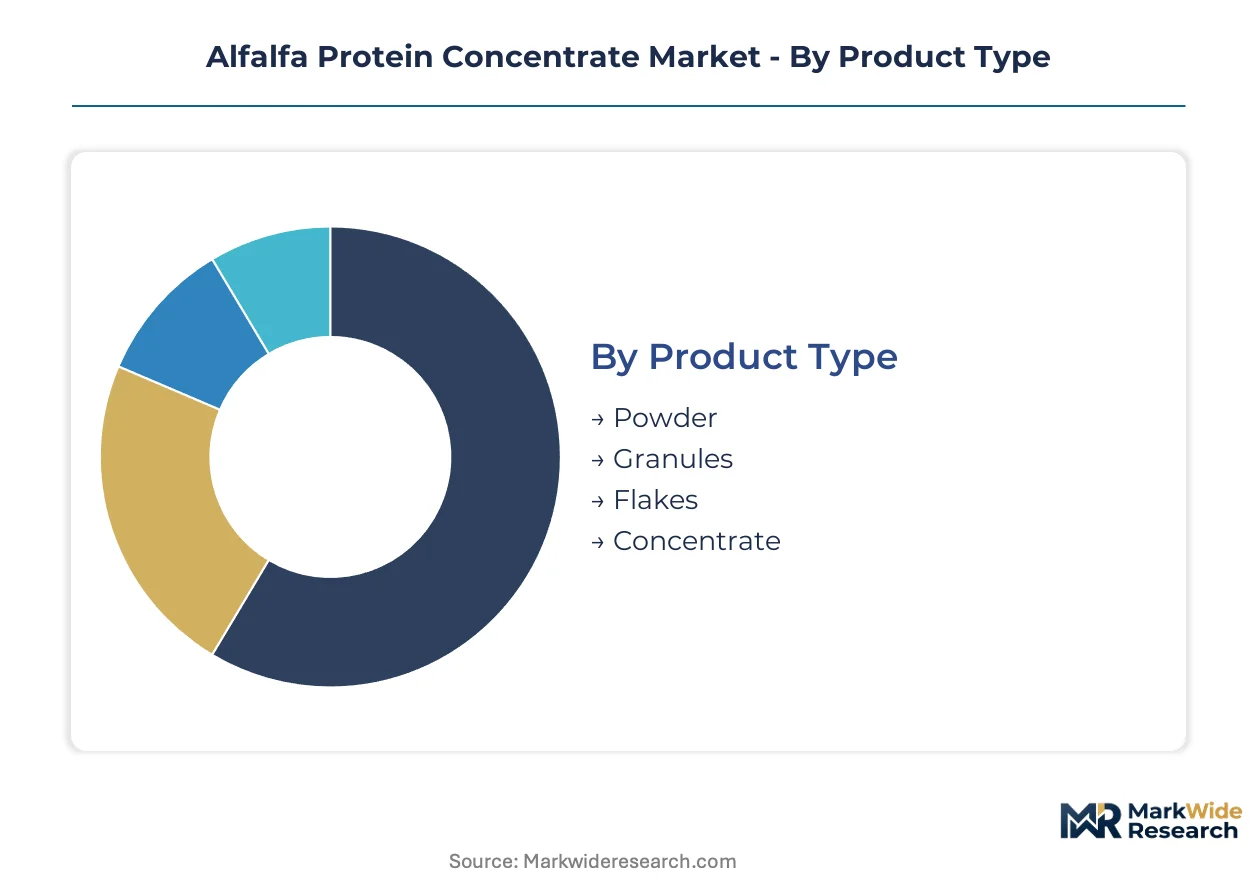
Segmentation in alfalfa protein concentrate reveals how capital deployment and regulatory compliance requirements fragment supplier capabilities across distinct commercial tiers. Buyers in pharmaceutical-grade channels impose specifications that commodity processors cannot meet without seven-figure equipment upgrades.
Product Type:
Capital intensity escalates sharply from mechanical dehydration through membrane filtration isolation, splitting the supplier base between feed-grade commodity producers and nutraceutical-grade specialists.
- Powder:Spray-dried particulate below 200 mesh delivers superior solubility for sports nutrition and clinical supplement formulations. German and Dutch formulators drive procurement of certified organic powder grades to meet EU Green Deal protein autonomy targets.
- Granules:Agglomerated particles sized for pelleting compatibility in compound feed manufacturing. Spanish and Italian poultry integrators specify granule formats with batch-level mycotoxin documentation that spot-market traders cannot provide.
- Flakes:Rolled dehydrated product retains structural integrity in ruminant ration mixing. French dehydration infrastructure dominates European pharmaceutical-grade flake output.
- Concentrate:Partially defatted intermediate requiring further processing before end-use application. Chinese aquafeed manufacturers source concentrate for in-house protein standardization.
Granules absorb the bulk of installed capacity; powder is expanding most quickly.
Application:
Regulatory burden and certification depth determine margin capture, with human nutrition channels demanding documentation that feed applications escape.
- Animal Feed:Formulated protein source for compound ration manufacturing. Shrimp and finfish producers in China substitute fishmeal with plant protein to meet sustainability audit requirements.
- Dietary Supplements:Human consumption-grade isolate with amino acid profile verification. Sports nutrition formulators in Germany trial alfalfa isolate for vegan protein fortification.
- Food Additives:Functional ingredient for texture and protein enrichment in processed foods. REACH chemical safety registrations mandate expanded substance dossiers extending approval timelines.
- Nutraceuticals:Pharmaceutical-grade isolate for therapeutic and preventive health applications. FDA Generally Recognized as Safe determinations and EMA guidance shape product specifications.
Animal Feed commands the largest revenue pool; Dietary Supplements is climbing the fastest.
End User:
Volume scale and specification stringency create divergent procurement patterns across livestock categories.
- Poultry:Broiler and layer operations in Spain and Italy require traceable cultivation-to-flake supply chains. Retail meat buyer transparency mandates enforce farm-to-fork documentation.
- Ruminants:Cattle and dairy operations sustain demand for flake and granule formats where pelleting compatibility determines procurement decisions.
- Aquaculture:Shrimp and finfish producers represent the steepest expansion trajectory as third-party certification requirements mandate fishmeal displacement.
- Pet Food:Premium companion animal formulations in North American and European markets absorb certified organic powder grades.
Poultry channels dominate current offtake; Aquaculture is gaining share fastest.
Distribution Channel:
Relationship depth and technical service capabilities separate channels serving specification-intensive buyers from price-sensitive commodity purchasers.
- Online Retail:E-commerce platforms serving small-scale supplement manufacturers and direct-to-consumer brands. Xi'an Tianrui Biotech controls Asian distribution through regional distributor networks.
- Offline Retail:Physical trading of commodity grades through agricultural supply cooperatives. Drought cycles in California's Central Valley compress processor margins without pass-through mechanisms.
- Distributors:Specialized ingredient distributors pre-qualifying suppliers based on existing registration depth rather than price positioning. German and French distributors face heaviest documentation burden for pharmaceutical-grade categories.
- Direct Sales:Long-term supply agreements between vertically integrated processors and large poultry integrators or aquafeed manufacturers. India's PLI scheme for food processing incentivizes domestic manufacturing reducing import dependency.
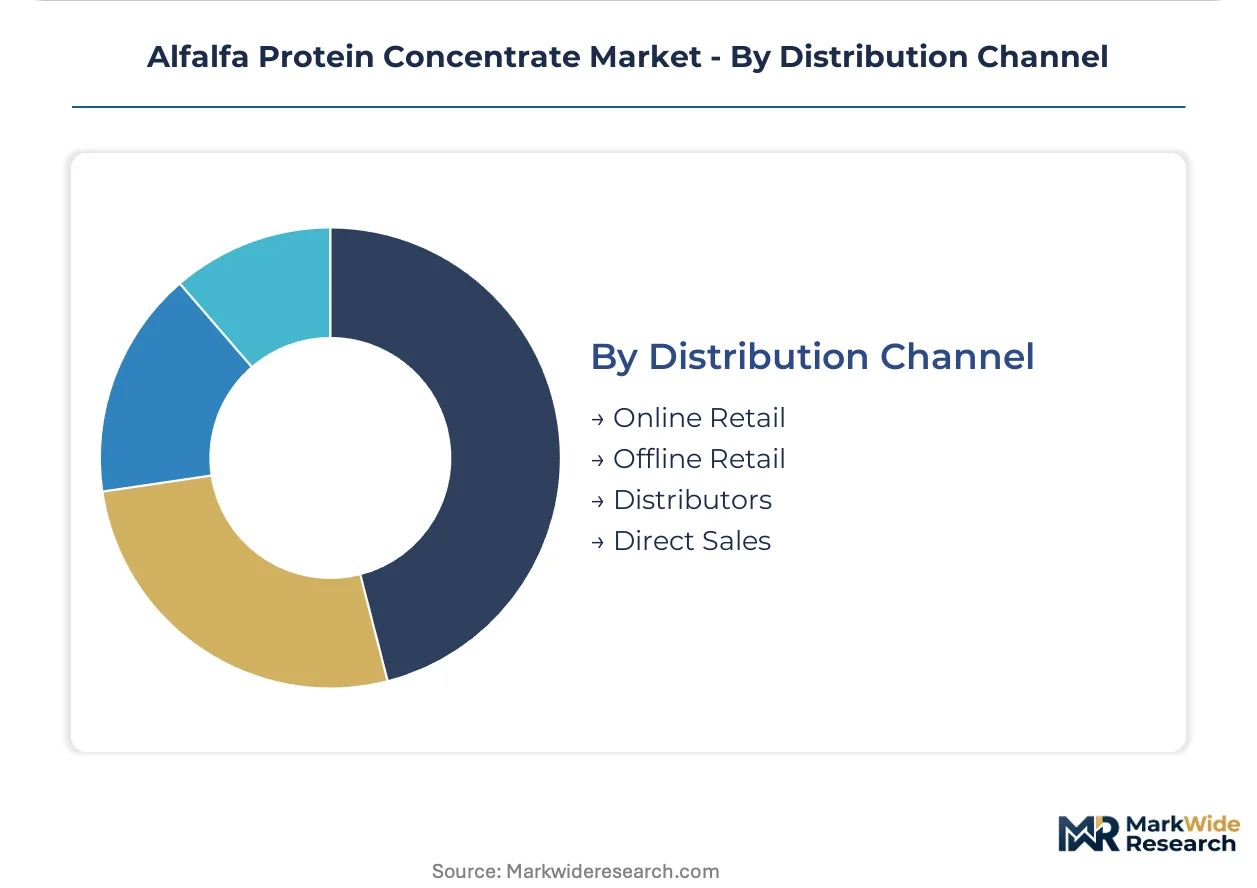
Distributors handle the majority of pharmaceutical-grade volume; Direct Sales is expanding most quickly among large integrators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Córdoba province anchors South American alfalfa cultivation, while California's Central Valley dehydration clusters and France's Loire Valley processing infrastructure command premium-grade flake output for nutraceutical channels.
United States
California's Central Valley hosts the densest concentration of dehydration facilities serving North American feed compounders. FDA feed ingredient guidelines impose evolving purity thresholds that processors must track through batch documentation. Drought cycles in Imperial County and Fresno County compress hay input availability without corresponding price pass-through mechanisms.
China
Shandong and Henan provinces scale domestic protein concentrate manufacturing to reduce import dependency for aquafeed and poultry sectors. GB standards for feed additives mandate mycotoxin limits stricter than Codex Alimentarius, forcing exporters into dual certification runs. Qingdao and Yantai port clusters concentrate inbound alfalfa processing for shrimp and finfish producers facing sustainability audit requirements.
France
Loire Valley and Picardy cultivation bases supply Desialis SAS with traceable organic biomass for pharmaceutical-grade flake production. REACH chemical safety registrations extend approval timelines for nutraceutical-grade concentrate entering European channels. Roquette and Lille industrial corridors anchor specialized dehydration protocols that control European certified organic supply chains.
India
Haryana and Punjab states sustain ruminant feed demand through regional trading networks of commodity-grade granules. The PLI scheme for food processing incentivizes domestic protein concentrate manufacturing capacity for poultry sector expansion. Mumbai and Delhi-NCR distribution hubs consolidate procurement for compound feed manufacturers seeking import substitution.
Germany
Bavaria and Lower Saxony host sports nutrition formulators trialing alfalfa isolate for vegan protein fortification in dietary supplements. EU Green Deal protein autonomy targets redirect agricultural subsidies toward domestic legume cultivation, creating captive demand. Hamburg and Bremen ports handle inbound concentrate flows for aquafeed manufacturers retrofitting specifications to accommodate higher-purity aqueous separation output.
Alfalfa Protein Concentrate Market Competitive Environment
Capital-heavy producers compete with asset-light distributors across tiered capability levels. The supplier base fragments between stainless steel membrane filtration operators and mechanical dehydration commodity processors. Three archetypes dominate: vertically integrated cultivation-to-flake processors, specialized nutraceutical-grade isolators, and regional trading distributors. Competitive moves concentrate on backward integration into captive alfalfa cultivation and pre-qualification around registration depth for REACH-compliant channels.
Within the North American extraction infrastructure tier, Bioriginal Food & Science Corporation occupies a position exemplifying certified organic grade supply to nutraceutical clients. Xi'an Tianrui Biotech Co., Ltd. anchors Asian distribution archetypes through regional network control and local specification customization. Desialis SAS represents the European pharmaceutical-grade specialist model, with French cultivation base traceability supporting dehydration protocol differentiation.
| Leading Market Players |
|---|
| Bioriginal Food & Science Corporation |
| Swanson Vitamins |
| Desialis SAS |
| Alfalfas Sat Ansó |
| Conduzioni Aziende Agricole Forte |
| Hindustan Animal Feeds |
| Xi'an Tianrui Biotech Co., Ltd. |
| Acetar Biotech |
| Unan Nutramax Inc |
| Others |
Value Chain & Pricing Dynamics
Pharmaceutical-grade isolate specifications diverge from commodity feed-grade tolerances through certification depth and amino acid completeness, compressing margins for mechanical dehydration operators while membrane filtration specialists capture sustained premiums. This bifurcation concentrates pricing power with French and North American processors holding REACH registrations and FDA Generally Recognized as Safe dossiers.
Pricing Analysis
Yield-based pricing anchors contract negotiations, with aquafeed manufacturers paying premiums for protein concentrates demonstrating fishmeal displacement ratios in shrimp and finfish trials. Price differentiation separates certified organic grades from conventional feed-grade output, while drought-induced hay cost volatility in California and Argentina squeezes processor margins without contractual pass-through mechanisms. Cost compression in commodity granules is intensifying because poultry integrators consolidate supplier rosters around traceable batch documentation. Feed compounders in Mediterranean markets exhibit highest price sensitivity; nutraceutical distributors in Germany and the Netherlands show lowest sensitivity given registration depth requirements.
Supply Chain Analysis
Organic certification traceability requirements create reverse-logistics complexity, with processors maintaining cultivation-to-flake documentation through dehydration, pressing, and packaging stages. Supply concentrates in France, the United States, and China, with Loire Valley infrastructure controlling European pharmaceutical-grade flake output. Raw material dependencies center on alfalfa hay from California's Central Valley, Argentina's Córdoba province, and Shandong cultivation bases. Single-source vulnerability in French dehydration capacity threatens certified organic supply chains. Distribution runs through specialized ingredient distributors pre-qualifying suppliers on registration depth rather than price positioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into captive alfalfa cultivation is accelerating as processors secure hay supply against drought volatility and traceability mandates. Players are pursuing upstream control over dehydration infrastructure to defend margin pools.
For Market Incumbents: Extend membrane filtration capacity in France and North America to isolate pharmaceutical-grade output from commodity competition. Consolidate supplier rosters around vertically integrated processors capable of batch-level mycotoxin documentation that spot-market traders cannot provide. Invest in REACH registration depth to pre-qualify for German and French nutraceutical distributor networks. Capacity addition in Loire Valley and California dehydration clusters reinforces position against aqueous separation technology entrants. For New Entrants and Emerging Players: India's PLI scheme for food processing opens a window for domestic protein concentrate manufacturing targeting poultry sector import substitution. White-space targets include sports nutrition formulators in Germany and the Netherlands trialing alfalfa isolate for vegan protein fortification. The most penetrable segment is human nutrition channels beyond traditional animal feed applications. A go-to-market angle through direct sales agreements with large aquafeed manufacturers retrofitting specifications for higher-purity aqueous separation output accelerates initial offtake. For Investors and Strategic Acquirers: Re-rating potential sits with stainless steel membrane filtration operators given EU Green Deal protein autonomy targets redirecting agricultural subsidies toward domestic legume cultivation. Long-term viability over a five-to-ten year window favors processors combining aqueous separation technology with captive organic certification traceability. Acquisition target archetype: mid-cap European or North American processors with existing REACH registrations and underutilized cleanroom packaging capacity. Monitor India's PLI scheme disbursement velocity and aquaculture sustainability audit mandate adoption rates as inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Cultivation | Secures hay supply against California and Argentina drought cycles while satisfying traceability mandates. |
| Membrane Filtration Capacity Expansion | Unlocks pharmaceutical-grade isolate output from standard cultivation batches through aqueous separation technology. |
| REACH Registration Depth Investment | Pre-qualifies processors for German and French nutraceutical distributor networks extending approval timelines. |
| Direct Sales Agreement Structuring | Bypasses commodity spot markets through long-term supply contracts with Spanish and Italian poultry integrators. |
| Sustainability Certification Program | Enables fishmeal displacement claims for aquafeed manufacturers facing third-party audit requirements. |
Study Parameters
Independent corroboration across primary interviews with alfalfa processors, feed compounder procurement leads, and nutraceutical ingredient distributors underwrites the qualitative findings. Secondary validation draws from FDA Generally Recognized as Safe determinations, ECHA REACH registration databases, and China's GB standards documentation for feed additives. Bottom-up triangulation against customs and trade data for alfalfa concentrate flows through Qingdao and Yantai port clusters combines with top-down market sizing across powder, granule, flake, and concentrate product categories.
Comparable-period anchoring to historical cultivation cycles and dehydration capacity utilization rates structures the projection framework. Segmentation dimensions modeled include product format, application channel, end-user livestock category, and distribution mechanism. CAGRs derive from protein autonomy policy trajectories, aquaculture sustainability audit adoption curves, and aqueous separation technology penetration assumptions. Industry-specific forecast inputs center on drought frequency in California's Central Valley and EU Green Deal subsidy redirection timelines.
Caveats apply where regulatory friction across FDA, REACH, and GB standards frameworks could materially shift the outlook. Forecasts reflect assumptions regarding membrane filtration yield improvements and alfalfa hay price pass-through mechanics. Practitioners should monitor India's PLI scheme implementation velocity and mycotoxin limit harmonization negotiations for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
United Kingdom Compound Feed Market
Agriculture and Agri Products
Marine Algae Market
Agriculture and Agri Products
Mexico Compound Feed Market
Agriculture and Agri Products
Brazil Rice Market
Agriculture and Agri Products
Seaweed Algae Market
Agriculture and Agri Products
Flower Pot Market
Agriculture and Agri Products
Swine Feed Premix Market
Agriculture and Agri Products
France Animal Protein Market
Agriculture and Agri Products
Slippery Elm Market
Agriculture and Agri Products
Coir Market
Agriculture and Agri Products
Asia-Pacific Swine Feed Market
Agriculture and Agri Products
Saudi Arabia Agriculture Market
Agriculture and Agri Products
Europe Eggs Market
Agriculture and Agri Products
Africa Cashew Market
Agriculture and Agri Products
Japan Compound Feed Market
Agriculture and Agri Products
Egypt Compound Feed Market