
 Hatchery Product Market | 2026-2036
Hatchery Product Market Size, Share, and Industry Trends Forecast 2026-2036
Hatchery Product Market Analytics
A capital-intensity divergence between single-stage and multi-stage incubation system providers is bifurcating competitive dynamics across the hatchery product landscape. Pas Reform Hatchery Technologies leverages advanced climate-control engineering to dominate premium automated installations in Western Europe. Big Dutchman International GmbH anchors its position through integrated feeding and ventilation systems that reduce operational complexity for large-scale operators. Aviagen Group specializes in genetic stock supply, competing on biosecurity protocols rather than equipment hardware.
Hatchery products encompass incubation equipment, climate systems, feeding infrastructure, and genetic stock used to produce day-old chicks for commercial meat and egg production, with modern single-stage incubators maintaining temperature precision within 0.1°C and humidity within 2% relative humidity to optimize embryonic development. The primary commercial purpose centers on maximizing hatchability rates while minimizing mortality and ensuring uniform chick quality for downstream broiler and layer operations. Eggs and chicks represent the core revenue pool where biological asset value concentrates, while hatchery management services are expanding fastest as operators outsource technical expertise to offset skilled labor shortages. Poultry farmers and commercial hatcheries constitute the dominant end-user base, though research institutions command premium pricing for specialized genetic lines.
EU F-Gas Regulation and REACH compliance requirements are elevating equipment standards for refrigerants and material safety in European hatchery operations, while FDA biosecurity guidelines and USDA-APHIS interstate movement regulations govern disease control and genetic stock certification in the United States. India's BIS certification and CDSCO veterinary health standards shape import protocols for foreign breeding stock and incubation technology. Stakeholders must monitor how evolving carbon-footprint disclosure rules under CSGD and emerging state-level biosecurity mandates reshape capital allocation priorities for facility upgrades and geographic expansion.
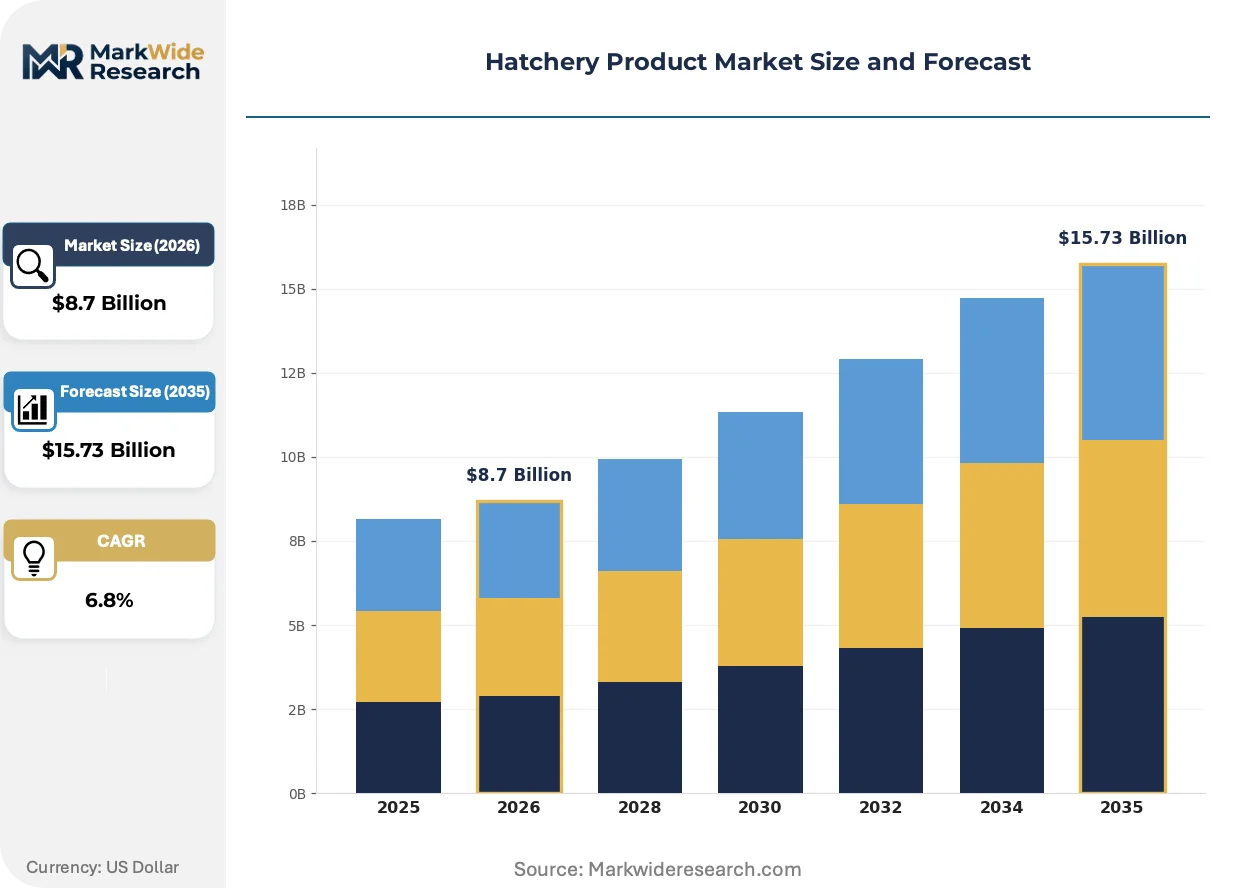
Market Dynamics
Automated single-stage incubation is displacing multi-stage systems as the dominant capital allocation priority, compressing equipment replacement cycles and elevating climate-control precision as the primary vendor selection criterion.
Growth Catalysts
- EU F-Gas Regulation:Mandatory refrigerant phase-down is accelerating retrofit demand for low-GWP climate systems in hatchery operations across Germany, the Netherlands, and Denmark.
- Integrated poultry belt expansion:Telangana and Andhra Pradesh are concentrating greenfield hatchery investment, pulling automated equipment procurement toward India's southeastern corridor.
- Embryonic monitoring sensors:Real-time temperature and humidity tracking is reducing early-stage mortality and justifying premium equipment pricing for commercial operators.
Market Restraints
- Input cost volatility:Specialized insulation materials and precision HVAC components face price instability tied to energy-intensive manufacturing inputs.
- Supplier concentration risk:Critical compressor and sensor subsystems rely on a narrow base of German and Japanese component specialists.
- REACH compliance friction:Extended material safety certification timelines delay equipment launches for European hatchery operators.
Strategic Opportunities
- Vietnam's emerging broiler sector:Underpenetrated automated hatchery infrastructure creates first-mover positioning for single-stage system providers.
- PLI scheme alignment:India's production-linked incentive framework for food processing equipment subsidizes domestic manufacturing scale-up.
- Sensor-AI convergence:Predictive embryonic health algorithms layered on IoT hardware enable outcome-based service pricing models.
Industry Challenges
- Climate-control engineering talent scarcity:Specialized technicians capable of calibrating precision incubation environments command premium wages and limited availability.
- Legacy multi-stage integration friction:Retrofitting automated monitoring into existing facilities requires custom engineering without standardized protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hatchery Product Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Eggs, Chicks, Poultry Feed, Brooders End User: Poultry Farmers, Commercial Hatcheries, Breeding Farms, Research Institutions Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesale Service Type: Consultation, Hatchery Management, Training Programs, Equipment Maintenance |
| Companies Covered | Pas Reform Hatchery Technologies, Big Dutchman International GmbH, Aviagen Group, LOHMANN Deutschland, Neogen Corporation, Hendrix Genetics, CTB, Inc., Bovendorp Holding B.V., Petersime N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hatchery Product Market Evolving Landscape
Digitalization of embryonic development monitoring is compressing operational decision cycles and enabling predictive intervention models that reshape hatchery workforce requirements.
Single-stage incubation architecture is decomposing the traditional multi-stage equipment paradigm by isolating each batch's climate parameters. Large-scale Brazilian operators are adopting these systems fastest, driven by biosecurity protocols that demand batch traceability. This shift is decomposing vendor competitive advantage from mechanical reliability toward software-defined climate precision.
EU F-Gas Regulation is mandating refrigerant transitions that elevate heat pump and natural cooling alternatives in climate-system design. Equipment manufacturers must reengineer thermal management subsystems to maintain precision within 0.1°C using lower-GWP working fluids. Western European hatcheries face the steepest compliance curves, with German operators already reporting 18-month equipment qualification delays.
Service unbundling is separating equipment procurement from technical management contracts. Commercial hatcheries in India's integrated belt increasingly outsource incubation expertise to specialized operators rather than building in-house capabilities. This pattern concentrates most visibly around Hyderabad, where third-party hatchery management services now capture recurring revenue streams previously embedded in equipment margins.
Hatchery Product Market Segmentation
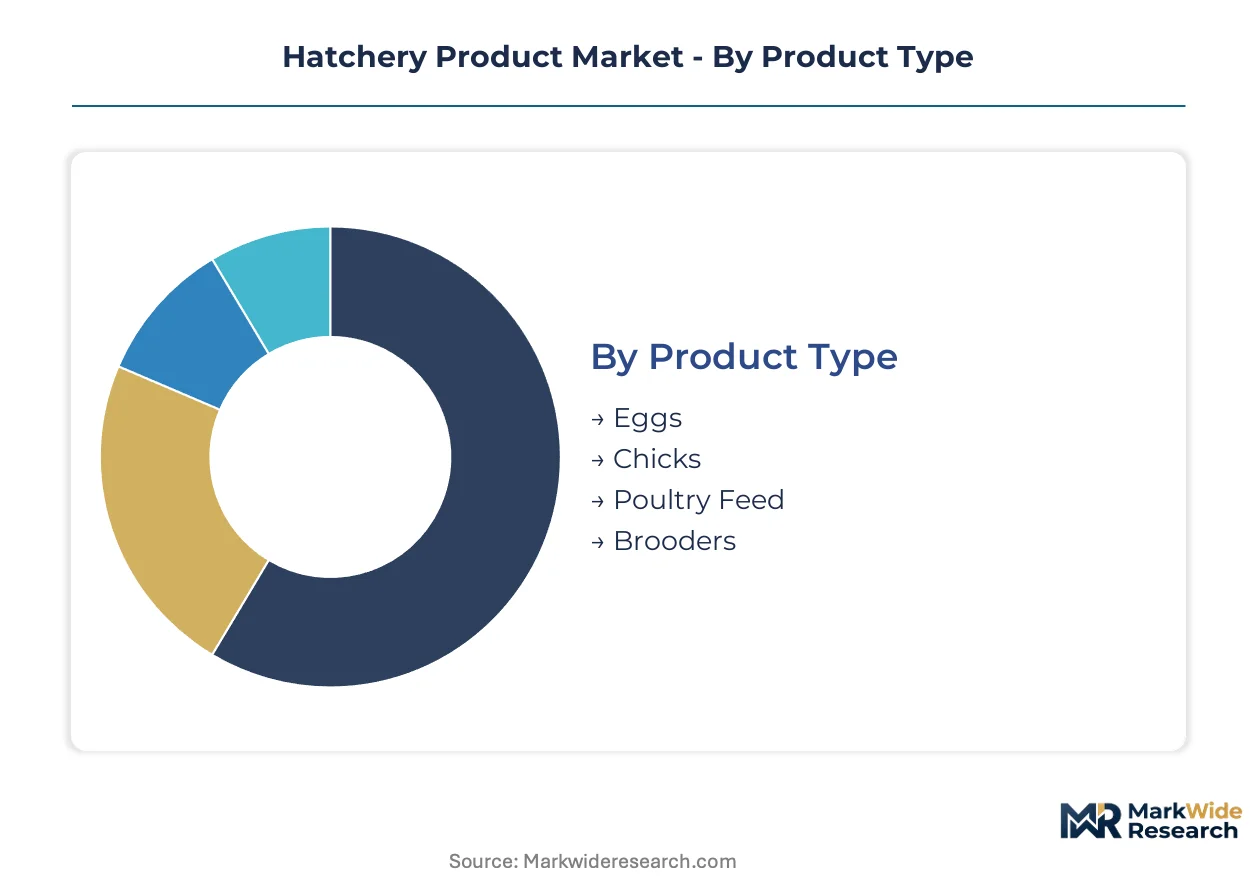
Hatchery product segmentation reveals divergent margin structures across biological assets versus equipment and services. Channel configuration varies sharply between perishable live products requiring cold-chain logistics and durable climate systems sold through technical specification.
Product Type:
Channel-mix patterns separate perishable biological flows from capital equipment procurement cycles. Eggs and chicks move through contracted direct sales to integrated poultry operations, while brooders and feed access wholesale agricultural distributors.
- Eggs:Fertilized hatching eggs demand temperature-controlled logistics maintaining 15-18°C from breeder farm to incubation facility. Demand clusters in Brazil's automated hatchery corridor and India's Telangana-Andhra Pradesh belt, where biosecurity protocols mandate batch traceability and single-source supplier relationships.
- Chicks:Day-old chicks represent the highest-value perishable output, with quality uniformity determining downstream broiler performance. Commercial hatcheries in Germany and the Netherlands prioritize genetic stock from certified breeding farms to meet EU F-Gas Regulation-aligned climate standards.
- Poultry Feed:Specialized starter formulations for newly hatched chicks concentrate procurement through integrated feed mills serving large-scale operations.
- Brooders:Supplementary heating equipment for early chick rearing distributes through agricultural equipment dealers serving smallholder poultry farmers.
By volume, Eggs lead. By growth pace, Chicks are climbing the fastest.
End User:
Cost-tier stratification separates integrated operators investing in automated systems from fragmented smallholders purchasing standardized inputs.
- Poultry Farmers:Small-to-medium operations purchasing chicks and feed through distributor networks dominate transaction volume but compress margins through price-sensitive procurement.
- Commercial Hatcheries:Large-scale automated facilities in Brazil and India drive premium equipment demand, outsourcing technical management to specialized service providers rather than building in-house climate-engineering capabilities.
- Breeding Farms:Genetic stock multiplication facilities operate under stringent biosecurity protocols, sourcing specialized incubation systems with precision climate control within 0.1°C tolerance.
- Research Institutions:Specialized genetic line development commands premium pricing for custom embryonic monitoring and rare breed preservation services.
Commercial Hatcheries capture the steepest expansion trajectory. Poultry Farmers retain dominant transaction volume.
Distribution Channel:
Maturity gradients separate established wholesale agricultural networks from emerging digital procurement platforms serving remote operations.
- Direct Sales:Contracted supply relationships between breeding farms and integrated poultry operations eliminate intermediary margins for high-volume chick and egg flows.
- Distributors:Regional agricultural supply networks dominate equipment and feed distribution, providing technical support for climate-system installation and calibration.
- Wholesale:Volume aggregation points for standardized feed and basic brooder equipment serve fragmented smallholder markets across India's rural poultry belt.
- Online Retail:Digital platforms emerging for specialized genetic stock catalogs and replacement sensor components, constrained by live product shipping regulations.
Direct Sales command highest value concentration. Online Retail is gaining share fastest.
Service Type:
Supply concentration in climate-control engineering talent is forcing service unbundling from equipment procurement.
- Hatchery Management:Outsourced technical operation of incubation facilities concentrates around Hyderabad, where third-party providers capture recurring revenue streams previously embedded in equipment margins.
- Equipment Maintenance:Precision calibration services for single-stage incubation systems require scarce technicians capable of maintaining 0.1°C temperature precision, commanding premium contractual rates.
- Consultation:Facility design and biosecurity protocol advisory supports greenfield investments in Vietnam's emerging broiler sector.
- Training Programs:Workforce development for embryonic monitoring sensor operation addresses skilled labor shortages in automated hatchery expansion zones.
Hatchery Management leads by revenue per engagement. Equipment Maintenance shows the steepest pricing escalation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Smallholder farmers in India's rural belts demonstrate acute price sensitivity for basic brooders and feed, while automated hatchery operators in Western Europe absorb premium equipment costs to meet regulatory compliance mandates.
Brazil
Large-scale commercial operators in São Paulo and Paraná are retrofitting multi-stage facilities with automated single-stage systems to satisfy export-market biosecurity protocols. ANVISA veterinary health standards govern genetic stock import certification and facility sanitation requirements. The automated hatchery corridor around Chapecó in Santa Catarina concentrates capital investment from integrated poultry exporters seeking batch traceability.
Germany
Precision climate-control engineering commands premium procurement budgets as operators phase out high-GWP refrigerants under EU F-Gas Regulation timelines. The KBA and federal environmental agencies enforce extended equipment qualification periods for thermal management subsystem redesigns. Lower Saxony's dense poultry processing belt around Oldenburg drives demand for heat pump-based incubation climate systems with natural cooling alternatives.
India
Integrated poultry belt expansion in Telangana and Andhra Pradesh pulls automated equipment procurement toward greenfield installations with outsourced technical management. BIS certification and CDSCO veterinary health standards shape import protocols for foreign breeding stock and incubation technology. The Hyderabad cluster concentrates third-party hatchery management services capturing recurring revenue streams from operators avoiding in-house climate-engineering capabilities.
United States
Genetic stock certification and interstate movement compliance elevate operational costs for breeding farms supplying integrated broiler operations across the Southeast. FDA biosecurity guidelines and USDA-APHIS regulations govern disease control protocols and breeding facility inspections. The Delmarva Peninsula and Georgia's poultry processing corridor concentrate demand for precision incubation systems maintaining embryonic development parameters within tight tolerances.
Vietnam
Emerging broiler sector growth creates first-mover positioning opportunities for single-stage system providers as domestic protein consumption rises. The country's national agricultural regulator enforces gradual facility modernization standards for commercial hatchery licensing. The Mekong Delta and Northern Red River Delta regions concentrate smallholder-to-commercial transition investments where automated infrastructure remains underpenetrated.
Hatchery Product Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding premium pricing through bundled equipment-service offerings while specialists compete on component precision and regional installation speed. The middle layer contains regional fabricators serving price-sensitive smallholder markets with standardized brooders and basic climate systems. Three archetypes dominate: climate-engineering purists, integrated feeding-ventilation bundlers, and genetic-stock biosecurity specialists. Competitive moves center on technology licensing partnerships for sensor-AI convergence and geographic expansion into underpenetrated Southeast Asian markets.
Within the climate-engineering tier, Pas Reform Hatchery Technologies and Petersime N.V. exemplify precision-focused European specialists, with the former representing Dutch automated incubation leadership and the latter anchoring Belgian climate-system fabrication. Big Dutchman International GmbH occupies a distinct position as a German integrated systems bundler. These three entities illustrate how vendor selection criteria bifurcate between precision-isolated batch control and operational complexity reduction.
| Leading Market Players |
|---|
| Pas Reform Hatchery Technologies |
| Big Dutchman International GmbH |
| Aviagen Group |
| LOHMANN Deutschland |
| Neogen Corporation |
| Hendrix Genetics |
| CTB, Inc. |
| Bovendorp Holding B.V. |
| Petersime N.V. |
| Others |
Value Network & Pricing Analysis
Single-stage incubation architecture replacing legacy multi-stage systems simultaneously concentrates equipment procurement in Germany and the Netherlands while elevating lifetime service revenue above upfront hardware margins. This substitution dynamic compresses capital equipment replacement cycles and redirects vendor economics toward recurring calibration contracts and sensor replacement streams.
Pricing Analysis
After-sales service tiers—spanning precision calibration contracts, sensor replacement programs, and outsourced hatchery management—now drive lifetime customer value beyond initial equipment sales. Equipment pricing stratifies across premium automated single-stage systems, standard multi-stage retrofits, and economy-grade brooders for smallholder markets, with differentiation anchored in climate precision certification and biosecurity protocol compliance. Cost compression in economy tiers intensifies as regional fabricators in India and Brazil compete on stripped-down climate control specifications. Smallholder poultry farmers in rural India demonstrate acute price sensitivity, while commercial hatcheries in Western Europe absorb premium pricing to meet EU F-Gas Regulation compliance mandates.
Supply Chain Analysis
Germany and Japan anchor precision compressor and sensor subsystem production, while China and India concentrate fabricated metal housings and basic HVAC component assembly. Critical supply inputs include specialized refrigerants transitioning under GWP phase-down schedules, precision temperature sensors maintaining 0.1°C tolerance, and energy-efficient insulation materials. Single-source vulnerability runs through German and Japanese component specialists for climate-control subsystems. Distribution runs through technical specification sales for automated systems and wholesale agricultural networks for standardized brooders and feed.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hatchery product markets are approaching a platform-economics inflection where sensor-AI convergence enables outcome-based service pricing and decommoditizes hardware procurement. Interoperability between embryonic monitoring systems and cloud-based predictive algorithms is reshaping vendor competitive advantage from mechanical reliability toward software-defined climate precision.
For Market Incumbents: Consolidate climate-control engineering talent through specialized technician training programs and exclusive calibration service contracts to defend against sensor-AI specialists entering from adjacent precision agriculture sectors. Deepen backward integration into compressor and sensor subsystems to reduce supplier concentration risk from German and Japanese component specialists. Prioritize certification investment for EU F-Gas Regulation-aligned heat pump climate systems to capture retrofit demand in Western Europe. For New Entrants and Emerging Players: Lead with embryonic health algorithm development layered on commodity IoT hardware to capture recurring revenue streams from commercial hatcheries outsourcing technical management. Vietnam's emerging broiler sector offers the most penetrable geography, with underpenetrated automated infrastructure and rising domestic protein consumption. Target India's production-linked incentive scheme alignment for food processing equipment to subsidize domestic manufacturing scale-up and compete on landed cost against established European vendors. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated climate-engineering specialists with captive sensor-AI development capabilities. Long-term viability over the next decade rests on vendors controlling both precision hardware fabrication and predictive software layers rather than pure equipment manufacturers. Acquisition target archetypes include embryonic monitoring sensor developers and third-party hatchery management service providers concentrated around Hyderabad. The signal to watch is regulatory acceleration of EU F-Gas refrigerant phase-down timelines, which would compress equipment replacement cycles and elevate premium system demand.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-AI Platform Integration | Predictive embryonic health algorithms enable outcome-based service pricing models for commercial hatcheries. |
| Backward Integration into Compressor Subsystems | Captive supply of precision climate components reduces exposure to German and Japanese supplier concentration. |
| EU F-Gas Compliance Certification | Heat pump-based incubation systems with natural cooling alternatives capture mandated retrofit demand in Germany and the Netherlands. |
| Hatchery Management Service Expansion | Third-party technical operation contracts in India's Telangana-Andhra Pradesh belt capture recurring revenue from labor-constrained operators. |
| Vietnam Market Entry Partnership | Joint ventures with domestic protein processors accelerate automated infrastructure deployment in underpenetrated broiler regions. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with hatchery operations managers, climate-system procurement leads, and agricultural equipment distributors, and secondary validation through customs trade records, EU F-Gas regulatory filings, and BIS certification databases. Primary fieldwork captured operational decision criteria for single-stage versus multi-stage system selection, workforce constraints in precision calibration, and outsourcing patterns for hatchery management services. Secondary sources included ANVISA veterinary health standards documentation, CDSCO import protocol records, and SEC filings from publicly traded poultry genetics companies. Bottom-up equipment shipment data triangulated against top-down protein production forecasts anchored regional demand sizing.
Across the projection horizon, the analytical framework modeled demand segmentation by product type, end-user scale tier, and distribution channel configuration, with additional dimensioning by regulatory compliance cluster. CAGRs were derived from equipment replacement cycle compression analysis and protein consumption elasticity modeling. Forecast inputs incorporated EU F-Gas refrigerant phase-down timelines, India's PLI scheme subsidy trajectories for food processing equipment, and sensor-AI convergence adoption curves in commercial hatchery operations.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement of climate-control equipment standards or accelerated smallholder-to-commercial transition in Southeast Asia would require recalibration. Forecasts reflect documented assumptions about skilled labor availability for precision calibration and continued concentration of integrated poultry investment in Brazil's Chapecó corridor and India's Hyderabad cluster. Recalibration cycles align with material shifts in EU F-Gas implementation timelines and emerging state-level biosecurity mandates affecting genetic stock movement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aquaculture Innovations
Ornamental Tropical Fish Feed Market
Aquaculture Innovations
Aquaculture UAE in Market
Aquaculture Innovations
United States Ornamental Fish Market
Aquaculture Innovations
Ecuador Shrimp Feed Market
Aquaculture Innovations
Global Aquafeed Market
Aquaculture Innovations
Aquaculture Feed and Pharmaceuticals Market
Aquaculture Innovations
Europe Aqua Feed Market
Aquaculture Innovations
Norway Aquaculture Market
Aquaculture Innovations
Marine Life Raft Market
Aquaculture Innovations
GCC Fish Farming Market
Aquaculture Innovations
Global Aquafeed and Aquaculture Additives Market
Aquaculture Innovations
China Shrimp Feed Market
Aquaculture Innovations
Fish Farming Market
Aquaculture Innovations
Bahrain Fisheries and Aquaculture Market
Aquaculture Innovations
Fish Breeding Tank Market
Aquaculture Innovations
Fish Farming Equipment Market